
 Irradiation Sterilization Services Market | 2026-2036
Irradiation Sterilization Services Market Size, Share, and Industry Trends Forecast 2026-2036
Irradiation Sterilization Services Market Analytics
Hospital procurement consolidation is collapsing the addressable market for small regional sterilization contractors. Sotera Health leverages its integrated network of gamma and electron beam facilities to sustain volume commitments from multinational device manufacturers. Sterigenics anchors North American capacity with specialized cobalt-60 infrastructure, while BGS Beta-Gamma-Service competes through dense geographic coverage across Central European manufacturing corridors.
Irradiation sterilization services deploy ionizing radiation—gamma rays from cobalt-60, accelerated electrons, or high-energy X-rays—to eliminate microbial contamination without residual chemical agents, typically operating at absorbed doses between 25 and 50 kGy for medical devices. The primary commercial purpose centers on terminal sterilization of temperature-sensitive products where heat or gas methods risk material degradation. Gamma radiation dominates current installed capacity due to deep penetration and established pharmacopeial recognition, while electron beam processing captures fastest growth in high-throughput pharmaceutical packaging lines where reduced turnaround time commands premium positioning. X-ray sterilization occupies an emerging niche for bulky or heterogeneous product loads where source uniformity limitations constrain gamma alternatives.
FDA 21 CFR Part 820 quality system regulations and ISO 11137 sterilization validation standards shape market access by mandating dose mapping, bioburden monitoring, and quarterly dose audit protocols that favor providers with dedicated microbiology laboratories. The EPA's National Emission Standards for Hazardous Air Pollutants for ethylene oxide commercial sterilizers is accelerating demand migration toward radiation-based alternatives in the United States. Stakeholders must monitor cobalt-60 supply chain concentration and emerging X-ray accelerator reliability data to determine capital allocation between isotope-dependent and electrically powered sterilization modalities.
Market Dynamics
Hospital procurement consolidation is collapsing the addressable market for small regional sterilization contractors. Sotera Health leverages its integrated network of gamma and electron beam facilities to sustain volume commitments from multinational device manufacturers. Sterigenics anchors North American capacity with specialized cobalt-60 infrastructure, while BGS Beta-Gamma-Service competes through dense geographic coverage across Central European manufacturing corridors.
Growth Catalysts
- EPA NESHAP for Ethylene Oxide:The EPA's National Emission Standards for Hazardous Air Pollutants for ethylene oxide commercial sterilizers is accelerating demand migration toward radiation-based alternatives in the United States.
- Implantable Device Validation:FDA 21 CFR Part 820 quality system regulations and ISO 11137 sterilization validation standards are tightening validation requirements for implantable products, favoring outsourced specialists with dedicated microbiology laboratories.
- Cold Sterilization Preference:Pharmaceutical packaging lines across North America and Western Europe are shifting toward cold sterilization methods to prevent material degradation in temperature-sensitive products.
Market Restraints
- Cobalt-60 Supply Concentration:Global cobalt-60 production concentrates in a handful of nuclear reactor facilities, creating vulnerability to supply disruptions and price volatility for gamma-dependent operators.
- X-Ray Accelerator Reliability:Emerging X-ray sterilization technology faces unproven long-term reliability data compared to established gamma and electron beam systems, constraining capital allocation decisions.
- Capital Intensity Barriers:Electron beam and X-ray facilities require substantial upfront investment in high-voltage accelerator infrastructure, limiting market entry for mid-scale regional providers.
Strategic Opportunities
- Underpenetrated Asian Markets:India's CDSCO regulatory framework and expanding domestic medical device manufacturing base present untapped demand for contract irradiation services with ISO 11137 certification capabilities.
- X-Ray Technology Convergence:The intersection of high-energy X-ray accelerators with robotics-enabled material handling systems enables processing of bulky or heterogeneous product loads previously constrained by gamma source uniformity limitations.
- EU MDR Compliance Services:The European Union's Medical Device Regulation mandates enhanced sterilization documentation and traceability, creating premium service tiers for providers with integrated quality management systems.
Industry Challenges
- Microbiology Talent Scarcity:Dose mapping, bioburden monitoring, and quarterly dose audit protocols require specialized microbiologists and radiation physicists in short supply across contract sterilization networks.
- Legacy System Integration:Multi-site sterilization providers face complexity integrating cobalt-60 gamma facilities with newer electron beam and X-ray operations under unified quality management and customer reporting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Irradiation Sterilization Services Market |
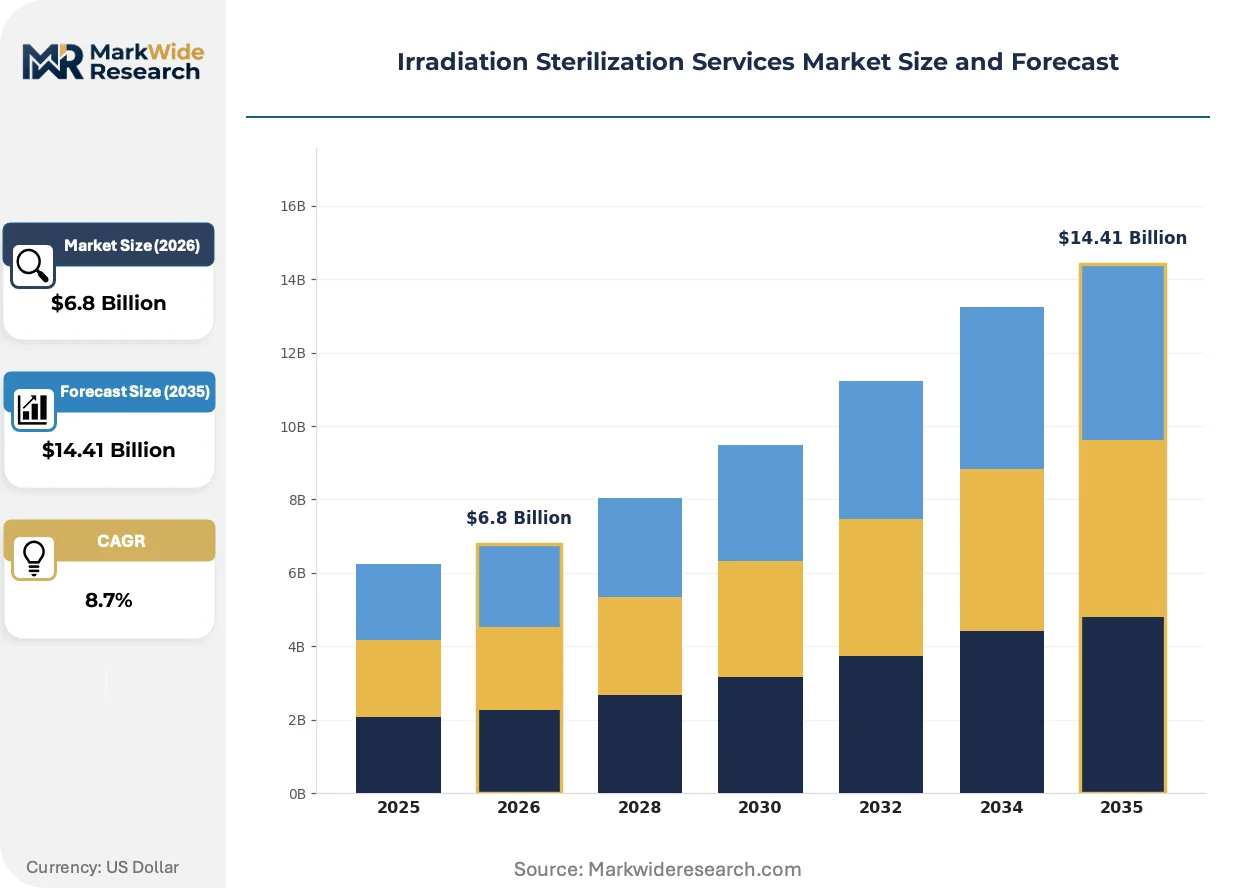
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Gamma Radiation, Electron Beam, X-Ray, Ultraviolet Application: Medical Devices, Packaging Materials, Pharmaceuticals, Food Preservation End User: Hospitals, Laboratories, Manufacturing, Food Industry Technology: Batch Processing, Continuous Processing, Robotic Systems, Automated Solutions |
| Companies Covered | STERIS, Sotera Health, Sterigenics, BGS Beta-Gamma-Service, Nordion, E-BEAM Services, Ionisos, IBA Industrial, Scapa Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Irradiation Sterilization Services Market Evolving Landscape
Technology substitution, regulatory stringency, and buyer consolidation are actively reshaping competitive positioning in irradiation sterilization. Providers must navigate modality selection between isotope-dependent and electrically powered systems while meeting escalating documentation requirements.
X-ray sterilization systems are decomposing traditional gamma dominance in bulky medical device applications. Orthopedic implant manufacturers with heterogeneous product loads are piloting high-energy X-ray accelerators for terminal sterilization. This modality shift is decomposing the historical penetration advantage cobalt-60 held for dense or irregularly shaped devices.
REACH and EU MDR frameworks are tightening material compatibility documentation requirements for sterilized medical devices entering European markets. Manufacturers must now demonstrate polymer stability under specified radiation doses with accelerated aging data. Cardiovascular device suppliers are restructuring supplier qualification protocols to include irradiation-specific material testing.
Consolidated hospital procurement departments are compressing sterilization service contracting cycles from multi-year agreements to annual or project-based engagements. Large health systems with centralized supply chain authority are unbundling sterilization from device purchase agreements. This pattern concentrates most acutely in United States metropolitan markets with dominant integrated delivery networks.
Irradiation Sterilization Services Market Segmentation
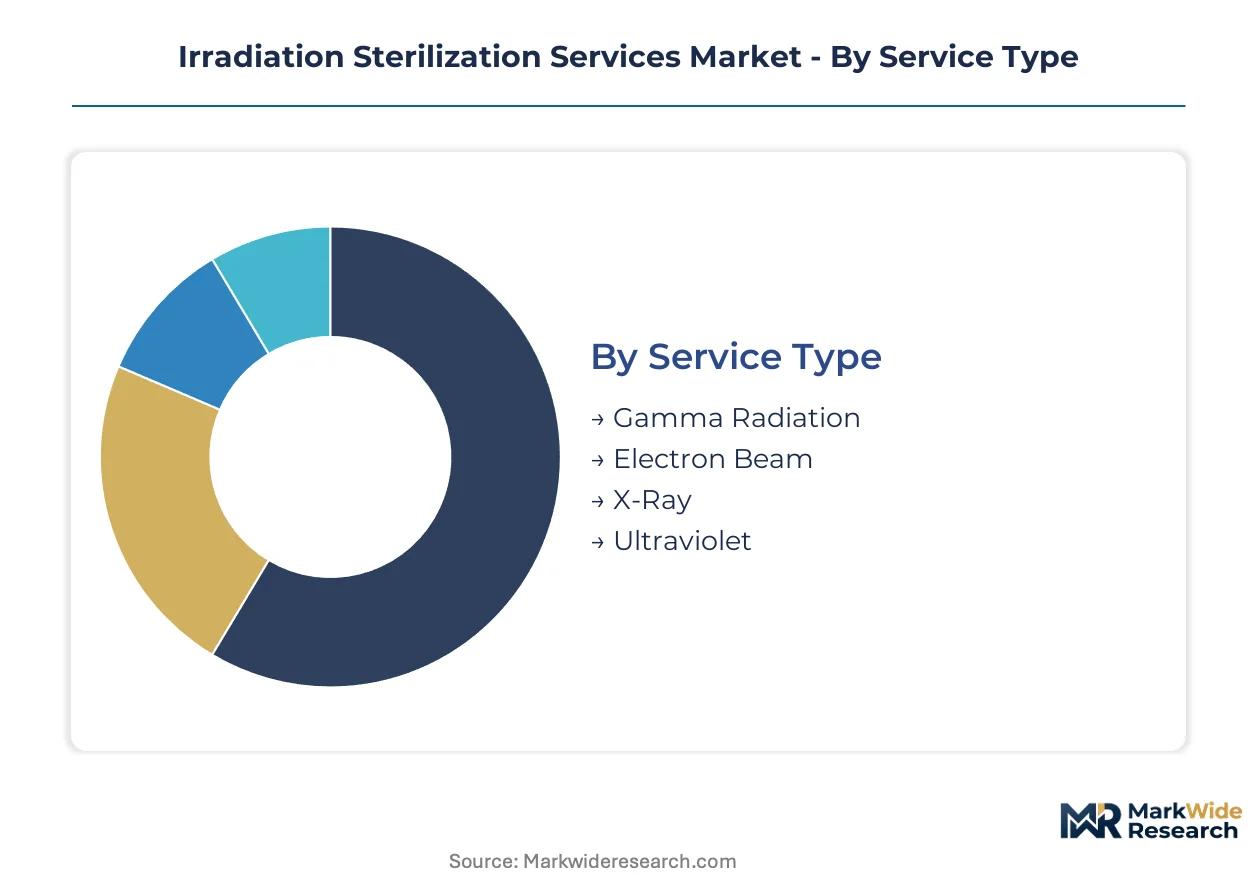
Irradiation sterilization services fragment across distinct technical modalities and customer workflows, each carrying specific regulatory validation burdens. Service providers must align capital deployment with modality-specific compliance pathways while matching processing throughput to end-use sterilization volume requirements.
Service Type:
FDA 21 CFR Part 820 and ISO 11137 impose divergent validation protocols across radiation modalities, with gamma and electron beam carrying established pharmacopeial recognition while X-ray remains under emerging regulatory scrutiny.
- Gamma Radiation:Cobalt-60 isotope sources deliver deep penetration with established dose uniformity for dense medical device loads. Hospital procurement consolidation in the United States favors gamma providers with multi-site networks capable of redundant supply assurance.
- Electron Beam:High-voltage accelerators generate ionizing radiation without isotope dependency, enabling rapid turnaround for pharmaceutical packaging lines. Western European manufacturers prioritize electron beam for temperature-sensitive polymer compatibility.
- X-Ray:Emerging high-energy accelerator technology processes bulky or heterogeneous orthopedic implants previously constrained by gamma source geometry limitations.
- Ultraviolet:Surface sterilization for packaging materials and laboratory equipment with limited penetration depth restricts application to thin-film or top-layer contamination control.
Gamma radiation handles the majority of throughput; electron beam is gaining share fastest on pharmaceutical packaging demand.
Application:
End-use sterilization requirements vary dramatically by product risk classification and material sensitivity, with implantable devices commanding the most stringent documentation protocols.
- Medical Devices:Terminal sterilization of implantable cardiovascular and orthopedic products requires dose mapping and quarterly dose audits per ISO 11137. FDA validation tightening for implantable categories concentrates demand with outsourced specialists maintaining dedicated microbiology laboratories.
- Pharmaceuticals:Cold sterilization of biologic drug containers and pre-filled syringes prevents heat degradation of active compounds. North American packaging lines are displacing ethylene oxide with radiation alternatives under EPA NESHAP pressure.
- Packaging Materials:Sterile barrier systems for medical device distribution require validated dose ranges that maintain polymer integrity.
- Food Preservation:Pathogen reduction in spices and refrigerated proteins operates under USDA and FDA food additive regulations with lower dose thresholds than medical applications.
Medical devices command premium pricing tiers; pharmaceuticals show the steepest volume expansion trajectory on cold chain biologics growth.
End User:
Customer scale and regulatory sophistication determine contracting structure, with consolidated health systems extracting volume commitments that exclude small regional operators.
- Hospitals:Centralized sterile processing departments in United States integrated delivery networks are unbundling sterilization from device purchase agreements, compressing contracting cycles to annual terms.
- Manufacturing:Medical device original equipment manufacturers outsource terminal sterilization to avoid captive cobalt-60 infrastructure investment and specialized microbiology staffing.
- Laboratories:Research and diagnostic facilities require small-batch validation with flexible scheduling for investigational product development.
- Food Industry:Commodity processors prioritize throughput economics over documentation sophistication, operating under separate regulatory frameworks from medical sterilization.
Manufacturing captures the dominant revenue share; hospitals are restructuring procurement fastest toward centralized contract models.
Technology:
Processing architecture selection balances throughput velocity against capital intensity and product mix flexibility.
- Batch Processing:Discrete load handling with full dose validation documentation suits medical device manufacturers with heterogeneous product portfolios and variable lot sizes.
- Continuous Processing:Conveyor-fed sterilization lines maximize throughput for high-volume pharmaceutical packaging with consistent product geometry.
- Robotic Systems:Automated material handling integrates with high-energy X-ray accelerators to process irregular orthopedic implant loads with source uniformity previously unattainable.
- Automated Solutions:End-to-end tracking and quality management system integration addresses EU MDR traceability mandates for European market access.
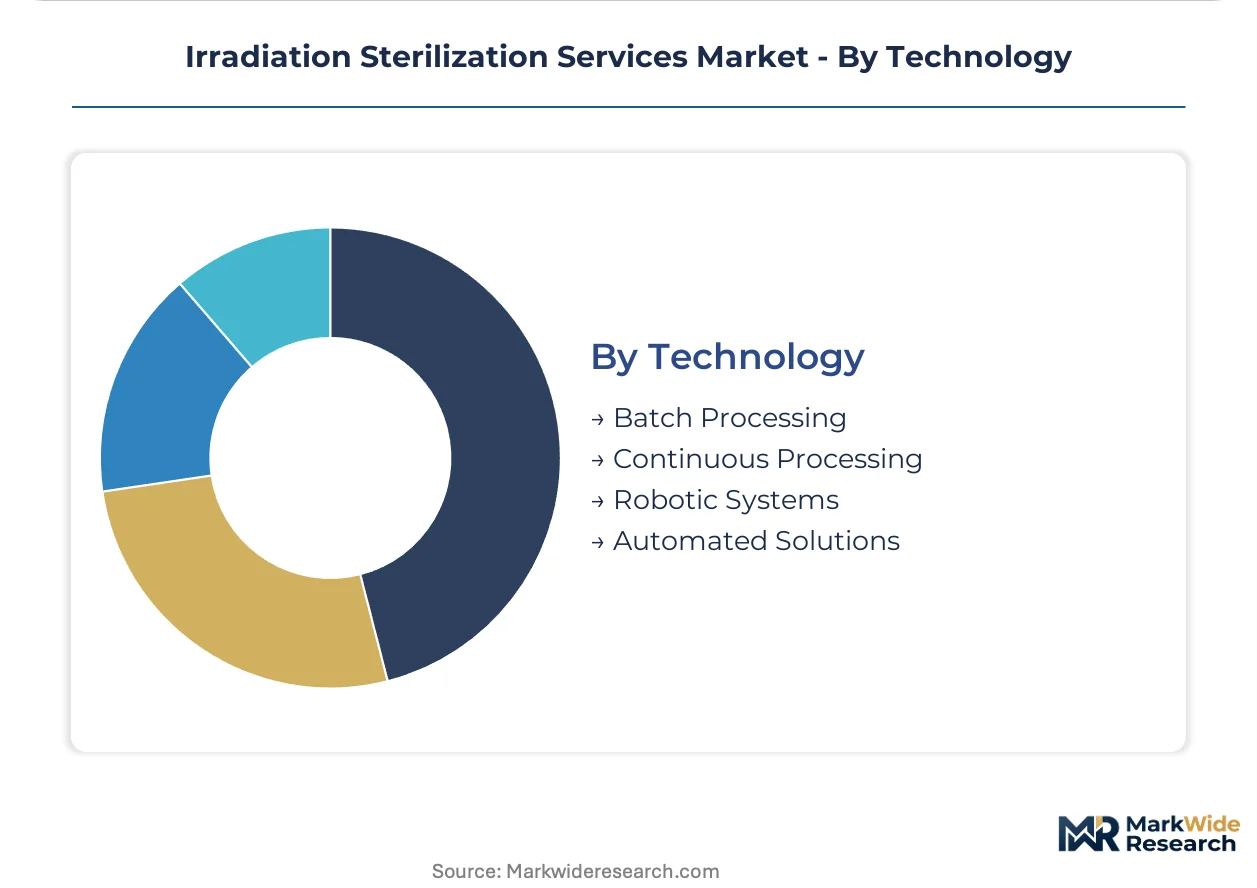
Batch processing retains the largest installed base; robotic systems are climbing fastest on X-ray modality adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain logistics corridor underwrites Western Europe's irradiation sterilization capacity, connecting cobalt-60 supply lines to pharmaceutical manufacturing clusters. This infrastructure anchors cross-border service delivery across the Benelux and into German industrial corridors.
United States
Hospital procurement consolidation in metropolitan markets concentrates sterilization demand with multi-site contract providers. The EPA's National Emission Standards for Hazardous Air Pollutants for ethylene oxide commercial sterilizers accelerates migration toward radiation-based alternatives. Minneapolis-St. Paul hosts dense medical device manufacturing corridors where sterilization providers cluster near OEM facilities.
Germany
REACH compliance requirements and EU MDR documentation mandates elevate sterilization validation standards for export-bound devices. The country's national pharmaceutical regulator enforces stringent material compatibility testing for irradiated polymers. Bavaria's orthopedic implant manufacturing belt around Munich and Nuremberg drives demand for heterogeneous load processing capabilities.
India
Expanding domestic medical device manufacturing under the Production Linked Incentive scheme creates sterilization capacity gaps. CDSCO regulatory frameworks require ISO 11137 certification for contract sterilizers serving export markets. Gujarat's Special Economic Zones around Ahmedabad and Vadodara concentrate emerging device fabrication facilities seeking terminal sterilization partnerships.
Japan
Aging demographics and implantable device penetration sustain premium sterilization service demand. PMDA quality system regulations align with global ISO standards while maintaining supplementary domestic documentation requirements. The Kansai corridor around Osaka anchors pharmaceutical packaging operations prioritizing electron beam cold sterilization for biologic drug containers.
Switzerland
Swissmedic oversight of medical device sterilization maintains equivalence with EU MDR while preserving national sovereignty on quality audits. High-value cardiovascular and orthopedic implant manufacturing clusters around Basel and Zurich require validated dose mapping for terminal sterilization. The country's rail freight integration with EU markets enables just-in-time sterilization logistics.
Irradiation Sterilization Services Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions. The market structure consolidates around three to five dominant multi-site networks with captive cobalt-60 infrastructure, while mid-scale regional operators face procurement exclusion from consolidated health systems. Strategic archetypes include integrated gamma-electron beam networks, isotope-dependent specialists with reactor supply contracts, and emerging X-ray accelerator operators. Competitive moves center on multi-site capacity expansion and microbiology laboratory accreditation to secure implantable device validation contracts.
Within the integrated network tier, Sotera Health and Sterigenics exemplify capital-intensive operators spanning gamma and electron beam modalities across North American manufacturing corridors. BGS Beta-Gamma-Service occupies a position among Central European specialists leveraging dense geographic coverage across German and Benelux pharmaceutical packaging clusters.
| Leading Market Players |
|---|
| STERIS |
| Sotera Health |
| Sterigenics |
| BGS Beta-Gamma-Service |
| Nordion |
| E-BEAM Services |
| Ionisos |
| IBA Industrial |
| Scapa Healthcare |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with cobalt-60 suppliers lock in multi-year price visibility for gamma-dependent operators while insulating them from spot-market volatility in isotope pricing. These arrangements concentrate pricing power with reactor-linked providers in Canada and Russia, forcing electron beam and X-ray competitors to compete on turnaround speed rather than cost stability.
Pricing Analysis
Volume-discount tiering structures stratify across annual commitment thresholds, with multinational device manufacturers capturing standard-tier rates above ten million units annually while mid-scale regional providers absorb economy-tier positioning. Price differentiation hinges on ISO 11137 certification grade and dedicated microbiology laboratory access, with premium tiers commanding substantial markups for implantable device validation. Cost compression in the standard tier is intensifying as hospital procurement consolidation extracts volume commitments from competing networks. Manufacturing original equipment manufacturers exhibit the highest price sensitivity due to unbundled sterilization procurement, while consolidated health systems with captive GPO contracts demonstrate the least.
Supply Chain Analysis
Strategic stockpiling of cobalt-60 pencils dominates gamma operator inventory strategy, with eighteen-to-twenty-four-month forward coverage standard against reactor outage risks. Geographic supply concentration centers on Ontario and Saskatchewan in Canada alongside Dimitrovgrad in Russia, with secondary output from South African reactors. Raw material dependencies encompass high-purity cobalt metal feedstock, specialized shipping casks certified for Type B radioactive transport, and precision-manufactured source encapsulation hardware. Single-source vulnerability permeates the reactor-to-irradiator supply chain, where any production interruption cascades through contracted offtake schedules. Distribution runs through licensed common carriers with dedicated radiological transport certifications, connecting reactor facilities to regional gamma processing centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Irradiation sterilization operates as a regulatory-moat business where FDA 21 CFR Part 820 validation history and ISO 11137 accreditation create switching costs that cement incumbent positioning. This entrenchment intensifies as implantable device manufacturers face requalification timelines exceeding eighteen months for alternative sterilization providers.
For Market Incumbents: Secure captive cobalt-60 supply through reactor partnership extensions or exclusive offtake renegotiations before spot-market exposure widens. Add electron beam capacity in Minneapolis-St. Paul and Bavarian manufacturing corridors to capture pharmaceutical packaging volume migrating from ethylene oxide under EPA NESHAP pressure. X-ray accelerator reliability improvements represent the priority R&D allocation to defend against modality substitution in orthopedic implant applications. For New Entrants and Emerging Players: Anchor in Gujarat's Special Economic Zones where CDSCO-export pathway demand outruns domestic sterilization capacity, leaving contract validation backlogs for ISO 11137-certified entrants. Target laboratory and investigational device segments with flexible batch scheduling that incumbent high-throughput networks disfavor. Pursue hospital system partnerships through centralized sterile processing department outsourcing rather than manufacturing-terminal sterilization competition. For Investors and Strategic Acquirers: Capital is best deployed toward integrated gamma-electron beam networks with existing microbiology laboratory infrastructure and multi-site redundancy across FDA-inspected jurisdictions. Long-term viability favors operators with demonstrated dose audit compliance histories and established cobalt-60 reactor relationships that resist replication. The signal to watch is EPA enforcement intensity against ethylene oxide sterilizers, which accelerates demand migration toward radiation-based alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Site Capacity Expansion | Sotera Health and Sterigenics extend gamma-electron beam networks to secure volume commitments from consolidating hospital procurement. |
| Microbiology Laboratory Accreditation | Dedicated bioburden monitoring and dose mapping capabilities unlock implantable device validation contracts under ISO 11137. |
| X-Ray Accelerator Deployment | High-energy systems with robotic handling penetrate bulky orthopedic implant loads previously constrained by cobalt-60 geometry. |
| Reactor Supply Contract Extension | Long-term cobalt-60 offtake agreements with Canadian and Russian facilities insulate against isotope price volatility. |
| EU MDR Compliance Integration | Enhanced documentation and traceability systems capture premium service tiers for European market access. |
Research Methodology
The analysis maps gamma radiation, electron beam, X-ray, and ultraviolet sub-sectors, each validated through sterilization operations directors, hospital GPO contracts managers, biomedical engineers, and regulatory affairs specialists at device manufacturers. Primary fieldwork combined structured interviews with secondary triangulation against FDA 510(k) sterilization validation filings, ISO 11137 audit records, EPA NESHAP compliance disclosures, and hospital procurement database extracts. Bottom-up facility capacity modeling and top-down healthcare expenditure attribution were cross-checked for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled radiation modality, application risk classification, end-user scale tier, and processing architecture as core segmentation dimensions. CAGRs were derived from sterilization volume elasticity to medical device production indices and pharmaceutical packaging throughput trends. Cobalt-60 supply contract renewal schedules and EPA enforcement action timelines served as industry-specific forecast inputs.
Material uncertainties — cobalt-60 reactor outage duration, X-ray accelerator mean-time-between-failure maturation, and EU MDR documentation requirement evolution — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and isotope supply chain stability. Revision becomes warranted when EPA ethylene oxide restriction intensity or cobalt-60 spot price volatility crosses thresholds that alter modality substitution economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Pneumococcal Testing Market
Testing Services
Passive Dosimetry Equipment and Service Market
Testing Services
Asia-Pacific Newborn Screening Market
Testing Services
Global Homocysteine Testing Market
Testing Services
Malaria Ag Rapid Testing Market
Testing Services
North America and Europe Preclinical Medical Device Testing Services Market
Testing Services
Global Cholesterol Testing Products and Services Market
Testing Services
Test Strips Market
Testing Services
Europe Endotoxin and Pyrogen Testing Market
Testing Services
Urodynamic Testing Market
Testing Services
North America Drug Screening Market
Testing Services
Global at-Home Drug of Abuse (DOA) Testing Market
Testing Services
Arbovirus Testing Market
Testing Services
West Nile Virus Testing Market
Testing Services
Asia Pacific Sterility Testing Market
Testing Services
US Independent Diagnostic Testing Facility Market