
 Blood Irradiator Device Market | 2026-2036
Blood Irradiator Device Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Irradiator Device Market Intelligence
The transition from radioactive sources like Cobalt-60 to alternative X-ray and electron beam technologies is reshaping product development and safety protocols. Rad Source Technologies specializes in non-isotope X-ray solutions, focusing on safety and reduced regulatory burdens. Best Theratronics sustains a significant market presence with its established gamma irradiation systems. IBA Group competes by offering a portfolio that includes both gamma and E-beam/X-ray options for diverse end-user needs.
A blood irradiator device is a medical instrument designed to expose blood and blood components to a controlled dose of ionizing radiation, typically from gamma or X-ray sources. Its primary purpose is to inactivate T-lymphocytes, preventing transfusion-associated graft-versus-host disease (TA-GVHD) in immunocompromised patients. X-Ray blood irradiators represent the fastest-growing product type, driven by the move away from radioactive materials. Blood banks and large hospitals constitute the principal end-user segments, where device utilization is highest.
Device approval pathways are governed by stringent regulations from bodies like the US FDA, Europe's Medical Device Regulation (MDR) for CE marking, and China's NMPA. These frameworks mandate rigorous testing for radiation safety, efficacy, and quality management systems, setting high barriers to market entry. Future investment decisions will hinge on navigating the lifecycle costs and logistical complexities of isotope-based versus non-isotope technologies.
Market Dynamics
The primary force governing the blood irradiator device market is the technological and regulatory transition away from isotope-based systems. This shift from Cobalt-60 sources to X-ray irradiators is fundamentally altering device design, safety protocols, and lifecycle cost considerations for end-users.
Growth Catalysts
- Stricter Isotope Regulations:Heightened security and disposal regulations for radioactive materials, enforced by bodies like the US Nuclear Regulatory Commission and its European counterparts, are increasing the total cost and complexity of owning gamma irradiators.
- Technological Safety Advances:The development of non-isotope X-ray irradiators eliminates the risks associated with radioactive source transport, handling, and security, attracting safety-conscious blood banks and hospitals.
- Expanding Clinical Need:A growing global population of immunocompromised patients, including transplant recipients and oncology patients, requires irradiated blood products to prevent TA-GVHD, sustaining demand from clinical institutions.
Market Restraints
- High Capital Outlay:The significant initial investment required to purchase new X-ray blood irradiator systems presents a major financial barrier for smaller hospitals, independent blood banks, and facilities in developing economies.
- Incumbent Technology Inertia:The long-established global infrastructure and deep-seated clinical familiarity with Cobalt-60 gamma irradiators create resistance to change, slowing the adoption of alternative technologies.
- Logistical Complexity of Decommissioning:The high cost and complex regulatory procedures associated with decommissioning and disposing of legacy gamma irradiation devices can delay or prevent facilities from upgrading to newer systems.
Strategic Opportunities
- Emerging Market Modernization:Upgrading blood safety infrastructure in countries across Asia-Pacific and Latin America presents a significant opportunity for vendors of modern, non-isotope irradiation systems.
- Decentralized Irradiation Solutions:Developing smaller, lower-throughput irradiators can address the needs of smaller regional hospitals or specialized research centers, opening a new segment beyond large, centralized blood banks.
- Software and Service Integration:Offering integrated software for dose verification, automated record-keeping compliant with standards like ISBT 128, and predictive maintenance services creates new, recurring revenue streams.
Industry Challenges
- Specialized Personnel Shortage:A lack of sufficient numbers of trained medical physicists and biomedical engineers to operate, calibrate, and service the more technologically advanced X-ray systems can hinder adoption.
- Workflow Integration Hurdles:Integrating new irradiator hardware and software into existing, validated Laboratory Information Systems (LIS) and hospital workflows can be complex and disruptive for end-users.
- Cross-Jurisdictional Regulatory Navigation:Manufacturers face long and expensive approval timelines to secure certifications from disparate agencies like the US FDA, Europe's MDR for CE marking, and China's NMPA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Irradiator Device Market |
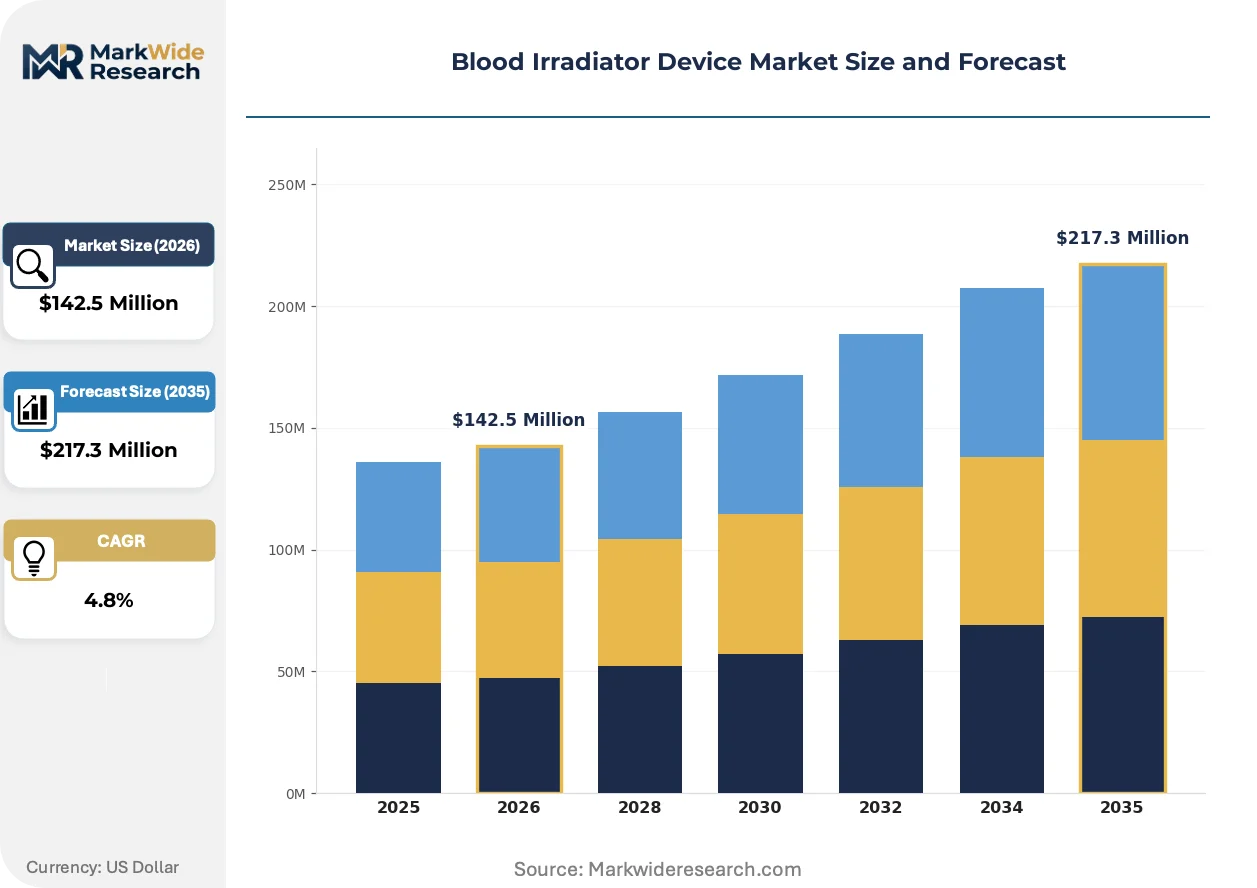
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $217.3 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray Blood Irradiators, Gamma Blood Irradiators, LED Blood Irradiators, Electron Beam Blood Irradiators Technology: Cobalt-60, Cesium-137, Linear Accelerator, Microbeam, Modular Tube Application: Blood Transfusion Centers, Hematology Labs, Cancer Treatment Facilities, Stem Cell Therapy Units, Immunology Labs End User: Hospitals, Specialized Clinics, Research Laboratories, Blood Banks, Diagnostic Centers |
| Companies Covered | Best Theratronics, Gamma-Service Medical GmbH, Hitachi Medical Systems, Gilardoni, Rad Source Technologies, Shinva Medical, IBA Group, Theragenics Corporation, MDS Nordion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Irradiator Device Market Strategic Shifts & Innovations
The convergence of heightened safety standards and digital workflow integration is fundamentally altering product development. This evolution prioritizes the reduction of operational risks associated with radioactive materials while enhancing the efficiency and traceability of the blood irradiation process.
X-ray irradiation technology functions by using electricity to generate high-energy photons, which irradiate blood components to inactivate T-lymphocytes. Large hospital networks and national blood services are adopting these systems to mitigate the security and logistical burdens of radioisotopes. The market's technological foundation is migrating from dependence on Cobalt-60 gamma sources toward inherently safer, on-demand X-ray solutions that eliminate long-term disposal liabilities.
Heightened global regulations governing the security, transport, and disposal of radioactive materials are increasing the total cost of ownership for gamma irradiators. This regulatory pressure, driven by agencies like the US Department of Transportation and international atomic energy bodies, creates significant operational friction. Blood banks are the most affected segment, prompting a strategic re-evaluation of their capital equipment plans to favor non-isotope alternatives.
A clear shift in purchasing criteria toward total lifecycle cost analysis is impacting vendor selection. End-users in health systems are moving beyond initial acquisition price to scrutinize long-term expenses, including service contracts, source replacement or disposal, and regulatory compliance overhead. This more sophisticated procurement behavior is most evident in North America and Europe, where hospital administrators apply rigorous financial models to equipment acquisitions.
Blood Irradiator Device Market Segmentation
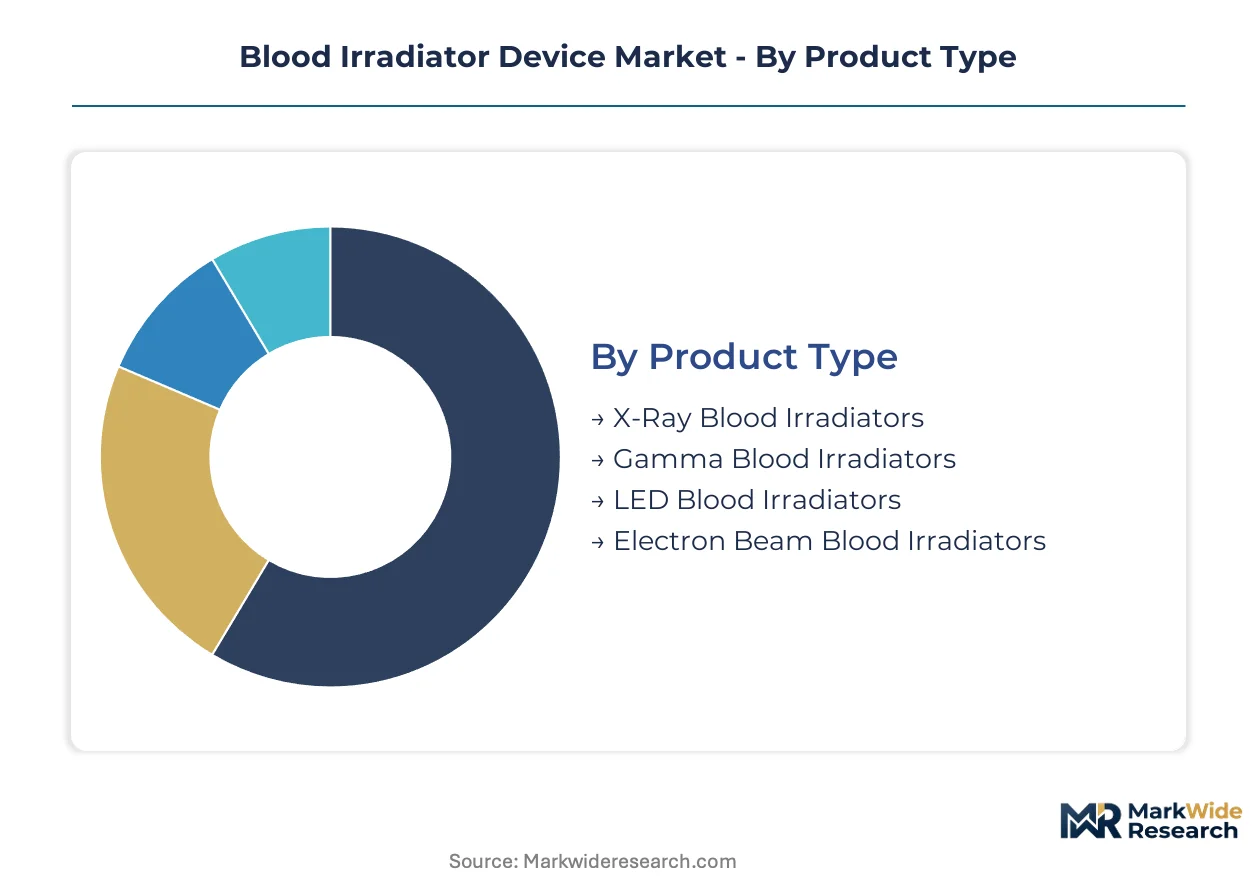
The blood irradiator device market is analyzed across several dimensions, providing a granular view of device evolution and end-user adoption patterns. Understanding these segments helps manufacturers tailor product development and service offerings to specific clinical and operational requirements. This segmentation highlights the technological shifts influencing purchasing decisions and market dynamics.
Product Type:
The product type segmentation reflects the maturity spectrum, with established radioactive systems coexisting with emerging non-isotope alternatives.
- X-Ray Blood Irradiators:These systems generate high-energy photons using electricity, inactivating T-lymphocytes without radioactive sources. Demand is notably concentrating in Germany's clinical and research sectors, driven by enhanced safety and reduced regulatory burdens.
- Gamma Blood Irradiators:Utilizing radioactive isotopes like Cobalt-60, these devices provide established irradiation capabilities for blood products. Their market presence is sustained by long-standing infrastructure, though increasing regulatory pressure on radioactive materials creates operational friction for blood banks.
- LED Blood Irradiators:These devices represent an emerging non-ionizing radiation approach, offering potential for compact designs and lower operational costs.
- Electron Beam Blood Irradiators:Electron beam technology provides a high-dose, non-isotope irradiation method, suitable for specific high-volume applications in large processing centers.
Gamma Blood Irradiators retain volume leadership; X-Ray Blood Irradiators hold the steepest expansion curve.
Technology:
The technology segment illustrates the lifecycle cost considerations for end-users, differentiating between isotope-based and electrically powered solutions.
- Linear Accelerator:This technology forms the core of non-isotope X-ray irradiators, generating high-energy radiation through electrical means. It offers a safer alternative to radioactive sources, particularly attractive to safety-conscious blood banks and hospitals.
- Cobalt-60:A traditional radioactive source, Cobalt-60 is widely used in gamma irradiators for its consistent radiation output. Its continued use faces challenges from stricter isotope regulations and complex disposal procedures, impacting total cost of ownership.
- Cesium-137:Another radioactive isotope employed in gamma irradiators, Cesium-137 systems also contend with increasing security and disposal regulations.
- Microbeam:This advanced technology focuses radiation into precise, narrow beams, offering potential for targeted applications and reduced dose to surrounding areas.
- Modular Tube:Modular tube designs enhance the flexibility and serviceability of X-ray generation components, improving system uptime and maintenance efficiency.
Technological evolution drives differentiation among these systems, with non-isotope solutions gaining traction.
Application:
This application segmentation highlights the diverse clinical needs and patient populations driving demand for irradiated blood products.
- Blood Transfusion Centers:These facilities are primary users, requiring high-throughput irradiation capabilities for a broad range of blood components. They prevent transfusion-associated graft-versus-host disease in vulnerable patient populations.
- Cancer Treatment Facilities:Oncology patients, particularly those undergoing chemotherapy or stem cell transplants, frequently require irradiated blood products due to their immunocompromised status. These facilities demand reliable and safe irradiation solutions.
- Hematology Labs:Hematology laboratories utilize blood irradiators for specific research protocols and specialized patient treatments involving blood components.
- Stem Cell Therapy Units:These units require precise irradiation of blood products to ensure patient safety during stem cell transplantation procedures.
- Immunology Labs:Immunology research and diagnostic labs employ irradiation for various experimental setups and to prepare specific blood components.
The expansion of specialized therapies will redefine demand patterns across these applications.
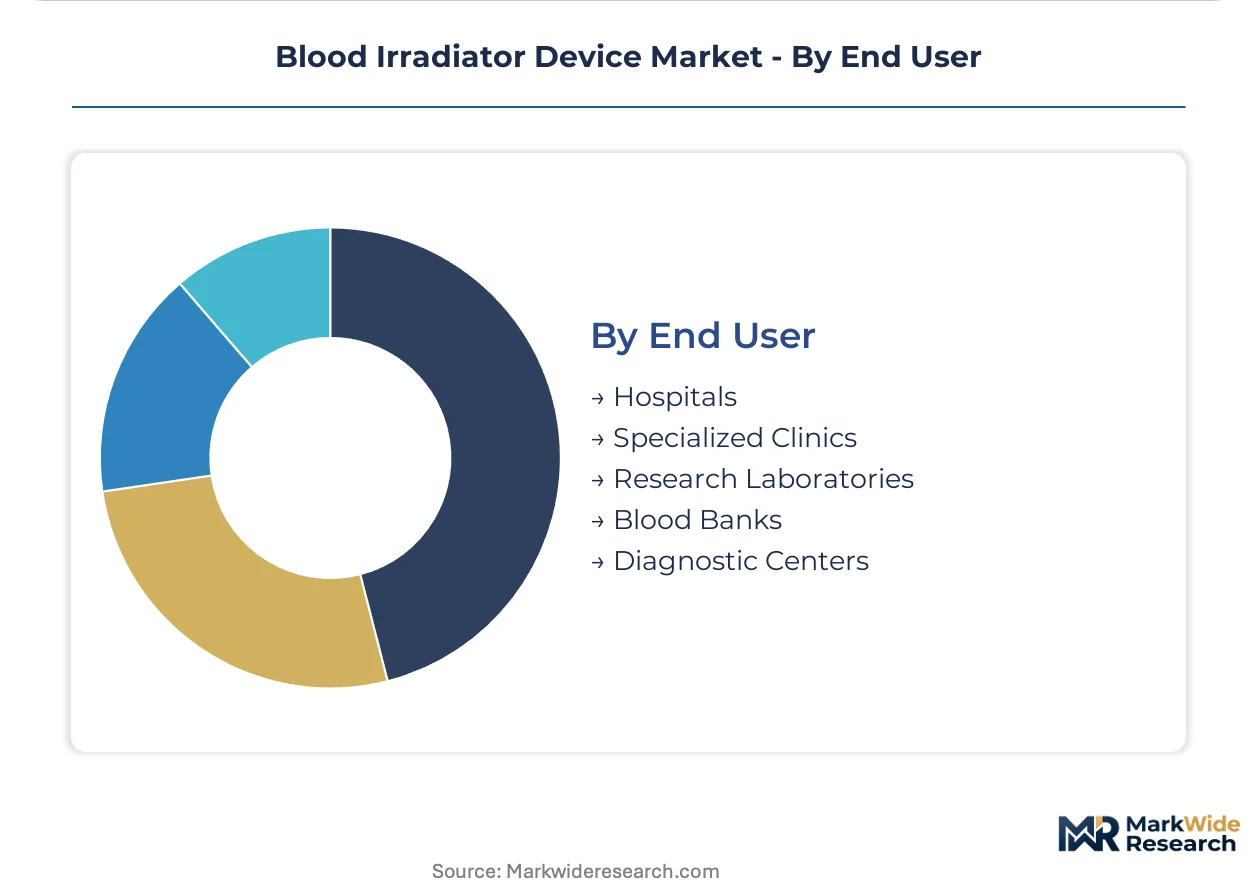
End User:
The end-user segment delineates the primary institutional consumers, reflecting varying operational scales and procurement priorities.
- Blood Banks:As central processing hubs, blood banks require robust, high-volume irradiators to prepare blood products for widespread distribution. They are significantly impacted by regulatory changes concerning radioactive materials.
- Hospitals:Large hospital networks and individual hospitals represent a principal end-user segment, needing on-site irradiation for immediate patient care. Their procurement decisions increasingly factor in total lifecycle costs and safety.
- Specialized Clinics:These clinics, focusing on specific treatments, may require smaller, more flexible irradiation units to meet their patient-specific needs.
- Research Laboratories:Academic and commercial research laboratories use irradiators for various studies, including immunology, hematology, and cell biology.
- Diagnostic Centers:Certain diagnostic procedures involve irradiated blood components, creating a niche demand within these facilities.
Procurement is shifting towards integrated solutions for these varied end-user groups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's clinical and research sectors currently concentrate demand for advanced blood irradiator devices, driving a significant trade flow within Europe. This shift towards non-isotope technologies influences procurement patterns across key global markets. Each region exhibits distinct drivers and regulatory landscapes shaping adoption rates for these critical medical instruments.
Germany
Stringent safety regulations and a strong clinical research infrastructure drive demand for X-ray blood irradiators in Germany. The Medical Device Regulation (MDR) for CE marking mandates rigorous safety and efficacy standards for new devices. Major university hospitals and blood services in cities like Berlin and Munich are actively upgrading their irradiation capabilities.
United States
A large patient population requiring irradiated blood products sustains demand for blood irradiators across the United States. The US Nuclear Regulatory Commission (NRC) imposes strict regulations on radioactive materials, increasing the appeal of non-isotope systems. Major blood banks and hospital networks in New York and California are investing in modern X-ray technologies.
Japan
Advanced healthcare infrastructure and a focus on patient safety propel the adoption of innovative blood irradiation solutions in Japan. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees device approvals, ensuring high standards for medical equipment. Research institutions and large hospitals in Tokyo and Osaka are key adopters of non-isotope systems.
China
Modernization initiatives in healthcare infrastructure and increasing awareness of blood safety drive market expansion in China. The National Medical Products Administration (NMPA) regulates medical devices, influencing technology adoption and market entry. Major urban centers like Shanghai and Beijing are seeing significant investment in advanced blood irradiators.
India
Expanding healthcare access and a growing number of complex medical procedures are increasing the need for irradiated blood products in India. The Central Drugs Standard Control Organization (CDSCO) manages device approvals, impacting market entry for new technologies. Large hospital chains and emerging blood banks in cities like Mumbai and Delhi are upgrading their equipment.
Blood Irradiator Device Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a dynamic market for blood irradiator devices. The market exhibits a stratified structure, with established gamma system providers coexisting with innovators in non-isotope technologies. Strategic partnerships and technology licensing are dominant competitive moves as companies seek to expand their product portfolios and geographic reach.
Among established manufacturers, Best Theratronics sustains a significant market presence with its traditional gamma irradiation systems. Rad Source Technologies exemplifies specialization in non-isotope X-ray solutions, focusing on enhanced safety and reduced regulatory burdens. IBA Group offers a comprehensive portfolio, including both gamma and E-beam/X-ray options, catering to diverse end-user needs across various clinical and research settings.
| Leading Market Players |
|---|
| Best Theratronics |
| Gamma-Service Medical GmbH |
| Hitachi Medical Systems |
| Gilardoni |
| Rad Source Technologies |
| Shinva Medical |
| IBA Group |
| Theragenics Corporation |
| MDS Nordion |
| Others |
Cost & Logistics Intelligence
European land freight corridors influence the total cost of ownership for blood irradiators, particularly due to the specialized handling required for both isotope and non-isotope systems. This impacts supply concentration from key manufacturing hubs and downstream price differentiation for end-users.
Pricing Analysis
The pricing gap between established gamma irradiators and newer X-ray systems is significant. The dominant pricing model is per-unit transactional, incorporating extensive service contracts. Price differentiation stems from the technology generation and the level of regulatory certification required. Pricing softness in the legacy gamma segment reflects increasing disposal costs. Hospitals in developing economies exhibit the highest price sensitivity.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support the procurement of high-value medical devices. Geographic supply concentration for critical components rests in Germany, the United States, and Japan, where specialized manufacturing capabilities exist. Dependency on high-purity metals for X-ray tubes presents a raw material risk. Regulatory restrictions on radioactive material transport pose a structural supply chain risk. Distribution typically runs through direct sales teams and specialized medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits a defensive moat story, primarily due to the significant regulatory entrenchment and high switching costs associated with medical device approvals and legacy infrastructure. Medical institutions face substantial hurdles when changing validated blood irradiation systems.
For Market Incumbents: Insulate core market share by investing in next-generation X-ray technology to counter the threat from non-isotope specialists. Deepen channel control through comprehensive service contracts and software integration, making it harder for new entrants to dislodge existing systems. Prioritize certification investment in emerging markets like China to secure future growth.
For New Entrants and Emerging Players: Build out specialized, lower-throughput irradiators for smaller clinics and research laboratories, which represent an underserved segment. Target modernization initiatives in Asia-Pacific countries like India, offering cost-effective and safety-enhanced non-isotope solutions. A go-to-market angle focusing on reduced operational overhead and simplified regulatory compliance will appeal to these institutions.
For Investors and Strategic Acquirers: Software-enabled X-ray irradiator specialists offer long-term viability within a market shifting towards safer, digitally integrated solutions. Focus on firms with strong intellectual property in dose verification and automated record-keeping. The accelerated decommissioning of Cobalt-60 systems globally serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop modular X-ray irradiator platforms | This allows for adaptable solutions across various end-user scales and clinical needs. |
| Integrate AI-driven dose verification software | Enhances safety protocols and streamlines compliance with US FDA and EU MDR standards. |
| Expand service and maintenance network in Asia-Pacific | Supports growing demand for advanced systems in markets like China and India. |
| Form partnerships with blood bank associations | Secures preferred vendor status and influences procurement patterns within the segment. |
| Invest in electron beam technology R&D | Positions companies for high-volume applications and future non-isotope advancements. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade association reports, and medical device databases. Primary interviews included clinical directors, hospital procurement managers, biomedical engineers, and specialized medical device distributors. This approach triangulates bottom-up market insights with top-down industry trends.
Forecast inputs considered historical market performance, technological adoption curves, and evolving regulatory landscapes. The analytical framework modeled segmentation across product type, technology, application, end-user, and regional healthcare infrastructure development. Compound annual growth rates derived from a weighted average of these factors. The expansion of immunocompromised patient populations served as a key forecast input.
The forecast holds incumbent behavior within observed patterns; aggressive moves by x-ray irradiator specialists or new market entrants would shift outcomes. Forecasts reflect documented assumptions regarding technology maturation and regulatory compliance. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
India Clear Aligners Market
Medical Devices
Microcurrent Facial Market
Medical Devices
MRI Coils Market
Medical Devices
Global Transcatheter Embolization and Occlusion Devices Market
Medical Devices
Skin Revitalizing Handheld Devices Market
Medical Devices
Global Advanced Drug Delivery Systems Market
Medical Devices
Distraction Osteogenesis Devices Market
Medical Devices
Implantable Neurostimulators Market
Medical Devices
North America Non-Surgical Procedures Market
Medical Devices
Japan Aesthetic Devices Market
Medical Devices
Pelvic Reconstruction Market
Medical Devices
UK Artificial Organs and Bionic Implants Market
Medical Devices
Global Vaccine Delivery Devices Market
Medical Devices
Image-Based Cytometer Market
Medical Devices
Italy Ultrasound Devices Market
Medical Devices
EMEA Surgical Microscopes Market