
 North America Drug Screening Market | 2026-2036
North America Drug Screening Market Size, Share, and Industry Trends Forecast 2026-2036
North America Drug Screening Market Outlook
CLIA certification for laboratory-developed tests is redrawing competitive boundaries across the North America drug screening landscape. Quest Diagnostics Incorporated leverages its national collection site network to sustain dominance in employer-mandated testing programs. Laboratory Corporation of America Holdings anchors its position through integrated clinical and forensic toxicology workflows. Abbott Laboratories differentiates via point-of-care immunoassay platforms that compete directly with centralized lab turnaround times.
North America drug screening encompasses analytical methods and devices designed to detect controlled substances, prescription medications, and alcohol metabolites in biological specimens, typically operating at cutoff concentrations measured in nanograms per milliliter to satisfy chain-of-custody requirements. The primary commercial purpose centers on workplace safety compliance, clinical toxicology monitoring, and forensic legal proceedings where defensible results carry employment or judicial consequences. Immunoassay kits retain the largest volume share due to cost efficiency in high-throughput workplace programs, while mass spectrometry segments command premium positioning in confirmatory testing where specificity requirements eliminate cross-reactivity risks. Point-of-care delivery modes are gaining share fastest among logistics and construction employers seeking same-shift hiring decisions without laboratory transit delays.
The U.S. Department of Transportation, Substance Abuse and Mental Health Services Administration, and Health Canada collectively shape product standards through mandatory cutoff thresholds, approved device lists, and medical review officer oversight requirements that determine market access for any testing platform. OSHA workplace safety rules and provincial Canadian occupational health codes further expand addressable demand by mandating post-incident and reasonable-suspicion testing protocols across hazardous industries. Stakeholders must monitor how oral fluid and hair matrix approvals alter collection site economics and device manufacturer revenue models across the forecast horizon.
Market Dynamics
The U.S. Department of Transportation's oral fluid testing mandate is fragmenting collection site economics and compressing device manufacturer margins as employers bypass centralized laboratories.
Growth Catalysts
- DOT Oral Fluid Protocols:Federal safety mandates in the United States now permit saliva-based screening for transportation workers, expanding device deployment across trucking and aviation sectors.
- Energy Sector Expansion:Oil and gas operators in Texas and Alberta are implementing continuous monitoring programs for pipeline and refinery personnel under stricter occupational health codes.
- Point-of-Care Immunoassay Miniaturization:Handheld readers with smartphone connectivity are eliminating laboratory transit delays for construction and logistics employers seeking same-shift hiring decisions.
Market Restraints
- Mass Spectrometry Capital Requirements:Confirmatory testing infrastructure demands substantial upfront investment in LC-MS/MS systems, concentrating advanced capabilities among large reference laboratories.
- Cross-Reactivity Technical Limitations:Immunoassay platforms face specificity challenges with synthetic cannabinoid analogues and novel psychoactive substances, requiring frequent antibody reformulation.
- Canadian Provincial Fragmentation:Occupational health regulations vary across Ontario, Alberta, and British Columbia, complicating standardized service delivery for multi-jurisdictional employers.
Strategic Opportunities
- Mexican Manufacturing Nearshoring:Automotive and aerospace production expansion in Nuevo León and Baja California is creating demand for Spanish-language testing protocols and bilingual medical review officers.
- Hair Matrix Regulatory Approval:SAMHSA's pending guidelines for hair specimen collection will unlock forensic-quality retrospective detection for pre-employment and post-incident screening programs.
- Direct-to-Employer Digital Platforms:Cloud-based scheduling and chain-of-custody documentation are disintermediating third-party administrators in mid-market manufacturing segments.
Industry Challenges
- Medical Review Officer Certification Bottlenecks:The credentialing pipeline for MROs qualified to interpret prescription medication disclosures cannot match employer program expansion timelines.
- CLIA Laboratory Accreditation Timelines:State-level variability in inspection scheduling delays test validation for laboratory-developed toxicology panels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Drug Screening Market |
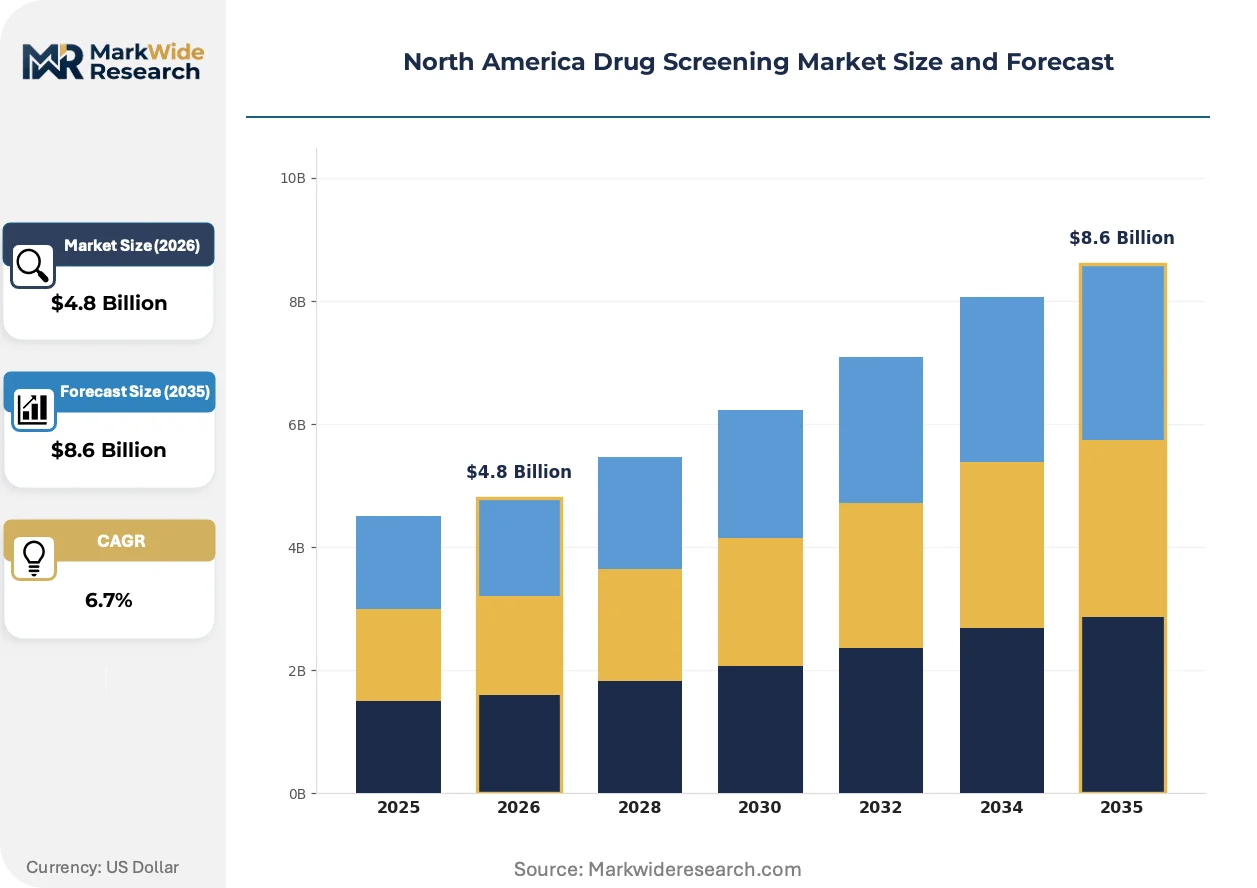
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassay Kits, Chromatography, Breath Analyzers, Saliva Testing Devices End User: Workplaces, Healthcare Facilities, Laboratories, Government Agencies Technology: Microfluidics, Mass Spectrometry, Enzyme Immunoassays, Liquid Chromatography Delivery Mode: Point-of-Care, Laboratory-Based, Mobile Testing, At-Home Testing |
| Companies Covered | Abbott Laboratories, Quest Diagnostics Incorporated, Laboratory Corporation of America Holdings, Thermo Fisher Scientific Inc., Siemens Healthineers AG, Danaher Corporation, OraSure Technologies Inc., Drägerwerk AG & Co. KGaA, Omega Laboratories Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Drug Screening Market Strategic Shifts
Oral fluid and hair matrix technologies are redrawing competitive boundaries as employers prioritize specimen integrity and donor convenience over traditional urine collection protocols.
Liquid chromatography-tandem mass spectrometry is decomposing the confirmatory testing bottleneck by enabling simultaneous multi-analyte detection with quantification precision that eliminates immunoassay cross-reactivity appeals. Reference laboratories in the United States are deploying high-resolution accurate mass platforms to compress turnaround times from 72 hours to 24 hours for post-accident investigations. This capability compression is forcing smaller regional labs to outsource confirmatory work or exit the forensic toxicology segment entirely.
Health Canada's updated oral fluid cutoff thresholds for cannabis metabolites are accelerating device substitution in federally regulated transportation and nuclear sectors. The policy shift eliminates the 15 nanogram per milliliter presumptive threshold that previously required urine confirmation, permitting standalone oral fluid results for compliance decisions. Manufacturers with pre-cleared devices on the approved products list are capturing provincial procurement contracts ahead of laboratory infrastructure adaptation.
Employer self-service ordering portals are replacing third-party administrator intermediation in mid-market manufacturing and warehousing segments. These platforms integrate scheduling, specimen tracking, and medical review officer consultation into unified dashboards that reduce per-test administrative overhead. The disintermediation is most visible in the U.S. Midwest where automotive suppliers and logistics operators maintain direct relationships with collection site networks.
North America Drug Screening Market Segmentation
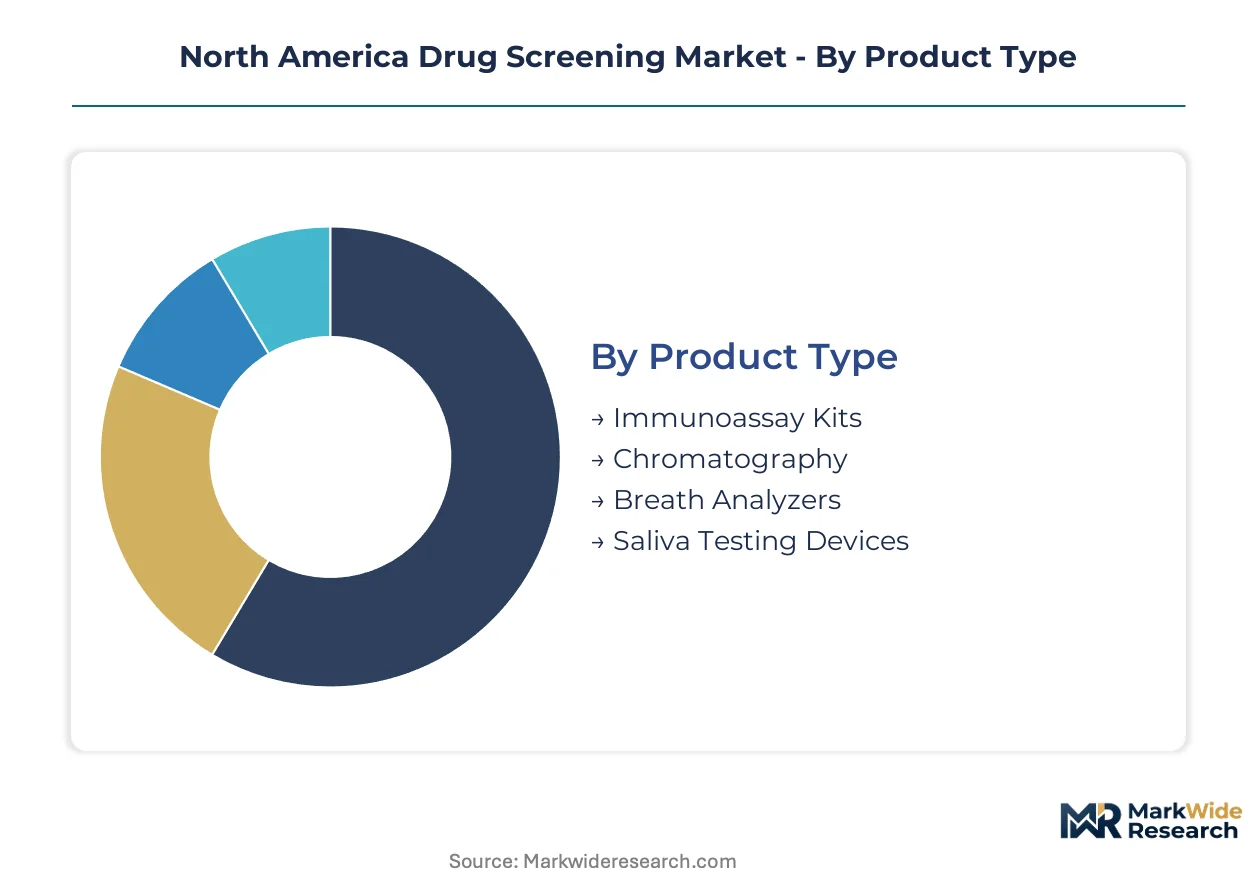
Drug screening markets fragment across four distinct axes that determine procurement patterns and margin structures. Product type and delivery mode classifications now dominate competitive positioning as employers weigh speed against forensic defensibility.
Product Type:
Oral fluid and breath-based platforms are displacing urine collection protocols fastest among transportation and logistics employers seeking same-shift hiring decisions.
- Immunoassay Kits:Antibody-based detection systems operating at nanogram-per-milliliter thresholds for presumptive screening across high-volume workplace programs. Demand concentrates in the U.S. South where energy sector operators maintain mandatory random testing pools under OSHA process safety mandates. Cross-reactivity limitations with synthetic cannabinoids drive frequent kit reformulation cycles.
- Chromatography:Separation-based analytical systems encompassing gas and liquid variants for confirmatory toxicology workflows. Reference laboratories in Texas and California anchor procurement volumes as post-accident investigations require legally defensible quantification. Capital intensity limits deployment to centralized facilities with CLIA-certified infrastructure.
- Breath Analyzers:Fuel-cell and infrared spectroscopy devices for real-time alcohol metabolite detection at roadside and workplace checkpoints.
- Saliva Testing Devices:Integrated collection-and-analysis platforms capturing oral fluid specimens without bathroom supervision requirements.
Immunoassay kits anchor the volume base while saliva testing devices gain share at the steepest rate.
End User:
Cost tier stratification separates enterprise programs with dedicated medical review officers from mid-market employers outsourcing to third-party administrators.
- Workplaces:Private-sector employers conducting pre-employment, random, and post-incident screening under federal safety mandates or insurance discount incentives. Manufacturing and warehousing operations in the U.S. Midwest drive procurement concentration as automotive suppliers implement zero-tolerance policies. DOT oral fluid guidelines are compressing collection site economics for trucking fleets.
- Healthcare Facilities:Hospitals and pain management clinics monitoring patient compliance with controlled substance prescriptions. Clinical toxicology departments in Ontario and Quebec anchor Canadian demand as provincial formularies tighten opioid dispensing protocols. Integration with electronic health records drives platform selection criteria.
- Laboratories:Independent reference labs and hospital-based toxicology services performing confirmatory testing with chain-of-custody documentation.
- Government Agencies:Federal, state, and provincial entities conducting applicant screening and employee monitoring for safety-sensitive positions.
Workplace employers command the largest procurement volumes while healthcare facilities expand most quickly as clinical toxicology monitoring protocols proliferate.
Technology:
Volume concentration favors mature immunoassay platforms, though mass spectrometry segments capture premium positioning where specificity requirements eliminate false-positive appeals.
- Microfluidics:Miniaturized fluid-handling systems enabling cartridge-based testing with smartphone-connected result transmission. Construction employers in Alberta and Texas are deploying handheld units for remote site access without laboratory logistics. Device manufacturers compete on reader portability and connectivity reliability.
- Mass Spectrometry:High-resolution accurate mass platforms delivering definitive analyte identification with quantification precision below therapeutic thresholds. LC-MS/MS systems in U.S. reference laboratories compress turnaround times from 72 hours to 24 hours for forensic investigations. Capital requirements concentrate advanced capabilities among Quest Diagnostics and Laboratory Corporation networks.
- Enzyme Immunoassays:Colorimetric detection systems using enzyme-linked antibodies for high-throughput presumptive screening.
- Liquid Chromatography:Separation technology paired with ultraviolet or mass detection for targeted drug panel confirmation.
Enzyme immunoassays sustain the installed base while mass spectrometry segments climb the fastest as confirmatory testing standards tighten.
Delivery Mode:
Customer type segmentation separates enterprise self-service platforms from third-party administrator intermediation in mid-market segments.
- Point-of-Care:Immediate-result testing at collection sites without specimen transport to centralized laboratories. Logistics operators in the U.S. Midwest leverage same-shift hiring decisions to reduce candidate dropout rates. Device reliability and operator training consistency determine program defensibility.
- Laboratory-Based:Specimen collection with chain-of-custody transport to CLIA-certified facilities for analysis and medical review officer interpretation. Federal transportation mandates and judicial proceedings require this delivery mode for legally actionable results. Turnaround time compression remains the primary competitive vector.
- Mobile Testing:Deployable collection units serving remote construction, mining, and pipeline operations across Alberta and Texas shale formations.
- At-Home Testing:Direct-to-consumer specimen collection kits with mail-back laboratory analysis for personal monitoring and telehealth integration.
Laboratory-based delivery anchors compliance-critical applications while point-of-care modes expand most quickly among time-sensitive hiring programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Workplace safety mandates and federal transportation regulations concentrate procurement among large employers with dedicated compliance infrastructure. Energy sector operators and logistics fleets drive volume concentration in specific sub-regions with strict occupational health codes. Hospital systems and pain management clinics anchor clinical demand in metropolitan clusters with integrated electronic health records.
United States
DOT oral fluid testing guidelines are accelerating device deployment across trucking and aviation sectors. OSHA workplace safety rules mandate post-incident screening protocols for hazardous industries. The U.S. South and Midwest concentrate demand where energy, logistics, and manufacturing sectors maintain the strictest requirements under federal safety mandates.
Canada
Health Canada updated oral fluid cutoff thresholds for cannabis metabolites in federally regulated transportation and nuclear sectors. Provincial occupational health codes vary across Ontario, Alberta, and British Columbia, complicating standardized service delivery. Alberta's oil sands operations and Ontario's manufacturing corridor anchor regional procurement volumes for continuous monitoring programs.
Mexico
Automotive and aerospace production expansion in Nuevo León and Baja California is creating demand for Spanish-language testing protocols. Nearshoring manufacturing investment from U.S. and Canadian parent companies is importing workplace safety standards. The Mexico City metropolitan area concentrates clinical toxicology demand among private hospital networks serving expatriate populations.
North America Drug Screening Market Competitive Environment
Player mix skews toward integrated laboratory networks with CLIA-certified infrastructure and point-of-care device manufacturers with portable immunoassay platforms. Consolidation pressure favors national collection site networks that can satisfy chain-of-custody requirements across multiple jurisdictions. Strategic archetypes include reference laboratory consolidators, handheld diagnostic specialists, and third-party administrator intermediaries. Dominant competitive moves encompass CLIA accreditation expansion and point-of-care miniaturization to compress turnaround times.
Within the reference laboratory tier, Quest Diagnostics Incorporated and Laboratory Corporation of America Holdings exemplify the integrated clinical-forensic model with national collection footprints. Abbott Laboratories occupies a differentiated position among point-of-care specialists with handheld reader platforms. These three entities represent the structural poles around which mid-market competitors and regional laboratories position their service offerings.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Quest Diagnostics Incorporated |
| Laboratory Corporation of America Holdings |
| Thermo Fisher Scientific Inc. |
| Siemens Healthineers AG |
| Danaher Corporation |
| OraSure Technologies Inc. |
| Drägerwerk AG & Co. KGaA |
| Omega Laboratories Inc. |
| Others |
Value Chain & Pricing Dynamics
CLIA-certified laboratory capacity utilization above eighty percent in Texas and California anchors price floors for confirmatory toxicology panels, compressing margins for regional competitors unable to match specimen throughput economies. This scale concentration forces smaller laboratories to outsource mass spectrometry workflows or exit forensic segments entirely, while point-of-care device manufacturers capture procurement contracts through disposable cartridge pricing indexed to federal reimbursement schedules.
Pricing Analysis
Cost-plus contracts with medical review officer services indexed to Medicare laboratory fee schedules dominate enterprise workplace programs. Three-tier pricing structure across CLIA-certified reference labs, regional toxicology specialists, and point-of-care device vendors separates forensic-defensible results from rapid-screening alternatives. Pricing pressure stems from employer self-service platforms disintermediating third-party administrators in mid-market manufacturing segments. Automotive suppliers in the U.S. Midwest demonstrate highest price sensitivity due to high-volume random testing pools, while pipeline operators in Alberta prioritize specimen integrity over per-test cost.
Supply Chain Analysis
Antibody production for immunoassay kits hinges on bioreactor capacity concentrated in Massachusetts, California, and Switzerland, with reagent formulation subject to single-source vulnerability for rare metabolite targets. Mass spectrometry instrumentation draws from German, Japanese, and U.S. precision engineering clusters, while oral fluid collection devices source injection-molded plastics from Mexican maquiladoras. Tariff exposure on Chinese-sourced electronic components for handheld readers threatens device manufacturer margins. Distribution runs through national laboratory networks with CLIA-certified collection sites, bypassing traditional medical distribution channels for direct employer contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oral fluid regulatory approval represents an early-cycle expansion opportunity as federal mandates displace urine collection protocols across transportation and energy sectors. Device manufacturers and laboratory networks must reposition before procurement patterns lock in.
For Market Incumbents: Secure CLIA accreditation expansion into Nuevo León and Baja California before nearshoring manufacturing imports U.S. safety standards. Lock in exclusive collection site partnerships with Alberta oil sands operators and Texas shale producers to defend against point-of-care device substitution. Invest in high-resolution accurate mass spectrometry capacity to compress confirmatory turnaround times below twenty-four hours, eliminating regional laboratory competition. For New Entrants and Emerging Players: Differentiate on Spanish-language medical review officer certification and bilingual chain-of-custody documentation to capture automotive and aerospace manufacturing expansion in northern Mexico. Target mid-market logistics employers in the U.S. Midwest with cloud-based scheduling platforms that disintermediate third-party administrator fees. Pursue direct-to-employer SaaS pricing models bypassing traditional per-test markups. For Investors and Strategic Acquirers: Regional toxicology laboratories with established CLIA infrastructure and existing medical review officer networks present the most defensible acquisition profile for consolidation plays. Long-term viability rests on specimen matrix diversification beyond urine as oral fluid and hair protocols gain regulatory traction. Watch SAMHSA hair testing guideline publication as the inflection signal for forensic-quality retrospective detection demand.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Laboratory Accreditation Expansion | Unlocks federal transportation and nuclear sector procurement contracts under Health Canada and DOT mandates. |
| Point-of-Care Device Miniaturization | Enables same-shift hiring decisions for construction and logistics employers bypassing laboratory transit delays. |
| Medical Review Officer Certification Pipeline Investment | Addresses credentialing bottlenecks constraining employer program expansion timelines across North America. |
| Cloud-Based Employer Self-Service Platform Launch | Disintermediates third-party administrators in mid-market manufacturing segments through integrated scheduling. |
| Hair Matrix Testing Regulatory Preparation | Positions laboratories for SAMHSA guideline publication unlocking forensic-quality retrospective detection programs. |
Study Parameters
The analysis maps immunoassay kits, chromatography systems, breath analyzers, and saliva testing devices, each validated through medical review officers, CLIA laboratory directors, employer compliance managers, and toxicology device procurement leads. Primary interviews across these stakeholder categories combined with secondary validation from FDA 510(k) filings, Health Canada approved device lists, DOT oral fluid testing guidelines, and SAMHSA laboratory certification databases. Bottom-up and top-down triangulation cross-checked manufacturer shipment data against employer program expansion surveys.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, end user, technology, and delivery mode segments alongside specimen matrix evolution from urine to oral fluid and hair. CAGRs derived from employer testing frequency expansion, federal mandate adoption curves, and device substitution rates. Forecast inputs incorporated OSHA workplace safety rule enforcement patterns and provincial Canadian occupational health code harmonization timelines.
Material uncertainties — regulatory delays in hair matrix approval, medical review officer certification pipeline constraints, and cross-reactivity technical limitations with novel psychoactive substances — sit outside the modeled envelope. Forecasts reflect assumptions about federal guideline implementation schedules and employer compliance behavior. Practitioners should keep alternative scenarios live as DOT oral fluid adoption rates and Mexican nearshoring investment flows evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Pancreatic Elastase Testing Market
Testing Services
Prothrombin Time Testing Market
Testing Services
Global Multiplex Assays Market
Testing Services
Antibiotic Residue Test Kits Market
Testing Services
Global Coagulation Testing Market
Testing Services
D-Dimer Testing Market
Testing Services
Toxicology Testing Services Market
Testing Services
Global Endocrine Testing Market
Testing Services
Apoptosis Testing Market
Testing Services
Global Specimen Validity Testing Market
Testing Services
US C-Reactive Protein Testing Market
Testing Services
Global Urinalysis Test Market
Testing Services
Trichomonas Rapid Testing Market
Testing Services
Helicobacter Pylori Testing Market
Testing Services
United States Hospital Acquired Disease Testing Market
Testing Services
Pharmaceutical Analytical Testing Outsourcing Market