
 Pneumococcal Testing Market | 2026-2036
Pneumococcal Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Pneumococcal Testing Market Analytics
The capital-intensity divergence between molecular platform developers and rapid test manufacturers is bifurcating competitive dynamics in pneumococcal diagnostics. Thermo Fisher Scientific leverages its integrated instrument-reagent ecosystem to sustain premium positioning in hospital core labs. Abbott Laboratories anchors its presence through point-of-care immunoassay systems deployed in emergency departments. bioMérieux SA differentiates via automated blood culture and antimicrobial susceptibility workflows that reduce time-to-result.
Pneumococcal testing encompasses laboratory and near-patient methods that detect Streptococcus pneumoniae antigens, nucleic acids, or host antibodies in clinical specimens, with PCR assays achieving analytical sensitivity below 10 colony-forming equivalents per reaction. These technologies serve therapeutic decision-making, vaccine efficacy monitoring, and outbreak investigation across acute care and public health settings. Molecular testing commands the highest margins among technology segments due to reagent annuity models and multiplexing capability. Immunoassays occupy the largest volume position in hospitals prioritizing turnaround time over pathogen serotyping. Rapid tests represent the fastest-expanding category in outpatient clinics and resource-limited settings where centralized lab infrastructure remains sparse.
FDA clearance pathways for in vitro diagnostics and CLIA categorization determine market access complexity for novel pneumococcal assays in the United States. The Centers for Medicare & Medicaid Services reimbursement schedules directly shape hospital procurement priorities between centralized molecular platforms and decentralized rapid alternatives. Stakeholders must monitor evolving FDA guidance on multiplex respiratory panel oversight and CMS technology add-on payment decisions to anticipate shifts in capital allocation and test menu expansion.
Market Dynamics
CLIA complexity reclassifications for multiplex respiratory panels are redistributing test deployment between hospital core laboratories and decentralized care sites, compressing traditional workflow hierarchies.
Growth Catalysts
- Medicare reimbursement expansion:CMS technology add-on payments for rapid diagnostic tests incentivize point-of-care adoption in US emergency departments and urgent care networks.
- PCR multiplexing advances:Single-reaction pathogen detection reduces per-test costs while expanding serotyping capability for vaccine surveillance programs.
- India's diagnostic infrastructure buildout:Government health mission investments in district hospital laboratories create demand for automated blood culture systems outside metropolitan centers.
Market Restraints
- Reagent annuity lock-in:Closed-system molecular platforms bind purchasers to proprietary consumables, elevating lifetime cost of ownership above instrument sticker prices.
- Specialized technician scarcity:Complex nucleic acid extraction protocols require trained personnel unavailable in rural and resource-limited clinical settings.
- FDA 510(k) pathway congestion:Multiplex respiratory panel submissions face extended review timelines as the agency clarifies analytical validation requirements for novel target combinations.
Strategic Opportunities
- Brazil's SUS laboratory modernization:Public health system procurement of automated susceptibility testing creates entry points for integrated pneumococcal diagnostic workflows.
- Host response biomarker integration:Combined pathogen-antibody detection distinguishes colonization from invasive infection, addressing unmet clinical need in immunocompromised patient management.
- Retail clinic channel emergence:Pharmacy-based rapid testing stations in the United States bypass traditional hospital laboratory networks for uncomplicated community-acquired pneumonia workups.
Industry Challenges
- Molecular diagnostics specialist recruitment:Shortage of PCR assay development scientists extends product validation timelines for emerging diagnostic developers.
- Legacy LIS integration complexity:Hospital information system interoperability requirements delay point-of-care device deployment despite regulatory clearance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pneumococcal Testing Market |
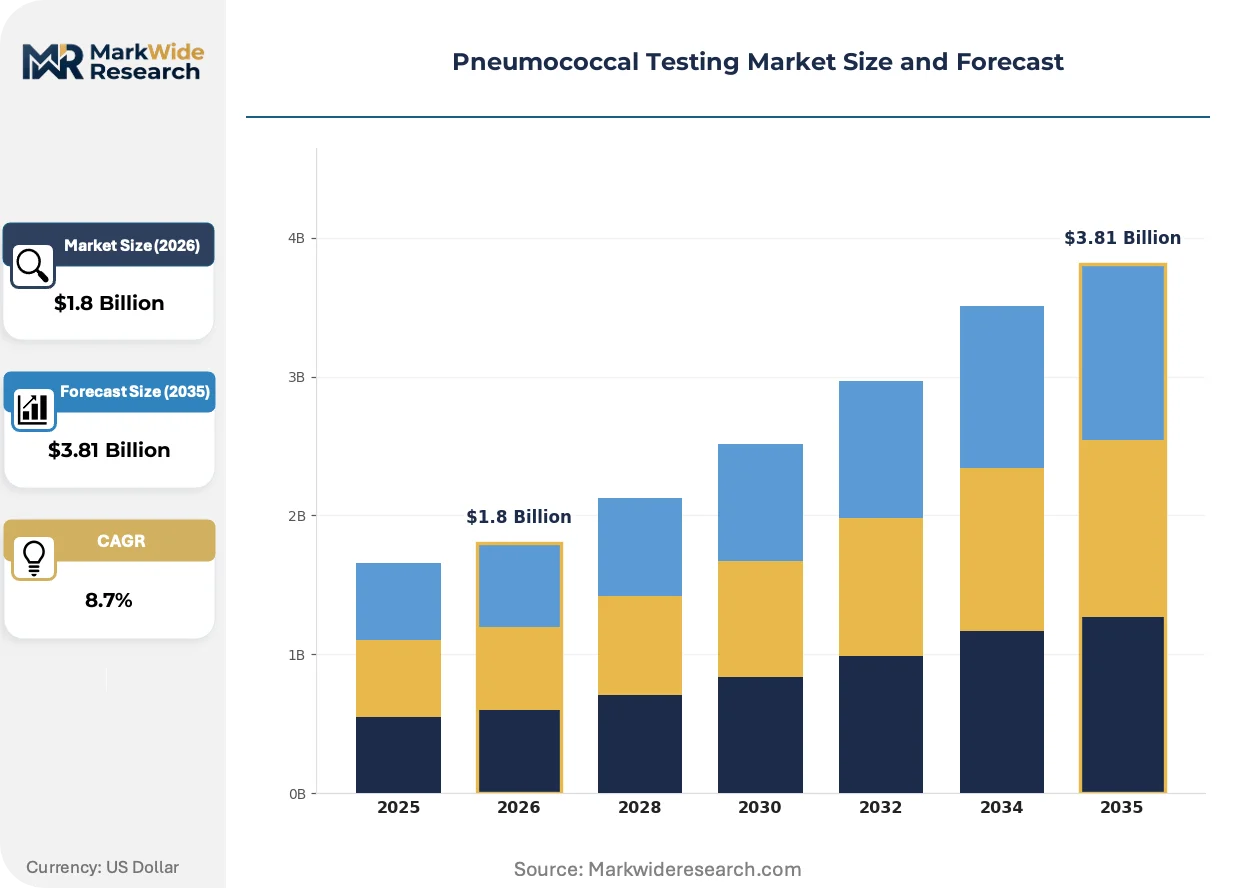
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antigen Detection, Culture Tests, PCR, Serology Application: Clinical Diagnostics, Vaccine Development, Research Studies, Epidemiological Surveillance End User: Hospitals, Diagnostic Laboratories, Research Institutions, Public Health Organizations Technology: Molecular Testing, Immunoassays, Rapid Tests, Conventional Methods |
| Companies Covered | Thermo Fisher Scientific Inc., Abbott Laboratories, F. Hoffmann-La Roche Ltd, Becton, Dickinson and Company, bioMérieux SA, Quidel Corporation, Meridian Bioscience Inc., Bio-Rad Laboratories Inc., Luminex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pneumococcal Testing Market Evolving Landscape
Next-generation sequencing workflows and AI-assisted result interpretation are compressing the traditional separation between research-grade pathogen characterization and routine clinical diagnostics.
Loop-mediated isothermal amplification (LAMP) assays are displacing conventional PCR in near-patient settings by eliminating thermal cycler dependency. Community health centers in sub-Saharan Africa deploy battery-powered LAMP devices for pneumococcal meningitis confirmation without cold-chain reagent storage. The technology is displacing centralized laboratory referral models in regions with sparse infrastructure.
Japan's PMDA revised guidance on in vitro diagnostic multivariate index assays tightens algorithm transparency requirements for AI-integrated result reporting. Manufacturers must submit training dataset documentation and performance stratification across demographic subgroups. High-complexity molecular laboratories in Tokyo and Osaka medical centers are recalibrating validation protocols to meet enhanced evidentiary standards.
Hospital procurement committees now bundle antimicrobial stewardship program metrics with diagnostic platform selection criteria. Integrated blood culture and susceptibility reporting contracts replace standalone instrument purchases in US health system RFPs. This pattern concentrates vendor relationships around full-workflow providers rather than point-solution specialists.
Pneumococcal Testing Market Segmentation
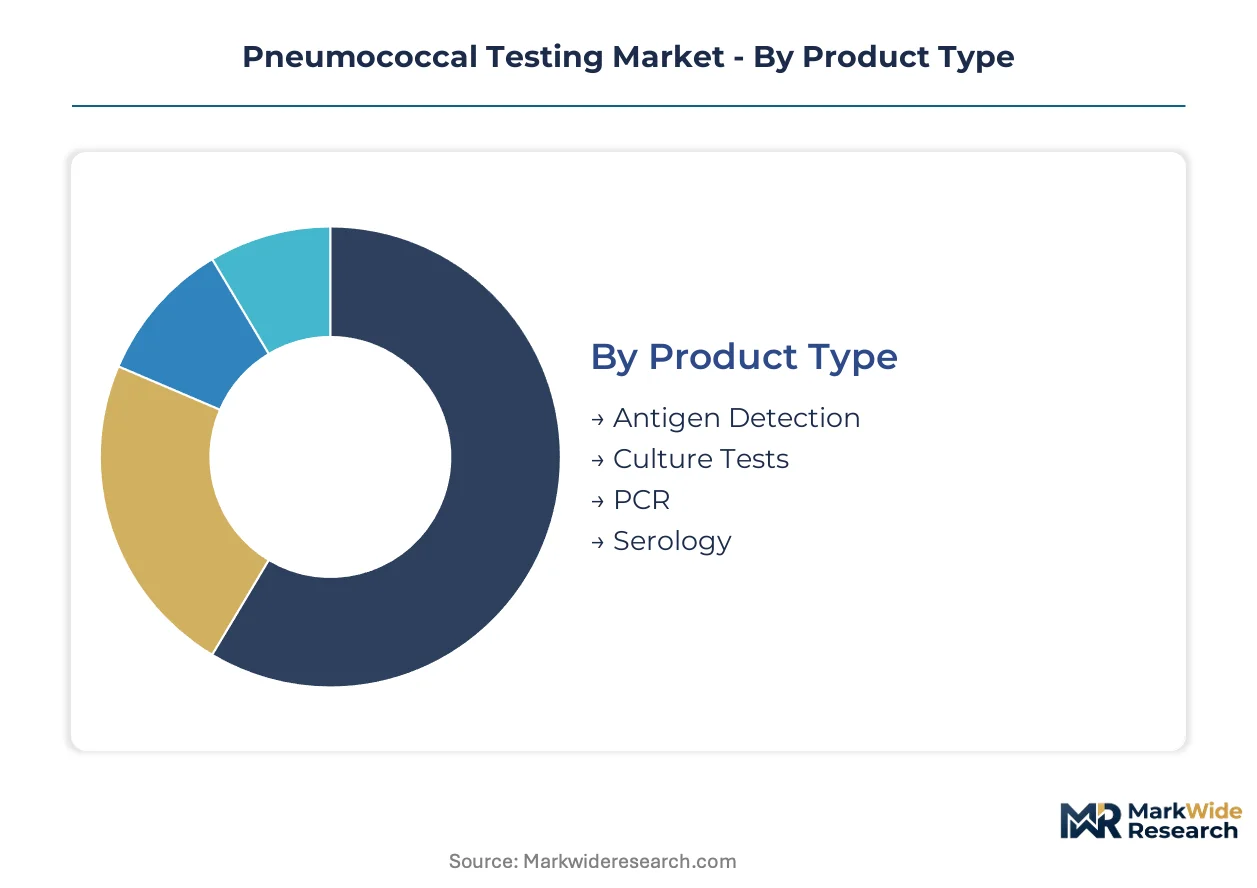
Pneumococcal testing segments fragment across technology maturity curves, with legacy methods facing displacement pressure from multiplex molecular platforms. Procurement committees now weight total cost of ownership against turnaround time requirements when allocating capital across these categories.
Product Type:
Antigen detection and conventional culture methods confront the steepest substitution threat from nucleic acid amplification technologies that compress diagnostic timelines from days to hours.
- Antigen Detection:Lateral flow and enzyme immunoassay formats detect pneumococcal capsular polysaccharides in urine, cerebrospinal fluid, and sputum specimens. US emergency departments favor these for immediate therapeutic decision-making despite lower analytical sensitivity versus molecular alternatives.
- PCR:Real-time nucleic acid amplification targets pneumolysin, autolysin, and capsular biosynthesis genes with analytical sensitivity below 10 colony-forming equivalents per reaction. Hospital core laboratories in the United States prioritize PCR for serotype-specific surveillance aligned with CDC vaccine effectiveness monitoring.
- Culture Tests:Blood and cerebrospinal fluid culture with optochin susceptibility confirmation remains the reference standard for antimicrobial susceptibility profiling.
- Serology:Enzyme-linked immunosorbent assays quantitate anti-pneumococcal capsular antibodies for vaccine response assessment in immunocompromised patient populations.
PCR anchors the volume base while antigen detection gains share at the steepest rate in point-of-care deployment.
Application:
Cost tier stratification separates high-complexity reference laboratory work from decentralized rapid testing, with reimbursement differentials driving site-of-care selection.
- Clinical Diagnostics:Acute care testing for community-acquired pneumonia, meningitis, and bacteremia guides empiric antibiotic selection and duration. US hospital systems bundle these tests into antimicrobial stewardship program metrics under CMS quality reporting requirements.
- Vaccine Development:Phase III immunogenicity trials require standardized serotype-specific antibody quantitation across pediatric and adult cohorts. Contract research organizations in the United States and Western Europe concentrate this demand.
- Research Studies:Academic medical centers investigate pneumococcal colonization dynamics, virulence factor expression, and host-pathogen interaction mechanisms.
- Epidemiological Surveillance:Public health laboratories track serotype distribution shifts following conjugate vaccine introduction to detect vaccine escape and inform formulation updates.
Clinical diagnostics commands the highest absolute spending while epidemiological surveillance expands most quickly with national immunization program investments.
End User:
Customer type fragmentation reflects divergent workflow priorities between centralized high-throughput laboratories and distributed rapid testing sites.
- Hospitals:Acute care institutions deploy multiplex respiratory panels in core laboratories and rapid antigen tests in emergency departments. US health systems consolidate purchasing through integrated delivery networks that negotiate instrument-reagent bundle contracts.
- Diagnostic Laboratories:Commercial reference laboratories process high volumes of outsourced testing from physician offices and smaller hospitals. Quest Diagnostics and LabCorp anchor this segment in the United States with national logistics networks.
- Research Institutions:Academic medical centers and biotechnology companies require research-use-only assays for mechanistic studies and therapeutic target validation.
- Public Health Organizations:CDC, state health departments, and WHO collaborating centers conduct population-level surveillance and outbreak investigation.
Diagnostic laboratories anchor the volume base while public health organizations gain share at the steepest rate with pandemic preparedness infrastructure investments.
Technology:
Margin stratification concentrates in closed-system molecular platforms versus commoditized rapid immunoassays, with supply concentration favoring integrated instrument-reagent vendors.
- Molecular Testing:PCR and next-generation sequencing platforms achieve pathogen identification and serotyping in single workflows. Thermo Fisher Scientific and Abbott anchor hospital core laboratory placements in the United States through installed base expansion strategies.
- Immunoassays:Automated chemiluminescence and enzyme-linked immunosorbent assay systems process high-throughput antibody detection for vaccine response assessment. Large reference laboratories favor these for batch efficiency.
- Rapid Tests:Lateral flow and immunochromatographic formats eliminate cold-chain and instrument dependencies for near-patient deployment. Community health centers in India and sub-Saharan Africa adopt these where laboratory infrastructure remains sparse.
- Conventional Methods:Gram stain, culture, and antimicrobial susceptibility testing persist as reference standards despite extended turnaround times.
Immunoassays anchor the volume base while rapid tests gain share at the steepest rate with retail clinic and pharmacy channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States show the lowest price elasticity, accepting premium instrument-reagent bundles for integrated molecular platforms. Indian district hospitals exhibit acute sensitivity to capital expenditure, favoring rapid antigen tests over closed-system PCR installations.
United States
Emergency departments in urban medical centers drive demand for point-of-care antigen detection with sub-hour turnaround requirements. CMS technology add-on payments for rapid diagnostic tests reduce net acquisition costs for hospital systems. The Boston-Cambridge corridor concentrates molecular assay development activity within academic medical center laboratories.
India
Government health mission investments in district hospital laboratories create procurement windows for automated blood culture systems outside metropolitan centers. CDSCO streamlined clearance pathways for imported diagnostic instruments accelerate deployment timelines. Maharashtra's public health infrastructure expansion in Pune and Nagpur prioritizes equipment with minimal cold-chain dependencies.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia consolidate purchasing through regional procurement cooperatives that negotiate multi-year service contracts. EMA diagnostic device regulations align with MDR requirements for clinical performance documentation. The Heidelberg-Mannheim medical technology cluster hosts reference laboratories validating novel serotyping assays for European surveillance networks.
Japan
Tokyo and Osaka medical centers recalibrate validation protocols under PMDA's tightened algorithm transparency requirements for AI-integrated diagnostics. METI funding for infectious disease preparedness infrastructure supports hospital laboratory automation upgrades. The Kansai region's diagnostic manufacturers concentrate development resources on multiplex respiratory panel miniaturization.
Brazil
Public health system procurement through SUS creates entry points for integrated diagnostic workflows in state reference laboratories. ANVISA's regulatory convergence with international standards reduces import certification delays for European and US manufacturers. São Paulo's Butantan Institute anchors regional vaccine efficacy surveillance requiring standardized serotype-specific testing protocols.
Pneumococcal Testing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in pneumococcal diagnostics, with capital intensity determining tier membership. The upper tier commands installed base advantages through instrument-reagent ecosystems that generate recurring revenue streams. Specialist competitors occupy rapid test manufacturing and regional distribution niches where regulatory agility outweighs scale. Consolidation pressure intensifies as hospital procurement committees favor full-workflow vendors over point-solution providers.
Within the integrated diagnostics tier, Thermo Fisher Scientific Inc. and Abbott Laboratories exemplify the instrument-reagent bundling archetype that dominates hospital core laboratory placements. F. Hoffmann-La Roche Ltd occupies a position representing European-headquartered molecular platform developers with automated sample-to-answer workflows. These three entities anchor competitive dynamics through installed base expansion strategies that complicate specialist challenger entry.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Becton, Dickinson and Company |
| bioMérieux SA |
| Quidel Corporation |
| Meridian Bioscience Inc. |
| Bio-Rad Laboratories Inc. |
| Luminex Corporation |
| Others |
Value Network & Pricing Analysis
Isothermal amplification chemistry is displacing conventional PCR thermal cyclers in near-patient settings, simultaneously shifting manufacturing concentration from precision instrument hubs to reagent formulation centers and collapsing the pricing premium previously attached to capital equipment.
Pricing Analysis
Consumable reagent streams drive lifetime value capture in closed-system molecular platforms, with instrument placements serving primarily as lock-in mechanisms for recurring annuity revenue. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared multiplex panels from CE-IVD equivalents and research-use-only assays. Pricing pressure stems from Indian and Brazilian government tenders favoring open-platform reagents over proprietary consumables. Academic medical centers in the United States show lowest price sensitivity, while district hospitals in Maharashtra and Uttar Pradesh prioritize per-test cost minimization.
Supply Chain Analysis
Extended lead times for specialized polymerases and fluorescent probe chemistries constrain assay production scheduling, particularly for seasonal respiratory panel manufacturing surges. Supply concentration rests on reagent formulation in the United States, Germany, and Japan, with plastic consumable molding concentrated in China and Malaysia. Critical dependencies include Taq polymerase enzymes, oligonucleotide synthesis capacity, and optical-grade polycarbonate for reaction vessels. Single-source vulnerability in lyophilization services for point-of-care test stabilization creates bottleneck exposure. Distribution runs through regional diagnostic distributors serving hospital systems and direct procurement contracts with public health reference laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pneumococcal testing market is recovering from pandemic-induced diagnostic demand cyclicality, with seasonal respiratory surveillance programs and antimicrobial stewardship mandates providing predictable demand baselines.
For Market Incumbents: Fortify installed base positions through extended service contracts that bundle instrument maintenance with guaranteed reagent supply allocations. Deepen backward integration into oligonucleotide synthesis to reduce dependency on third-party probe suppliers facing capacity constraints. Lock in exclusive partnerships with integrated delivery networks before CLIA complexity reclassifications enable point-of-care displacement of core laboratory volumes. For New Entrants and Emerging Players: Differentiate on battery-powered isothermal platforms that eliminate cold-chain infrastructure requirements for sub-Saharan African and South Asian district hospital deployments. Target Brazil's SUS laboratory modernization tenders where ANVISA regulatory convergence has shortened import approval timelines. Pursue retail clinic channel partnerships in the United States that bypass consolidated hospital procurement committees. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rapid test manufacturers holding FDA 510(k) clearances but lacking automated manufacturing scale. Five-to-ten year viability hinges on successful multiplexing technology transitions rather than single-analyte test portfolios. Watch FDA guidance publication timelines on multiplex respiratory panel analytical validation requirements as the inflection signal for capital allocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Complexity Reclassification Strategy | CMS reimbursement alignment determines site-of-care deployment economics for emerging assay formats. |
| Integrated Instrument-Reagent Ecosystem Expansion | Thermo Fisher and Abbott lock hospital core laboratories into proprietary consumable annuity streams. |
| Battery-Powered LAMP Platform Development | bioMérieux and Meridian Bioscience target African and Indian district hospitals lacking cold-chain infrastructure. |
| Multiplex Serotyping Assay Validation | CDC vaccine effectiveness monitoring programs require standardized pneumococcal surveillance panels. |
| Retail Clinic Channel Partnership | Quidel and Abbott bypass hospital procurement consolidation through pharmacy-based rapid testing stations. |
Research Methodology
Desk research of FDA 510(k) clearance databases, CMS reimbursement schedules, and EMA diagnostic device guidance preceded structured interviews with hospital laboratory directors, GPO contracts managers, diagnostic platform engineers, and public health surveillance officers. Secondary validation drew from CDC vaccine effectiveness reports, WHO collaborating center publications, and instrument-reagent bundle pricing disclosed in US health system procurement records. Bottom-up modeling of installed base expansion and top-down triangulation against national health expenditure forecasts anchored volume projections.
Variance decomposition across technology adoption curves, reimbursement policy scenarios, and seasonal respiratory disease burden patterns shaped the analytical framework. Segmentation dimensions included test complexity tier, site-of-care deployment, and regional regulatory cluster. CAGRs were derived from logistic diffusion modeling of molecular platform replacement cycles and immunoassay volume retention. Industry-specific inputs incorporated antimicrobial stewardship program adoption rates and district hospital laboratory automation investment pipelines.
The analysis sits within stated boundaries; outcomes outside sustained CMS technology add-on payment authorization or accelerated FDA multiplex panel review timelines would require recalibration. Forecasts reflect assumptions regarding CLIA complexity stability and seasonal respiratory disease seasonality. Pandemic disruption recurrence or novel serotype emergence outside vaccine coverage would revise trajectory projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Laboratory Proficiency Testing Market
Testing Services
North America Newborn Screening Market
Testing Services
Global Bilirubin Colorimeter Assay Market
Testing Services
Pregnancy Point of Care Testing Market
Testing Services
Ige Allergy Blood Tests Market
Testing Services
Genetic Toxicology Testing Market
Testing Services
Arbovirus Testing Market
Testing Services
Fecal Pancreatic Elastase Testing Market
Testing Services
Global Rapid Test Market
Testing Services
Adiponectin Testing Market
Testing Services
Rift Valley Fever Testing Market
Testing Services
Global Metabolic Testing Market
Testing Services
Global HPV Testing and Pap Test Market
Testing Services
Global Creatinine Assay Kits Market
Testing Services
Autoimmune Disease Testing Market
Testing Services
Drug Testing Systems Market