
 Test Strips Market | 2026-2036
Test Strips Market Size, Share, and Industry Trends Forecast 2026-2036
Test Strips Market Analysis
Continuous glucose monitoring interoperability is reconfiguring how test strip data flows into digital health ecosystems. Abbott Laboratories leverages its FreeStyle platform to anchor connectivity across hospital and home environments. Siemens Healthcare GmbH sustains laboratory-grade accuracy standards that differentiate its offerings in clinical settings. F. Hoffmann-La Roche Ltd dominates European distribution channels through deep pharmacy network relationships.
Test strips are thin, disposable polymer or cellulose substrates impregnated with enzyme reagents that produce a colorimetric or electrochemical signal proportional to analyte concentration, typically requiring microliter sample volumes and readout within seconds to minutes. Their primary commercial purpose is enabling rapid, point-of-care diagnostic measurement without centralized laboratory infrastructure. Glucose test strips occupy the largest revenue pool given diabetes prevalence, while ovulation test strips represent the fastest-expanding segment driven by direct-to-consumer fertility tracking trends. Home care end users are shifting volume away from hospital supply channels as reimbursement policies favor remote patient monitoring.
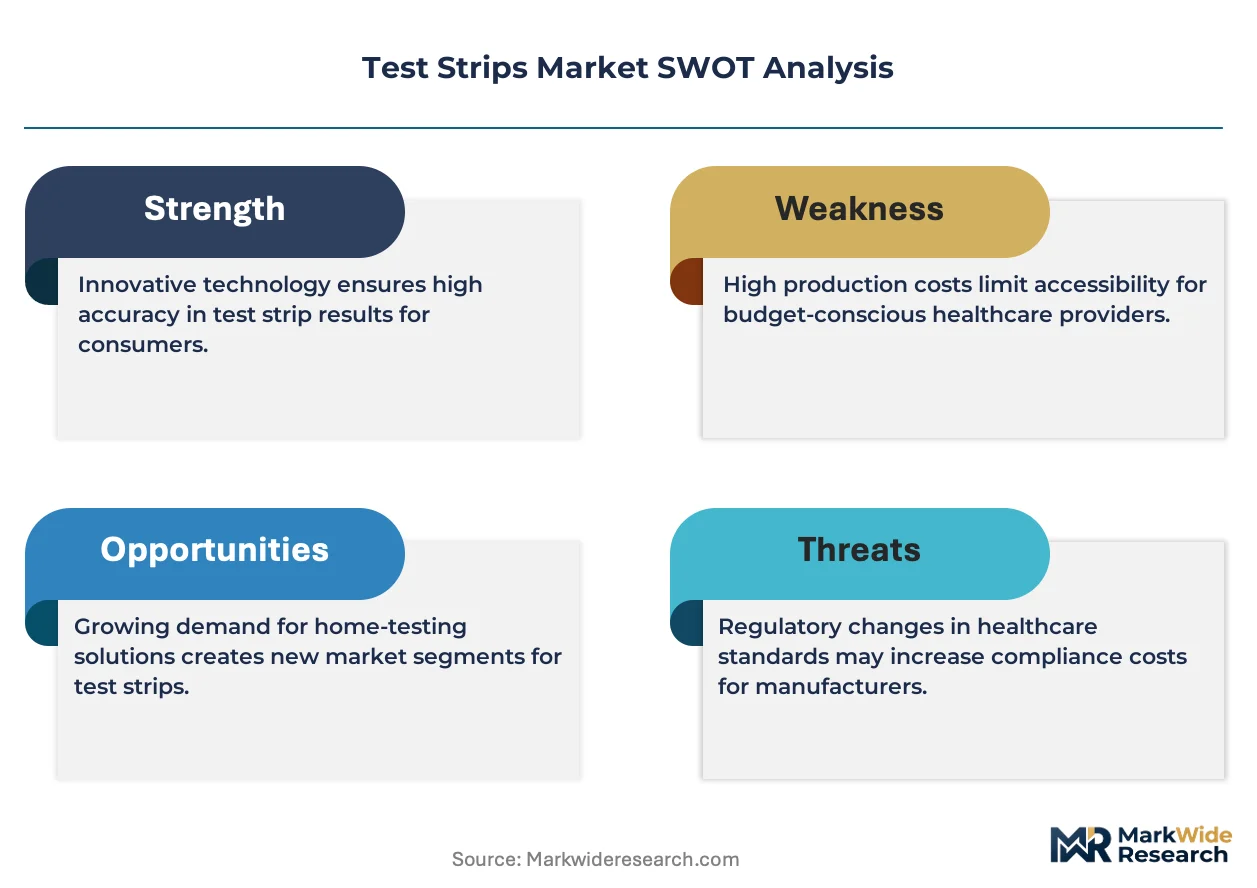
FDA 510(k) clearance requirements and ISO 15197 accuracy standards govern blood glucose strip performance claims in the United States, while the EU Medical Device Regulation imposes post-market surveillance obligations across European markets. These frameworks elevate compliance costs for new entrants but protect incumbent positions of manufacturers with established quality management systems. Stakeholders must monitor evolving interoperability mandates that could strip commoditize hardware while concentrating value in data analytics platforms.
Market Dynamics
Continuous glucose monitoring systems are compressing traditional blood glucose strip demand while simultaneously expanding total addressable market through interoperability mandates that force data portability across competing platforms.
Growth Catalysts
- Remote Patient Monitoring Reimbursement:CMS expanded coverage for home-based glucose monitoring in the United States, accelerating strip consumption outside clinical settings.
- Fertility Tracking Applications:Direct-to-consumer ovulation test strips are capturing demand from women delaying conception, with pharmacy chains expanding shelf space for hormone-based diagnostics.
- ISO 15197 Accuracy Harmonization:Stricter international performance standards are elevating product quality floors and protecting premium positioning for compliant manufacturers.
Market Restraints
- Enzyme Reagent Cost Volatility:Glucose oxidase and dehydrogenase input prices fluctuate with biotech fermentation capacity, squeezing margin on high-volume strip production.
- CGM Substitution Threat:Factory-calibrated continuous sensors reduce daily fingerstick frequency for insulin-dependent diabetics, eroding per-patient strip consumption in Type 1 populations.
- EU MDR Compliance Burden:The European Medical Device Regulation imposes costly post-market surveillance obligations that disproportionately burden smaller strip manufacturers.
Strategic Opportunities
- India Preventive Diagnostics:Undiagnosed diabetes prevalence and expanding health insurance penetration create whitespace for affordable strip distribution through pharmacy networks.
- Multiplex Biomarker Convergence:Electrochemical strips integrating glucose-ketone-cholesterol readings are hybridizing point-of-care panels for metabolic syndrome management.
- Digital Health Integration Mandates:FDA guidance on device interoperability creates regulatory tailwind for strips with embedded NFC or Bluetooth connectivity.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Strip manufacturers compete with battery and semiconductor sectors for specialists in thin-film electrode fabrication.
- Legacy Meter Compatibility:New strip formulations must maintain backward compatibility with installed bases of aging glucose meters, constraining design freedom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Test Strips Market |
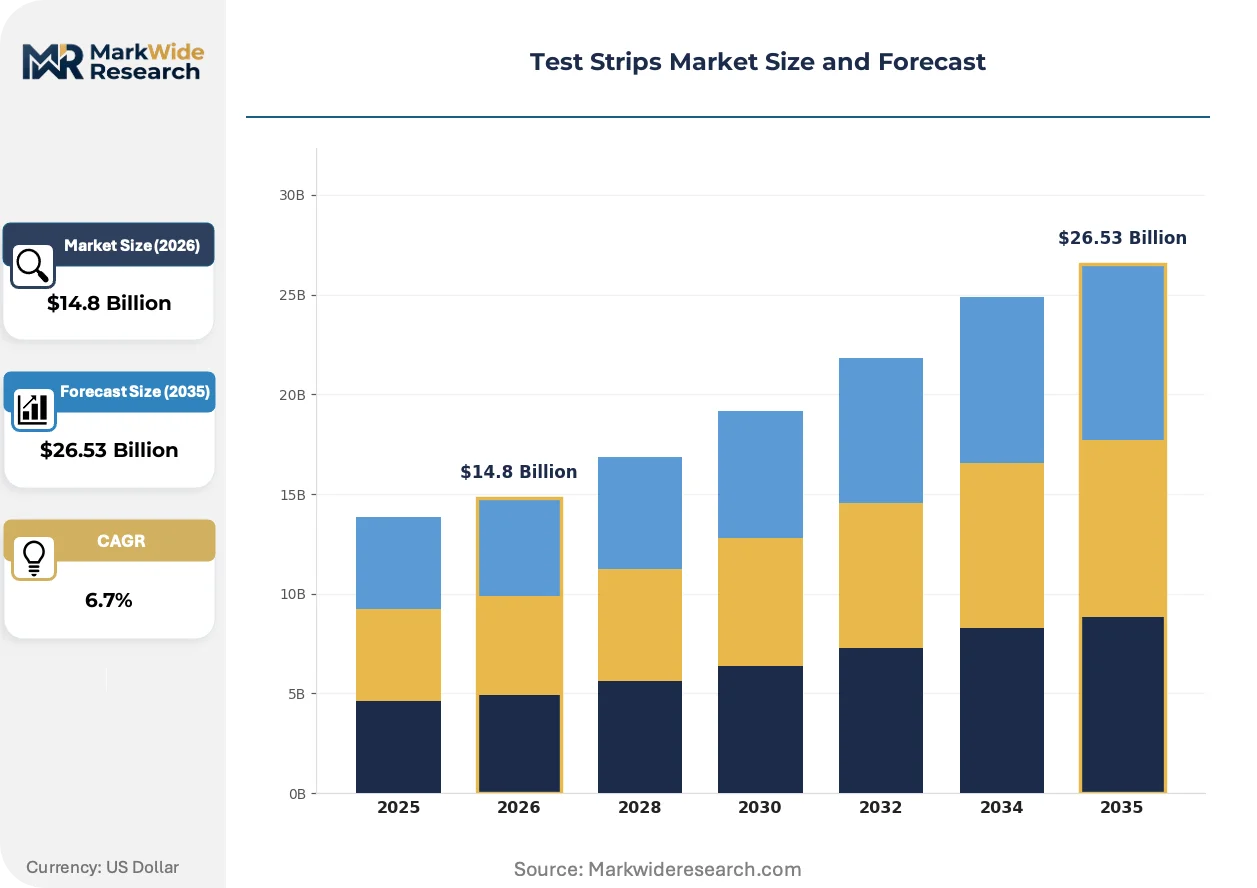
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucose Test Strips, Cholesterol Test Strips, Ovulation Test Strips, Hemoglobin Test Strips End User: Hospitals, Clinics, Home Care, Laboratories Application: Diabetes Management, Fertility Assessment, Cardiovascular Monitoring, Blood Testing Distribution Channel: Retail Pharmacies, Online Stores, Direct Sales, Hospital Supply |
| Companies Covered | Ascensia Diabetes Care, Siemens Healthcare GmbH, Abbott Laboratories, ACON Laboratories Inc, Becton Dickinson and Company, F. Hoffmann-La Roche Ltd, ARKRAY Inc, TaiDoc Technology Corporation, LifeScan Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Test Strips Market Emerging Trajectories
Enzymatic electrochemistry is converging with semiconductor manufacturing techniques, compressing production costs while enabling multi-analyte detection in single-use formats.
Printed biosensor electrodes are hybridizing roll-to-roll manufacturing with precision coating deposition, cutting unit costs for high-volume glucose strip production. Contract manufacturers in East Asia are adopting these hybrid processes to serve both branded and private-label demand. The technology is hybridizing commodity strip economics with performance characteristics previously reserved for laboratory analyzers.
The FDA's 2023 guidance on integrated continuous glucose monitoring systems is tightening accuracy correlation requirements between fingerstick and factory-calibrated sensor readings. Manufacturers must now demonstrate statistical equivalence across hypoglycemic, euglycemic, and hyperglycemic ranges. Blood glucose strip suppliers serving the United States are responding by narrowing production tolerances and expanding in-process testing protocols.
Pharmacy benefit managers are consolidating formulary control over test strip procurement, compressing reimbursement rates and favoring high-volume contract manufacturers. Independent diabetes supply distributors are losing shelf space to vertically integrated pharmacy chains with captive generic programs. The United States exhibits the most pronounced channel consolidation, with three national pharmacy networks controlling over half of reimbursed strip volume.
Test Strips Market Segmentation
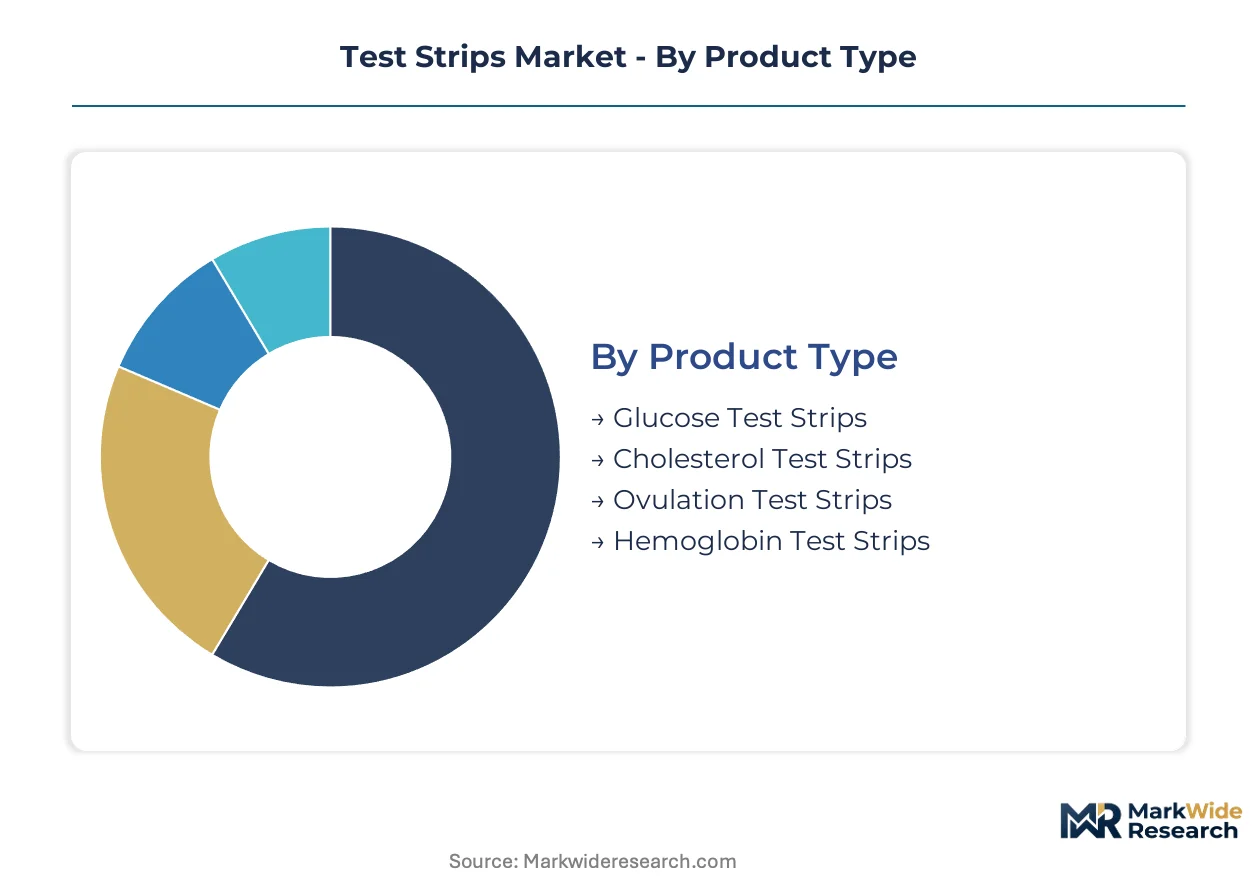
Test strip segmentation reveals distinct margin profiles across enzymatic chemistries and purchasing channels. Manufacturers align R&D investment and pricing architecture to the compliance burden and reimbursement pathway of each vertical.
Product Type:
Cost tier differentiation separates commodity glucose strips from specialized metabolic panels requiring precision electrode engineering.
- Glucose Test Strips:Electrochemical biosensors employing glucose oxidase or dehydrogenase enzymes on printed electrodes. Demand concentrates in United States home care settings where CMS reimbursement sustains high per-capita consumption despite CGM substitution pressure.
- Ovulation Test Strips:Lateral flow immunoassays detecting luteinizing hormone surges in urine samples. Direct-to-consumer fertility tracking in Germany and United Kingdom pharmacy chains drives the steepest volume expansion as women delay conception.
- Cholesterol Test Strips:Dry chemistry reflectance strips for total lipid quantification from capillary blood.
- Hemoglobin Test Strips:Cation-exchange chromatography strips for glycated hemoglobin estimation in point-of-care diabetes monitoring.
Glucose Test Strips command the established base. The steepest expansion runs through Ovulation Test Strips.
End User:
Application context determines accuracy tolerance, with clinical settings demanding ISO 15197 compliance and home environments prioritizing cost accessibility.
- Home Care:Self-monitoring patients purchasing strips through retail or reimbursed channels. United States Medicare expansion for remote glucose monitoring accelerates volume migration from institutional settings.
- Hospitals:Acute care facilities requiring laboratory-correlated accuracy for insulin dosing decisions. FDA 510(k) clearance mandates and Joint Commission accreditation sustain premium pricing for compliant suppliers.
- Clinics:Outpatient facilities balancing throughput economics with diagnostic reliability for chronic disease management.
- Laboratories:Centralized reference sites validating strip performance against analyzer-grade standards for quality control protocols.
Home Care captures volume growth momentum. Hospitals retain margin concentration through compliance barriers.
Application:
Customer type stratification separates chronic disease management platforms from episodic diagnostic use cases with divergent repurchase cycles.
- Diabetes Management:Daily glucose monitoring for insulin titration and HbA1c correlation. Prevalence concentration in United States, India, and China sustains the largest addressable population.
- Fertility Assessment:Hormone tracking for conception timing across menstrual cycles. European pharmacy network expansion and Asian direct-to-consumer platforms drive adoption acceleration.
- Cardiovascular Monitoring:Lipid panel screening for statin therapy adjustment in metabolic syndrome patients.
- Blood Testing:General wellness screening and occupational health monitoring with lower testing frequency.
Diabetes Management anchors installed base economics. Fertility Assessment demonstrates the most rapid adoption curve.
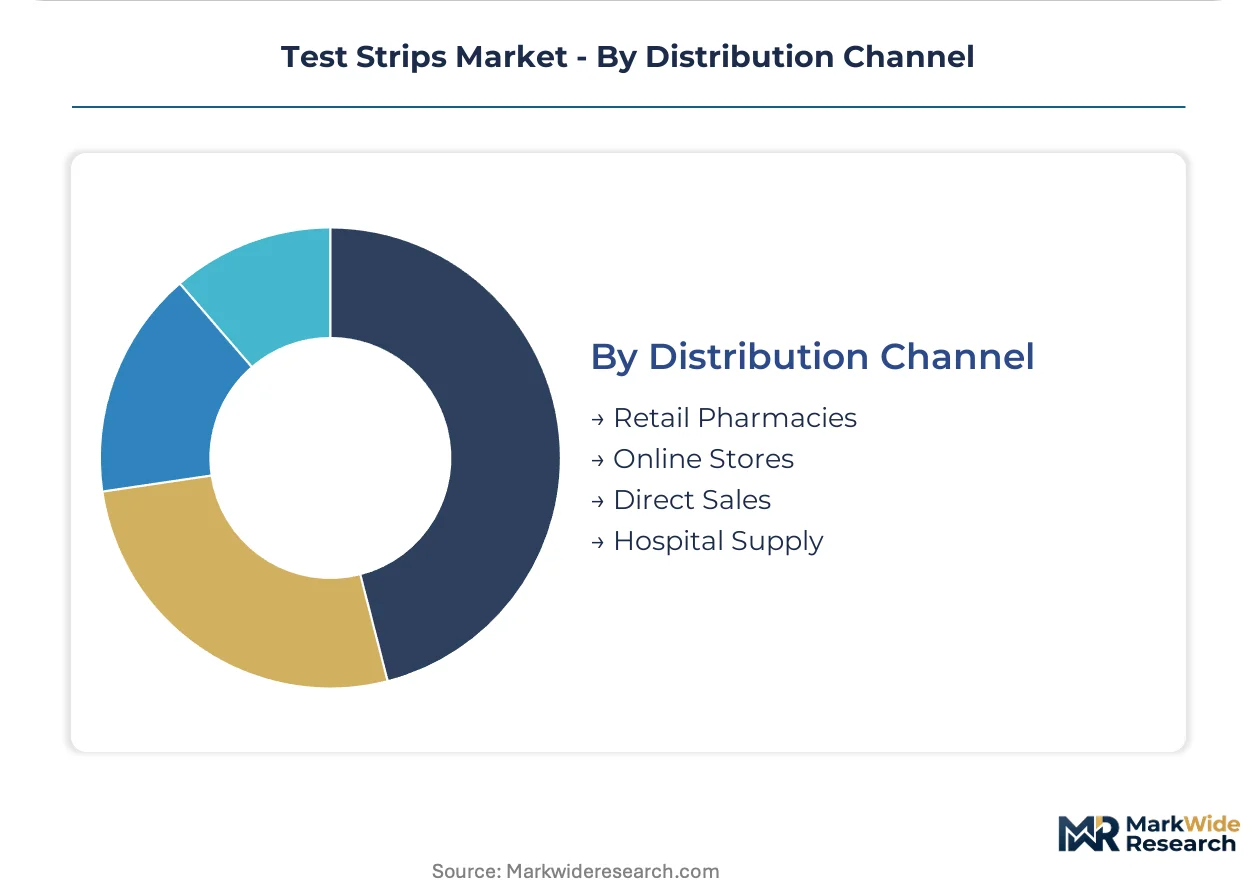
Distribution Channel:
Volume concentration shapes procurement leverage, with consolidated pharmacy networks extracting price concessions from manufacturers dependent on formulary placement.
- Retail Pharmacies:Brick-and-mortar chains and independent drugstores serving walk-in strip demand. Three United States national networks control over half of reimbursed volume, compressing supplier margins through captive generic programs.
- Online Stores:E-commerce platforms and direct-to-consumer subscription models for fertility and wellness strips. Privacy-sensitive ovulation testing and price-transparent glucose strip purchasing gain share fastest in Germany and United Kingdom markets.
- Direct Sales:Manufacturer-to-patient shipments for diabetes supply distributors and institutional procurement.
- Hospital Supply:Group purchasing organization contracts for acute care glucose monitoring programs.
Retail Pharmacies dominate current throughput. Online Stores show the steepest channel shift trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement officers and pharmacy benefit managers concentrate purchasing power in markets with mature reimbursement infrastructure. Self-monitoring patients drive volume in regions expanding remote patient monitoring coverage. Regulatory stringency varies by geography, shaping where premium-tier manufacturers concentrate compliance investment.
United States
Medicare expansion for home-based glucose monitoring accelerates strip consumption outside clinical settings. FDA 510(k) clearance requirements and ISO 15197 accuracy standards govern blood glucose strip performance claims. Three national pharmacy networks in the Northeast and Midwest control over half of reimbursed strip volume, compressing supplier margins through captive generic programs.
Germany
Direct-to-consumer ovulation testing gains share fastest among privacy-sensitive consumers delaying conception. The EU Medical Device Regulation imposes post-market surveillance obligations that protect incumbent positions of manufacturers with established quality management systems. Pharmacy chains in Bavaria and North Rhine-Westphalia expand shelf space for hormone-based diagnostics.
India
Undiagnosed diabetes prevalence and expanding health insurance penetration create whitespace for affordable strip distribution. The country's national pharmaceutical regulator enforces quality standards for point-of-care diagnostics through state-level drug control authorities. Maharashtra and Gujarat host contract manufacturers adopting hybrid roll-to-roll processes to serve both branded and private-label demand.
China
Prevalence concentration of diabetes sustains the largest addressable population for glucose monitoring. NMPA medical device registration requirements elevate compliance costs for new entrants. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta compress production costs while enabling multi-analyte detection in single-use formats.
United Kingdom
Price-transparent glucose strip purchasing gains share through e-commerce platforms and direct-to-consumer subscription models. The national health service procurement frameworks favor high-volume contract manufacturers in formulary placement. London and Southeast England concentrate distribution infrastructure for European pharmacy network expansion.
Test Strips Market Vendor Landscape
Channel-controlling players compete with product-specialist players for formulary placement and retail shelf space. The vendor base fragments across vertically integrated multinationals, regional distributors, and contract manufacturers serving private-label programs. Three strategic archetypes dominate: platform-integrated device manufacturers, precision-focused laboratory suppliers, and high-volume generic producers. Competitive moves concentrate on M&A for pharmacy network access and capacity expansion for roll-to-roll electrode fabrication.
Within the platform-integrated tier, Abbott Laboratories and F. Hoffmann-La Roche Ltd exemplify archetypes anchoring connectivity across hospital and home environments. Siemens Healthcare GmbH occupies a position representing laboratory-grade accuracy differentiation. These three entities sit within distinct competitive vectors—Abbott Laboratories exemplifies digital health ecosystem integration, F. Hoffmann-La Roche Ltd represents European pharmacy network depth, and Siemens Healthcare GmbH anchors clinical-setting performance thresholds.
| Leading Market Players |
|---|
| Ascensia Diabetes Care |
| Siemens Healthcare GmbH |
| Abbott Laboratories |
| ACON Laboratories Inc |
| Becton Dickinson and Company |
| F. Hoffmann-La Roche Ltd |
| ARKRAY Inc |
| TaiDoc Technology Corporation |
| LifeScan Inc |
| Others |
Supply Flow & Price Mechanics
East Asian contract manufacturers of printed biosensor electrodes concentrate capacity for glucose oxidase strips, anchoring margin pools in formulary-controlled pharmacy networks and captive generic programs downstream. This upstream concentration forces branded manufacturers to compete on ISO 15197 certification tiers rather than unit economics alone.
Pricing Analysis
Cost-plus contracts with glucose oxidase price indexation dominate procurement between strip manufacturers and enzyme suppliers, exposing margins to biotech fermentation capacity swings. Pricing stratifies across premium ISO 15197-certified tiers, standard FDA-cleared tiers, and economy private-label tiers, with differentiation driven by accuracy certification and backward integration into electrode fabrication. Pricing pressure stems from pharmacy benefit manager consolidation extracting formulary concessions. Home care patients exhibit highest price sensitivity, while hospital purchasing committees prioritize Joint Commission compliance over unit cost.
Supply Chain Analysis
Export controls on electrochemical sensor fabrication equipment limit technology transfer to emerging manufacturing hubs, constraining capacity expansion outside established clusters. Supply concentrates in China, South Korea, and Germany for precision electrode coating equipment, while glucose oxidase and dehydrogenase enzymes draw from biotech fermentation facilities in the United States and Europe. Single-source vulnerability runs through specialty polymer substrate suppliers. Distribution runs through vertically integrated pharmacy chains with captive generic programs, bypassing independent diabetes supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Test strip demand sits in early-cycle expansion as remote patient monitoring reimbursement policies accelerate home-based glucose monitoring adoption beyond traditional clinical settings.
For Market Incumbents: Pre-empt CGM substitution by embedding NFC connectivity into strip formulations before FDA interoperability mandates harden. Defend formulary position through backward integration into roll-to-roll electrode fabrication in Maharashtra and Gujarat. Lock in glucose oxidase supply through long-term fermentation capacity contracts.
For New Entrants and Emerging Players: Build out affordable strip distribution through India's expanding pharmacy networks, where undiagnosed diabetes prevalence and health insurance penetration create whitespace. Target direct-to-consumer ovulation testing in Germany and United Kingdom privacy-sensitive segments. Launch through e-commerce subscription models bypassing consolidated retail pharmacy gatekeepers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturers holding hybrid roll-to-roll electrode capacity. Long-term viability hinges on digital health integration capabilities rather than commodity strip economics. Watch FDA guidance on CGM-strip accuracy correlation as inflection signal for premium tier repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR post-market surveillance obligations protect incumbent quality management systems from new entrants. |
| Hospital System Partnership | Joint Commission accreditation requirements sustain premium pricing for ISO 15197-compliant strip suppliers. |
| Software Companion Development | NFC-enabled strip connectivity meets FDA interoperability mandates for data portability across CGM platforms. |
| Reimbursement Strategy | CMS remote patient monitoring expansion accelerates volume migration from institutional to home care settings. |
| Backward Integration | In-house roll-to-roll electrode fabrication defends margin against pharmacy benefit manager price compression. |
Methodological Framework
Initial hypotheses were tested against primary input from hospital purchasing committee members, pharmacy benefit manager formulary directors, biomedical engineers at point-of-care device manufacturers, and GPO contracts managers, then refined against secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR post-market surveillance records, and hospital procurement contract disclosures. Bottom-up strip volume estimates by country and channel triangulated against top-down market sizing from manufacturer capacity disclosures.
Demand-supply balance modeling across the analysis window segmented volume by glucose versus ovulation versus multi-analyte strip chemistries, by home care versus hospital versus clinic end-use settings, by retail pharmacy versus online versus direct sales channels, and by ISO 15197 certification tier. CAGRs derived from regression against diabetes prevalence trajectories, fertility tracking adoption curves, and reimbursement policy expansion timelines. Enzyme reagent cost volatility and CGM substitution rates fed sensitivity scenarios.
The forecast holds incumbent behavior within observed patterns; aggressive moves by continuous glucose monitoring platform owners into strip-compatible interoperability would shift outcomes. Material shifts in FDA accuracy correlation requirements or CMS remote monitoring reimbursement rates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Pneumococcal Testing Market
Testing Services
Phenytoin Testing Market
Testing Services
Prothrombin Time Testing Market
Testing Services
Pharmaceutical Sterility Testing Market
Testing Services
North America and Europe Preclinical Medical Device Testing Services Market
Testing Services
Platelet Function Test Market
Testing Services
Preclinical Medical Device Testing Services Market
Testing Services
Rift Valley Fever Testing Market
Testing Services
Chromatin Immunoprecipitation Testing Market
Testing Services
North America Drug Screening Market
Testing Services
Toxicology Drug Screening Market
Testing Services
Rapid Antigen Testing Market
Testing Services
Fecal Occult Testing Market
Testing Services
Esoteric Testing Market
Testing Services
Sports Drug Testing Market
Testing Services
Global Electronystagmography Testing Market