
 West Nile Virus Testing Market | 2026-2036
West Nile Virus Testing Market Size, Share, and Industry Trends Forecast 2026-2036
West Nile Virus Testing Market Analytics
Public health agency demand is repositioning the West Nile Virus Testing Market toward surveillance-dominant procurement models. Abbott Laboratories leverages its point-of-care platform breadth to compete in field-deployable screening. Thermo Fisher Scientific anchors molecular testing workflows through its PCR instrument installed base. F. Hoffmann-La Roche Ltd. differentiates via automated serology systems that sustain high-throughput laboratory throughput.
West Nile Virus Testing encompasses serological, molecular, and antigen-based diagnostic methods designed to detect viral RNA or host antibodies in clinical specimens, typically requiring nucleic acid amplification sensitivity limits below 10 copies per reaction for reliable early infection identification. The primary purpose centers on timely patient diagnosis, vector-borne disease surveillance, and blood supply safety assurance. Serology testing occupies the largest installed base among test type segments due to established immunofluorescence and ELISA workflows, while PCR testing captures the fastest expansion as laboratory infrastructure for molecular arbovirus detection strengthens. Blood donation screening within the application dimension commands premium pricing structures tied to regulatory compliance mandates, whereas research applications exhibit fragmented procurement with variable funding cycles.
The FDA's Emergency Use Authorization framework and the CDC's Laboratory Response Network standards jointly shape assay validation requirements and interstate reporting protocols for West Nile Virus Testing. State public health laboratories operate under CLIA high-complexity certification demands that restrict market access to validated platform providers. Stakeholders must monitor evolving vector distribution patterns and corresponding shifts in seasonal testing demand geography to align capacity investments with outbreak probability corridors.
Market Dynamics
Public health surveillance mandates are compressing assay development timelines and reshaping procurement relationships between state laboratories and diagnostic platform vendors. The CDC's Laboratory Response Network certification requirements now function as a structural gatekeeper determining which assay formats achieve interstate standardization.
Growth Catalysts
- Arbovirus Surveillance Expansion:State public health laboratories are broadening testing panels beyond human clinical specimens to include mosquito pool screening and avian sentinel surveillance, creating sustained reagent demand cycles.
- FDA Emergency Use Authorization Pathway:The streamlined validation framework for emerging infectious disease assays accelerates commercialization timelines for novel molecular detection platforms.
- Blood Donation Screening Mandates:Nucleic acid testing protocols at southern United States donation centers generate recurring high-volume demand during seasonal transmission peaks.
Market Restraints
- CLIA High-Complexity Certification Barriers:Laboratory infrastructure requirements restrict assay deployment to qualified facilities, limiting point-of-care market penetration outside hospital networks.
- Seasonal Demand Volatility:Concentrated testing volume during summer transmission windows in the southern United States creates capacity utilization inefficiencies and inventory management complexity.
- Cross-Reactivity Technical Limitations:Serological assays face specificity challenges from related flaviviruses including dengue and Zika, necessitating confirmatory molecular testing workflows.
Strategic Opportunities
- Multiplex Arbovirus Panels:Convergence of West Nile, Zika, and dengue detection targets onto single PCR platforms reduces per-test costs and streamlines laboratory workflows.
- Vector Control District Integration:Mosquito abatement programs in Texas and Florida represent underpenetrated end-users for field-deployable rapid antigen screening systems.
- CDC Epidemiology and Laboratory Capacity Grants:Federal funding mechanisms for emerging infectious disease preparedness create procurement channels independent of hospital capital budgets.
Industry Challenges
- Molecular Diagnostic Specialist Shortage:Qualified personnel for nucleic acid amplification testing are concentrated in metropolitan reference laboratories, constraining rural and suburban testing access.
- Interstate Reporting Standardization:Variable electronic laboratory reporting formats between state health departments complicates national surveillance data integration and outbreak response coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | West Nile Virus Testing Market |
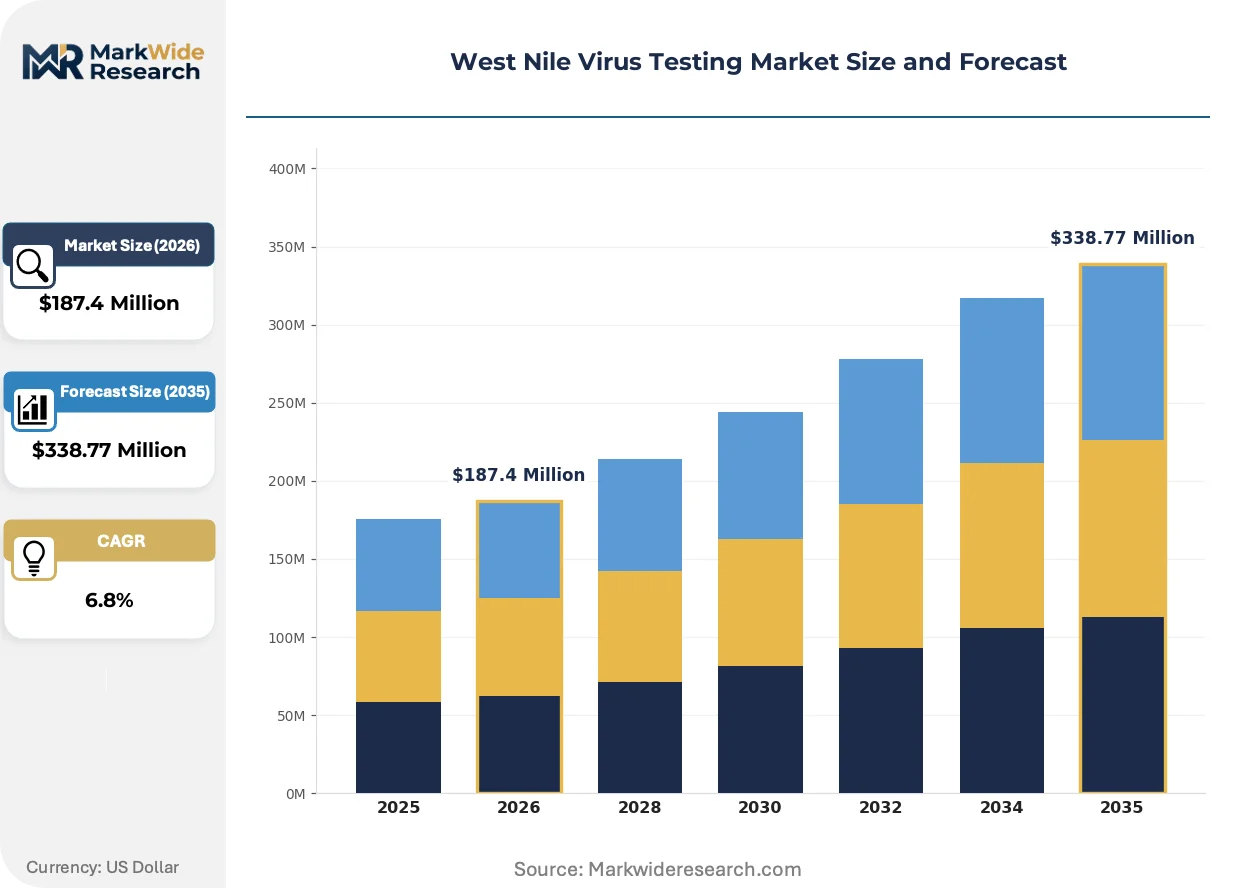
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Serology, PCR, Antigen Detection, Viral Culture Sample Type: Blood, Serum, Plasma, Tissue Application: Diagnosis, Surveillance, Research, Blood Donation Screening End User: Laboratories, Hospitals, Research Institutions, Public Health Agencies |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd., Thermo Fisher Scientific Inc., QIAGEN N.V., Bio-Rad Laboratories, Inc., Siemens Healthineers AG, bioMérieux SA, Cepheid (Danaher Corporation), InBios International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
West Nile Virus Testing Market Evolving Landscape
Diagnostic platform architecture is pivoting toward modular systems capable of simultaneous arbovirus detection, while regulatory frameworks accelerate assay validation for emergency response scenarios. Procurement relationships are simultaneously consolidating around integrated platform vendors and fragmenting across specialized vector control applications.
CRISPR-based nucleic acid detection is overtaking conventional real-time PCR for field-deployable screening applications. Vector control districts in Florida and Texas are piloting these platforms for mosquito pool surveillance. The technology is compressing turnaround times from hours to minutes, enabling same-day source reduction decisions that PCR workflows cannot support.
The FDA's Emergency Use Authorization framework is tightening evidentiary standards for serological assay specificity claims. Manufacturers must now demonstrate cross-reactivity profiles against a broader flavivirus panel prior to authorization. Blood donation screening centers are responding by prioritizing molecular confirmation workflows over standalone serology protocols.
Consolidated service contracts are displacing instrument-reagent unbundling in state public health laboratory procurement. Integrated platform vendors now capture multi-year commitments spanning instruments, assays, and maintenance. This shift is most visible in the southern United States, where seasonal volume spikes favor predictable operational expenditure models over capital-intensive instrument acquisition.
West Nile Virus Testing Market Segmentation
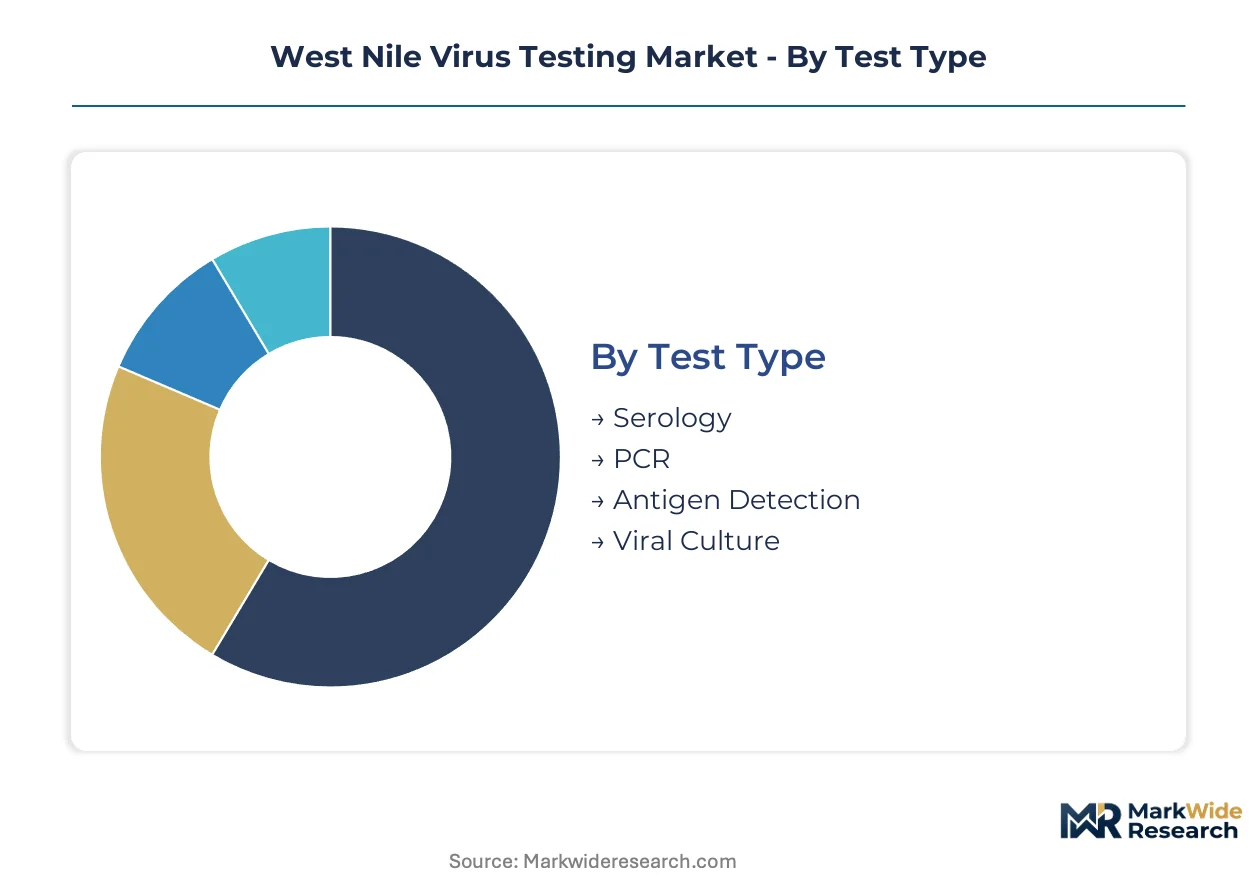
West Nile Virus Testing Market segmentation reveals divergent procurement priorities across clinical, surveillance, and research workflows. Test type selection hinges on sensitivity requirements versus infrastructure constraints, while end-user category determines pricing tolerance and regulatory compliance burden.
Test Type:
Laboratory infrastructure investment and turnaround time requirements differentiate buyer preferences across assay formats.
- Serology:Immunofluorescence and ELISA workflows detect host IgM and IgG antibodies with established protocols in high-complexity CLIA laboratories. Demand concentrates in southern United States public health laboratories during summer transmission windows, constrained by cross-reactivity with dengue and Zika flaviviruses that necessitate confirmatory testing.
- PCR:Nucleic acid amplification platforms achieve sensitivity below 10 copies per reaction for reliable early infection identification. Blood donation screening centers in Texas and Florida drive procurement volume, accelerated by FDA Emergency Use Authorization pathways that compress validation timelines for emerging infectious disease assays.
- Antigen Detection:Rapid immunoassay formats enable field-deployable screening without thermal cycler infrastructure.
- Viral Culture:Isolation methods retain utility for reference laboratory confirmation and strain characterization studies.
Volume sits with Serology; growth tilts toward PCR.
Sample Type:
Specimen stability windows and collection logistics shape processing workflow design across testing sites.
- Blood:EDTA-collected whole blood supports both molecular and serological workflows with standardized phlebotomy protocols. Southern United States blood donation centers generate recurring high-volume demand during seasonal transmission peaks.
- Serum:Clotted blood derivatives enable antibody detection with extended cold-chain stability versus whole blood.
- Plasma:Anticoagulated derivatives preferred for nucleic acid testing protocols in blood banking applications.
- Tissue:Post-mortem specimens support avian sentinel surveillance and neuropathology confirmation in fatal neuroinvasive cases.
Processing economics favor Blood; Plasma gains share fastest in screening applications.
Application:
Regulatory compliance mandates and funding mechanisms create divergent pricing structures across use cases.
- Diagnosis:Clinical patient management drives acute-phase testing with rapid turnaround requirements. Hospital laboratories in high-incidence southern states concentrate demand, constrained by reimbursement variability for arbovirus panels.
- Blood Donation Screening:Nucleic acid testing protocols at southern United States donation centers command premium pricing tied to FDA compliance mandates.
- Surveillance:Mosquito pool screening and avian sentinel monitoring sustain reagent demand cycles in vector control districts.
- Research:Epidemiological studies and assay development exhibit fragmented procurement with federal grant funding dependencies.
Revenue concentrates in Blood Donation Screening; surveillance applications show steepest expansion trajectory.
End User:
Capital availability and technical specialization determine platform selection and contract structure preferences.
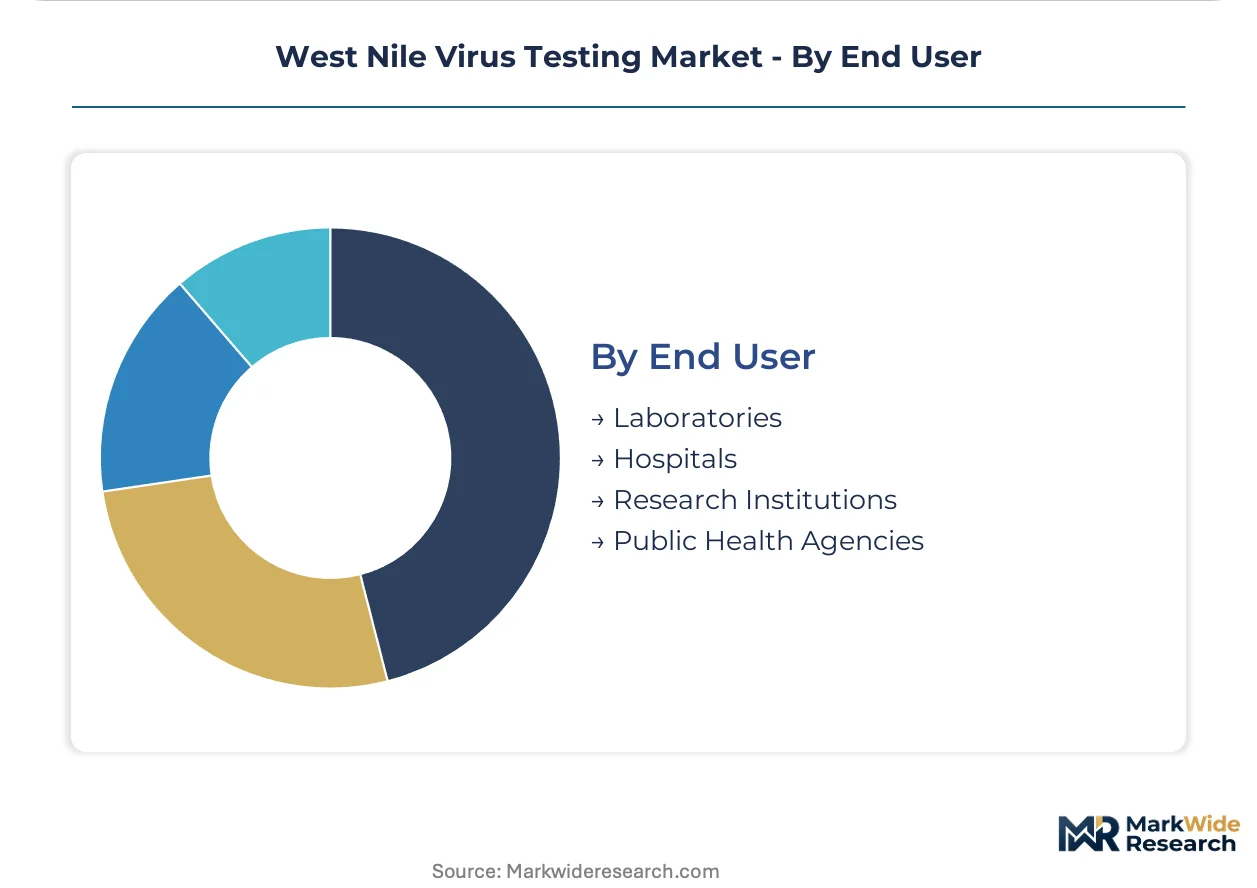
- Laboratories:High-complexity CLIA-certified facilities anchor molecular testing workflows with automated serology systems sustaining throughput. State public health laboratories in the southern United States consolidate procurement through multi-year integrated service contracts.
- Public Health Agencies:CDC Laboratory Response Network certification requirements function as structural gatekeepers for interstate standardization.
- Hospitals:Acute-care facilities prioritize rapid turnaround for neuroinvasive disease differential diagnosis.
- Research Institutions:Academic centers and vector control districts pilot CRISPR-based field-deployable platforms for mosquito pool surveillance.
Instrument placements concentrate in Laboratories; Public Health Agencies drive platform standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southern United States tax-incentive zones for biotechnology manufacturing anchor diagnostic platform concentration. State public health laboratory networks in Texas and Florida drive regional procurement volume. Vector control districts in the Sun Belt generate sustained reagent demand through seasonal transmission cycles.
United States
Blood donation screening centers in Texas and Florida command premium pricing tied to FDA compliance mandates. The CDC's Laboratory Response Network certification requirements structure interstate standardization protocols. Houston and Miami metropolitan clusters concentrate molecular testing infrastructure for arbovirus surveillance panels.
Canada
Provincial public health laboratories in Ontario and Quebec expand arbovirus surveillance beyond traditional endemic zones. Health Canada's regulatory alignment with FDA Emergency Use Authorization frameworks accelerates assay validation timelines. Toronto and Montreal anchor high-complexity CLIA-equivalent testing capacity for seasonal mosquito pool screening.
Germany
Automated serology system demand concentrates in Bavaria and North Rhine-Westphalia reference laboratories. EMA diagnostic device regulations and CE marking requirements shape assay commercialization pathways. Munich and Düsseldorf industrial clusters sustain high-throughput laboratory instrument manufacturing for European export markets.
France
ANSM oversight of in vitro diagnostic medical devices governs assay specificity validation standards. Île-de-France and Auvergne-Rhône-Alpes regions host centralized national reference laboratories for flavivirus differential diagnosis. Paris and Lyon metropolitan areas coordinate European arbovirus surveillance data integration protocols.
Australia
TGA regulatory frameworks for point-of-care molecular devices enable field-deployable screening platform commercialization. New South Wales and Queensland vector control programs pilot CRISPR-based mosquito pool surveillance systems. Sydney and Brisbane public health laboratories anchor regional nucleic acid testing capacity for seasonal outbreak response.
West Nile Virus Testing Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors capturing multi-year service contracts in state public health laboratories. The vendor base concentrates around molecular diagnostics conglomerates and specialized serology instrument manufacturers. Three strategic archetypes dominate: automated high-throughput system providers, point-of-care rapid test developers, and reagent-focused assay specialists. Competitive moves center on multiplex arbovirus panel development and vector control district partnership formation.
Within the integrated diagnostics tier, Abbott Laboratories, F. Hoffmann-La Roche Ltd., and Thermo Fisher Scientific Inc. occupy positions defined by platform breadth and installed base scale. Abbott exemplifies point-of-care expansion into field-deployable screening applications. Roche represents automated serology system standardization for high-volume laboratory workflows. Thermo Fisher anchors molecular testing infrastructure through PCR instrument ecosystem penetration. These three conglomerates sit within a competitive structure where CDC Laboratory Response Network certification functions as a structural gatekeeper for interstate market access.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd. |
| Thermo Fisher Scientific Inc. |
| QIAGEN N.V. |
| Bio-Rad Laboratories, Inc. |
| Siemens Healthineers AG |
| bioMérieux SA |
| Cepheid (Danaher Corporation) |
| InBios International Inc. |
| Others |
Value Network & Pricing Analysis
State public health laboratory consolidation around multi-year integrated service contracts is compressing vendor margins and forcing reagent manufacturers toward predictable operational expenditure models that sacrifice upfront instrument revenue for recurring revenue stability.
Pricing Analysis
Expedited assay validation timelines command premium pricing tiers, while standard lead-time procurement accesses discounted contract rates. The dominant pricing structure runs through tiered service contracts bundling instruments, reagents, and maintenance across premium, standard, and economy certification levels. Price differentiation hinges on FDA Emergency Use Authorization status and CLIA high-complexity laboratory throughput scale. Pricing pressure stems from consolidated procurement at southern United States state laboratories with concentrated seasonal demand. Research institutions exhibit highest price sensitivity due to federal grant funding dependencies; blood donation screening centers show lowest sensitivity tied to regulatory compliance mandates.
Supply Chain Analysis
Single-source vulnerability sits with thermal cycler instrument manufacturing concentrated in the United States, Germany, and Japan. Raw material dependencies encompass specialized polymerases, fluorescence probe chemistries, and cold-chain logistics infrastructure. Supply chain risk centers on regulatory restriction exposure from evolving FDA evidentiary standards for serological assay specificity. Distribution runs through direct vendor-to-laboratory relationships with limited third-party channel penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CLIA-certified molecular testing specialist scarcity props pricing power for qualified platform vendors, creating a supply-constrained market structure favoring incumbents with established personnel training ecosystems.
For Market Incumbents: Lock in multi-year integrated service contracts at southern United States state public health laboratories before federal grant funding cycles refresh competitive procurement windows. Expand backward integration into fluorescence probe chemistry manufacturing to reduce raw material cost volatility exposure. Prioritize CDC Laboratory Response Network certification maintenance as the structural barrier against point-of-care platform substitution threats. For New Entrants and Emerging Players: Launch via vector control district direct sales channels in Texas and Florida, bypassing hospital network CLIA infrastructure requirements that favor established vendors. Target mosquito pool surveillance applications with CRISPR-based field-deployable platforms where incumbent PCR instrument installed base advantages weaken. Pursue CDC Epidemiology and Laboratory Capacity Grants as procurement channels independent of hospital capital budget constraints. For Investors and Strategic Acquirers: The window for entry favors automated serology system specialists with FDA-validated cross-reactivity profiles against dengue and Zika flaviviruses. Long-term viability hinges on multiplex arbovirus panel development capabilities spanning West Nile, Zika, and dengue detection targets. Watch for Emergency Use Authorization pathway tightening as the inflection signal for consolidation pressure on standalone serology assay developers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Emergency Use Authorization Pathway Navigation | Accelerated assay validation compresses commercialization timelines for emerging infectious disease platforms. |
| Multiplex Arbovirus Panel Development | Converged West Nile, Zika, and dengue detection reduces per-test costs and streamlines laboratory workflows. |
| Vector Control District Partnership Formation | Texas and Florida mosquito abatement programs represent underpenetrated end-users for field-deployable screening. |
| Integrated Service Contract Consolidation | Multi-year instrument-reagent-maintenance bundling displaces unbundled procurement at state public health laboratories. |
| CRISPR-Based Field-Deployable Platform Piloting | Same-day turnaround capabilities enable source reduction decisions that PCR workflows cannot support. |
Research Methodology
Multi-period observation of FDA Emergency Use Authorization issuance patterns, CDC Laboratory Response Network certification expansions, and state public health laboratory procurement cycles anchored the trend analysis, supplemented by interviews with diagnostic platform product managers, CLIA laboratory directors, vector control district entomologists, blood donation screening center medical directors, and federal grant program administrators. Secondary validation drew from FDA 510(k) and EUA filing databases, CDC arbovirus surveillance bulletins, state health department electronic laboratory reporting standards, and hospital GPO contract disclosure records. Bottom-up test volume modeling and top-down market sizing triangulation cross-validated segment-level estimates.
Input-output matrices mapped serology, PCR, and antigen detection test type volumes against blood, serum, plasma, and tissue sample type processing economics, with diagnosis, blood donation screening, surveillance, and research application pricing tiers feeding value aggregation across the projection horizon. CAGRs were derived from segmented growth trajectory blending. Forecast inputs incorporated seasonal transmission peak intensity modeling for southern United States geography and vector distribution pattern shifts.
Regulatory pathway delays, vector control district budget freezes, and cross-reactivity assay failure rates are the dominant revision risks to modeled outcomes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Aerospace and Life Sciences TIC Market
Testing Services
INR Test Meter Market
Testing Services
Global Sterility Testing Market
Testing Services
United States Testing, Inspection, and Certification (TIC) Market
Testing Services
Global at-Home Drug of Abuse (DOA) Testing Market
Testing Services
Pharmaceutical Sterility Testing Market
Testing Services
US Independent Diagnostic Testing Facility Market
Testing Services
Anderson Cascade Impactor Market
Testing Services
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market
Testing Services
South America Endotoxin and Pyrogen Testing Market
Testing Services
Ready-To-Use Laboratory Test Kits Market
Testing Services
Ovulation Testing Kits Market
Testing Services
Global Biological Safety Testing Market
Testing Services
Rapid Test Cards Market
Testing Services
Carbapenem-Resistant Enterobacteriaceae Testing Market
Testing Services
Global Bilirubin Colorimeter Assay Market