
 US Independent Diagnostic Testing Facility Market | 2026-2036
US Independent Diagnostic Testing Facility Market Size, Share, and Industry Trends Forecast 2026-2036
US Independent Diagnostic Testing Facility Market Intelligence
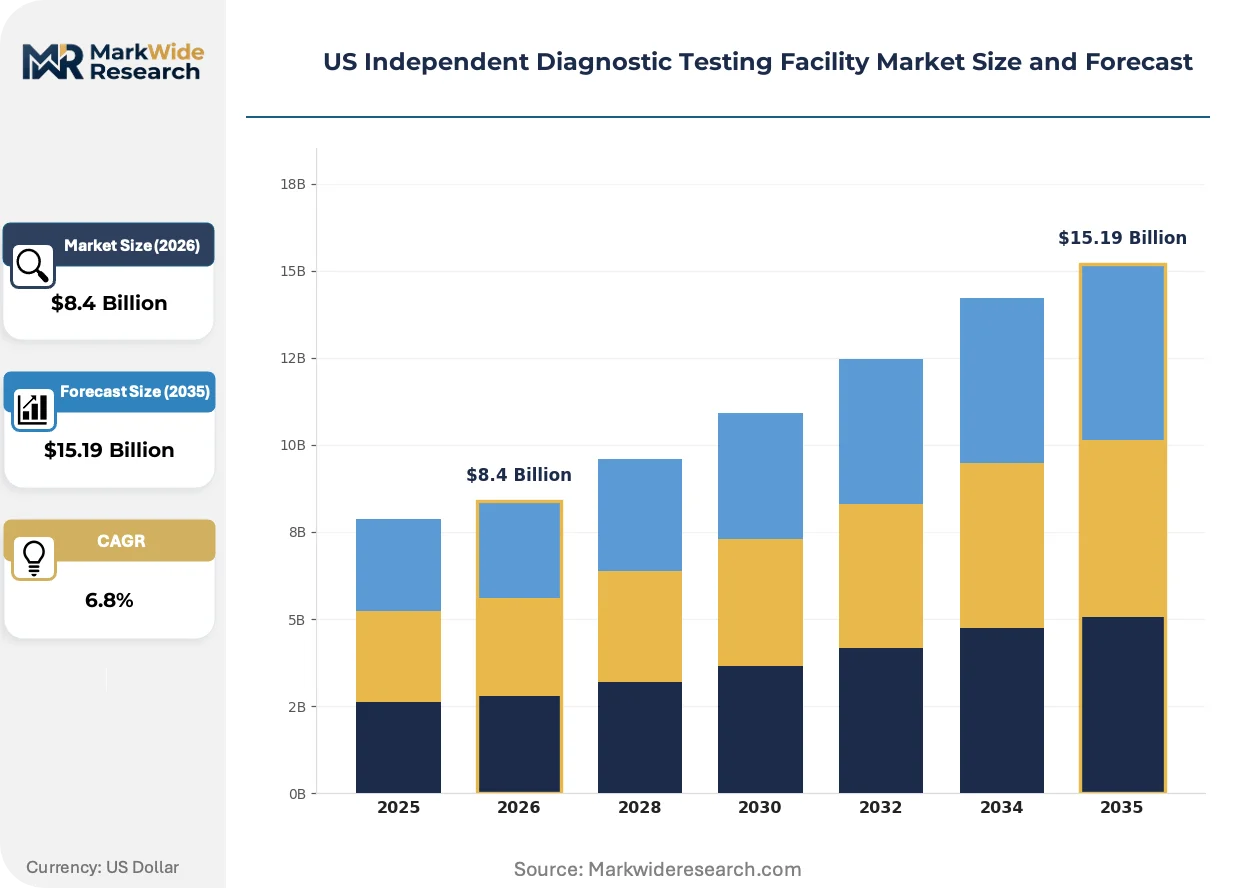
CMS Medicare reimbursement reform toward site-neutral payment parity is consolidating referral patterns away from hospital-based labs. RadNet, Inc. leverages its multi-state imaging network to sustain geographic dominance across California and New York metropolitan corridors. Covenant Health Diagnostics anchors its position through deep specialization in cardiac and vascular diagnostics across Tennessee and surrounding states.
An independent diagnostic testing facility operates outside hospital ownership, performing laboratory analyses and imaging procedures under Clinical Laboratory Improvement Amendments certification with defined analytical sensitivity and specificity thresholds for patient reporting. Molecular diagnostics and next-generation sequencing segments capture expanding margin pools as oncology panels and pharmacogenomic testing shift from academic medical centers to freestanding sites. Clinical chemistry retains the largest service volume but faces commoditization pressure as centralized hospital labs reclaim routine testing.
FDA oversight of laboratory-developed tests, CLIA quality certification requirements, and CAP accreditation standards collectively shape market access and operational compliance burdens for facility operators. Stakeholders must monitor evolving CMS coverage determinations for multi-cancer early detection assays and corresponding prior authorization requirements that will determine referral economics and capital deployment priorities.
Market Dynamics
CMS site-neutral payment parity is consolidating referral flows away from hospital-based laboratories toward freestanding diagnostic facilities, compressing reimbursement differentials and reshaping capital deployment across outpatient networks.
Growth Catalysts
- Protecting Access to Medicare Act:The statute's site-neutral provisions reduce hospital outpatient department reimbursement premiums, steering oncology and cardiology referrals toward independent testing facilities in Texas and Florida.
- Molecular diagnostics:Next-generation sequencing panels for pharmacogenomic testing and liquid biopsy applications are migrating from academic medical centers to CLIA-certified freestanding sites with faster turnaround times.
- Aging demographics:Medicare enrollment expansion across California, Arizona, and Nevada generates sustained volume for cardiac stress testing, vascular ultrasound, and cancer screening protocols.
Market Restraints
- CLIA certification complexity:High-complexity laboratory accreditation demands specialized personnel and proficiency testing expenditures that constrain new market entry in competitive metropolitan corridors.
- Reagent supply concentration:Dependence on concentrated domestic suppliers for specialized molecular diagnostic consumables creates input cost volatility and procurement vulnerability during supply disruptions.
- Laboratory-developed test uncertainty:Pending FDA oversight frameworks for LDTs generate regulatory friction and capital deployment hesitation among operators expanding oncology panel menus.
Strategic Opportunities
- Rural health clinic integration:Federally qualified health centers across Mississippi, Alabama, and rural Texas present underpenetrated access points for mobile imaging and specimen collection networks.
- Multi-cancer early detection:Emerging blood-based screening assays for simultaneous tumor site identification offer white-space expansion beyond single-organ testing protocols.
- Telehealth-tethered diagnostics:Remote physician consultation models paired with local specimen collection and centralized laboratory analysis create channel innovation opportunities in underserved metropolitan peripheries.
Industry Challenges
- Histotechnologist scarcity:Specialized tissue processing and immunohistochemistry staining expertise faces acute workforce gaps, extending turnaround times for anatomic pathology services.
- PACS-EHR interoperability:Legacy picture archiving systems require costly interface engineering to achieve seamless data exchange with diverse hospital and physician practice electronic health records.
- Prior authorization burden:Expanding insurer pre-certification requirements for advanced imaging and molecular testing create administrative friction and revenue cycle elongation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Independent Diagnostic Testing Facility Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Clinical Chemistry, Microbiology, Molecular Diagnostics, Hematology Technology: ELISA, PCR, Immunohistochemistry, Next-Generation Sequencing End User: Hospitals, Outpatient Clinics, Research Laboratories, Public Health Organizations Quality Certification: CLIA, CAP, ISO 15189, JCAHO |
| Companies Covered | Houston MRI & Diagnostic Imaging, ACS Diagnostics, Inc., RadNet, Inc., TestSmarter Inc., Vestavia Diagnostic Center, Vitalistics, The Brookwood Diagnostic Center, Covenant Health Diagnostics, Texas MRI, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Independent Diagnostic Testing Facility Market Strategic Shifts & Innovations
Digital pathology platforms and artificial intelligence-assisted image analysis are compressing diagnostic turnaround times while reducing subspecialist labor dependency across high-volume screening programs.
Whole-slide imaging systems paired with cloud-based computational pathology are modularizing anatomic pathology workflows, enabling remote case distribution and subspecialist consultation without geographic constraint. Regional pathology groups across the Midwest and Southeast are adopting these platforms to address staffing shortages. The technology is modularizing traditional hub-and-spoke laboratory structures into distributed networks with centralized quality oversight.
CMS coverage determination processes for multi-cancer early detection assays are creating precedent-setting reimbursement frameworks that will shape molecular diagnostics economics for the next decade. Commercial payers are awaiting Medicare signaling before establishing parallel prior authorization protocols. Oncology practices in California and New York metropolitan areas are most affected, restructuring patient counseling workflows to accommodate complex screening result interpretation.
Physician employment by health systems is consolidating referral authority and compressing independent laboratory access to inpatient-adjacent testing volumes. Hospital-owned multispecialty groups are directing specimens toward captive laboratory assets, displacing traditional independent facility relationships. This concentration is most visible in Florida and Texas markets where private equity-backed physician practice management platforms have achieved rapid geographic scale.
US Independent Diagnostic Testing Facility Market Segmentation
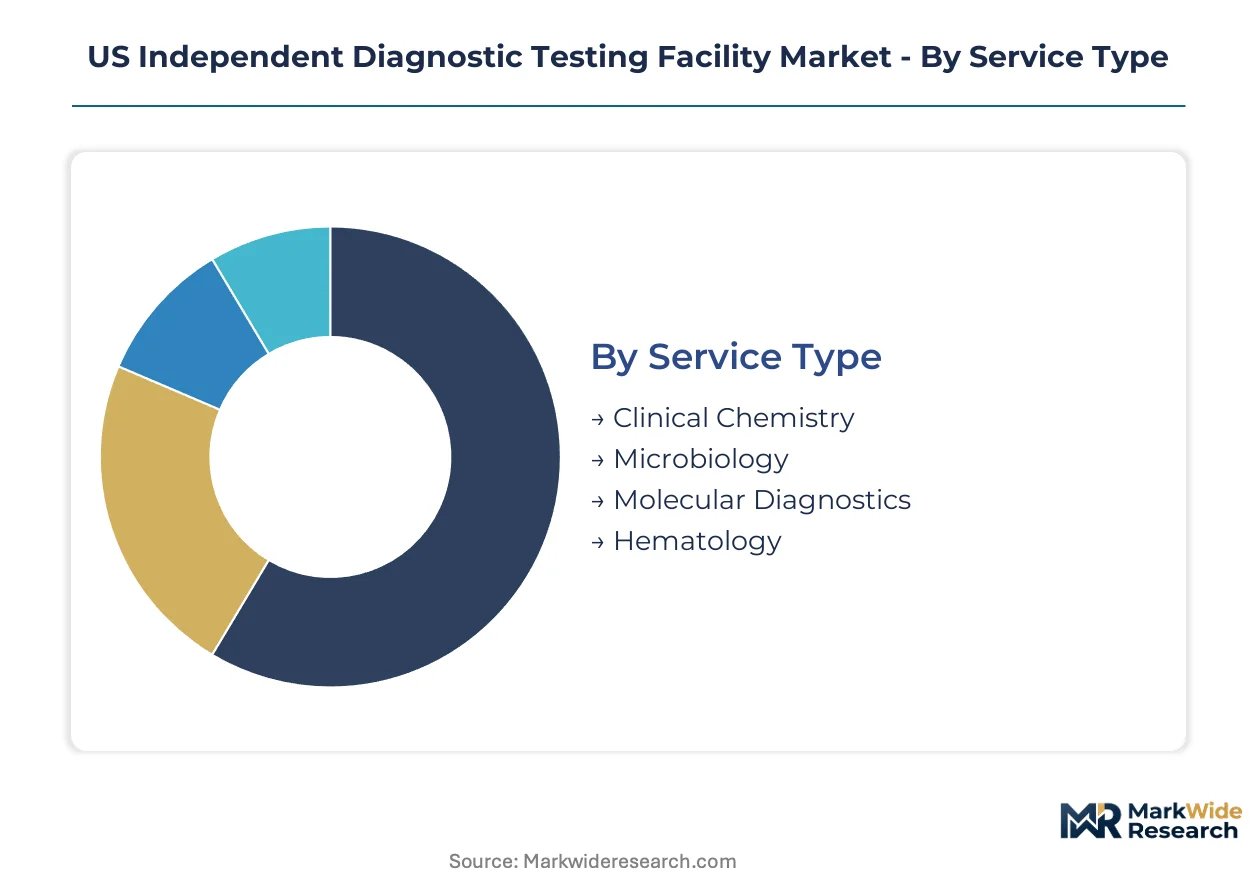
Segmentation reveals how reimbursement economics, technology intensity, and certification requirements fragment purchasing authority across distinct buyer profiles. Understanding these divides clarifies where capital deployment and commercial strategy must concentrate.
Service Type:
Volume concentration and margin structure drive facility investment sequencing across testing modalities.
- Clinical Chemistry:Routine metabolic panels, lipid profiles, and electrolyte analyses constitute the highest test throughput. Demand concentrates in outpatient clinics across Florida and Texas where Medicare site-neutral payment parity accelerates referral migration from hospital labs.
- Molecular Diagnostics:Oncology panels, pharmacogenomic assays, and infectious disease genotyping command premium reimbursement. California and New York metropolitan corridors see fastest adoption as academic medical center workflows shift toward freestanding CLIA-certified sites.
- Microbiology:Bacterial culture, antimicrobial susceptibility testing, and viral isolation support infection control protocols. Public health laboratories in Arizona and Nevada anchor demand.
- Hematology:Complete blood count, coagulation studies, and bone marrow analysis serve oncology and primary care practices. Volume correlates with aging demographics in Pennsylvania and Ohio.
Clinical Chemistry leads on scale; Molecular Diagnostics leads on momentum.
Technology:
Capital intensity and workflow integration requirements shape technology adoption curves.
- Next-Generation Sequencing:High-throughput parallel sequencing enables multi-gene oncology panels and liquid biopsy applications. Research laboratories in Massachusetts and Maryland drive early adoption before clinical translation.
- PCR:Polymerase chain reaction delivers rapid nucleic acid amplification for infectious disease and genetic testing. Outpatient clinics in Texas deploy point-of-care variants for respiratory pathogen detection.
- ELISA:Enzyme-linked immunosorbent assays provide cost-effective protein quantification for hormone and infectious disease markers. Public health organizations leverage standardized protocols for population screening.
- Immunohistochemistry:Antibody-based tissue staining supports cancer diagnosis and biomarker profiling. Hospital-affiliated pathology groups in Florida maintain captive capacity.
PCR dominates current installed base; Next-Generation Sequencing captures steepest expansion trajectory.
End User:
Procurement authority and specimen volume determine contract structure and pricing leverage.
- Outpatient Clinics:Federally qualified health centers and specialty practices generate sustained referral volume. Rural Texas and Mississippi sites present underpenetrated access points for mobile collection networks.
- Hospitals:Emergency departments and surgical services require rapid turnaround for critical care decisions. California health systems increasingly outsource non-core testing to reduce fixed cost burden.
- Research Laboratories:Academic medical centers and pharmaceutical sponsors demand analytical validation for investigational protocols. New York and Boston corridors concentrate contract research spending.
- Public Health Organizations:State health departments and disease surveillance programs mandate standardized reporting formats. Arizona and Nevada enrollment expansion drives communicable disease screening volume.
Outpatient Clinics command volume growth; Research Laboratories dictate technology roadmap.
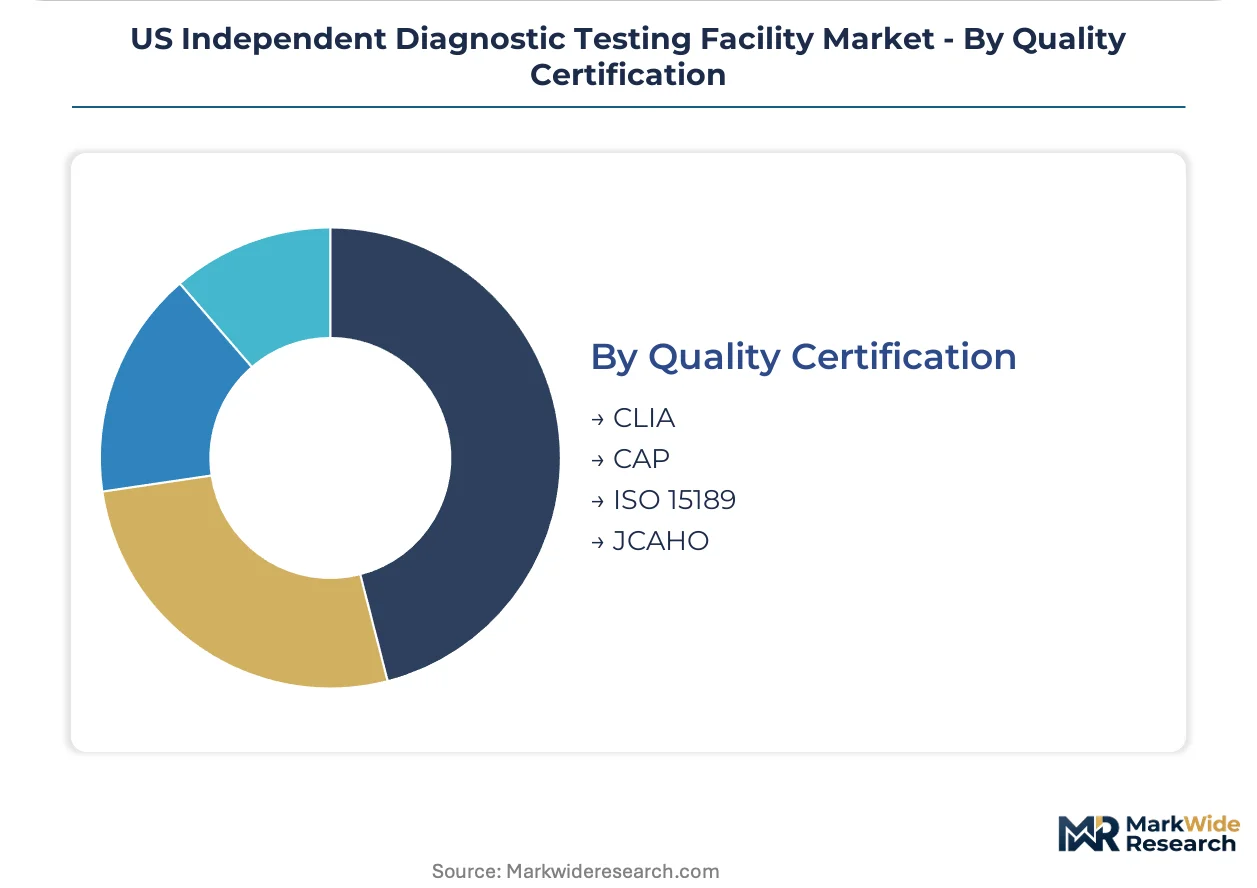
Quality Certification:
Regulatory compliance burden and payer credentialing requirements segment operational capabilities.
- CLIA:Clinical Laboratory Improvement Amendments certification establishes baseline quality standards for patient reporting. High-complexity designation enables molecular diagnostics and specialized testing menus.
- CAP:College of American Pathologists accreditation signals proficiency in anatomic pathology and laboratory management. Florida and Texas facilities pursue dual certification for competitive differentiation.
- ISO 15189:International standard for medical laboratories facilitates cross-border specimen exchange and pharmaceutical sponsor preference. Research-oriented sites in California adopt for global contract eligibility.
- JCAHO:Joint Commission accreditation supports hospital laboratory management contracts and integrated health system relationships. Tennessee and surrounding states see concentration in Covenant Health Diagnostics network.
CLIA represents minimum viable compliance; CAP commands premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US independent diagnostic testing facility industry traces its modern expansion to the 1988 Clinical Laboratory Improvement Amendments, which established federal quality standards enabling freestanding laboratories to compete with hospital-based operations. Medicare reimbursement reforms in subsequent decades accelerated geographic dispersal across metropolitan and rural corridors.
California
Los Angeles and San Francisco metropolitan areas concentrate the nation's highest imaging and molecular diagnostics volume. CMS site-neutral payment parity drives health system outsourcing of non-core testing to independent facilities. The state's aging Medicare enrollment expansion sustains demand for cardiac stress testing and cancer screening protocols across Orange County and San Diego corridors.
Texas
Dallas-Fort Worth and Houston anchor the largest independent imaging networks in the southern United States. The Protecting Access to Medicare Act steers oncology and cardiology referrals away from hospital outpatient departments toward freestanding sites. Rural health clinic integration across the Panhandle and Rio Grande Valley presents underpenetrated access points for mobile collection networks.
Florida
Miami, Tampa, and Orlando metropolitan areas exhibit dense specialty clinic expansion alongside retiree demographic concentration. Private equity-backed physician practice management platforms have achieved rapid geographic scale, consolidating referral authority toward hospital-owned laboratory assets. FDA oversight frameworks for laboratory-developed tests generate regulatory friction among operators expanding oncology panel menus.
New York
New York City and Long Island corridors lead adoption of next-generation sequencing workflows shifting from academic medical centers to CLIA-certified freestanding sites. Commercial payers await Medicare signaling on multi-cancer early detection coverage before establishing parallel prior authorization protocols. The metropolitan periphery offers telehealth-tethered diagnostics opportunities pairing remote physician consultation with local specimen collection.
Tennessee
Nashville and Memphis anchor regional cardiac and vascular diagnostics specialization. Covenant Health Diagnostics maintains network dominance through Joint Commission accreditation supporting hospital laboratory management contracts. Histotechnologist scarcity across the state extends turnaround times for anatomic pathology services despite digital pathology platform adoption.
US Independent Diagnostic Testing Facility Market Key Industry Players
Capital-heavy imaging center operators compete with asset-light laboratory service designers for physician referral relationships and payer network inclusion. The market exhibits moderate consolidation with national networks coexisting alongside state-level specialists and metropolitan single-site operators. Three archetypes dominate: multi-state imaging networks with dense geographic coverage, cardiovascular and oncology-focused specialty laboratories, and hospital-affiliated outpatient ventures capturing system-integrated referrals. M&A activity concentrates on acquiring CLIA-certified sites with established Medicare enrollment, while strategic partnerships with telehealth platforms expand remote patient access.
Within the multi-state network tier, RadNet, Inc. and Covenant Health Diagnostics exemplify divergent geographic strategies. RadNet occupies a position across California and New York metropolitan corridors through dense imaging center networks. Covenant Health Diagnostics anchors southeastern concentration in Tennessee and surrounding states through cardiac and vascular specialization. Among metropolitan-focused operators, Houston MRI & Diagnostic Imaging represents single-market depth. These three illustrate how scale, specialization, and local density constitute alternative viable positions.
| Leading Market Players |
|---|
| Houston MRI & Diagnostic Imaging |
| ACS Diagnostics, Inc. |
| RadNet, Inc. |
| TestSmarter Inc. |
| Vestavia Diagnostic Center |
| Vitalistics |
| The Brookwood Diagnostic Center |
| Covenant Health Diagnostics |
| Texas MRI |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up imaging networks anchor supply consolidation across Texas and Florida metropolitan corridors, translating captive referral relationships into pricing discipline that resists commoditization pressure in routine clinical chemistry panels. Their scale-driven procurement leverage compresses reagent costs while site-neutral Medicare reimbursement parity constrains premium capture in cardiology and oncology testing segments.
Pricing Analysis
Three-tier pricing structure across premium molecular diagnostics, standard imaging services, and economy clinical chemistry panels stratifies revenue capture by certification intensity and turnaround urgency. Price differentiation rests on CLIA high-complexity designation and CAP dual accreditation, with California and New York facilities commanding 15-20 point spreads over unaccredited competitors. Cost compression in routine metabolic panels intensifies as hospital-owned laboratories reclaim outpatient volume through employed physician networks. Federally qualified health centers exhibit acute price sensitivity, while research laboratories and pharmaceutical sponsors demonstrate inelastic demand for validated oncology panel workflows.
Supply Chain Analysis
Histotechnologist scarcity across Tennessee and surrounding states constrains tissue processing capacity, extending immunohistochemistry turnaround times and forcing premium labor sourcing from academic medical center pipelines. Reagent supply draws from concentrated domestic manufacturers in Massachusetts and California for next-generation sequencing consumables, with PCR enzyme production anchored in Maryland research corridors. Single-source vulnerability in specialized molecular diagnostic inputs creates procurement risk during FDA laboratory-developed test enforcement actions. Distribution runs through regional reference laboratory hubs serving spoke collection sites across rural Mississippi, Alabama, and Texas Panhandle corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through digital pathology platform adoption, which compresses labor cost per case while enabling remote subspecialist coverage that commands premium reimbursement in anatomic pathology services.
For Market Incumbents: Extend geographic density through mobile imaging and specimen collection networks targeting rural health clinic integration across Mississippi, Alabama, and rural Texas. Defend against hospital-owned physician practice management platforms by securing exclusive CLIA-certified site contracts with oncology and cardiology specialty groups. Prioritize CAP accreditation investment to maintain pricing power in molecular diagnostics segments where academic medical center referrals are migrating. For New Entrants and Emerging Players: Telehealth-tethered diagnostics platforms present the most penetrable wedge for underserved metropolitan peripheries, pairing remote physician consultation with local specimen collection infrastructure. Target multi-cancer early detection assay distribution partnerships in advance of CMS coverage determinations, positioning for first-mover advantage in blood-based screening protocols. Pursue direct-to-employer contracting models that bypass traditional payer prior authorization friction. For Investors and Strategic Acquirers: Valuations sit cheapest among single-site metropolitan operators with established Medicare enrollment but limited molecular diagnostics menu expansion. Long-term viability centers on facilities with dual CLIA-CAP certification and demonstrated proficiency in next-generation sequencing workflow implementation. Watch FDA final guidance on laboratory-developed test oversight as the critical inflection signal for capital deployment timing in oncology panel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA High-Complexity Certification Investment | Enables molecular diagnostics menu expansion that captures premium reimbursement from oncology panel migration. |
| Digital Pathology Platform Deployment | Addresses histotechnologist scarcity through cloud-based case distribution and AI-assisted image analysis. |
| Rural Health Clinic Integration | Creates mobile collection network access points across underpenetrated Mississippi, Alabama, and Texas corridors. |
| Multi-Cancer Early Detection Assay Partnership | Positions for CMS coverage determination precedent that will shape molecular diagnostics economics. |
| Telehealth-Tethered Diagnostics Channel | Pairs remote physician consultation with local specimen collection for metropolitan periphery expansion. |
Research Approach
Direct dialogue with laboratory operations directors, CLIA compliance officers, hospital purchasing committee members, and GPO contracts managers grounded qualitative assessment of facility economics and referral pattern shifts. Secondary validation drew from CMS Medicare reimbursement databases, FDA laboratory-developed test guidance dockets, CAP accreditation directories, and state health department surveillance reports. Bottom-up facility capacity modeling triangulated against top-down Medicare claims volume analysis.
Segment-level revenue and volume trajectories across the projection horizon reflect analytical frameworks incorporating service type intensity, technology capital requirements, certification tier, and end-user procurement authority. Modeled dimensions span clinical chemistry throughput, molecular diagnostics reimbursement tiers, next-generation sequencing adoption curves, and outpatient clinic referral concentration. CAGRs emerged from regression analysis against Medicare enrollment expansion, site-neutral payment parity implementation, and specialty clinic geographic penetration.
The model holds under stable CMS reimbursement policy and continued site-neutral payment parity enforcement; deviation in FDA laboratory-developed test oversight timing or multi-cancer early detection coverage determinations would shift capital deployment priorities and facility expansion trajectories. Material deviation in histotechnologist workforce availability or reagent supply concentration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Toxicology Drug Screening Market
Testing Services
Vials Leak Testing Market
Testing Services
Fertility Testing Market
Testing Services
Mask Bacterial Filtration Efficiency Tester Market
Testing Services
Arthropod-Borne Viral Infections Testing Market
Testing Services
North America Endotoxin and Pyrogen Testing Market
Testing Services
Candida Vaginitis Rapid Testing Market
Testing Services
Rapid Coagulation Testing Market
Testing Services
Global Specimen Validity Testing Market
Testing Services
Blood Borne Testing Market
Testing Services
Ovulation Test Kit Market
Testing Services
Ready-To-Use Laboratory Test Kits Market
Testing Services
Point of Care Testing Market
Testing Services
Warfarin Sensitivity Test Market
Testing Services
Friability Tester Market
Testing Services
Asia-Pacific Viral Clearance Market