
 Arbovirus Testing Market | 2026-2036
Arbovirus Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Arbovirus Testing Market Analysis
Multiplex PCR specification upgrades is reorganizing competitive dynamics in arbovirus diagnostics. Abbott Laboratories leverages its integrated molecular platform to anchor hospital laboratory contracts across endemic regions. Roche Diagnostics sustains R&D intensity in automated sample-to-answer systems that reduce technician handling time. Thermo Fisher Scientific specializes in research-grade reagent supply chains that feed both clinical and surveillance networks.
Arbovirus testing encompasses molecular, serological, and antigen-based methods for detecting RNA viruses transmitted by arthropod vectors, typically requiring cold-chain reagent stability between two and eight degrees Celsius and nucleic acid extraction protocols with sensitivity thresholds below ten copies per microliter. The primary commercial purpose centers on differential diagnosis of dengue, Zika, chikungunya, and West Nile virus in febrile patients where clinical presentation overlaps. Molecular diagnostics occupies the highest-margin tier within product type segmentation due to multiplexing capacity and quantitative viral load reporting. Public health organizations represent the fastest-growing end user channel as national surveillance programs integrate point-of-care rapid testing into vector control operations.
FDA emergency use authorization pathways and WHO emergency use listing procedures shape product entry timelines for novel arbovirus assays, while EMA's CE-IVDR transition imposes stricter clinical evidence requirements on serological kit manufacturers. EPA vector control coordination with diagnostic data reporting creates interagency demand linkages in the United States. Stakeholders must monitor climate-driven expansion of Aedes aegypti habitat into temperate zones to anticipate geographic demand redistribution for testing infrastructure.
Market Dynamics
Multiplex molecular diagnostics is fragmenting the traditional serology-dominant testing hierarchy as laboratories demand simultaneous detection of dengue, Zika, and chikungunya from single specimens. Cold-chain logistics requirements and nucleic acid extraction complexity create tiered capability gaps between hospital laboratories and point-of-care settings.
Growth Catalysts
- WHO Emergency Use Listing:The prequalification pathway accelerates assay validation for tropical disease diagnostics, compressing regulatory timelines for manufacturers targeting endemic markets in Brazil and Southeast Asia.
- Climate-Driven Vector Expansion:Aedes aegypti habitat migration into temperate zones extends the addressable patient population beyond historical dengue belts, forcing health systems to build testing infrastructure in previously unaffected regions.
- Surveillance Integration:National vector control programs in India and Thailand now mandate diagnostic reporting linkage to entomological monitoring, institutionalizing testing demand through public health procurement channels.
Market Restraints
- Cold-Chain Dependency:Reagent stability requirements between two and eight degrees Celsius impose infrastructure costs that exclude rural clinics and field settings from molecular testing adoption.
- CE-IVDR Clinical Evidence Burden:The European Medical Device Regulation transition demands expanded serological kit validation studies, extending time-to-market and elevating compliance expenditure for manufacturers.
- Antigen Cross-Reactivity:Serological methods face inherent diagnostic uncertainty where flavivirus antibody responses overlap, limiting standalone clinical utility and necessitating confirmatory molecular testing.
Strategic Opportunities
- Lyophilized Reagent Formats:Ambient-stable nucleic acid extraction chemistries eliminate cold-chain requirements, enabling molecular testing deployment at peripheral health posts and border screening stations.
- Digital PCR Quantification:Absolute viral load enumeration without calibration curves supports therapeutic monitoring and vaccine trial endpoints, creating premium pricing tiers in research and clinical trial networks.
- EPA Diagnostic-Vector Control Coordination:The United States Environmental Protection Agency's integration of human case data into spraying prioritization algorithms institutionalizes testing demand through interagency funding mechanisms.
Industry Challenges
- Technician Training Deficits:Nucleic acid extraction protocols demand laboratory personnel competency in contamination control and thermocycler operation, creating bottlenecks at facilities transitioning from rapid immunochromatographic methods.
- Sample-to-Answer Integration Complexity:Automated platforms require reconfiguration of existing laboratory workflows and information system interfaces, extending implementation timelines and elevating total cost of ownership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arbovirus Testing Market |
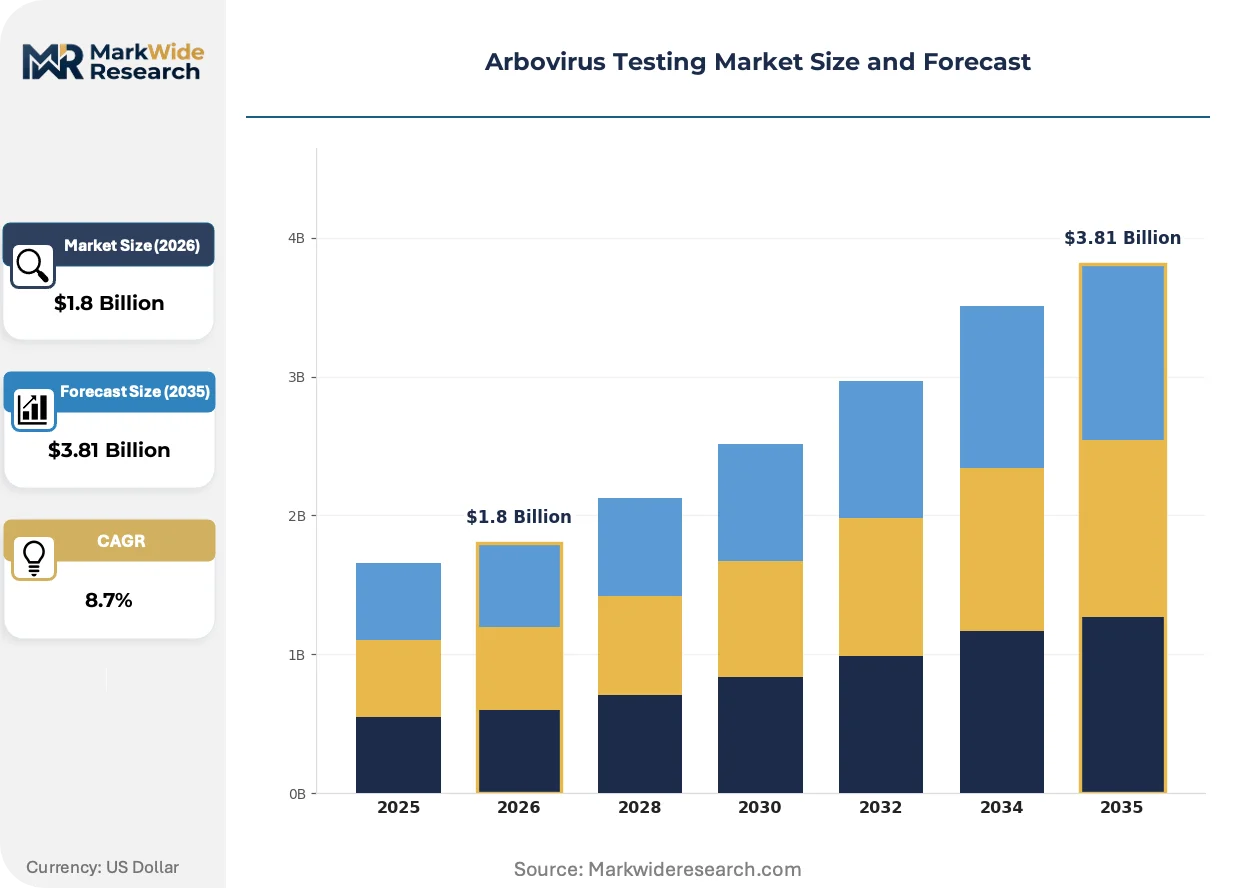
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR Kits, Serological Test Kits, Antigen Detection Kits, Viral Culture Systems End User: Hospitals, Diagnostic Laboratories, Research Institutions, Public Health Organizations Technology: Molecular Diagnostics, ELISA, Next-Generation Sequencing, Rapid Testing Application: Disease Surveillance, Outbreak Investigation, Epidemiological Studies, Blood Screening |
| Companies Covered | Abbott Laboratories, Roche Diagnostics, Thermo Fisher Scientific, Bio-Rad Laboratories, Cepheid, bioMérieux, Siemens Healthineers, QIAGEN, DiaSorin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arbovirus Testing Market Emerging Trajectories
Arbovirus diagnostics is fragmenting across three simultaneous axes: molecular multiplexing depth, regulatory pathway diversification, and procurement model restructuring. These shifts compress traditional technology lifecycles while expanding addressable settings.
Cartridge-based integrated molecular systems is fragmenting the historical separation between extraction, amplification, and detection workflows. Hospital laboratories in endemic regions are adopting these platforms to reduce technician handling steps and contamination risk. The consolidation is compressing demand for standalone extraction chemistries and open-system thermocyclers.
FDA Emergency Use Authorization pathway refinements for emerging infectious diseases compress pre-market review timelines for novel arbovirus assays during outbreak declarations. Manufacturers now maintain modular submission packages that activate upon epidemic triggers. The policy shift most affects developers targeting dual-use surveillance-clinical products for the United States market.
Public health procurement consolidation is aggregating testing demand through national tender mechanisms in Brazil, India, and Thailand. Single-source contracts for multi-year panel supply are displacing fragmented hospital-level purchasing. The behavioral shift concentrates vendor negotiation leverage with ministry-level procurement authorities rather than individual laboratory managers.
Arbovirus Testing Market Segmentation
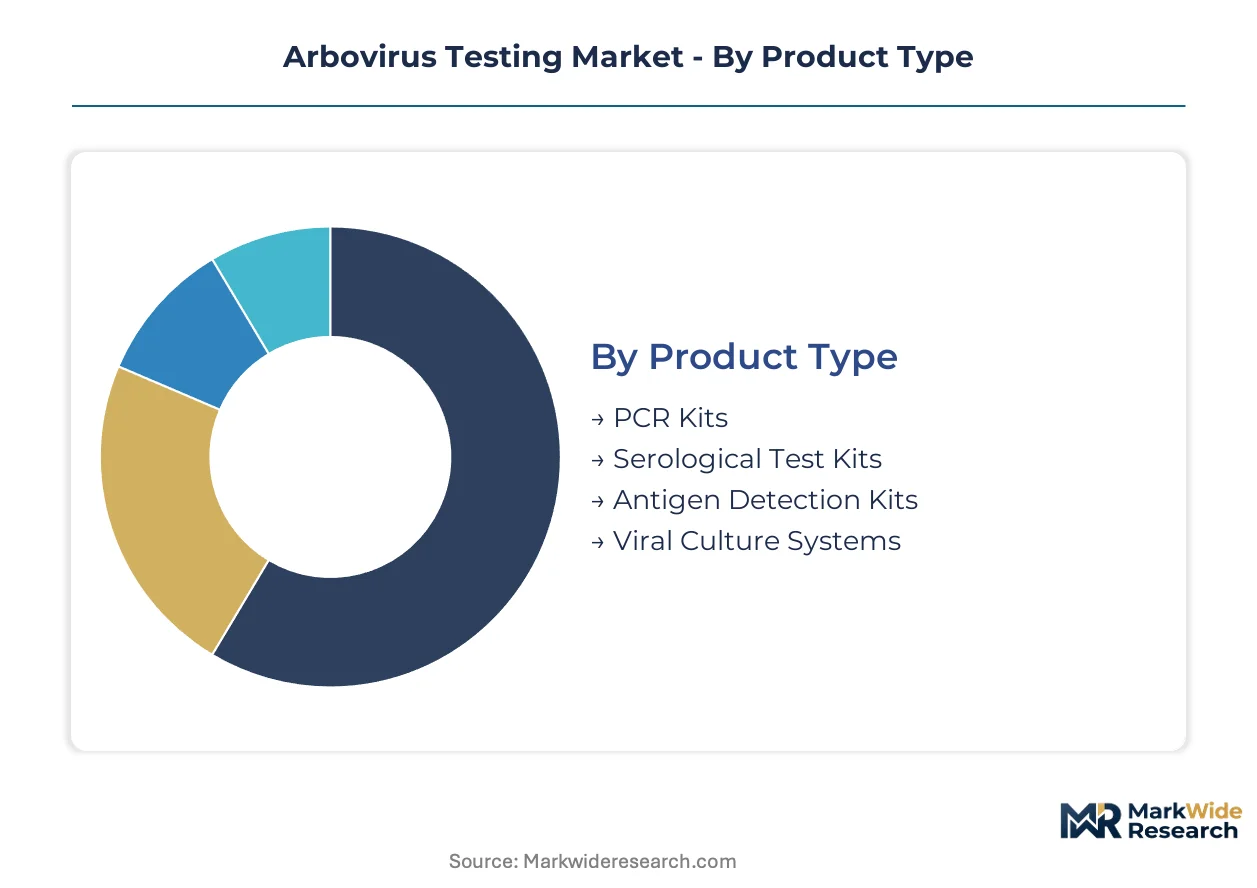
Arbovirus testing segments fragment along capability tiers that separate centralized laboratory infrastructure from distributed point-of-care deployment. Substitution pressures vary sharply across these divides, with molecular platforms facing ambient-stable rapid test encroachment in field settings while serology confronts multiplex PCR displacement in hospital laboratories.
Product Type:
PCR kits face the most acute substitution threat as lyophilized reagent formats and isothermal amplification methods erode their cold-chain monopoly in peripheral health posts.
- PCR Kits:Nucleic acid amplification systems requiring thermocycling infrastructure and nucleic acid extraction protocols with sensitivity below ten copies per microliter. Demand concentrates in Brazilian hospital networks and Southeast Asian reference laboratories where differential diagnosis of dengue, Zika, and chikungunya from single specimens drives panel adoption. Multiplexing capacity sustains premium positioning despite ambient-stable alternatives.
- Serological Test Kits:Antibody detection platforms utilizing ELISA and immunochromatographic formats for IgM/IgG profiling. Indian national tenders and Thai ministry procurement channels absorb volume for surveillance integration with entomological monitoring. Cross-reactivity limitations between flaviviruses constrain standalone clinical utility.
- Antigen Detection Kits:Rapid immunochromatographic devices delivering results without laboratory infrastructure.
- Viral Culture Systems:Reference-grade isolation methods retained for strain characterization and vaccine development.
PCR kits anchor the volume base while antigen detection kits gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive hospital installations from lean public health procurement models that prioritize unit economics over feature depth.
- Hospitals:Acute care facilities managing febrile patient triage and differential diagnosis workflows. Brazilian and Indian tertiary centers drive automated sample-to-answer platform adoption to reduce technician handling time and contamination risk.
- Diagnostic Laboratories:Independent and hospital-affiliated testing facilities processing high-throughput specimen volumes. Southeast Asian networks expand arbovirus panel menus as climate migration shifts vector distributions into previously unaffected catchment areas.
- Research Institutions:Academic and commercial entities conducting vaccine trials and therapeutic monitoring.
- Public Health Organizations:National surveillance programs and vector control operations in Brazil, India, and Thailand. EPA diagnostic-vector control coordination in the United States institutionalizes demand through interagency funding mechanisms.
Diagnostic laboratories dominate current revenue while public health organizations expand most quickly.
Technology:
Application context determines technology selection, with outbreak investigation demanding speed and epidemiological studies requiring phylogenetic resolution.
- Molecular Diagnostics:PCR and isothermal amplification methods occupying the highest-margin tier through quantitative viral load reporting and multiplexing capacity. FDA Emergency Use Authorization pathway refinements compress pre-market review timelines for novel assays during outbreak declarations.
- ELISA:Enzyme-linked immunosorbent assay platforms for antibody quantification in seroprevalence studies. CE-IVDR transition imposes stricter clinical evidence requirements on kit manufacturers, extending time-to-market.
- Next-Generation Sequencing:Whole-genome characterization for phylogenetic tracking and novel variant identification.
- Rapid Testing:Lateral flow and immunochromatographic devices enabling point-of-care deployment without cold-chain dependency.
Molecular diagnostics commands the premium tier while rapid testing climbs the fastest.
Application:
Customer maturity separates institutionalized surveillance programs from reactive outbreak response modalities with volatile procurement timing.
- Disease Surveillance:Systematic monitoring of arbovirus circulation through sentinel sites and routine screening. Thai national programs mandate diagnostic reporting linkage to entomological monitoring, embedding demand in vector control operations.
- Outbreak Investigation:Epidemic response testing with compressed turnaround requirements. WHO Emergency Use Listing accelerates assay validation, compressing regulatory timelines for manufacturers targeting endemic markets.
- Epidemiological Studies:Population-level seroprevalence and transmission dynamics research.
- Blood Screening:Donor testing protocols for transfusion-transmitted arbovirus prevention.
Disease surveillance anchors the volume base while outbreak investigation shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public health procurement in Brazil and India absorbs volume at price points that exclude premium-tier vendors, while hospital laboratories in the United States and Germany sustain margins for automated sample-to-answer platforms. This elasticity gap fragments vendor pricing power across geographies.
United States
Hospital networks in Texas and Florida deploy multiplex PCR panels as Aedes aegypti habitat expands into temperate zones. EPA diagnostic-vector control coordination institutionalizes testing demand through interagency funding mechanisms that link human case data to spraying prioritization algorithms. The Southeast corridor from Miami to Houston anchors infrastructure investment for febrile patient triage.
Brazil
ANVISA regulatory pathways and national tender mechanisms aggregate demand through ministry-level procurement rather than fragmented hospital purchasing. São Paulo and Rio de Janeiro reference laboratories anchor automated platform adoption for differential diagnosis of dengue, Zika, and chikungunya. Public health surveillance integration mandates diagnostic reporting linkage to entomological monitoring.
India
CDSCO oversight and national vector control programs in Maharashtra and Tamil Nadu drive serological kit volumes for surveillance integration. Diagnostic laboratories in Mumbai and Chennai expand arbovirus panel menus as climate migration shifts vector distributions into previously unaffected catchment areas. Ministry procurement channels absorb cost-sensitive volume.
Germany
CE-IVDR transition imposes stricter clinical evidence requirements that extend time-to-market for serological kit manufacturers targeting European hospital networks. Bavarian and Baden-Württemberg reference laboratories sustain premium positioning for quantitative viral load reporting. EMA regulatory convergence shapes product entry timelines for tropical disease diagnostics.
Thailand
WHO Emergency Use Listing accelerates assay validation for manufacturers targeting endemic markets in Southeast Asia. Bangkok-centered laboratory networks mandate diagnostic reporting linkage to national vector control operations. Ministry of Public Health procurement consolidation aggregates multi-year panel supply contracts.
Arbovirus Testing Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated molecular platform vendors commanding hospital laboratory contracts while reagent specialists feed surveillance networks at lower margin tiers. The vendor base organizes around three strategic positions: automated sample-to-answer systems, research-grade reagent supply chains, and rapid point-of-care devices. Consolidation pressures concentrate negotiation leverage with ministry-level procurement authorities in Brazil, India, and Thailand. Competitive moves center on regulatory pathway diversification and lyophilized reagent format development.
Among diversified diagnostics conglomerates, Abbott Laboratories and Roche Diagnostics occupy positions anchored in hospital laboratory automation, while Thermo Fisher Scientific exemplifies the research-reagent specialist archetype. Abbott represents the integrated platform model with molecular system contracts across endemic regions. Roche sits within the premium automated tier with sustained R&D intensity in sample-to-answer workflows. Thermo Fisher anchors the reagent supply chain position feeding both clinical and surveillance networks. These three patterns illustrate how vendor archetypes align with distinct procurement channels and price elasticity profiles.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Diagnostics |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Cepheid |
| bioMérieux |
| Siemens Healthineers |
| QIAGEN |
| DiaSorin |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at lyophilized reagent manufacturing facilities in Germany and the United States shapes both supply concentration and price floors for molecular diagnostics. Scale advantages at these production nodes compress unit economics for ambient-stable formats while cold-chain-dependent PCR kits face persistent cost premiums from refrigerated logistics infrastructure.
Pricing Analysis
FDA Emergency Use Authorization pathways dictate the pricing tier structure across the arbovirus testing landscape. Three-tier pricing structure across premium, standard, and economy levels separates automated sample-to-answer systems from open-platform PCR kits and rapid immunochromatographic devices. Price differentiation hinges on certification grade and volume scale, with Brazilian national tender mechanisms driving cost compression in economy tiers. Margins are tightening due to ministry-level procurement consolidation in India and Thailand.
Supply Chain Analysis
Cold-chain logistics chokepoints at regional distribution hubs in São Paulo and Mumbai tether supply reliability to refrigerated transport capacity. Manufacturing concentrates in Germany, the United States, and Singapore for nucleic acid extraction chemistries and thermocycler components. Raw material dependencies span purified enzymes, fluorescent probes, and specialized polymerases. Single-source vulnerability from sole-supplier enzyme manufacturers elevates disruption risk. Distribution runs through national tender authorities and hospital group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized competency in nucleic acid extraction protocol optimization represents the scarcest capability layer in arbovirus diagnostics, constraining laboratory transition from serology to molecular methods.
For Market Incumbents: Consolidate hospital laboratory contracts in Brazilian and Indian tertiary centers through automated platform leasing arrangements. Deepen backward integration into lyophilized reagent manufacturing to offset cold-chain cost premiums. Anchor defensive positioning against ambient-stable rapid test encroachment by embedding workflow reconfiguration services into platform contracts. For New Entrants and Emerging Players: Differentiate on ambient-stable molecular formats targeting peripheral health posts and border screening stations in Southeast Asia. Penetrate Thai and Indian public health procurement channels through WHO Emergency Use Listing pathway acceleration. Deploy direct ministry engagement models that bypass fragmented hospital-level purchasing. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated molecular platform vendors with multi-year service contracts. Long-term viability favors automated sample-to-answer specialists with installed base expansion capacity. Monitor EPA diagnostic-vector control coordination funding allocations as inflection indicators for United States demand institutionalization.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Emergency Use Listing Pathway | Accelerates assay validation for Brazilian and Southeast Asian endemic market entry. |
| Lyophilized Reagent Development | Eliminates cold-chain dependency for molecular testing at peripheral health posts. |
| Hospital System Partnership | Secures automated platform placement in São Paulo and Rio de Janeiro reference laboratories. |
| CE-IVDR Certification Investment | Enables European hospital network access amid stricter serological kit evidence requirements. |
| EPA Diagnostic-Vector Control Coordination | Institutionalizes United States demand through interagency human case data integration. |
Methodological Framework
The analysis maps molecular diagnostics, serological testing, and rapid antigen detection sub-sectors, each validated through hospital laboratory directors, public health procurement officers, and regulatory affairs specialists. Primary interviews with biomedical engineers, GPO contracts managers, and vector control program administrators combined with secondary validation against FDA Emergency Use Authorization databases, WHO prequalification listings, and ANVISA registration filings. Bottom-up and top-down triangulation anchored volume estimates.
Consistency checks against external benchmarks validated analytical framework outputs across the projection horizon. Segmentation dimensions modeled include product type, end-user channel, technology platform, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating climate-driven vector expansion parameters and national surveillance program budget trajectories.
Decision-makers should treat outputs as directional under sustained dengue and chikungunya endemic burden assumptions; material deviation in outbreak frequency or vector control funding would warrant model refresh. Practitioners should keep alternative scenarios live as WHO emergency pathway refinements and CE-IVDR transition timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Breath Biopsy Testing Market
Testing Services
Global Laboratory Proficiency Testing Market
Testing Services
Global Creatinine Assay Kits Market
Testing Services
Malaria Ag Rapid Testing Market
Testing Services
Active B12 Test Market
Testing Services
Lab Screening Test Kit Market
Testing Services
Drug Testing Equipment Market
Testing Services
Platelet Function Testing Market
Testing Services
Global Medical Device Testing and Certification Market
Testing Services
Creatinine Testing Market
Testing Services
Pharmaceutical Dosage Form Testing Systems Market
Testing Services
Special Coagulation Tests Market
Testing Services
Global Electronystagmography Testing Market
Testing Services
Global Legionella Testing Market
Testing Services
Genetic Toxicology Testing Market
Testing Services
Asia-Pacific Newborn Screening Market