
 Asia-Pacific Newborn Screening Market | 2026-2036
Asia-Pacific Newborn Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Newborn Screening Market Insights
China's expanded heel-prick screening infrastructure is fragmenting competitive dynamics across the region. PerkinElmer Inc. leverages its tandem mass spectrometry installed base to sustain service contracts in provincial maternal hospitals. Bio-Rad Laboratories anchors its position through neonatal quality-control reagent supply chains. Agilent Technologies competes by specializing in high-throughput genetic screening platforms for centralized reference laboratories.
Newborn screening comprises biochemical and genetic testing protocols applied within 48-72 hours of birth to detect congenital disorders amenable to early intervention. Tandem mass spectrometry analyzes dried blood spot metabolite profiles at detection thresholds below 1 μmol/L, enabling simultaneous multiplex assay of 30-50 metabolic conditions. Blood Tests occupy the largest revenue share due to mandated phenylketonuria and congenital hypothyroidism panels across national immunization programs. DNA Sequencing represents the fastest-expanding technology segment as whole-genome screening pilots launch in Singapore and South Korea. Laboratory-Based delivery mode dominates transaction volume, though Point-of-Care instruments are penetrating India's district-level community health centers.
India's CDSCO regulates in vitro diagnostic kit registration for expanded newborn panels, while China's NMPA enforces GB standard compliance for domestic screening device manufacturing. Japan's PMDA maintains stringent analytical validation requirements that limit import pathways for non-JIS-certified platforms. Stakeholders must monitor regulatory divergence between national mandatory screening lists and reimbursement eligibility to align product portfolio investments with addressable program budgets.
Market Dynamics
China's NMPA is accelerating GB standard harmonization for screening device manufacturing, compressing certification timelines and forcing provincial maternal hospitals to consolidate supplier relationships around validated platform ecosystems.
Growth Catalysts
- India's National Policy for Rare Diseases:State-level newborn screening mandates are unlocking procurement budgets across public hospital maternity wards in Maharashtra, Tamil Nadu, and Karnataka.
- Tandem mass spectrometry multiplexing:Provincial reference laboratories in China are expanding heel-prick panels from 2-4 conditions toward 30-50 metabolic assays per dried blood spot.
- Singapore whole-genome screening pilots:Government-funded precision medicine programs are validating DNA sequencing workflows for population-scale congenital disorder detection.
Market Restraints
- Reagent import dependency:Quality-control metabolite standards for tandem mass spectrometry concentrate in North American and European specialty chemical suppliers, exposing provincial laboratories to currency volatility and customs delays.
- Japan's PMDA analytical validation requirements:Non-JIS-certified screening platforms face extended registration pathways that limit competitive entry and sustain premium pricing for incumbent device manufacturers.
- Specialized technician scarcity:Interpretation of complex metabolite profiles and genetic variant calls requires clinical biochemical genetics expertise that remains concentrated in tier-one city academic medical centers.
Strategic Opportunities
- Indonesia's archipelago district health centers:Point-of-care screening instruments are penetrating community health posts that lack cold-chain logistics for dried blood spot transport to centralized laboratories.
- South Korea's National Health Insurance Service:Expanded reimbursement eligibility for expanded metabolic panels is creating pull-through demand for high-throughput genetic screening platforms in Seoul metropolitan hospital networks.
- Convergence of dried blood spot automation with AI-assisted variant interpretation:Machine learning algorithms are reducing genetic counseling bottlenecks in centralized reference laboratories across Australia and New Zealand.
Industry Challenges
- Integration complexity with legacy laboratory information systems:Provincial maternal hospitals in Vietnam and the Philippines operate fragmented health IT infrastructure that complicates screening result routing to pediatric specialists.
- CDSCO in vitro diagnostic kit registration timelines:India's domestic manufacturing incentives are creating backlog in expanded panel approvals, delaying market entry for novel biochemical assays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Newborn Screening Market |
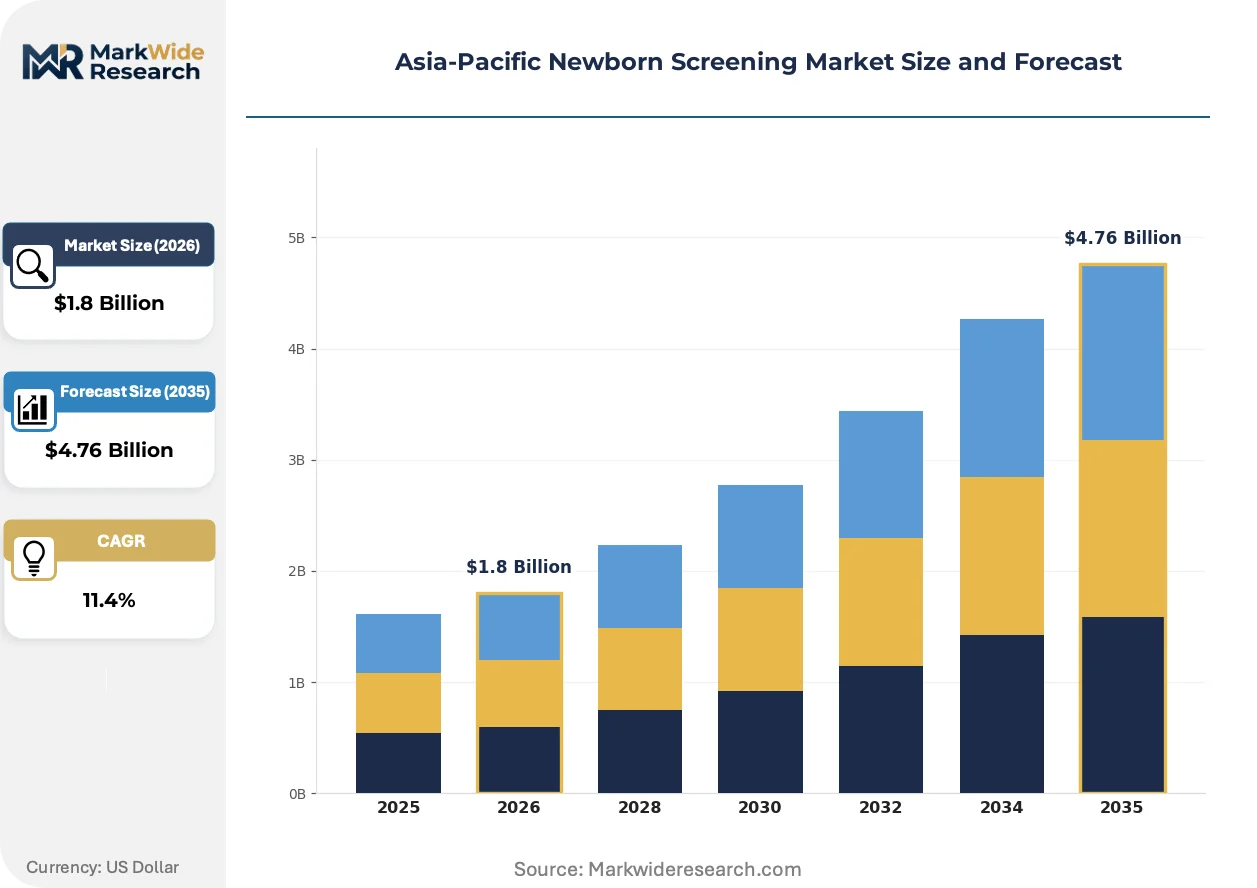
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Tests, Genetic Tests, Hearing Screening, Metabolic Screening Technology: Mass Spectrometry, DNA Sequencing, Immunoassay, PCR Delivery Mode: Point-of-Care, Laboratory-Based, Home Testing, Mobile Testing End User: Hospitals, Clinics, Laboratories, Community Health Centers |
| Companies Covered | Medtronic plc, PerkinElmer Inc., Agilent Technologies, Waters Technologies Corporation, Bio-Rad Laboratories, AB SCIEX, Masimo Corporation, GE Healthcare Technologies, Natus Medical, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Newborn Screening Market Trends and Innovations
Next-generation sequencing workflows and point-of-care miniaturization are fragmenting the traditional laboratory-centered screening model across the Asia-Pacific region. These shifts are compressing turnaround times and redistributing testing capacity toward peripheral health systems.
Tandem mass spectrometry platforms are migrating from centralized provincial reference laboratories toward district-level maternal hospitals with moderate throughput requirements. Equipment manufacturers are downsizing instrument footprints and simplifying software interfaces for technicians without specialized metabolomics training. This migration from high-complexity centers is enabling same-result-day clinical decision-making in tier-two and tier-three Chinese cities.
Japan's PMDA has tightened post-market surveillance requirements for neonatal screening devices under revised pharmaceutical and medical device regulations. Manufacturers must now submit real-world performance data from domestic installations as a condition of registration renewal. This policy shift is favoring established suppliers with existing installed bases and captive service networks across Tokyo, Osaka, and Nagoya metropolitan hospital systems.
Public hospital procurement committees are unbundling screening instrument purchases from long-term reagent supply contracts. Tier-one city networks in China and South Korea are negotiating competitive reagent sourcing from third-party manufacturers, compressing margins for integrated platform vendors. This purchasing pattern shift is most visible in Shanghai and Beijing, where municipal health bureaus have centralized tender processes for expanded metabolic panel consumables.
Asia-Pacific Newborn Screening Market Segmentation
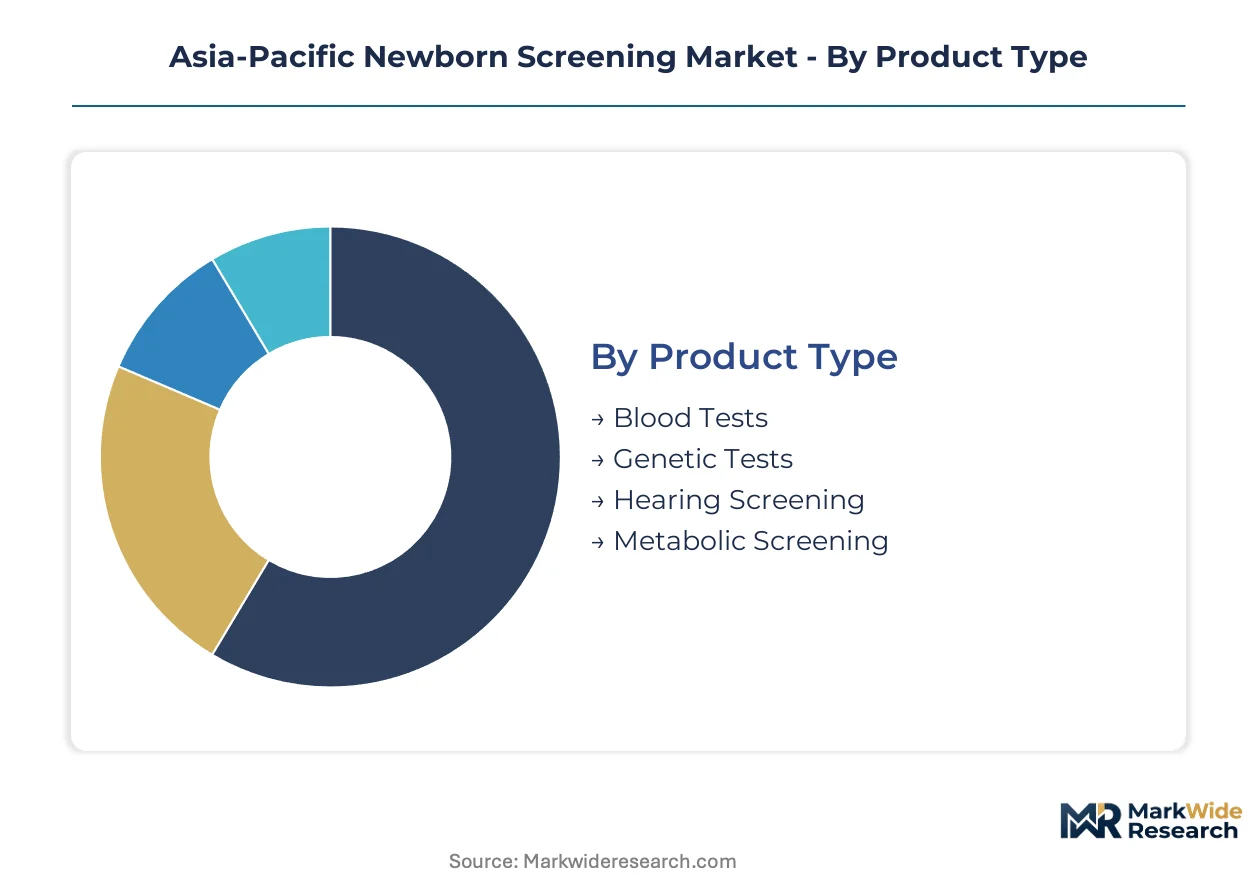
Newborn screening market segmentation reflects divergent technology maturities and infrastructure requirements across Asia-Pacific healthcare systems. Product portfolios must align with provincial laboratory capabilities, reimbursement pathways, and national mandatory screening lists.
Product Type:
Mature biochemical assays anchor volume while genetic modalities accelerate fastest in precision medicine corridors.
- Blood Tests:Dried blood spot collection cards enable multiplex metabolic profiling through heel-prick sampling within 48-72 hours of birth. China's provincial maternal hospitals in Jiangsu and Guangdong are expanding phenylketonuria and congenital hypothyroidism panels toward 30-50 condition assays per spot.
- Genetic Tests:Next-generation sequencing workflows detect chromosomal abnormalities and single-gene disorders with variant resolution below 5% allelic frequency. Singapore's National University Hospital and Seoul National University Hospital are piloting whole-genome screening for population-scale congenital disorder detection.
- Hearing Screening:Otoacoustic emission and auditory brainstem response protocols identify congenital sensorineural deficits requiring early cochlear intervention.
- Metabolic Screening:Tandem mass spectrometry panels quantify amino acid and acylcarnitine profiles for fatty acid oxidation disorders and organic acidemias.
Blood Tests retain volume leadership; Genetic Tests hold the steepest expansion curve.
Technology:
Platform selection hinges on throughput requirements, technician specialization depth, and reagent supply security.
- Mass Spectrometry:Triple-quadrupole and time-of-flight configurations achieve detection thresholds below 1 μmol/L for metabolite quantification. Provincial reference laboratories in China's tier-one cities are consolidating around validated tandem MS ecosystems to compress turnaround times.
- DNA Sequencing:Targeted gene panels and whole-genome approaches reduce variant interpretation bottlenecks through machine learning-assisted pipelines. South Korea's National Health Insurance Service reimbursement expansion is pulling through high-throughput platform demand in Seoul metropolitan networks.
- Immunoassay:Enzyme-linked and chemiluminescent formats deliver thyroid-stimulating hormone and 17-hydroxyprogesterone quantification for congenital hypothyroidism and congenital adrenal hyperplasia detection.
- PCR:Real-time amplification protocols enable rapid cystic fibrosis and spinal muscular atrophy carrier screening with same-day result turnaround.
Mass Spectrometry dominates installed base; DNA Sequencing is climbing the fastest.
Delivery Mode:
Infrastructure fragmentation across archipelago geographies and cold-chain limitations are redistributing testing capacity toward peripheral access points.
- Laboratory-Based:Centralized reference laboratories with automated dried blood spot processing and liquid chromatography-tandem mass spectrometry suites handle high-volume metabolic panel throughput. China's municipal health bureaus in Shanghai and Beijing have centralized tender processes for expanded panel consumables.
- Point-of-Care:Miniaturized immunoassay and PCR instruments with simplified software interfaces are penetrating Indonesia's district health posts lacking specimen transport logistics. Equipment manufacturers are downsizing footprints for technicians without specialized metabolomics training.
- Home Testing:Self-collection kits with telemedicine-integrated result reporting are emerging in Australia's private healthcare channels.
- Mobile Testing:Van-mounted screening units extend coverage to remote maternal facilities in India's Maharashtra and Karnataka state programs.
Laboratory-Based retains transaction dominance; Point-of-Care is gaining share fastest in district-level penetration.
End User:
Procurement authority concentration varies between public hospital networks, independent laboratory chains, and community health systems.
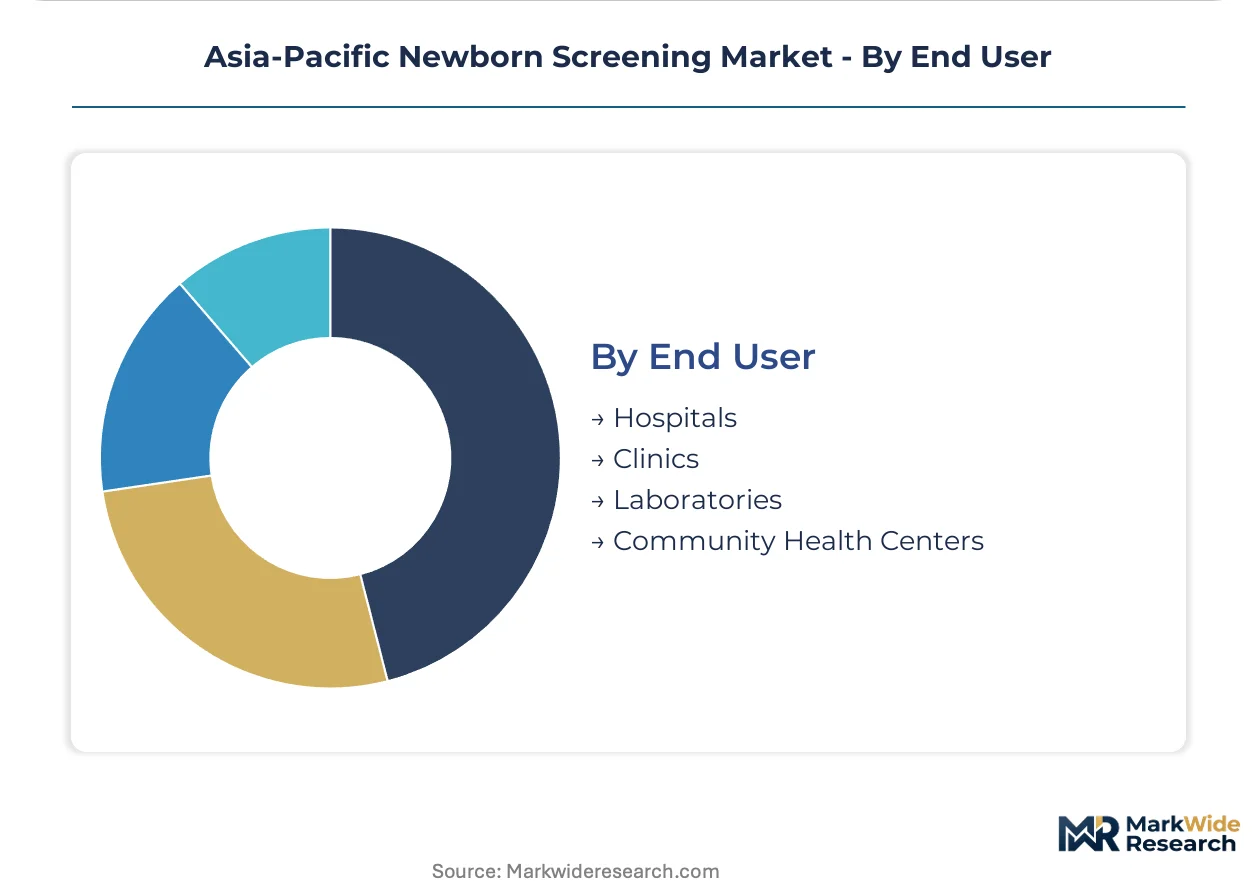
- Hospitals:Maternity wards in China's tier-one city networks and India's state-level public facilities drive instrument procurement through centralized government tenders. Japan's PMDA post-market surveillance requirements favor established suppliers with captive service networks across Tokyo, Osaka, and Nagoya metropolitan systems.
- Laboratories:Independent diagnostic chains and hospital-affiliated reference centers negotiate competitive reagent sourcing from third-party manufacturers, compressing margins for integrated platform vendors.
- Clinics:Private obstetric practices in South Korea and Australia are adopting boutique genetic screening panels for affluent patient segments.
- Community Health Centers:India's district-level facilities under the National Health Mission are receiving point-of-care instrument deployments to meet state-level newborn screening mandates.
Hospitals command procurement volume; Community Health Centers show the steepest capacity expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform vendors concentrate manufacturing and service networks across coastal China and metropolitan Japan, while reagent supply chains thread through Singapore and South Korea. Provincial maternal hospitals in Jiangsu and Guangdong anchor tandem mass spectrometry demand. Tier-one city networks in Beijing and Shanghai fragment procurement through centralized municipal tenders.
China
NMPA's GB standard harmonization compresses certification timelines for domestic screening device manufacturing. Provincial maternal hospitals in Jiangsu and Guangdong consolidate supplier relationships around validated tandem mass spectrometry ecosystems. Tier-two cities in Sichuan and Shaanxi are migrating same-day heel-prick screening from centralized reference laboratories toward district-level facilities.
India
The 2021 National Policy for Rare Diseases mandates state-level newborn screening expansion across Maharashtra, Tamil Nadu, and Karnataka. CDSCO regulates in vitro diagnostic kit registration for expanded panels, creating approval backlogs for novel biochemical assays. District health centers under the National Health Mission receive point-of-care instrument deployments to meet procurement targets.
Japan
PMDA maintains stringent analytical validation requirements that limit import pathways for non-JIS-certified screening platforms. Post-market surveillance rules now require real-world performance data from domestic installations for registration renewal. Tokyo, Osaka, and Nagoya metropolitan hospital systems sustain premium pricing for incumbent device manufacturers with captive service networks.
South Korea
The National Health Insurance Service has expanded reimbursement eligibility for expanded metabolic panels. Seoul metropolitan hospital networks are pulling through demand for high-throughput genetic screening platforms. Precision medicine programs at Seoul National University Hospital pilot whole-genome screening workflows for population-scale congenital disorder detection.
Singapore
Government-funded precision medicine initiatives validate DNA sequencing workflows for population-scale screening. The National University Hospital anchors next-generation sequencing pilot programs with machine learning-assisted variant interpretation. Biomedical manufacturing clusters supply quality-control metabolite standards to regional reference laboratories.
Asia-Pacific Newborn Screening Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in reagent and quality-control supply chains. The vendor base stratifies between multinational conglomerates with full-stack screening portfolios and regional distributors with service-dependent installed bases. Three archetypes dominate: tandem mass spectrometry platform vendors, neonatal quality-control reagent suppliers, and point-of-care miniaturization specialists. Competitive moves concentrate on reagent contract unbundling and AI-assisted variant interpretation partnerships.
Within the platform integrator tier, PerkinElmer Inc. and Agilent Technologies occupy positions defined by installed base leverage and high-throughput specialization. Bio-Rad Laboratories anchors the quality-control reagent segment through neonatal metabolite standard supply chains. These three entities exemplify how service contract retention and consumable recurring revenue sustain margin structures against municipal procurement pressure.
| Leading Market Players |
|---|
| Medtronic plc |
| PerkinElmer Inc. |
| Agilent Technologies |
| Waters Technologies Corporation |
| Bio-Rad Laboratories |
| AB SCIEX |
| Masimo Corporation |
| GE Healthcare Technologies |
| Natus Medical |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Singapore maritime corridor's refrigerated container rates directly compress margins for metabolite standard imports, concentrating pricing power among North American and European specialty chemical suppliers while forcing provincial laboratories in Jiangsu and Guangdong to absorb currency volatility through tiered instrument service contracts.
Pricing Analysis
China's NMPA GB standard harmonization dictates the pricing tier structure across provincial maternal hospital networks. Three-tier pricing separates JIS-certified platforms in Japan's metropolitan systems from validated tandem MS ecosystems in China's tier-one cities, with economy-tier point-of-care instruments penetrating India's district health centers. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in reagent supply contracts is intensifying because municipal health bureaus are unbundling long-term consumable agreements. Community health centers in Indonesia's archipelago districts exhibit highest price sensitivity; Seoul metropolitan networks show lowest.
Supply Chain Analysis
Export control regimes restricting high-resolution mass spectrometry and next-generation sequencing platforms limit flows into China's provincial reference laboratories. Manufacturing concentrates in the United States, Germany, and Japan for precision instrumentation, while quality-control metabolite standards draw from Singapore's biomedical clusters and Swiss specialty chemical producers. Raw material dependencies include rare earth magnets for ion optics, high-purity solvents for chromatography, and synthetic stable-isotope standards for calibration. Single-source vulnerability pervades the tandem MS reagent tier. Distribution runs through hospital procurement committees and GPO contracts in tier-one city networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent platform vendors face substitution pressure from AI-assisted variant interpretation pipelines that reduce genetic counseling bottlenecks and compress margins on high-complexity testing workflows.
For Market Incumbents: Pre-empt margin erosion by locking in captive service networks across Tokyo, Osaka, and Nagoya metropolitan hospital systems before PMDA registration renewal requirements tighten further. Anchor reagent supply security through backward integration into metabolite standard production or exclusive partnerships with Singapore's biomedical manufacturing clusters. Counter point-of-care miniaturization threats by downsizing instrument footprints for district-level deployment in China's Sichuan and Shaanxi provinces. For New Entrants and Emerging Players: Build out white-space positions in Indonesia's archipelago district health posts lacking cold-chain logistics for dried blood spot transport, where point-of-care immunoassay and PCR instruments face minimal installed-base competition. Penetrate India's community health centers under National Health Mission procurement targets by offering simplified software interfaces for technicians without metabolomics training. Lead with telemedicine-integrated result reporting to bypass fragmented laboratory information system infrastructure in Vietnam and the Philippines. For Investors and Strategic Acquirers: Quality-control reagent specialists with ISO-certified metabolite standard portfolios represent the most defensible acquisition archetype against municipal procurement unbundling. Long-term viability hinges on recurring revenue streams from neonatal screening program expansion across Asia-Pacific precision medicine corridors. Watch for inflection when South Korea's National Health Insurance Service expands reimbursement eligibility toward whole-genome screening workflows.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Variant Interpretation Partnership | Machine learning pipelines at Singapore's National University Hospital reduce genetic counseling bottlenecks in centralized reference laboratories. |
| Point-of-Care Miniaturization Launch | Downsized immunoassay instruments penetrate Indonesia's district health posts lacking specimen transport logistics. |
| Reagent Supply Contract Unbundling | Municipal health bureaus in Shanghai and Beijing negotiate competitive third-party metabolite standard sourcing. |
| JIS Certification Investment | PMDA post-market surveillance requirements favor established suppliers with domestic installed bases across Japan's metropolitan systems. |
| Backward Integration into Metabolite Standards | Captive production of stable-isotope calibration materials insulates provincial laboratories from currency volatility and customs delays. |
Research Methodology
The analysis maps tandem mass spectrometry platforms, DNA sequencing workflows, point-of-care miniaturization instruments, and quality-control reagent supply chains, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and provincial maternal hospital laboratory directors. Primary interview intelligence triangulates against NMPA GB standard filings, CDSCO in vitro diagnostic registration databases, PMDA post-market surveillance reports, and hospital procurement tender records. Bottom-up instrument deployment counts and top-down healthcare expenditure allocations were cross-referenced for consistency.
Assumptions held fixed include current reimbursement eligibility thresholds across Asia-Pacific national health insurance schemes and existing regulatory certification requirements for screening device manufacturing. The analytical framework models technology segments, delivery modes, and end-user procurement authority concentrations across the projection horizon. CAGRs were derived from logistic diffusion curves fitted to provincial screening program expansion timelines and precision medicine initiative funding trajectories. Forecast inputs incorporated dried blood spot automation adoption rates and AI-assisted interpretation pipeline validation status.
Stress conditions across CDSCO approval backlog durations, NMPA certification timeline compression, and reagent import tariff volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about sustained public hospital procurement budget allocations and stable regulatory harmonization momentum. Material shifts in rare disease policy mandates or export control regime expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Bioburden Testing Market
Testing Services
INR Test Meter Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
Adiponectin Testing Market
Testing Services
Europe IVD Regulatory Affairs Outsourcing Market
Testing Services
Asia-Pacific Hereditary Cancer Testing Market
Testing Services
Pharmaceutical Dosage Form Testing Systems Market
Testing Services
In-Vitro Toxicology Testing Market
Testing Services
Toxicology Drug Screening Market
Testing Services
US Pharmaceutical Sterility Testing Market
Testing Services
Europe Endotoxin and Pyrogen Testing Market
Testing Services
Global Virology Testing Market
Testing Services
US C-Reactive Protein Testing Market
Testing Services
Malaria Ag Rapid Testing Market
Testing Services
Autoimmune Disease Testing Market
Testing Services
Anti-Asthma TDM Assay Kits Market