
 Sterilization Market | 2026-2036
Sterilization Market Size, Share, and Industry Trends Forecast 2026-2036
Sterilization Market Outlook
Qualified sterilization technicians is collapsing across North American hospital systems, forcing facilities toward third-party sterilization service providers. STERIS leverages its integrated device and service platform to capture outsourced hospital volumes. Getinge anchors European sterilization infrastructure through its infection control equipment portfolio. Sotera Health sustains North American gamma and ethylene oxide capacity through Sterigenics and Nordion facilities.
Sterilization encompasses thermal, chemical, radiation, and filtration modalities that eliminate all viable microorganisms from surfaces, fluids, and compounds, typically achieving a sterility assurance level of 10^-6 for medical applications. Steam sterilizers dominate hospital central sterile supply departments due to reliability and low operating cost, while ethylene oxide sterilizers retain critical importance for heat-sensitive polymer devices and electronics. Gamma radiation leads pharmaceutical and medical device terminal sterilization for high-volume disposable products. Plasma sterilization competes for specialized endoscope and delicate instrument applications where moisture and temperature constraints apply.
FDA ethylene oxide emission regulations and EPA air toxics standards are accelerating capital shifts toward hydrogen peroxide gas plasma and electron beam alternatives in United States manufacturing. EMA medical device regulation and REACH chemical restrictions shape European sterilization modality selection and validation protocols. Stakeholders must monitor evolving residual chemistry limits and energy costs to determine modality mix and facility location decisions.
Market Dynamics
FDA ethylene oxide residual limits are compressing sterilization modality choices across United States medical device manufacturing, forcing capital reallocation toward hydrogen peroxide gas plasma and electron beam systems while sterilization technician shortages accelerate hospital outsourcing.
Growth Catalysts
- Hospital central sterile supply outsourcing:North American health systems facing qualified technician shortages are expanding third-party sterilization service contracts for surgical instrument reprocessing.
- REACH chemical restrictions:European chemical safety frameworks are validating alternative sterilization chemistries and driving equipment replacement cycles across pharmaceutical packaging operations.
- Gamma radiation capacity:Terminal sterilization demand for high-volume disposable medical devices is pulling investment into cobalt-60 and electron beam irradiation infrastructure.
Market Restraints
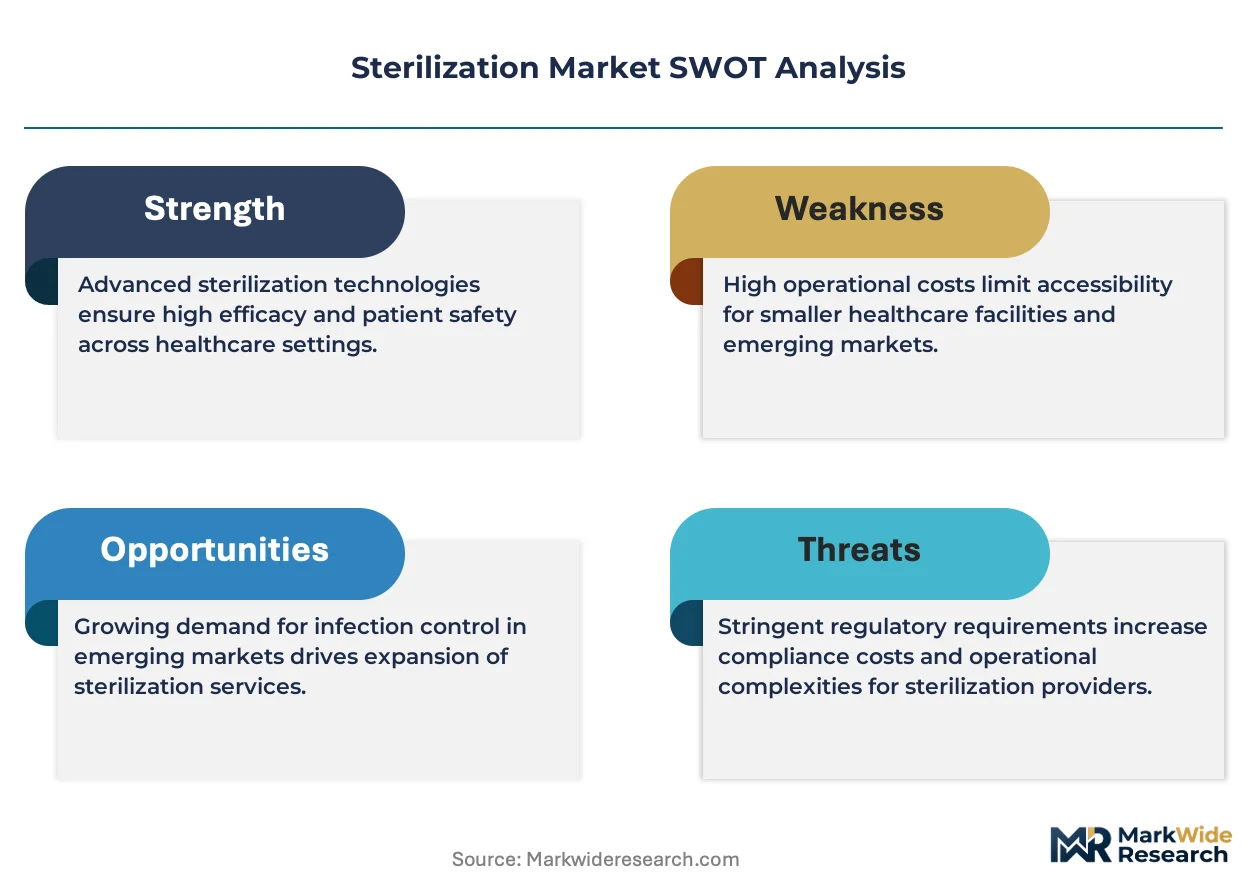
- Ethylene oxide regulatory friction:EPA air toxics standards and FDA residual chemistry limits are constraining capacity expansion for heat-sensitive polymer sterilization in United States manufacturing corridors.
- Capital intensity of modality conversion:Hydrogen peroxide gas plasma and electron beam systems require substantial facility reconfiguration and validation timelines that extend payback periods.
- Supply concentration in cobalt-60:Gamma radiation source production concentrates among limited radiochemical suppliers, creating isotope availability risk for terminal sterilization operations.
Strategic Opportunities
- Plasma sterilization for endoscopy:Moisture-sensitive and temperature-constrained instrument categories present white space for hydrogen peroxide gas plasma system deployment in ambulatory surgical centers.
- India medical device manufacturing:CDSCO regulatory alignment with international standards is attracting contract sterilization investment for export-oriented disposable production.
- Electron beam pharmaceutical integration:Convergence of radiation processing with aseptic filling lines offers inline terminal sterilization for temperature-sensitive biologic containers.
Industry Challenges
- Sterilization technician certification pipelines:North American hospital systems face collapsing enrollment in sterile processing technician programs, constraining in-house capacity expansion.
- Cross-modality validation complexity:Medical device manufacturers switching from ethylene oxide to hydrogen peroxide or radiation face extended FDA 510(k) amendment timelines and biocompatibility requalification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterilization Market |
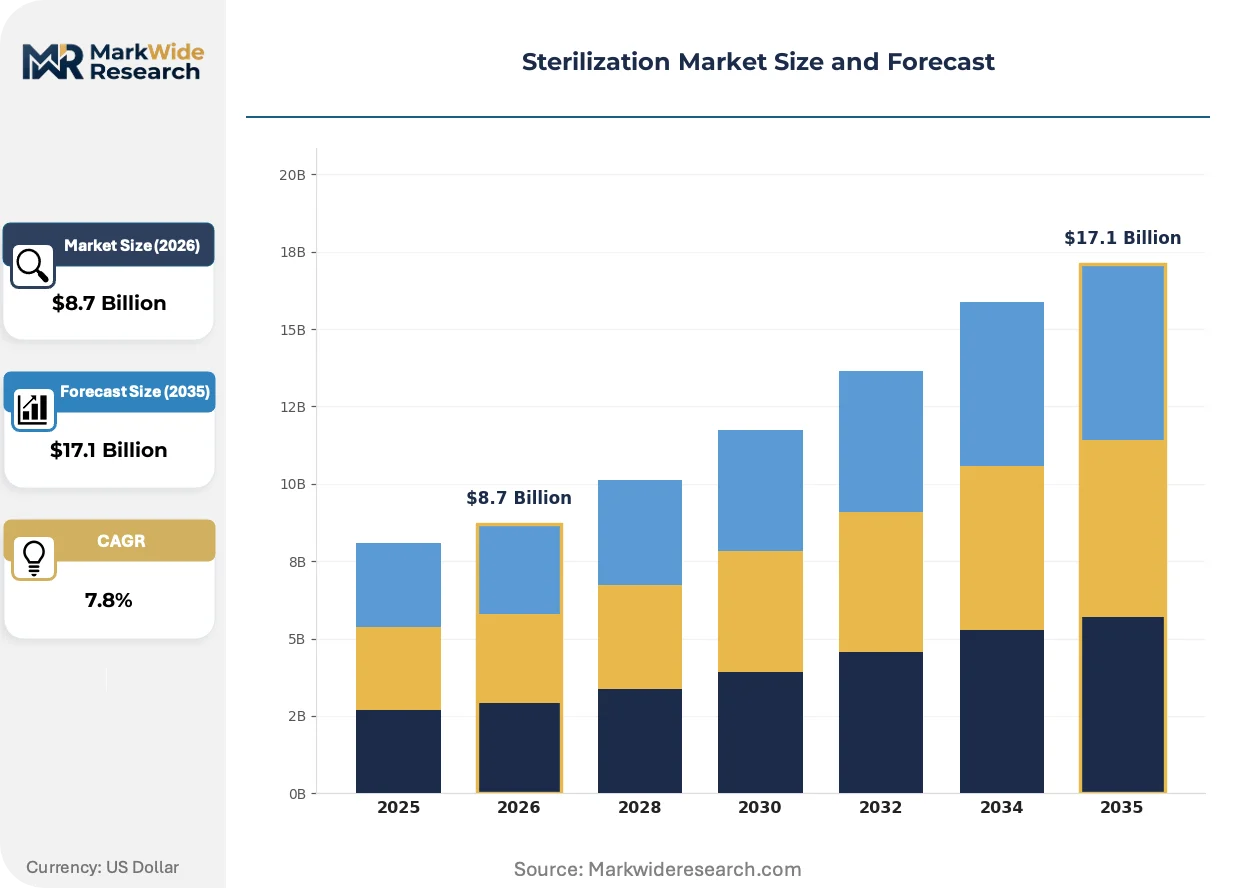
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Sterilization, Chemical Sterilization, Radiation Sterilization, Filtration Sterilization Application: Medical Devices, Pharmaceuticals, Laboratory Equipment, Food Preservation Technology: Steam Sterilizers, Ethylene Oxide Sterilizers, Gamma Radiation, Plasma Sterilization End User: Hospitals, Clinics, Pharmaceutical Companies, Research Laboratories |
| Companies Covered | STERIS, Sotera Health, Getinge, 3M, Sterigenics, E-BEAM Services, Belimed, Medistri, Steelco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterilization Market Strategic Shifts
Terminal sterilization modalities are fragmenting across medical device and pharmaceutical manufacturing as regulatory chemistry limits and energy costs reshape equipment investment patterns.
Nitrogen dioxide sterilization is decomposing the ethylene oxide monopoly for heat-sensitive electronics and polymer devices. Medical device manufacturers in Minnesota and Massachusetts are piloting NO2 systems for printed circuit board assemblies and drug-device combination products. This chemistry is decomposing the traditional trade-off between thermal tolerance and sterilization efficacy, compressing validation timelines for new product introductions.
EPA commercial sterilizer residual risk regulations are accelerating facility relocation and technology substitution across United States contract sterilization networks. The agency's 2024 updated emission standards are forcing ethylene oxide-dependent operators toward hydrogen peroxide gas plasma or electron beam alternatives. California and Illinois manufacturing corridors are experiencing the most acute capacity constraints as sterilizers consolidate or convert.
Ambulatory surgical centers are unbundling instrument reprocessing from capital equipment ownership, preferring per-procedure service fees over central sterile supply department investment. Third-party sterilization service providers are capturing volume through mobile sterilization units and regional hub-and-spoke logistics. Texas and Florida outpatient surgery markets display the most pronounced shift toward outsourced sterile processing.
Sterilization Market Segmentation
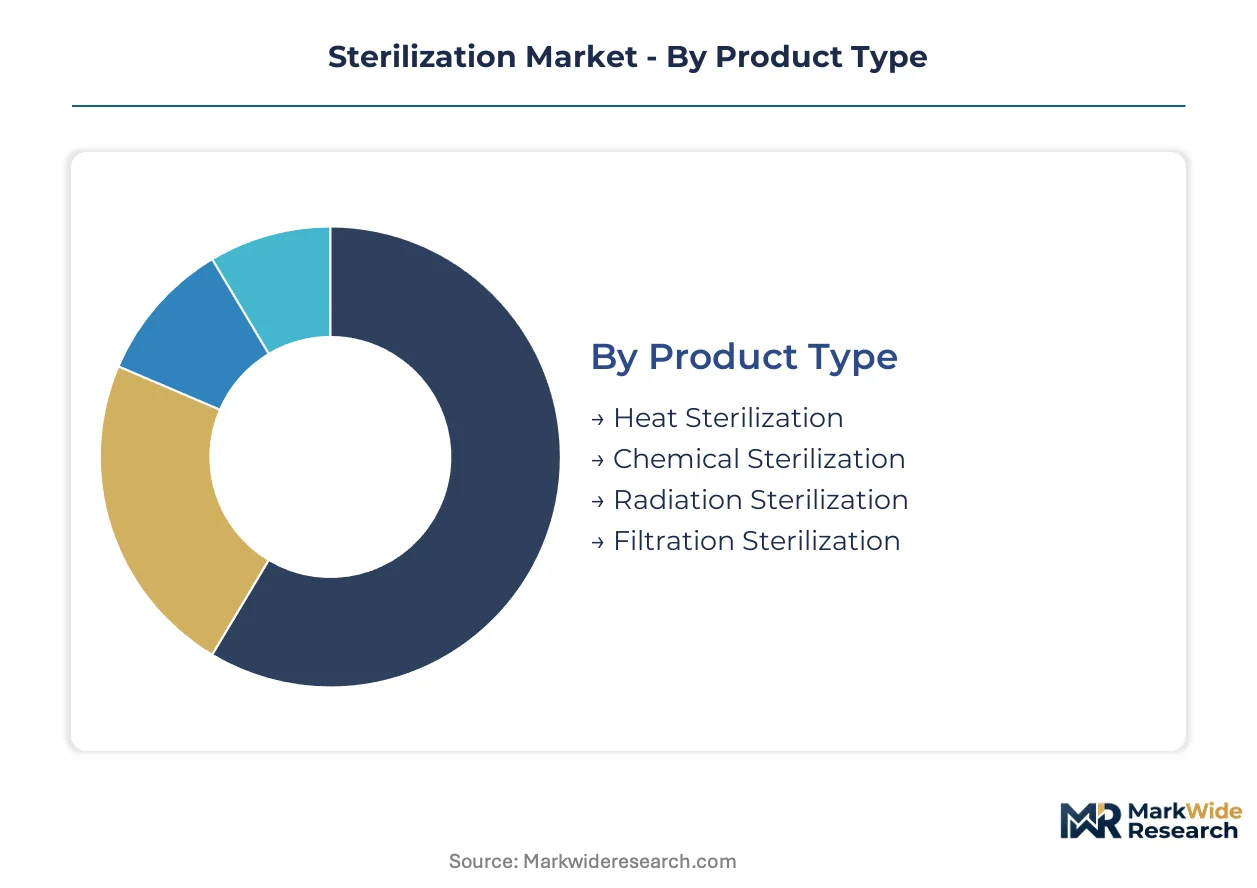
Sterilization modality selection varies sharply across domestic hospital networks versus export-oriented manufacturing corridors. Geographic demand concentration determines equipment specifications, validation protocols, and service contract structures within each segment.
Product Type:
Heat sterilization dominates domestic hospital infrastructure across the United States surgical corridor. Chemical and radiation modalities concentrate in export-led medical device manufacturing zones.
- Heat Sterilization:Saturated steam under pressure achieves microbial elimination through protein denaturation and enzyme coagulation. United States hospital central sterile supply departments favor autoclave systems for surgical instrument reprocessing due to operational simplicity and low consumable costs. FDA validation requirements for steam sterilization cycles are well-established, compressing equipment procurement timelines.
- Chemical Sterilization:Low-temperature gas and vapor chemistries penetrate complex device geometries without thermal degradation. Ethylene oxide retains dominance for heat-sensitive polymer devices in Minnesota and Massachusetts manufacturing clusters, though EPA emission regulations are forcing capacity consolidation. Hydrogen peroxide gas plasma is displacing EtO in new California and Illinois facility investments.
- Radiation Sterilization:Gamma photons and electron beams disrupt microbial DNA through ionization. Terminal sterilization for high-volume disposable devices concentrates in cobalt-60 and e-beam facilities serving export markets.
- Filtration Sterilization:Membrane barriers exclude microorganisms from heat-sensitive liquids and gases. Biologic drug manufacturing in Puerto Rico and North Carolina relies on 0.22-micron filtration for aseptic processing.
Heat sterilization commands the established base. The steepest expansion runs through radiation sterilization.
Application:
Application demand splits between regulated domestic healthcare delivery and export-oriented manufacturing compliance.
- Medical Devices:Implantable and surgical instruments require terminal sterilization achieving 10^-6 sterility assurance levels. United States orthopedic and cardiovascular device manufacturers in Warsaw, Indiana and Irvine, California drive gamma and EtO capacity utilization.
- Pharmaceuticals:Parenteral drug packaging and biologic containers demand aseptic processing or terminal sterilization. New Jersey and Massachusetts biopharma clusters favor filtration and radiation modalities for temperature-sensitive formulations.
- Laboratory Equipment:Cell culture media, reagents, and consumables require sterilization to prevent contamination. Research institutions across the National Institutes of Health corridor standardize on steam and filtration protocols.
- Food Preservation:Irradiation extends shelf life and eliminates pathogens in spices, poultry, and produce. USDA-approved facilities in Florida and California handle low-volume specialty applications.
Medical devices absorb the largest equipment investment. Pharmaceuticals are climbing the fastest as biologic container sterilization requirements intensify.
Technology:
Technology selection tracks energy costs, chemistry regulatory limits, and device material compatibility constraints.
- Steam Sterilizers:Gravity displacement and pre-vacuum autoclaves process wrapped and unwrapped instrument loads. United States Veterans Health Administration and Department of Defense medical centers standardize on steam systems for reliability in deployed settings.
- Ethylene Oxide Sterilizers:Alkylation chemistry penetrates porous materials and long lumens at low temperatures. FDA residual limits and EPA commercial sterilizer standards are compressing United States EtO capacity, forcing modality substitution for polymer device manufacturers.
- Gamma Radiation:Cobalt-60 decay emits penetrating photons suitable for pallet-scale terminal sterilization. High-volume disposable device manufacturers in Michigan and Ohio depend on gamma infrastructure for export production.
- Plasma Sterilization:Hydrogen peroxide vapor ionization generates reactive species for low-temperature surface sterilization. Ambulatory surgical centers in Texas and Florida are adopting plasma systems for endoscope reprocessing where moisture constraints apply.
Steam sterilizers anchor installed hospital base. Plasma sterilization is gaining share fastest in outpatient surgery expansion zones.
End User:
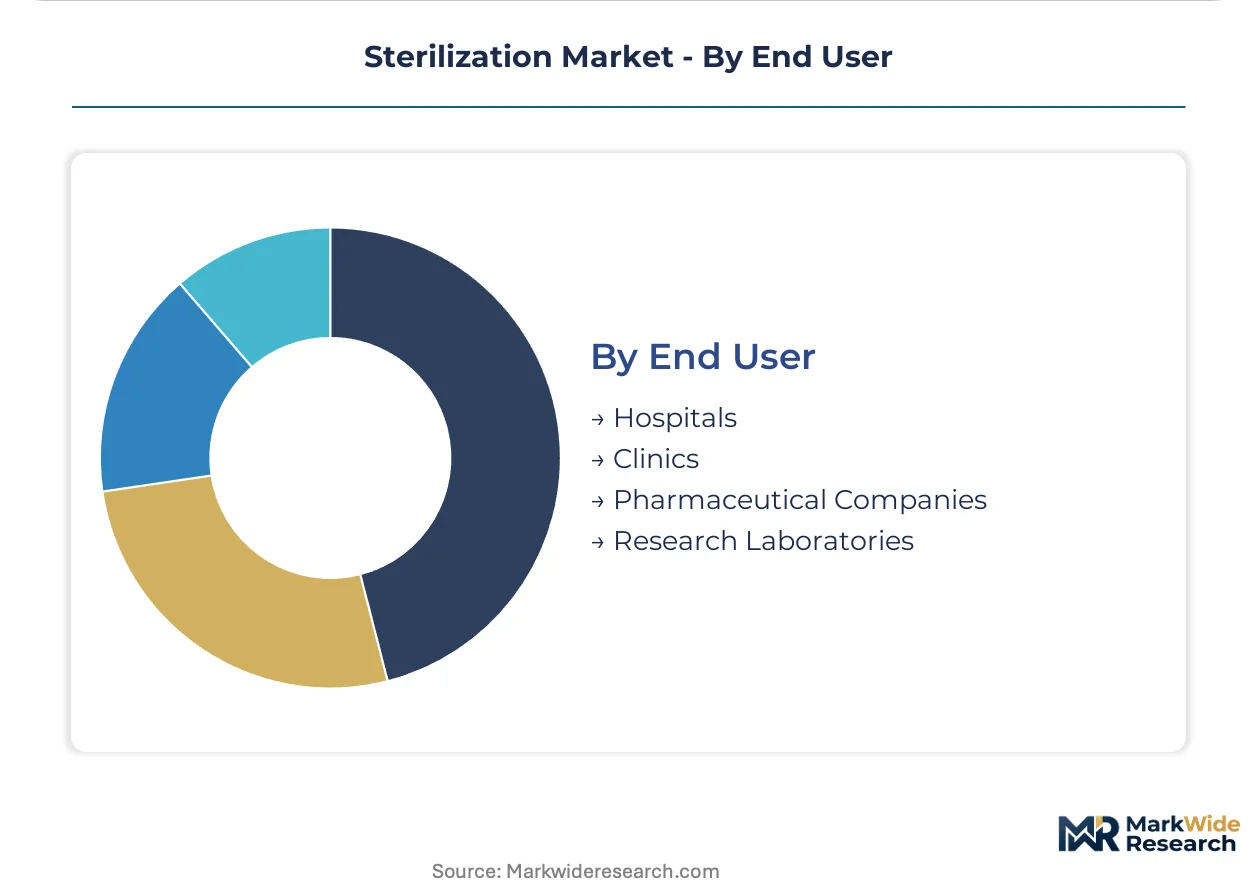
End-user procurement patterns diverge between capital ownership and outsourced service fee structures.
- Hospitals:Central sterile supply departments process surgical instruments for operating room reuse. United States health systems facing technician certification shortages are expanding third-party sterilization service contracts.
- Clinics:Limited instrument volume favors tabletop autoclaves or regional hub-and-spoke sterilization logistics. Federally qualified health centers in rural corridors depend on mobile sterilization units.
- Pharmaceutical Companies:In-house terminal sterilization or contract irradiation services support aseptic filling operations. Biopharma manufacturers in Puerto Rico maintain captive gamma capacity for export compliance.
- Research Laboratories:Academic and government facilities sterilize media, equipment, and biological samples. NIH intramural research programs operate centralized steam sterilization facilities in Bethesda, Maryland.
Hospitals retain the largest equipment footprint. Pharmaceutical companies are expanding capacity most aggressively for biologic manufacturing scale-up.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA ethylene oxide regulations anchor United States sterilization capacity decisions, while EMA medical device frameworks and CDSCO alignment programs reshape modality investment across manufacturing corridors worldwide.
United States
Hospital central sterile supply departments in Illinois and California face acute technician shortages, forcing third-party sterilization contracts. EPA commercial sterilizer emission standards are compressing ethylene oxide capacity in manufacturing zones. Minneapolis-St. Paul and Warsaw, Indiana orthopedic clusters are piloting nitrogen dioxide alternatives for heat-sensitive polymer devices.
Germany
Baden-Württemberg medical device manufacturers prioritize hydrogen peroxide gas plasma for precision electronics sterilization. REACH chemical restrictions and EU MDR validation protocols are extending equipment replacement cycles across pharmaceutical packaging operations. Bavarian sterilization service providers are integrating electron beam capacity for high-volume disposable exports.
China
Yangtze River Delta contract sterilizers are expanding gamma radiation infrastructure for export-oriented disposable medical device production. NMPA medical device registration alignment with international standards is attracting multinational terminal sterilization investment. Suzhou and Hangzhou manufacturing parks are concentrating cobalt-60 and electron beam capacity for global supply chain integration.
India
Gujarat and Maharashtra medical device manufacturing zones are drawing contract sterilization investment under CDSCO regulatory harmonization programs. PLI scheme incentives for domestic device production are accelerating terminal sterilization facility deployment. Hyderabad and Bengaluru biopharma corridors are validating alternative chemistries for temperature-sensitive biologic container processing.
Japan
Kanto region pharmaceutical manufacturers maintain captive gamma sterilization capacity for domestic and export compliance. PMDA quality management system requirements are shaping validation protocols for novel modalities including vaporized hydrogen peroxide. Osaka medical device clusters are consolidating steam sterilization infrastructure for surgical instrument reprocessing networks.
Sterilization Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across sterilization modality categories. The market structures around integrated device-service platforms, specialized radiation contractors, and regional equipment fabricators. Three archetypes dominate: full-service sterilization operators managing multi-modality facilities, equipment specialists with captive service networks, and pure-play contract irradiation providers. Competitive moves concentrate on modality conversion partnerships and geographic hub expansion to capture hospital outsourcing volume.
Among integrated platform operators, STERIS and Sotera Health exemplify the full-service archetype spanning equipment manufacturing and third-party sterilization services. Getinge represents the European equipment-specialist model with anchored infection control infrastructure. These three occupy positions across hospital central sterile supply, contract manufacturing, and pharmaceutical terminal sterilization segments without overlapping technology claims.
| Leading Market Players |
|---|
| STERIS |
| Sotera Health |
| Getinge |
| 3M |
| Sterigenics |
| E-BEAM Services |
| Belimed |
| Medistri |
| Steelco |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) clearance tiers and ISO 13485 certification levels gate both supplier qualification and service pricing power simultaneously, compressing margins for uncertified operators while enabling premium capture by validated multi-modality providers.
Pricing Analysis
United States contract sterilization rates command substantial premiums over Indian and Chinese terminal sterilization corridors. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated gamma facilities from REACH-compliant European operators and emerging-market electron beam providers. Price differentiation centers on certification grade and geographic delivery cost, with California and Illinois health systems absorbing elevated per-cycle fees due to EtO capacity constraints. Cost compression in mid-tier chemical sterilization is intensifying because EPA emission compliance is extending facility validation timelines.
Supply Chain Analysis
Port congestion across the Shanghai-Ningbo corridor and container availability constraints on the trans-Pacific lane are elevating inbound logistics costs for cobalt-60 source replenishment. Supply concentrates in Canada, Russia, and South Africa for radioisotope production, with Germany and Belgium anchoring precision sterilization equipment fabrication. Raw material dependencies include cobalt-60, hydrogen peroxide pharmaceutical grade, and medical-grade stainless steel for autoclave construction. Single-source vulnerability in cobalt-60 radiochemical supply creates terminal sterilization capacity risk. Distribution runs through regional hub-and-spoke networks serving hospital central sterile supply departments and contract manufacturing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among consolidated United States health system networks, with ten largest GPOs controlling procurement for over sixty percent of hospital sterilization service contracts.
For Market Incumbents: Fortify modality diversification across hydrogen peroxide gas plasma and electron beam infrastructure to offset ethylene oxide regulatory compression in United States manufacturing corridors. Anchor capacity expansion in Texas and Florida ambulatory surgery markets where outsourced sterile processing demand is accelerating. Certification investment in nitrogen dioxide validation protocols offers defensive positioning against emerging chemistry substitution threats. For New Entrants and Emerging Players: Mobile sterilization unit deployment for rural federally qualified health centers represents an underserved service-layer gap where incumbents under-serve due to capital intensity thresholds. Texas outpatient surgery corridors and Florida ambulatory endoscopy centers present the most penetrable geographic targets. Per-procedure service fee structures bypass capital ownership barriers for clinic segment entry. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across gamma radiation infrastructure due to cobalt-60 source security requirements and shielding construction costs. Long-term viability favors contract sterilization operators with multi-modality flexibility over single-chemistry dependent assets. Acquisition targets should display validated alternative chemistry portfolios. FDA emission standard revision timelines serve as the critical inflection indicator for modality substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Modality Capacity Expansion | STERIS and Sotera Health are diversifying beyond ethylene oxide to capture EPA-driven substitution demand. |
| Nitrogen Dioxide Validation Investment | Minnesota and Massachusetts device clusters are piloting NO2 systems for polymer electronics sterilization. |
| Regional Hub-and-Spoke Logistics | Third-party providers are deploying mobile units to serve Texas and Florida ambulatory surgery growth. |
| Cobalt-60 Security Partnerships | Sterigenics is securing Canadian and Russian isotope supply agreements against concentration risk. |
| Technician Certification Pipeline | Getinge is partnering with Baden-Württemberg technical institutes to address European sterile processing labor shortages. |
Study Parameters
Desk research of FDA 510(k) submission databases, EPA commercial sterilizer emission filings, and hospital procurement contract disclosures preceded structured interviews with central sterile supply directors, contract sterilization operations managers, biomedical engineers, and GPO contracts managers. Secondary validation drew from cobalt-60 trade flow data, medical device registration filings, and health system capital expenditure disclosures. Bottom-up facility capacity modeling triangulated against top-down healthcare spending projections.
Variance decomposition across sterilization modality, end-user segment, and geographic regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, application category, technology platform, and end-user procurement structure. CAGRs were derived from installed base replacement cycles, regulatory-driven modality conversion timelines, and hospital outsourcing penetration curves. Forecast inputs incorporated EPA emission standard implementation pace and CDSCO regulatory harmonization progress in Indian manufacturing corridors.
Underlying assumptions cover steady-state FDA enforcement intensity, cobalt-60 supply continuity, and technician certification program enrollment recovery, with deviation risk concentrated in accelerated ethylene oxide phase-out schedules and trade restriction impacts on radioisotope sourcing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Medical Activated Carbon Dressing Market
Infection Control
Sterilization Technologies Market
Infection Control
Clinical Hand Hygiene Products Market
Infection Control
Sanitizers Market
Infection Control
United States Hand Sanitizer Market
Infection Control
Healthcare Associated Infections (HAI) Treatment Market
Infection Control
Ultrasound Probe Disinfection Market
Infection Control
Denture Disinfectants Market
Infection Control
Global Prophylactic Human Vaccine Market
Infection Control
Europe Hospital-Acquired Infection Diagnostics Market
Infection Control
UV Sterilizer Pouch Market
Infection Control
Veterinary Disinfectant for Pets and Farms Market
Infection Control
Australia Healthcare Surface Disinfectant Wipes Market
Infection Control
Multi-Surface Disinfection Booster Systems with Low QAC Load Market
Infection Control
Sterility Indicators Market
Infection Control
Global High Level Disinfection Services Market