
 Global at-Home Drug of Abuse (DOA) Testing Market | 2026-2036
Global at-Home Drug of Abuse (DOA) Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global at-Home Drug of Abuse (DOA) Testing Market Foresight
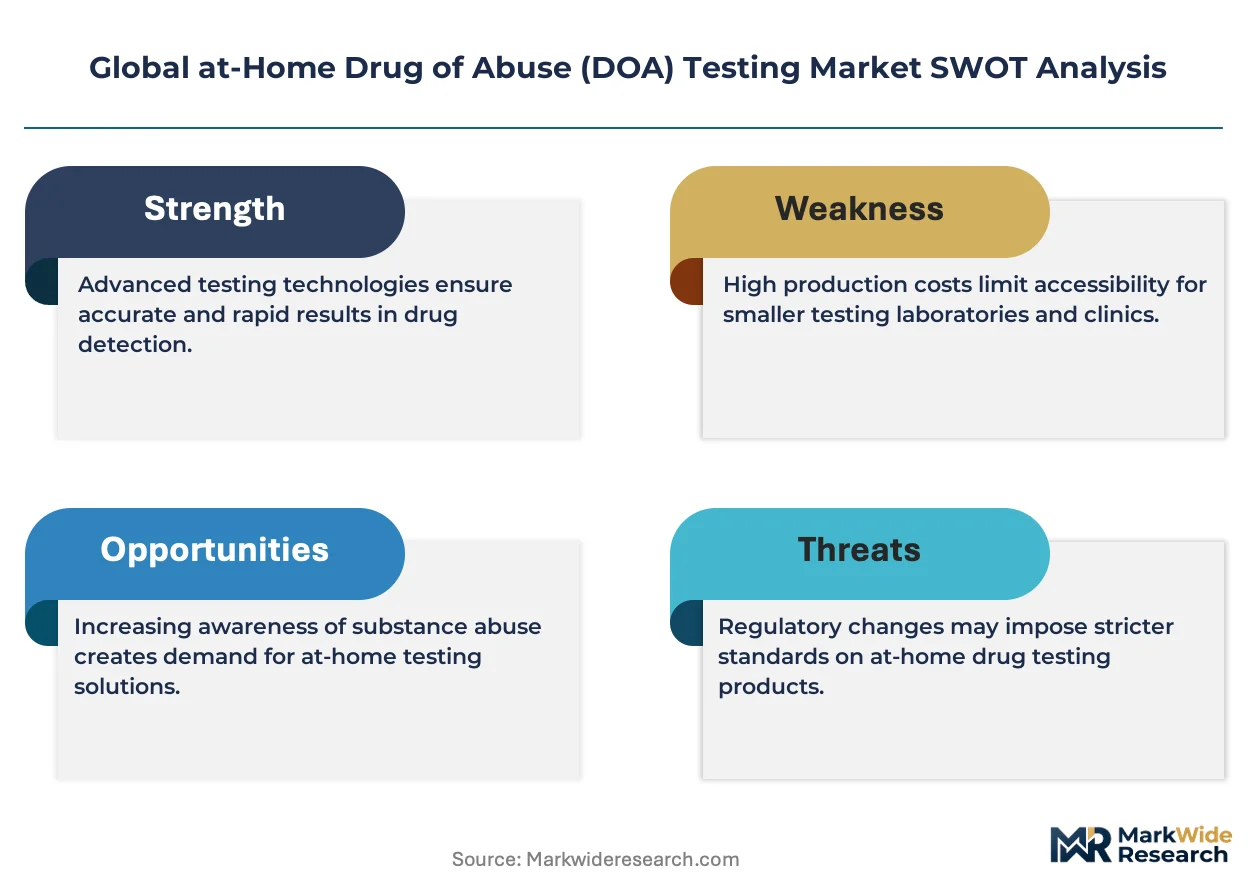
The EU Green Deal's chemical hazard reduction targets is recalibrating material selection across diagnostic supply chains. Abbott Laboratories leverages captive manufacturing of immunoassay reagents to sustain cost advantages in urine test kits. OraSure Technologies anchors its position through specialized oral fluid collection devices that compete with traditional matrix approaches. Drägerwerk AG & Co. KGaA dominates European distribution channels for workplace screening applications.
At-Home Drug of Abuse (DOA) Testing encompasses self-administered diagnostic systems that detect illicit substances or prescription drug misuse through biological matrices, typically employing lateral flow immunoassay strips with cutoff concentrations calibrated to SAMHSA guidelines for sensitivity and specificity. These devices serve industrial and commercial purposes by enabling decentralized screening without clinical infrastructure, reducing employer liability and healthcare system burden. Urine test kits occupy the largest volume position due to decades of regulatory familiarity and established chain-of-custody protocols, while saliva test kits represent the fastest-expanding segment as employers prioritize non-invasive collection and observed sampling. Chromatography-based testing technology commands premium pricing in confirmation workflows where mass spectrometry integration delivers legally defensible quantitative results.
The FDA oversees 510(k) clearance pathways for OTC diagnostic devices in the United States, while EMA coordination through the EU IVDR transition shapes conformity assessment requirements across European markets. Japan's PMDA maintains distinct pharmaceutical affairs standards that influence kit registration timelines and clinical validation expectations for manufacturers. Stakeholders must monitor evolving reimbursement policies for remote testing and the alignment of home-use labeling claims with occupational health provider liability frameworks.
Market Dynamics
Workplace screening mandates in transportation and logistics sectors are consolidating testing volumes into employer-sponsored at-home programs, compressing traditional clinical channel dependency while elevating chain-of-custody requirements for self-administered devices.
Growth Catalysts
- FDA 510(k) OTC Pathway Expansion:The FDA's streamlined clearance framework for over-the-counter diagnostic devices accelerates product commercialization timelines, reducing regulatory friction for urine and saliva test kit manufacturers targeting home-use labeling claims.
- SAMHSA Guideline Alignment:Federal workplace testing standards mandating specific cutoff concentrations for amphetamines, opioids, and cannabinoids create procurement specifications that favor pre-calibrated lateral flow immunoassay strips in employer screening programs.
- Oral Fluid Matrix Preference:Employers across trucking, aviation, and warehousing sectors prioritize non-invasive saliva collection devices that enable observed sampling without clinical infrastructure, displacing urine-based protocols in pre-employment and random testing workflows.
Market Restraints
- Reagent Supply Concentration:Captive manufacturing of monoclonal antibodies and enzyme conjugates concentrates among three North American and European chemical suppliers, exposing kit assemblers to input cost volatility and allocation constraints during demand surges.
- Confirmation Testing Bottleneck:Chromatography-based laboratory confirmation workflows require mass spectrometry infrastructure that remains geographically concentrated in urban clinical hubs, creating logistical delays and chain-of-custody vulnerabilities for remote collection models.
- EU IVDR Transition Friction:The European Union's In Vitro Diagnostic Regulation imposes new conformity assessment requirements and notified body capacity constraints that extend registration timelines and elevate compliance costs for kit manufacturers seeking CE marking.
Strategic Opportunities
- Japan PMDA Registration:Japan's distinct pharmaceutical affairs standards for home-use diagnostic devices create a protected market segment where early registrants secure distribution partnerships with occupational health providers serving manufacturing and construction sectors.
- Digital Result Integration:Smartphone-enabled test result capture and blockchain-verified chain-of-custody documentation converge with employer HR information systems, enabling real-time compliance reporting and reducing manual documentation errors in federally regulated industries.
- Remote Telehealth Reimbursement:Evolving Medicaid and private payer policies for substance use disorder screening create reimbursement pathways for physician-supervised at-home testing programs, expanding addressable volume beyond employer-paid models.
Industry Challenges
- Clinical Laboratory Scientist Shortage:Confirmation testing facilities face recruitment constraints for mass spectrometry operators and toxicology reviewers, extending turnaround times and creating backlogs that undermine the value proposition of rapid preliminary screening.
- Cross-Reactivity Validation Burden:Immunoassay manufacturers must demonstrate specificity against structurally similar prescription medications and dietary supplements, requiring extensive matrix studies that compress development timelines and elevate R&D expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global at-Home Drug of Abuse (DOA) Testing Market |
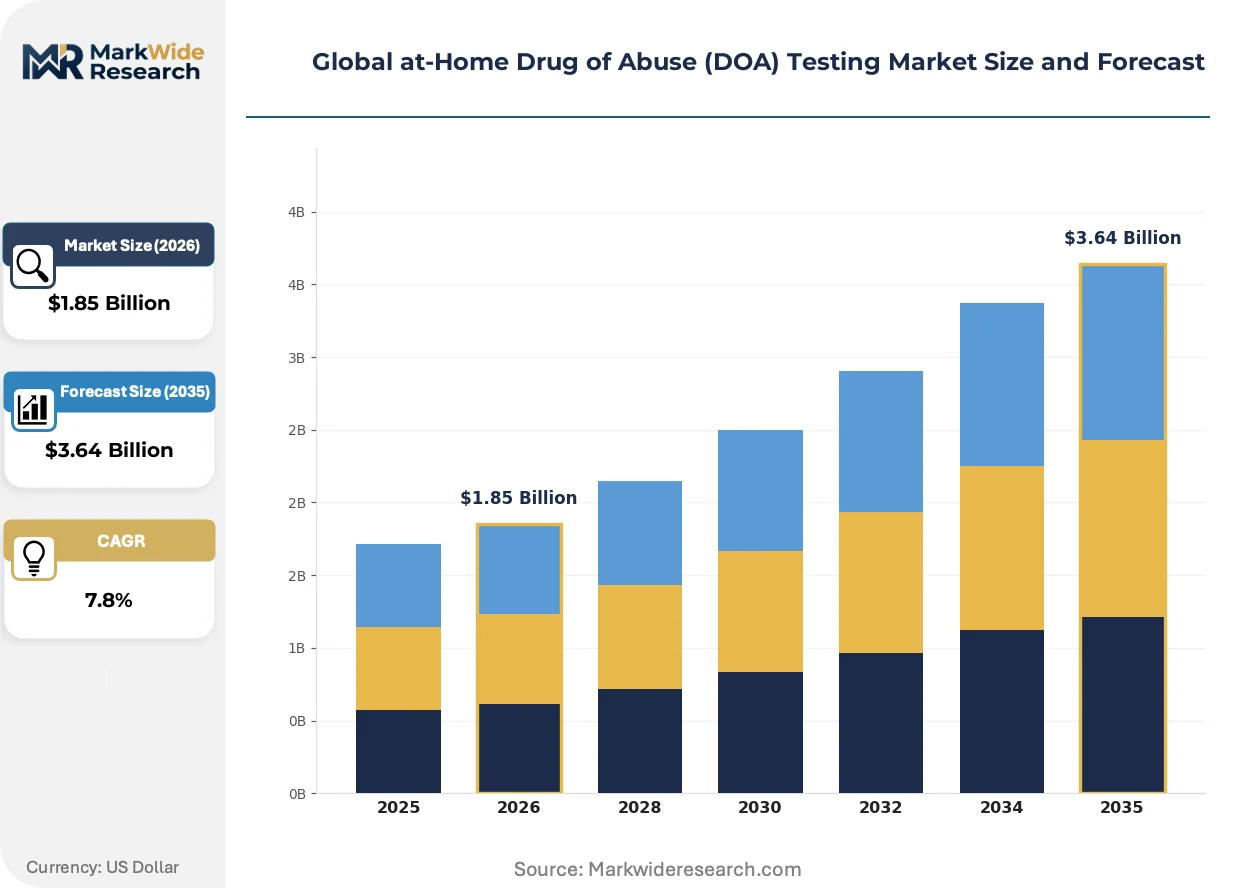
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urine Test Kits, Saliva Test Kits, Hair Follicle Test Kits, Sweat Patch Test Kits Testing Technology: Immunoassay, Chromatography, Enzyme Multiplied Immunoassay Technique, Mass Spectrometry Application: Workplace Screening, Home Use, Criminal Justice, Educational Institutions End User: Individual Consumers, Rehabilitation Centers, Occupational Health Providers, Law Enforcement Agencies |
| Companies Covered | Abbott Laboratories, OraSure Technologies, Psychemedics Corporation, Drägerwerk AG & Co. KGaA, Atlas Medical, Confirm BioSciences, Premier Biotech, First Check Diagnostics, Assure Tech. (Hangzhou) Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global at-Home Drug of Abuse (DOA) Testing Market Shifts & Advancements
Biometric authentication and automated result verification systems are displacing manual documentation workflows, while regulatory harmonization efforts across North America, Europe, and Asia-Pacific reshape product development roadmaps for multi-jurisdictional kit manufacturers.
Lateral flow immunoassay strips are integrating near-field communication chips and encrypted QR codes that enable tamper-evident result transmission directly to employer databases. Transportation sector safety managers adopt these connected devices at accelerated procurement cycles, compressing traditional paper-based chain-of-custody protocols into automated compliance workflows that reduce administrative burden and legal exposure.
The EU Green Deal's chemical hazard reduction targets are forcing reformulation of nitrocellulose membranes and plastic assay housings across European supply chains. Diagnostic manufacturers serving Germany, France, and the Netherlands respond by qualifying bio-based substrate alternatives and redesigning device geometries to minimize petroleum-derived content without compromising assay sensitivity or shelf stability.
Employer procurement committees now bundle at-home testing services with occupational health provider contracts, consolidating vendor relationships and demanding outcome-based performance guarantees. This concentration pattern is most visible in United States logistics hubs where third-party administrators negotiate enterprise pricing for multi-site trucking and warehousing operations, displacing decentralized purchasing by individual facility managers.
Global at-Home Drug of Abuse (DOA) Testing Market Segmentation
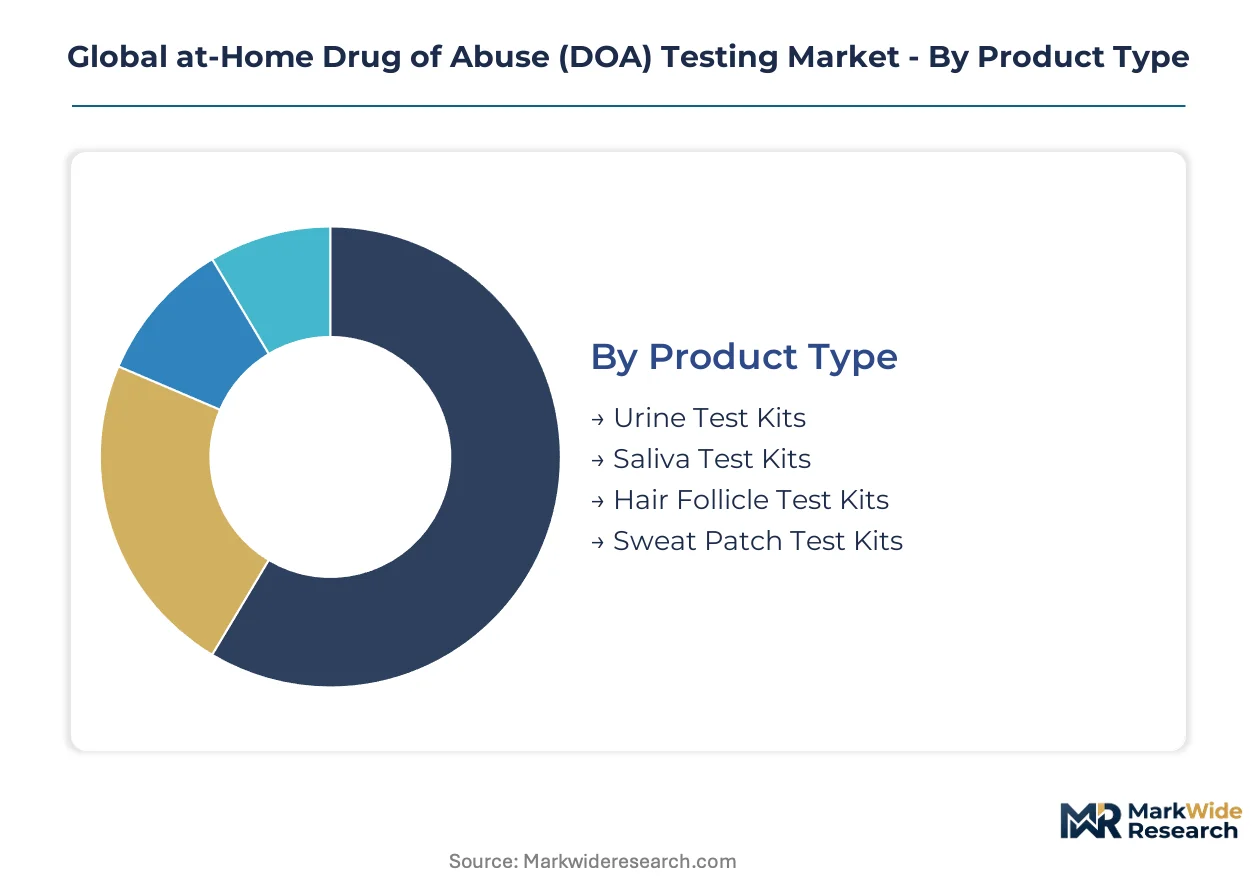
Segmentation in the at-home DOA testing market reveals how capital allocation, regulatory pathways, and end-user procurement power reshape competitive positioning across product formats and testing methodologies. Understanding these divides exposes where margin pools concentrate and which segments command premium pricing.
Product Type:
Capital intensity varies sharply across collection matrices, with integrated device manufacturing and reagent stabilization demanding differential upfront investment in production infrastructure and quality systems.
- Urine Test Kits:Lateral flow cassettes with nitrocellulose membranes and colloidal gold conjugates require precision coating equipment and humidity-controlled assembly environments. Demand concentrates in United States transportation and logistics employers where SAMHSA-mandated cutoff calibrations and established chain-of-custody protocols sustain procurement volume despite collection invasiveness.
- Saliva Test Kits:Oral fluid collection devices with integrated buffer systems and tamper-evident seals command higher per-unit manufacturing investment due to specialized plastic molding and biosafety validation requirements. Germany and Japan employers prioritize these formats for observed sampling without clinical infrastructure, displacing urine protocols in pre-employment screening workflows.
- Hair Follicle Test Kits:Specimen collection pouches with solvent-resistant sealing and chain-of-custody documentation support extended detection windows for criminal justice applications.
- Sweat Patch Test Kits:Adhesive transdermal collectors with semipermeable membranes serve continuous monitoring programs in rehabilitation settings.
Most installed capacity flows through Urine Test Kits. Expansion is steepest in Saliva Test Kits.
Testing Technology:
Technology selection tracks the tension between rapid qualitative screening and legally defensible quantitative confirmation, with capital deployment skewing toward platforms that bridge both requirements.
- Immunoassay:Competitive and sandwich format lateral flow strips with monoclonal antibody reagents dominate volume production due to established supply chains and FDA 510(k) familiarity. United States kit assemblers source antibody conjugates from captive North American chemical suppliers, creating input cost concentration that elevates working capital requirements during demand surges.
- Chromatography:High-performance liquid chromatography systems with ultraviolet or fluorescence detection serve laboratory confirmation workflows where mass spectrometry integration delivers quantitative results admissible in employment disputes and legal proceedings.
- Enzyme Multiplied Immunoassay Technique:EMIT-based analyzers with enzyme-labeled reagents occupy intermediate positions in occupational health clinic settings requiring higher throughput than lateral flow but lower capital burden than chromatography.
- Mass Spectrometry:LC-MS/MS and GC-MS platforms with triple-quadrupole configuration command the steepest infrastructure investment and operator training expenditure, concentrating in urban clinical hubs serving federally regulated industries.
Volume concentrates in Immunoassay for preliminary screening. Value capture climbs fastest in Mass Spectrometry for confirmation protocols.
Application:
Application segmentation maps directly to procurement authority structures, with employer-sponsored programs consolidating purchasing power that individual consumers cannot replicate.
- Workplace Screening:Federally mandated and employer-initiated testing programs in trucking, aviation, and warehousing sectors drive kit procurement through third-party administrators negotiating enterprise pricing. United States Department of Transportation regulations and Japan's Ministry of Health, Labour and Welfare guidelines shape validation requirements and documentation standards.
- Home Use:Individual purchase decisions for personal monitoring or family screening operate through retail pharmacy and e-commerce channels with lower per-transaction value but higher margin percentages.
- Criminal Justice:Probation and parole programs with court-ordered testing requirements demand evidentiary-grade documentation and defensible chain-of-custody protocols.
- Educational Institutions:Secondary school and university athletic programs with zero-tolerance policies sustain seasonal procurement cycles tied to academic calendars.
Procurement volume aggregates in Workplace Screening. Reimbursement pathway development is advancing most quickly in Home Use through evolving telehealth integration.
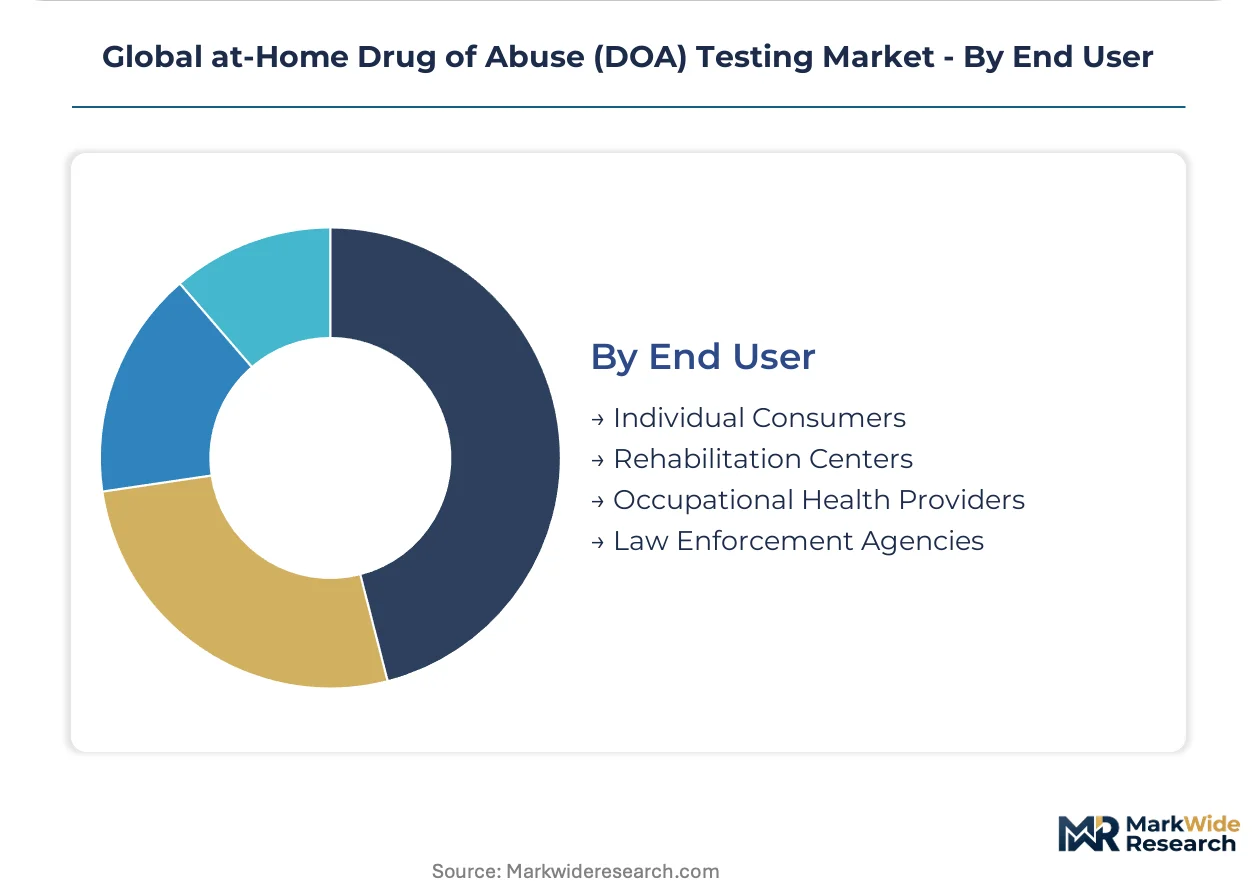
End User:
End-user categories reflect divergent technical sophistication and price sensitivity, with institutional buyers extracting volume discounts that compress manufacturer margins.
- Individual Consumers:Retail purchasers with limited technical training require intuitive result interpretation and smartphone-enabled documentation, driving design investment in simplified user interfaces and encrypted result transmission.
- Rehabilitation Centers:Substance use disorder treatment facilities with clinical oversight prioritize test frequency and cost efficiency over laboratory-grade precision, sustaining demand for mid-sensitivity lateral flow formats.
- Occupational Health Providers:Third-party administrators serving multi-site employers in Germany and the United States consolidate kit procurement through outcome-based contracts with performance guarantees.
- Law Enforcement Agencies:Police departments and correctional facilities with forensic requirements demand higher specificity and legal defensibility, channeling volume toward confirmation-capable platforms.
Contract concentration is tightest among Occupational Health Providers. Regulatory tailwinds are strongest for Law Enforcement Agencies with federal funding expansion for drug monitoring programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The at-home drug testing industry traces its commercial scale to United States workplace safety mandates established during the 1980s Reagan administration, with federal transportation regulations creating the first mass-market procurement channel for decentralized screening devices.
United States
Department of Transportation regulations and SAMHSA workplace testing guidelines sustain employer-sponsored kit procurement through third-party administrators. FDA 510(k) clearance pathways for OTC diagnostic devices accelerate commercialization timelines for domestic manufacturers. Dallas-Fort Worth logistics hubs concentrate multi-site trucking and warehousing operations that negotiate enterprise pricing for saliva and urine test formats.
Germany
Occupational health providers serving manufacturing and chemical processing sectors prioritize non-invasive saliva collection devices for observed sampling workflows. EU IVDR transition imposes new conformity assessment requirements that extend CE marking timelines for kit registrants. The Rhine-Ruhr industrial corridor anchors distribution networks where Drägerwerk AG & Co. KGaA maintains channel dominance for workplace screening applications.
Japan
PMDA pharmaceutical affairs standards for home-use diagnostic devices create protected market segments with distinct validation expectations. Ministry of Health, Labour and Welfare guidelines shape employer screening protocols in construction and transportation sectors. The Kanto region around Tokyo concentrates occupational health providers serving manufacturing operations with bundled testing service contracts.
United Kingdom
Railway and aviation safety regulators mandate pre-employment and random testing programs that channel volume toward rapid immunoassay formats. MHRA oversight of in vitro diagnostic devices aligns with broader European regulatory frameworks while maintaining national notification requirements. The Greater London logistics cluster drives procurement for courier and delivery fleet screening programs.
Netherlands
EU Green Deal chemical hazard reduction targets force reformulation of nitrocellulose membranes and plastic assay housings across diagnostic supply chains. REACH compliance obligations elevate material qualification costs for European kit assemblers. The Randstad conurbation hosts third-party administrators negotiating outcome-based contracts for multi-site employer programs across Benelux markets.
Global at-Home Drug of Abuse (DOA) Testing Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory sophistication and distribution infrastructure dimensions. The vendor base stratifies into three tiers: multinational diagnostics conglomerates with captive reagent manufacturing, specialized oral fluid device developers with proprietary collection technologies, and regional kit assemblers sourcing antibody conjugates from concentrated chemical suppliers. Consolidation pressures favor backward integration into immunoassay reagent production and strategic partnerships with occupational health providers for outcome-based contracting.
Within the multinational diagnostics tier, Abbott Laboratories and OraSure Technologies exemplify divergent specialization strategies. Abbott's captive manufacturing of immunoassay reagents sustains cost advantages in standardized urine test formats. OraSure occupies a distinct position through proprietary oral fluid collection devices that compete with traditional matrix approaches. Drägerwerk AG & Co. KGaA anchors European distribution channels, particularly in German-speaking workplace screening markets. Assure Tech. (Hangzhou) Co., Ltd. represents the regional assembler archetype, sourcing antibody inputs from North American and European chemical suppliers while serving price-sensitive procurement segments.
| Leading Market Players |
|---|
| Abbott Laboratories |
| OraSure Technologies |
| Psychemedics Corporation |
| Drägerwerk AG & Co. KGaA |
| Atlas Medical |
| Confirm BioSciences |
| Premier Biotech |
| First Check Diagnostics |
| Assure Tech. (Hangzhou) Co., Ltd. |
| Others |
Supply & Pricing Matrix
Lateral flow immunoassay manufacturing automation in North American and European facilities is compressing per-unit production costs while simultaneously concentrating antibody conjugate supply among three chemical suppliers. This dual effect elevates pricing power for captive reagent producers and exposes kit assemblers to input allocation constraints during demand surges.
Pricing Analysis
Three-tier pricing structure across FDA-cleared premium, standard CE-marked, and economy unbranded tiers separates validated workplace screening kits from personal-use retail formats. Price differentiation hinges on SAMHSA guideline calibration precision and chain-of-custody documentation sophistication. Cost compression in economy tiers is intensifying because Chinese and Indian regional assemblers source antibody inputs from concentrated North American suppliers. Occupational health providers exhibit lowest price sensitivity due to outcome-based contracting, while individual consumers drive margin erosion through retail pharmacy price comparison.
Supply Chain Analysis
Reverse logistics for expired or defective lateral flow cassettes remain underdeveloped, with most kit manufacturers lacking formal refurbishment programs for unused inventory returns. Nitrocellulose membrane production concentrates in the United States, Germany, and Japan, while colloidal gold conjugate synthesis draws from captive North American and European chemical facilities. Single-source vulnerability for monoclonal antibody inputs creates exposure during FDA inspection backlogs or EMA notified body capacity constraints. Distribution runs through third-party occupational health administrators in the United States and direct employer procurement in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The at-home DOA testing market functions as a stable compounder, with employer screening mandates in transportation and logistics sectors generating recurring procurement volume resistant to economic cyclicality.
For Market Incumbents: Anticipate margin compression from oral fluid device specialists by deepening captive manufacturing of immunoassay reagents and securing exclusive distribution partnerships with multi-site occupational health providers. Invest in smartphone-enabled result verification to defend against digital-native entrants offering blockchain chain-of-custody documentation.
For New Entrants and Emerging Players: Capture white-space opportunity in Japan's PMDA-regulated home-use segment where early registrants secure protected distribution partnerships with construction sector occupational health providers. Target Medicaid reimbursement pathway development for physician-supervised at-home testing programs, leveraging telehealth integration as the primary go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional kit assemblers lacking backward integration into antibody conjugate production. Long-term viability over the projection horizon rests on regulatory clearance velocity and occupational health provider contract concentration. Monitor FDA 510(k) backlog duration and EU IVDR notified body capacity expansion as inflection indicators for commercialization timeline risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reagent Manufacturing | Abbott Laboratories sustains cost advantages through captive monoclonal antibody production. |
| Digital Result Integration Development | Blockchain-verified chain-of-custody documentation aligns with DOT compliance reporting requirements. |
| Japan PMDA Registration Priority | Early registrants secure distribution partnerships serving manufacturing and construction sectors. |
| EU IVDR Conformity Assessment Acceleration | CE marking timeline compression enables faster market entry in German workplace screening channels. |
| Telehealth Reimbursement Pathway Investment | Medicaid policy alignment expands addressable volume beyond employer-paid testing models. |
Research Methodology
Multiple input streams — primary interviews with diagnostic kit manufacturers, occupational health procurement directors, and toxicology laboratory operators, alongside secondary validation through FDA 510(k) filings, EMA IVDR transition guidance, and SAMHSA workplace testing guideline documents — were reconciled through bottom-up and top-down triangulation. Primary fieldwork encompassed discussions with third-party administrator executives, GPO contracts managers, and clinical laboratory scientists operating confirmation testing facilities.
Cross-referencing historical procurement volume patterns against expert panel input shaped the analytical framework across product type, testing technology, application, and end-user segmentation dimensions. CAGRs were derived from modeled unit economics incorporating reagent input cost trajectories, regulatory clearance timeline assumptions, and employer screening mandate expansion rates. Forecast inputs included PMDA registration pipeline visibility and EU Green Deal material reformulation cost impacts.
Regulatory approval delays, supply chain disruption in antibody conjugate manufacturing, and reimbursement policy reversals are the dominant revision risks to modeled outputs. Practitioners should monitor FDA inspection backlog duration, North American chemical supplier allocation announcements, and Medicaid telehealth policy bulletins for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Specimen Validity Testing Market
Testing Services
Indoor Allergen and Particulate Exposure Assessment Test Devices Market
Testing Services
Home DNA Testing Market
Testing Services
Irradiation Sterilization Services Market
Testing Services
Global Vitamin D Testing Market
Testing Services
Drug Testing Systems Market
Testing Services
Global HIV Self Test Kits Market
Testing Services
Outsourced Testing Services Market
Testing Services
Global ADME Toxicology Testing Market
Testing Services
Asia Pacific Sterility Testing Market
Testing Services
Rift Valley Fever Testing Market
Testing Services
Ready-To-Use Laboratory Test Kits Market
Testing Services
Global Diagnostic Testing Market
Testing Services
Test Strips Market
Testing Services
Drug Testing Equipment Market
Testing Services
Global Virology Testing Market