
 Global Homocysteine Testing Market | 2026-2036
Global Homocysteine Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Homocysteine Testing Market Foresight
CE marking under the EU In Vitro Diagnostic Regulation is shifting the cost-of-entry calculus for homocysteine assay manufacturers seeking European market access. Abbott Laboratories leverages its integrated diagnostics platform to sustain competitive positioning across hospital laboratory networks. Siemens Healthineers anchors its presence through automated immunoassay systems that dominate high-throughput clinical workflows. Thermo Fisher Scientific differentiates via specialized reagent kits serving academic research institutes with custom protocol requirements.
Homocysteine testing quantifies total plasma homocysteine concentration, typically via enzymatic cycling methods or chromatographic separation with fluorometric detection, to assess cardiovascular and neurological risk through elevated sulfur amino acid levels. Chemiluminescence immunoassay systems occupy the largest installed base among product types due to throughput efficiency and analyzer consolidation trends in diagnostic laboratories. Cardiovascular risk assessment leads application demand, while neurological disorder diagnosis represents the fastest-expanding segment as biomarker panels for cognitive decline gain clinical traction. Microplate assays retain relevance in resource-limited settings where capital equipment constraints favor manual workflow formats.
The FDA oversees premarket notification pathways for novel homocysteine assays, while the Clinical Laboratory Improvement Amendments govern analytical performance standards in US testing facilities. EMA coordination through the In Vitro Diagnostic Medical Devices Regulation harmonizes conformity assessment requirements across European member states, directly shaping product development timelines for multinational manufacturers. Stakeholders must monitor evolving reimbursement coding for cardiovascular prevention services, as coverage determinations by national health authorities will dictate volume expansion trajectories in outpatient and inpatient settings alike.
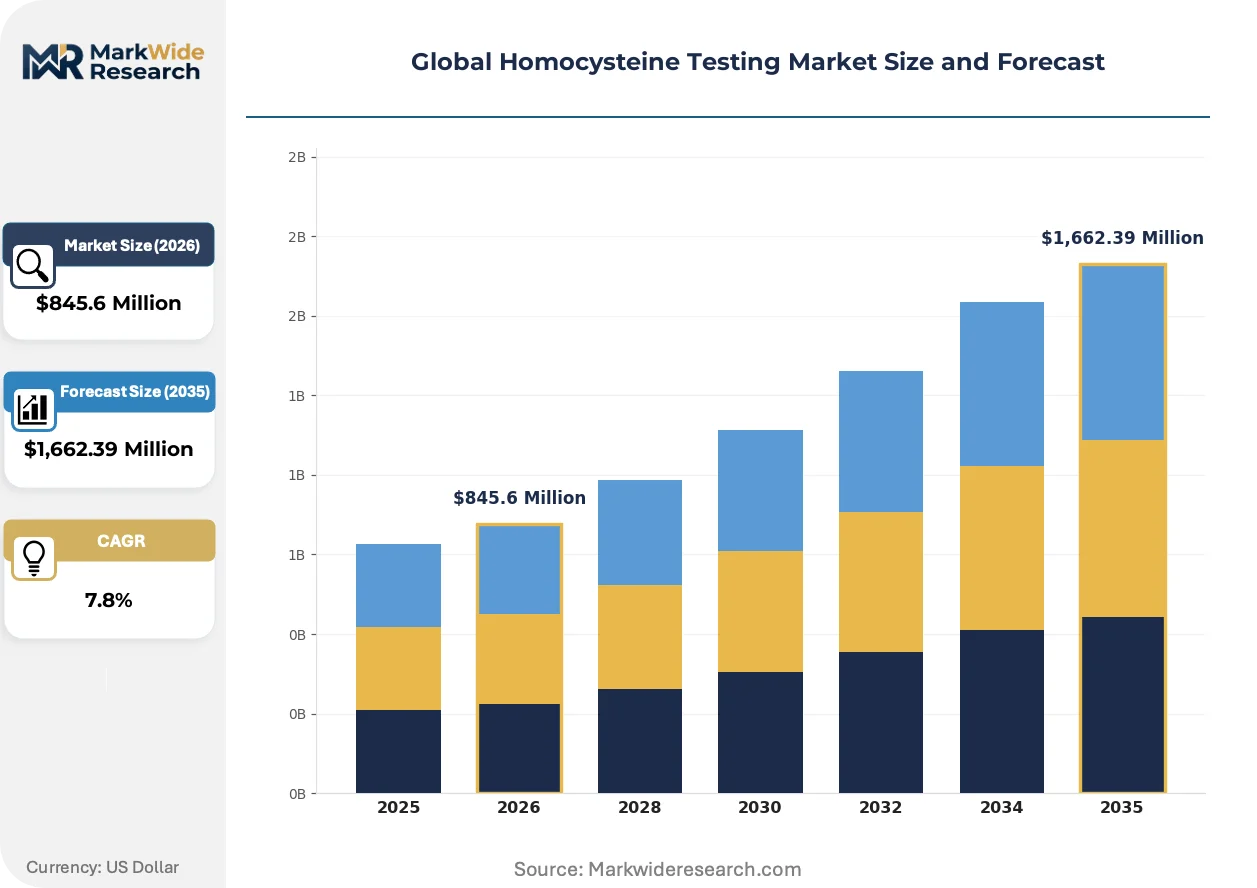
Market Dynamics
Automated chemiluminescence platforms are compressing manual assay formats as hospital laboratories consolidate testing menus onto unified analyzers, reshaping vendor competitive dynamics around throughput efficiency and reagent bundling power.
Growth Catalysts
- Medicare preventive screening protocols:US reimbursement expansion for cardiovascular risk panels drives outpatient volume in physician office laboratories and ambulatory care centers.
- Enzymatic cycling methods:These assays reduce chromatography infrastructure requirements, enabling mid-tier hospital labs to bring homocysteine testing in-house rather than outsourcing.
- Neurology biomarker adoption:Cognitive decline research programs at academic medical centers are integrating homocysteine into multi-analyte panels for Alzheimer's risk stratification.
Market Restraints
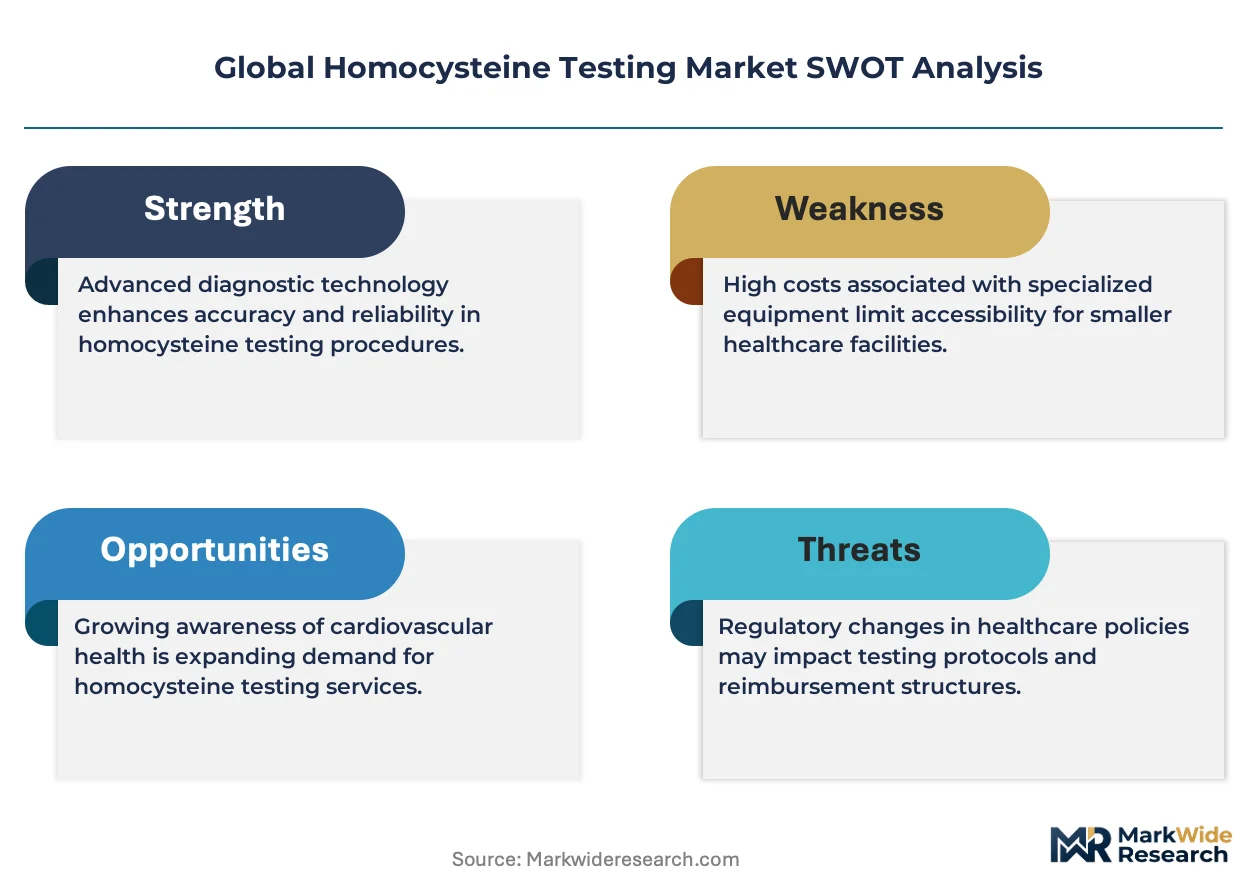
- Analyzer capital intensity:High-throughput immunoassay systems require substantial upfront investment, limiting access for independent clinical laboratories and rural health networks.
- CE marking transition costs:EU In Vitro Diagnostic Medical Devices Regulation conformity assessments impose documentation and quality management burdens that disproportionately affect smaller reagent manufacturers.
- Alternative cardiovascular biomarkers:High-sensitivity C-reactive protein and lipoprotein(a) assays compete for limited panel slots in preventive cardiology protocols.
Strategic Opportunities
- Point-of-care expansion:Fingerstick homocysteine assays for pharmacy clinic settings could capture preventive screening volumes outside traditional laboratory channels.
- China's hospital laboratory consolidation:Regional medical center alliances in Jiangsu and Zhejiang provinces favor vendors offering integrated reagent-analyzer contracts.
- EMA biomarker qualification pathways:Formal regulatory recognition of homocysteine as a neurological endpoint could unlock pharmaceutical clinical trial testing demand.
Industry Challenges
- Cross-platform standardization gaps:Methodological differences between enzymatic and chromatographic assays create result harmonization difficulties for multi-site health systems.
- Specialized field service engineer scarcity:Automated analyzer maintenance requires technical expertise concentrated in urban metropolitan labor markets, complicating rural deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Homocysteine Testing Market |
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $1,662.39 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Immunoassay, High Performance Liquid Chromatography, Chemiluminescence Immunoassay, Fluorescence Polarization Immunoassay, Gas Chromatography Mass Spectrometry, Microplate Assay Application: Cardiovascular Risk Assessment, Neurological Disorder Diagnosis, Nutritional Deficiency Screening, Prenatal Testing, Kidney Disease Monitoring, Stroke Evaluation End User: Diagnostic Laboratories, Specialty Clinics, Academic Research Institutes, Preventive Care Centers, Primary Care Providers, Clinical Hospitals Distribution Channel: Direct Sales, Laboratory Distributors, Online Pharmacies, Medical Device Wholesalers, Hospital Procurement, Healthcare Retail Chains |
| Companies Covered | F. Hoffmann-La Roche Ltd, Abbott Laboratories, Siemens Healthineers AG, Bio-Rad Laboratories, Sekisui Diagnostics, Thermo Fisher Scientific Inc., DiaSorin S.p.A., ARUP Laboratories, Quest Diagnostics Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Homocysteine Testing Market Shifts & Advancements
Diagnostic platforms are converging around automated sample-to-result workflows, compressing turnaround times while elevating analytical performance requirements for routine metabolic testing.
Random-access chemiluminescence immunoassay analyzers are consolidating previously fragmented testing workflows onto single instruments. Large health system laboratories in the United States and Germany are retiring standalone homocysteine analyzers in favor of multi-analyte systems. This vendor-driven consolidation is compressing the addressable market for dedicated assay manufacturers and favoring integrated diagnostics suppliers with broad reagent menus.
EU In Vitro Diagnostic Medical Devices Regulation implementation is extending conformity assessment timelines for novel assay introductions. Manufacturers must navigate notified body capacity constraints and expanded clinical evidence requirements. High-complexity reference laboratories are responding by accelerating internal validation of existing CE-marked products before transitional deadlines expire.
Subscription-based reagent procurement is displacing transactional purchasing in consolidated health networks. Group purchasing organizations are negotiating multi-year supply agreements that bundle homocysteine reagents with cardiovascular and metabolic panels. This shift is most visible in US integrated delivery networks, where standardization committees mandate preferred vendor relationships across affiliated hospitals.
Global Homocysteine Testing Market Segmentation
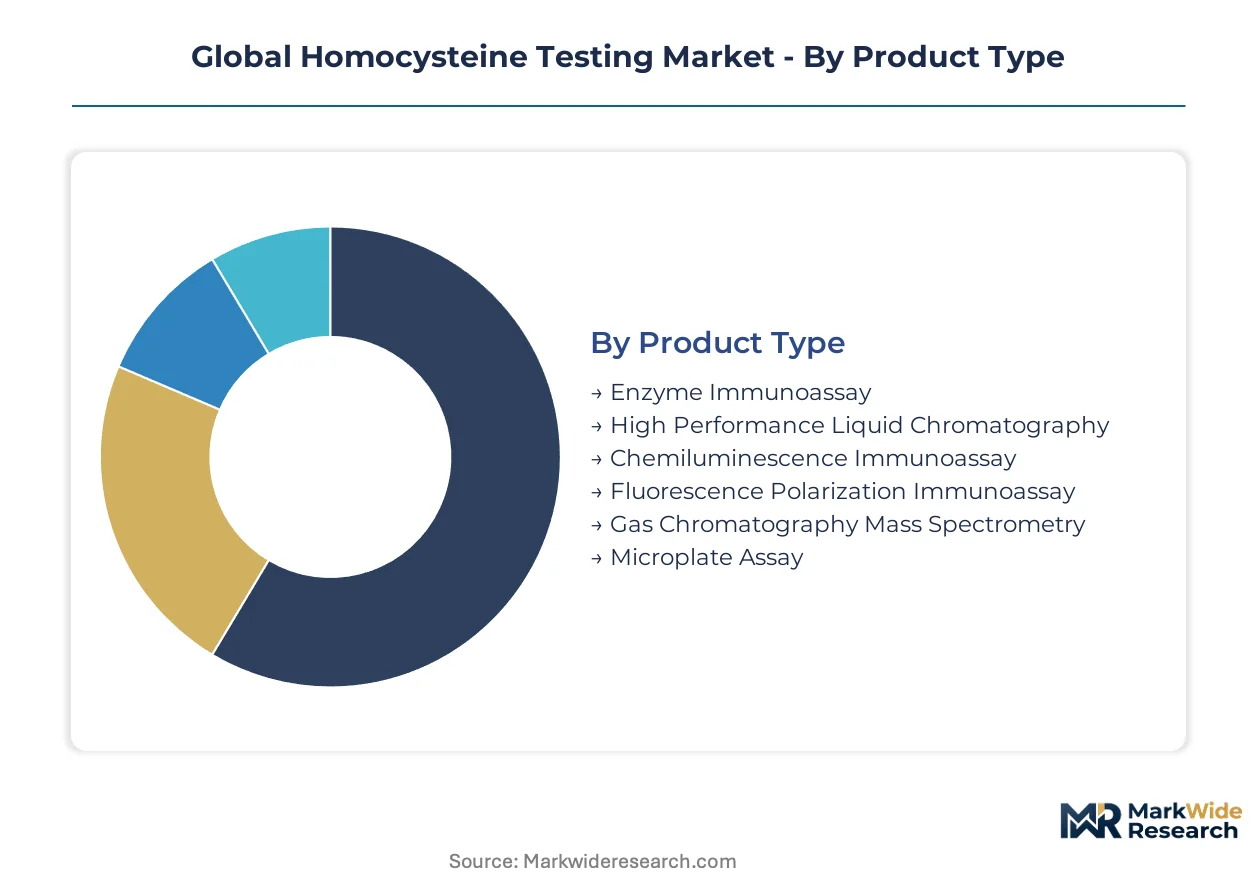
Homocysteine testing segmentation reflects divergent technical requirements across clinical workflows, from high-throughput hospital laboratories demanding analyzer integration to resource-constrained settings prioritizing manual flexibility. Product architecture choices directly determine addressable end-user pools and reagent procurement economics.
Product Type:
Chemiluminescence immunoassay systems anchor the installed base in consolidated laboratory networks, while enzymatic and chromatographic methods serve differentiated throughput and capital constraints.
- Chemiluminescence Immunoassay:Random-access analyzers consolidate homocysteine testing with cardiovascular and metabolic panels on unified instruments. Siemens Healthineers and Abbott Laboratories dominate US hospital laboratory procurement through multi-year reagent bundling contracts.
- Enzyme Immunoassay:Enzymatic cycling methods reduce infrastructure requirements, enabling mid-tier hospital labs in Germany and Japan to bring testing in-house. Medicare reimbursement expansion for preventive cardiac panels accelerates US physician office laboratory adoption.
- High Performance Liquid Chromatography:Gold-standard reference method retained by academic medical centers for harmonization studies.
- Fluorescence Polarization Immunoassay:Specialized detection chemistry serving smaller diagnostic laboratories with moderate throughput needs.
- Gas Chromatography Mass Spectrometry:High-complexity validation platform for forensic toxicology and research applications.
- Microplate Assay:Manual workflow format sustaining relevance in India's tier-2 cities and Brazil's public health networks where capital equipment constraints predominate.
Chemiluminescence immunoassay leads volumes today; enzyme immunoassay is gaining share fastest.
Application:
Clinical utility spans preventive cardiology protocols through emerging neurological biomarker integration, with reimbursement coding determining volume concentration across use cases.
- Cardiovascular Risk Assessment:Elevated plasma homocysteine concentration predicts coronary artery disease and stroke independent of traditional lipid panels. US Medicare preventive screening protocols and Germany's statutory health insurance cardiovascular prevention programs concentrate demand in outpatient settings.
- Neurological Disorder Diagnosis:Multi-analyte panels for Alzheimer's risk stratification at academic medical centers in Massachusetts and California integrate homocysteine with amyloid and tau biomarkers. EMA biomarker qualification pathways could unlock pharmaceutical clinical trial testing demand.
- Nutritional Deficiency Screening:B-vitamin status evaluation in functional medicine practices.
- Prenatal Testing:Neural tube defect risk assessment in maternal-fetal medicine protocols.
- Kidney Disease Monitoring:Homocysteine elevation tracking in chronic renal failure progression.
- Stroke Evaluation:Secondary prevention workups in cerebrovascular clinics.
Cardiovascular risk assessment commands the largest revenue pool; neurological disorder diagnosis shows the steepest expansion trajectory.
End User:
Customer concentration shifts toward integrated delivery networks and consolidated diagnostic platforms, compressing standalone analyzer markets.
- Diagnostic Laboratories:Quest Diagnostics and LabCorp network consolidation in the US drives standardized reagent procurement across regional reference laboratories. Automated platform migration eliminates dedicated homocysteine analyzers in favor of multi-analyte systems.
- Clinical Hospitals:Academic medical centers in Boston, Heidelberg, and Tokyo anchor demand for high-throughput immunoassay installations. Subscription-based reagent agreements displace transactional purchasing in consolidated health networks.
- Specialty Clinics:Cardiology and endocrinology practices with in-house laboratory capabilities.
- Academic Research Institutes:Custom protocol requirements for longitudinal cognitive decline studies.
- Preventive Care Centers:Corporate wellness programs and executive health screening services.
- Primary Care Providers:Point-of-care expansion targets for fingerstick assay development.
Diagnostic laboratories capture the dominant share; clinical hospitals are expanding most quickly through analyzer consolidation.
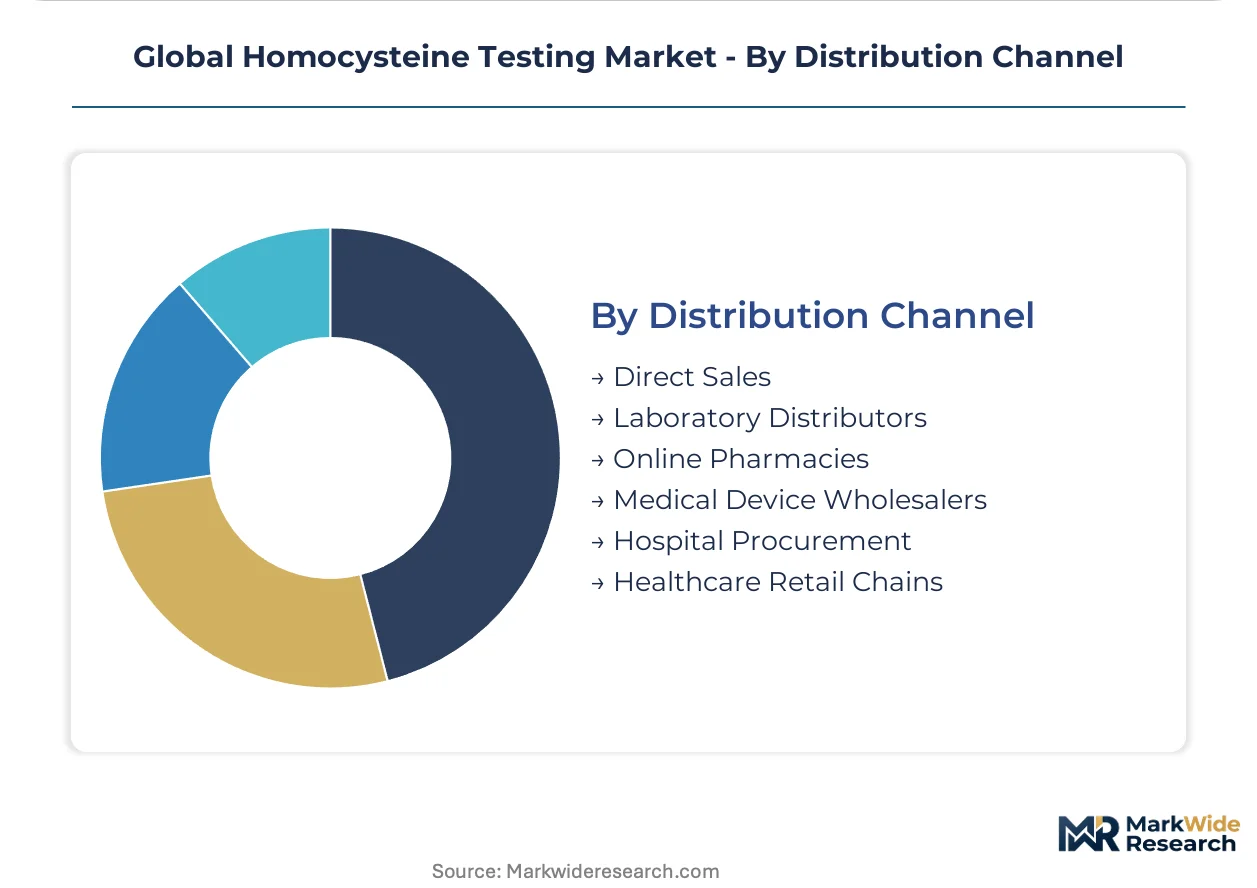
Distribution Channel:
Procurement pathway selection reflects customer scale, geographic concentration, and regulatory compliance requirements across markets.
- Laboratory Distributors:McKesson and Cardinal Health in the US, Henry Schein in Europe, and regional players in Japan intermediate reagent supply to mid-sized independent laboratories. Group purchasing organization negotiations bundle homocysteine reagents with cardiovascular panels.
- Direct Sales:Integrated diagnostics vendors deploy field application scientists for high-throughput analyzer placements at major health systems. Technical service engineer scarcity in rural US markets and Australia's Northern Territory complicates remote deployment.
- Online Pharmacies:Direct-to-consumer testing kits in regulatory-permissive markets.
- Medical Device Wholesalers:Capital equipment distribution in emerging markets.
- Hospital Procurement:Centralized purchasing committees in US integrated delivery networks.
- Healthcare Retail Chains:Pharmacy clinic preventive screening channels in development.
Laboratory distributors maintain volume leadership; direct sales is climbing the fastest through integrated platform contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical laboratory technologists and cardiovascular epidemiologists concentrate in metropolitan medical corridors across five countries, anchoring regional demand patterns for homocysteine testing infrastructure.
United States
Medicare preventive screening protocols and integrated delivery network consolidation drive outpatient volume in physician office laboratories. FDA premarket notification pathways govern novel assay introductions, while CLIA standards shape analytical performance requirements. Boston's academic medical corridor anchors neurological biomarker research integrating homocysteine into cognitive decline panels.
Germany
Statutory health insurance cardiovascular prevention programs concentrate demand in outpatient cardiology practices. EMA coordination through IVDR harmonizes conformity assessment timelines for multinational manufacturers. Heidelberg's university hospital network sustains high-throughput immunoassay installations serving regional medical center alliances.
Japan
PMDA regulatory frameworks and aging demographics expand preventive cardiac screening protocols in metropolitan health networks. METI industrial policy supports diagnostic platform innovation through targeted research subsidies. Tokyo's diagnostic laboratory clusters favor automated analyzer consolidation onto unified multi-analyte systems.
China
Hospital laboratory consolidation in Jiangsu and Zhejiang provinces favors integrated reagent-analyzer procurement contracts. NMPA medical device registration pathways shape product development timelines for domestic and multinational manufacturers. Shanghai's regional medical center alliances standardize cardiovascular risk panel menus across affiliated facilities.
India
Microplate assay formats sustain relevance in tier-2 cities where capital equipment constraints predominate over automated platform adoption. CDSCO medical device regulations govern import and domestic manufacturing compliance for assay manufacturers. Maharashtra's diagnostic laboratory networks balance cost constraints with expanding preventive screening volumes.
Global Homocysteine Testing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the homocysteine testing landscape, producing a tiered competitive structure anchored by integrated diagnostics platforms and specialized reagent manufacturers. Market concentration favors vendors with broad cardiovascular and metabolic assay menus capable of securing multi-year hospital procurement contracts. Three archetypes dominate: integrated diagnostics conglomerates with analyzer-installed bases, specialized immunoassay reagent manufacturers, and reference laboratory service providers with in-house assay development capabilities. Competitive dynamics center on reagent bundling negotiations and analyzer placement contracts rather than standalone product differentiation.
Among integrated diagnostics conglomerates, Abbott Laboratories and Siemens Healthineers occupy positions exemplifying platform-centric competitive strategy, while Thermo Fisher Scientific represents the specialized reagent and research-oriented archetype. These three companies anchor distinct competitive vectors without exclusive segment dominance, reflecting the market's structural division between high-throughput clinical workflows and custom protocol academic applications.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| Siemens Healthineers AG |
| Bio-Rad Laboratories |
| Sekisui Diagnostics |
| Thermo Fisher Scientific Inc. |
| DiaSorin S.p.A. |
| ARUP Laboratories |
| Quest Diagnostics Incorporated |
| Others |
Supply & Pricing Matrix
CE-IVDR certification tiers bifurcate the homocysteine testing landscape into premium automated platforms and manual assay alternatives, with each tier commanding distinct supply chain footprints and procurement economics. Siemens Healthineers and Abbott Laboratories anchor the premium segment through analyzer-installed bases, while microplate manufacturers feed cost-sensitive networks in India and Brazil via distributor-heavy logistics.
Pricing Analysis
Bundled reagent-analyzer contracts dominate hospital procurement, compressing standalone assay margins while subscription-based agreements lock in multi-year revenue streams. Price differentiation rests on throughput capacity and IVDR certification status, with CLIA-waived platforms commanding premiums over research-use-only alternatives. Cost compression in manual assay tiers intensifies as enzymatic cycling methods displace chromatography infrastructure. Physician office laboratories exhibit highest price sensitivity; academic medical centers prioritize analytical performance over unit economics.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan anchor hub-and-spoke patterns for reagent cold-chain logistics. Key inputs draw from specialized enzyme suppliers in Denmark, fluorometric detection chemistry from Japanese component manufacturers, and plastic consumables from Chinese molding facilities. Single-source vulnerability concentrates in high-purity enzyme feedstocks. Distribution runs through laboratory distributors McKesson and Cardinal Health in North America, with direct sales penetrating consolidated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The homocysteine testing market represents a late-cycle quality story as neurological biomarker adoption shifts demand toward analytically validated, IVDR-certified platforms over commodity alternatives.
For Market Incumbents: Deepen reagent bundling power across cardiovascular and metabolic panels to defend analyzer placements against emerging enzymatic cycling specialists. Prioritize backward integration into enzyme manufacturing to insulate margins from raw material volatility. Expand field service engineer training programs to address scarcity in rural US markets and Australia's Northern Territory. For New Entrants and Emerging Players: Launch via point-of-care distribution partnerships targeting pharmacy clinic preventive screening channels outside traditional laboratory networks. White-space opportunity concentrates in fingerstick assay formats for corporate wellness programs and tier-2 Indian cities where capital constraints favor manual workflows. Pursue EMA biomarker qualification pathways to unlock pharmaceutical clinical trial demand. For Investors and Strategic Acquirers: Consolidation pressure builds where IVDR transition costs disproportionately burden smaller reagent manufacturers lacking notified body relationships. Long-term viability favors platforms with installed-base moats and multi-analyte menu breadth. Acquisition target archetype: specialized immunoassay developers with CE-marked neurological panels. Signal to watch: EMA formal recognition of homocysteine as Alzheimer's trial endpoint.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVDR Certification Pathway | Notified body capacity constraints extend timelines for novel assay introductions from EMA-regulated manufacturers. |
| Hospital System Partnership | Integrated delivery network standardization committees mandate preferred vendor relationships across affiliated laboratories. |
| Reimbursement Strategy | Medicare coverage determinations for cardiovascular prevention services dictate volume expansion in outpatient settings. |
| Software Companion Development | Random-access analyzer middleware integration streamlines workflow consolidation onto unified diagnostic platforms. |
| Enzymatic Cycling Scale-Up | Reduced chromatography infrastructure enables mid-tier hospital laboratories to bring homocysteine testing in-house. |
Research Methodology
Coverage spans the United States, Germany, Japan, China, and India, with primary inputs from each market's diagnostic laboratory networks. Conversations with hospital purchasing committee members, clinical laboratory directors, GPO contracts managers, and biomedical engineers combined with FDA 510(k) filings, EMA IVDR documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up reagent volume estimates triangulated against top-down analyzer installed-base calculations.
Rate-of-change decomposition across product type, application, end user, and regional regulatory cluster dimensions shaped the analytical framework. CAGRs derived from segment-level growth trajectories weighted by revenue concentration. Forecast inputs incorporated Medicare preventive screening protocol expansions, IVDR transitional deadline impacts, and neurological biomarker adoption curves at academic medical centers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under notified body capacity constraints and alternative cardiovascular biomarker displacement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Toxicology Testing Services Market
Testing Services
Global Extractables and Leachables Testing Services Market
Testing Services
Irradiation Sterilization Services Market
Testing Services
Global Anti Thrombin III Testing Market
Testing Services
Genetic Toxicology Testing Market
Testing Services
Global Bilirubin Colorimeter Assay Market
Testing Services
Asia-Pacific Antimicrobial Susceptibility Testing Market
Testing Services
Europe Antimicrobial Susceptibility Testing Market
Testing Services
Test Strips Market
Testing Services
Drug Testing Equipment Market
Testing Services
Warfarin Sensitivity Test Market
Testing Services
Active B12 Test Market
Testing Services
Blood Sugar Tester Market
Testing Services
Passive Dosimetry Equipment and Service Market
Testing Services
ATP Assays Market
Testing Services
Biological Indicator Vials Market