
 Iron Deficiency Anemia Treatment Market | 2026-2036
Iron Deficiency Anemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Iron Deficiency Anemia Treatment Market Intelligence
Patient monitoring subscriptions tied to infusion scheduling is realigning how anemia management gets sold. Sanofi leverages its hospital formulary relationships to sustain high-volume ferric derisomaltose positioning. CSL Vifor anchors the nephrology segment through specialized iron portfolio depth. Shield Therapeutics competes on differentiated oral iron delivery that bypasses traditional IV clinic infrastructure.
Iron deficiency anemia treatment encompasses pharmaceutical and transfusion interventions that restore hemoglobin-carrying capacity through elemental iron replacement or red cell supplementation, with IV formulations typically containing 100-1000 mg iron per dose engineered for controlled release kinetics. Oral supplements dominate prescription volume due to accessibility and cost structure, though intravenous iron captures disproportionate value in nephrology and perioperative settings where rapid repletion is clinically mandated. Homecare settings represent the fastest-growing delivery channel as payors push infusion cost away from hospital outpatient departments. Chronic kidney disease applications command premium positioning due to dialysis-linked anemia burden and bundled reimbursement incentives.
FDA bioequivalence standards for complex iron formulations shape generic market entry timelines and reference product exclusivity duration. EMA's pharmacovigilance requirements for hypersensitivity reactions influence IV iron labeling and administration protocols across European markets. WHO prequalification programs for iron-folic acid combinations govern procurement eligibility in low-income health systems. Stakeholders must monitor evolving site-of-care policies and biosimilar iron complex development pipelines to anticipate reimbursement and competitive inflection points.
Market Dynamics
Hospital formulary consolidation and site-of-care migration are compressing traditional IV iron distribution channels while expanding home infusion networks. Bundled reimbursement models for dialysis centers now mandate rapid hemoglobin correction protocols that favor high-dose IV formulations over oral alternatives.
Growth Catalysts
- EMA Pharmacovigilance Framework:Standardized hypersensitivity monitoring requirements across European nephrology clinics have streamlined IV iron administration protocols, reducing clinical hesitation and expanding eligible patient pools.
- Ferric Carboxymaltose Formulation:Single-infusion dosing kinetics enable same-day discharge from outpatient facilities, aligning with payor cost-containment targets and patient preference for reduced clinic visits.
- Chronic Kidney Disease Prevalence:Dialysis-dependent populations in Germany and the United States drive sustained demand for parenteral iron replacement as oral absorption fails in advanced renal impairment.
Market Restraints
- API Supply Concentration:Elemental iron complex manufacturing clusters in Chinese pharmaceutical zones create single-source dependency risks for European and North American formulation facilities.
- FDA Bioequivalence Complexity:Physicochemical characterization requirements for iron carbohydrate complexes extend generic development timelines and sustain reference product pricing power.
- Oral Iron Substitution:Ferrous bisglycinate and other gastrointestinal-tolerable oral salts retain first-line status in non-dialysis anemia, limiting IV penetration in primary care settings.
Strategic Opportunities
- Home Infusion Channel Expansion:Specialty pharmacy networks in the United States are capturing hospital outpatient department volume as payors mandate site-neutral reimbursement for non-complex iron infusions.
- Perioperative Anemia Protocols:Enhanced recovery after surgery programs in German and Austrian hospitals now mandate preoperative iron repletion, creating procedural demand outside nephrology.
- WHO Prequalification Pathway:Iron-folic acid combination products eligible for low-income country procurement programs open volume markets with distinct formulation and packaging requirements.
Industry Challenges
- Infusion Nursing Workforce Scarcity:Homecare expansion strains certified vascular access specialists, creating scheduling bottlenecks that limit patient throughput regardless of product availability.
- Hypersensitivity Risk Management:Anaphylaxis monitoring protocols require 30-minute post-infusion observation periods that constrain clinic capacity and complicate same-day scheduling logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iron Deficiency Anemia Treatment Market |
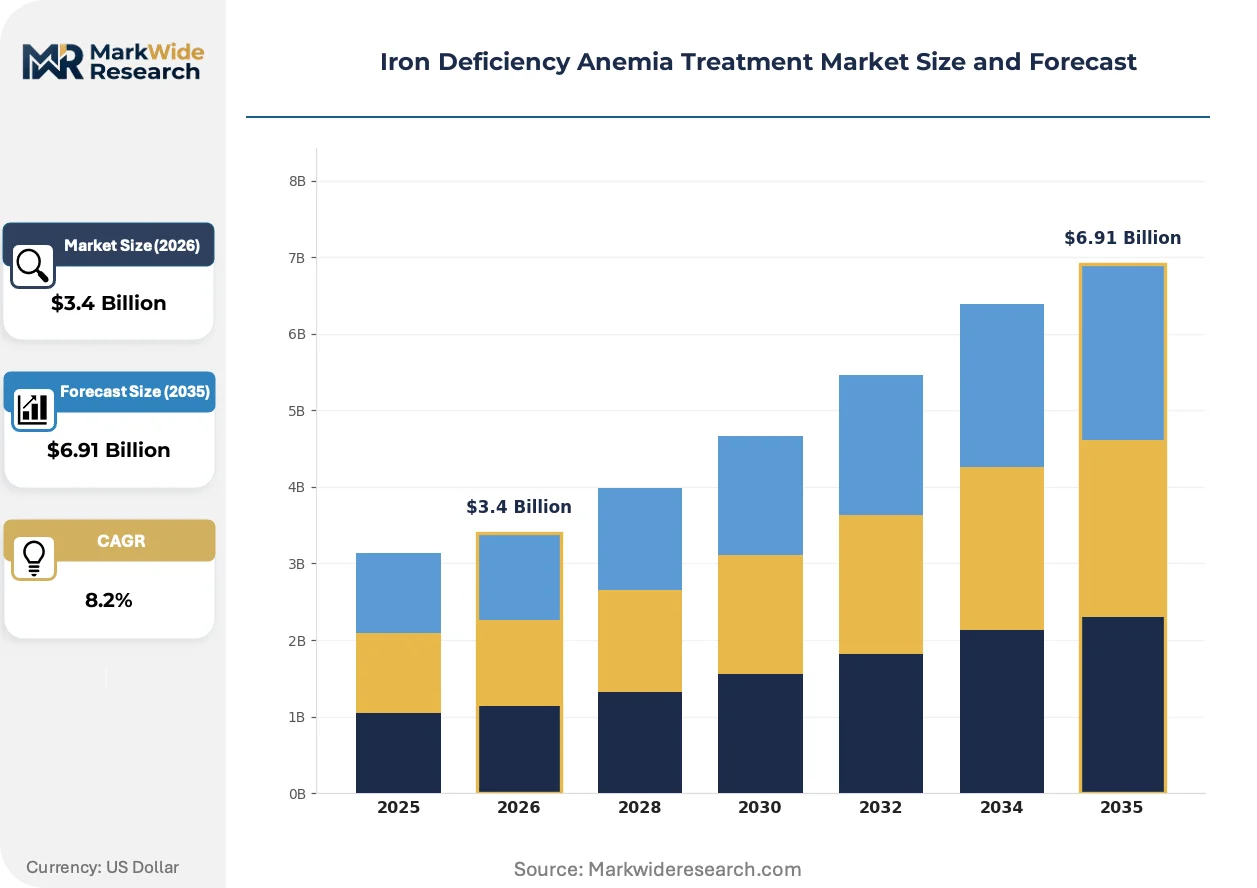
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.91 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Supplements, Intravenous Iron, Dietary Sources, Blood Transfusions End User: Hospitals, Clinics, Homecare Settings, Pharmacies Application: Chronic Kidney Disease, Pregnancy, Malnutrition, Menstrual Disorders Delivery Mode: Injectable, Oral, Transfusion, Infusion |
| Companies Covered | Shield Therapeutics, Sanofi, CSL Vifor, Teva Pharmaceuticals, AbbVie, Akebia Therapeutics, Pharmacosmos Therapeutics, Johnson & Johnson, AMAG Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iron Deficiency Anemia Treatment Market Strategic Shifts & Innovations
Formulation science and administration logistics are converging to compress treatment cycles and displace facility-based care. These developments favor products engineered for rapid repletion with minimal clinical infrastructure.
Controlled-release iron nanoparticle suspensions are rewriting the pharmacokinetic profile of IV replacement therapy. Nephrology clinics in Germany and the United States are adopting these formulations for patients with prior intolerance to older iron dextran complexes. The technology is compressing total correction timelines from multiple infusions to single-visit protocols.
REACH authorization requirements for pharmaceutical excipients are tightening impurity thresholds for iron complex manufacturing inputs. European formulation facilities must now document full supply chain chemistry for carbohydrate ligands used in ferric carboxymaltose production. German manufacturers are responding by qualifying domestic excipient suppliers to reduce regulatory exposure.
Site-neutral payment mandates from US commercial payors are accelerating disintermediation of hospital outpatient departments. Specialty pharmacy infusion suites and home health nursing networks are capturing iron administration volume previously captive to hospital systems. This channel rotation is most advanced in Medicare Advantage populations where capitated contracts reward care migration to lower-cost settings.
Iron Deficiency Anemia Treatment Market Segmentation
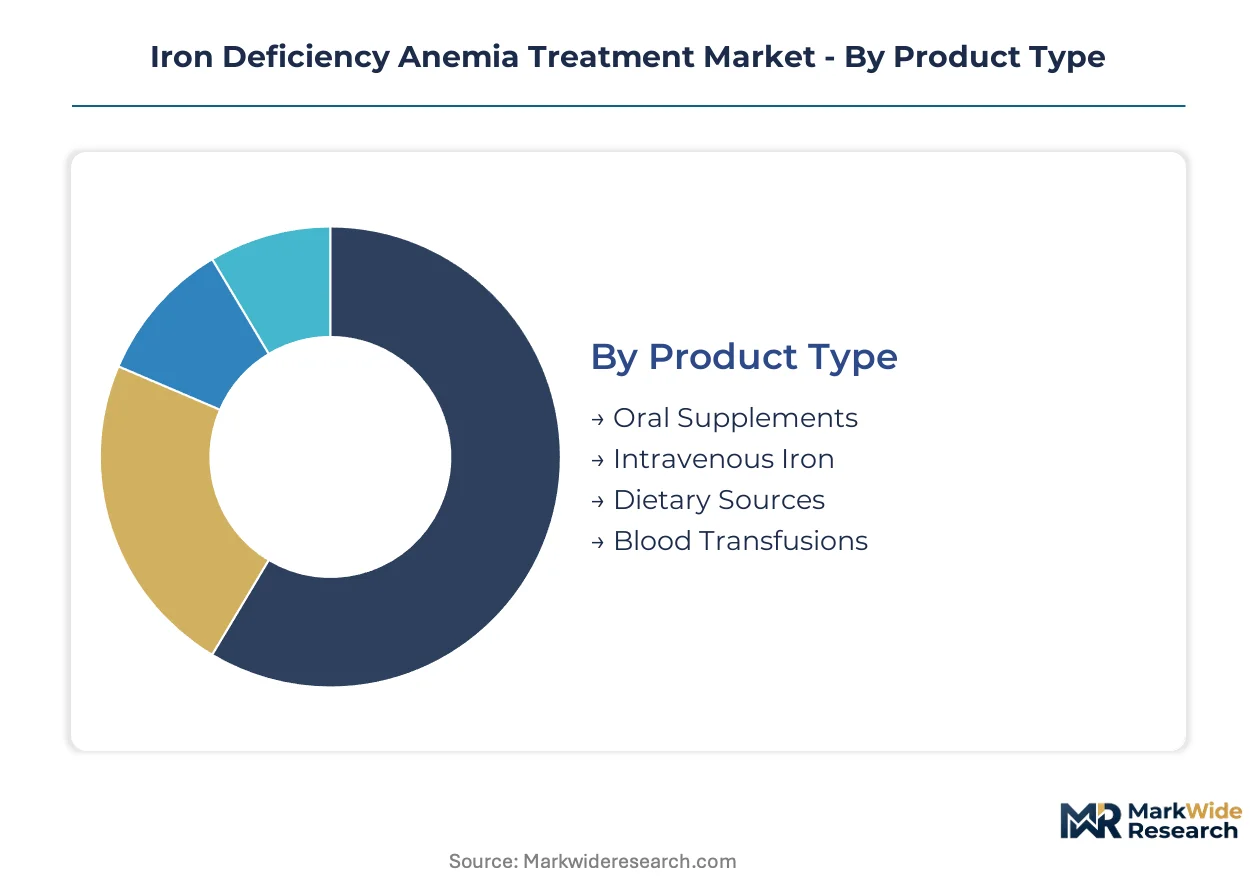
Iron deficiency anemia treatment markets fragment along therapeutic intensity and care setting axes. Product form, delivery logistics, and clinical indication each reshape procurement patterns and margin structures across patient populations.
Product Type:
Clinical severity and reimbursement bundling drive product selection more than price sensitivity alone.
- Intravenous Iron:Complex carbohydrate-encapsulated ferric salts engineered for controlled release kinetics. German nephrology clinics and US dialysis centers favor high-dose IV formulations where oral absorption fails and rapid hemoglobin correction is mandated by bundled payment protocols.
- Oral Supplements:Ferrous salts and amino acid chelates formulated for gastrointestinal tolerability. Primary care settings in non-dialysis anemia rely on oral first-line protocols, though adherence gaps persist due to side effect profiles.
- Dietary Sources:Fortified food matrices and nutritional interventions addressing mild deficiency states.
- Blood Transfusions:Allogeneic red cell replacement reserved for acute hemorrhagic or severe symptomatic cases.
Intravenous iron leads on scale; oral supplements lead on prescription volume momentum.
End User:
Site-of-care economics and nursing capacity constraints are redistributing patient volume across facility types.
- Homecare Settings:Specialty pharmacy networks and visiting nurse services administering non-complex iron infusions. US Medicare Advantage capitation and commercial payor site-neutral mandates are accelerating migration from hospital outpatient departments.
- Hospitals:Academic medical centers and community hospital systems managing perioperative anemia protocols and transfusion-dependent cases. German hospitals are expanding ferric carboxymaltose protocols for surgical prehabilitation programs.
- Clinics:Nephrology and hematology ambulatory practices with dedicated infusion capacity.
- Pharmacies:Retail and specialty pharmacy channels dispensing oral supplements and coordinating home infusion logistics.
Hospitals lead on acute case complexity; homecare settings gain share fastest through channel migration.
Application:
Disease burden severity and treatment urgency determine reimbursement tier and product positioning.
- Chronic Kidney Disease:Dialysis-dependent anemia requiring parenteral iron replacement due to erythropoietin-stimulating agent co-therapy and gut absorption impairment. US dialysis centers operate under ESRD bundled payment incentives that reward rapid hemoglobin correction.
- Pregnancy:Gestational iron deficiency protocols balancing maternal hemodynamic demands with fetal safety profiles.
- Malnutrition:Deficiency states complicating chronic disease or socioeconomic deprivation.
- Menstrual Disorders:Heavy menstrual bleeding driving iron loss and replacement needs in premenopausal populations.
Chronic kidney disease anchors revenue concentration; pregnancy applications show steepest protocol expansion trajectory.
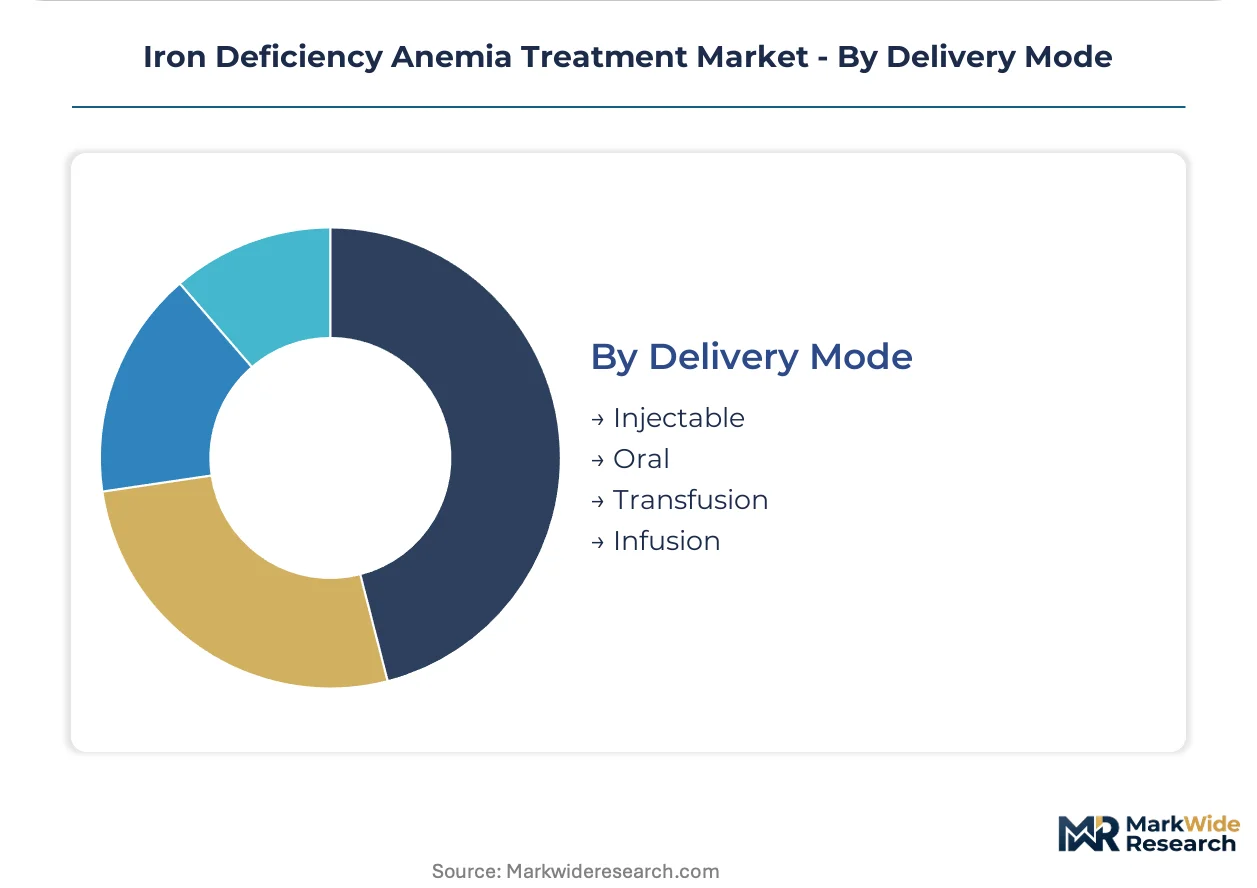
Delivery Mode:
Administration infrastructure requirements and pharmacokinetic targets shape modality selection.
- Infusion:Controlled-rate parenteral delivery of iron carbohydrate complexes requiring vascular access and hypersensitivity monitoring. German and US nephrology clinics are consolidating around single-infusion ferric carboxymaltose protocols.
- Injectable:Intramuscular or subcutaneous depot formulations for selected patient populations.
- Oral:Self-administered tablet and liquid preparations dominating ambulatory non-dialysis care.
- Transfusion:Allogeneic blood component therapy for hemodynamically unstable patients.
Infusion leads on value capture; oral delivery retains volume dominance through accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States demonstrate contrasting reimbursement architectures for parenteral iron, with German nephrology clinics favoring single-infusion protocols while US dialysis centers navigate bundled payment incentives. These divergent policy environments reshape how manufacturers position high-dose formulations across developed markets.
United States
Dialysis-dependent populations in the US drive concentrated demand for IV iron replacement, with Medicare Advantage capitation accelerating site-of-care migration from hospital outpatient departments to specialty pharmacy networks. FDA bioequivalence guidance for iron carbohydrate complexes sustains reference product exclusivity timelines. The Dallas-Fort Worth metroplex anchors expanding home infusion capacity as payors mandate cost-neutral reimbursement across settings.
Germany
Nephrology clinics in Bavaria and North Rhine-Westphalia have adopted ferric carboxymaltose as first-line IV therapy for chronic kidney disease patients, compressing treatment cycles from multiple visits to single-infusion protocols. EMA pharmacovigilance requirements for hypersensitivity reactions standardize administration monitoring across outpatient facilities. The Munich medical corridor concentrates formulation manufacturing and clinical trial infrastructure for next-generation iron complexes.
China
Rising chronic disease burden and expanding health insurance coverage for parenteral iron drive volume growth in tier-one hospital nephrology departments. NMPA regulatory pathways for complex iron formulations extend development timelines compared to small-molecule generics. The Yangtze River Delta pharmaceutical cluster, centered on Shanghai and Suzhou, hosts active ingredient manufacturing for ferric salts supplying domestic formulation facilities.
India
Widespread iron deficiency anemia among women and children sustains oral supplement volume, while dialysis center expansion in metropolitan areas creates emerging IV iron demand. CDSCO registration requirements for imported iron complexes govern market entry timelines for multinational manufacturers. The Hyderabad-Visakhapatnam pharmaceutical corridor houses formulation facilities serving both domestic consumption and WHO prequalification pathways for iron-folic acid combinations.
United Kingdom
NHS England's perioperative anemia protocols mandate preoperative iron repletion for elective surgical pathways, creating procedural demand outside traditional nephrology settings. MHRA alignment with EMA pharmacovigilance standards shapes IV iron labeling and administration requirements. The Greater Manchester health innovation cluster pilots home infusion models for non-complex iron administration, testing site-of-care migration at scale.
Iron Deficiency Anemia Treatment Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with hospital formulary relationships determining access in nephrology while retail pharmacy networks govern oral supplement distribution. The market structures around three tiers: multinational pharmaceutical conglomerates with nephrology portfolio depth, mid-cap specialists in IV formulation science, and generic manufacturers competing on oral iron cost positioning. Dominant competitive moves include strategic partnerships with dialysis provider networks and geographic expansion of home infusion service capabilities.
Within the branded specialist tier, Shield Therapeutics occupies a position exemplifying differentiated oral delivery approaches that bypass traditional IV infrastructure. Sanofi and CSL Vifor anchor the parenteral iron segment, representing contrasting strategic archetypes—Sanofi through hospital formulary integration and CSL Vifor through nephrology-focused portfolio concentration. These three companies collectively illustrate how competitive positioning diverges across administration modalities and care settings.
| Leading Market Players |
|---|
| Shield Therapeutics |
| Sanofi |
| CSL Vifor |
| Teva Pharmaceuticals |
| AbbVie |
| Akebia Therapeutics |
| Pharmacosmos Therapeutics |
| Johnson & Johnson |
| AMAG Pharmaceuticals |
| Others |
Cost & Logistics Intelligence
Certified vascular access specialists concentrated in the Dallas-Fort Worth metroplex and Munich medical corridor command wage premiums that compress margins in home infusion tiers while expanding spreads between hospital outpatient and specialty pharmacy pricing. Labor-cost differentials between these nursing workforce clusters and secondary markets in India and Eastern Europe feed directly into three-tier pricing stratification across premium IV formulations, standard oral supplements, and economy-grade ferrous salts.
Pricing Analysis
Capacity additions in China's Yangtze River Delta pharmaceutical cluster are reshaping price floors for elemental iron API, pressuring margin structures for European and North American formulation facilities. The market operates through contract-based long-term offtake for hospital systems and spot purchasing for retail pharmacy channels, with price differentiation hinging on FDA bioequivalence certification tier and volume scale commitments. Cost compression in the oral supplement tier is intensifying as Indian generic manufacturers expand ferrous bisglycinate output. Dialysis centers exhibit lowest price sensitivity due to bundled reimbursement incentives, while primary care settings remain most responsive to out-of-pocket cost differentials.
Supply Chain Analysis
Single-source vulnerability sits with Chinese pharmaceutical zones for iron carbohydrate complex active ingredients, creating concentration risk for ferric carboxymaltose and ferric derisomaltose manufacturing. Formulation facilities in Germany, the United States, and India draw from these API clusters, with downstream distribution running through hospital GPO contracts, specialty pharmacy networks, and retail pharmacy chains. REACH authorization requirements for carbohydrate ligand excipients impose regulatory friction that limits supplier switching. Logistics chokepoints at Shanghai port and Rotterdam container terminals compound lead time volatility for just-in-time infusion center inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between German nephrology clinics operating under EMA pharmacovigilance frameworks and US dialysis centers navigating site-neutral reimbursement mandates creates divergent margin pools for identical ferric carboxymaltose formulations, rewarding manufacturers with regulatory pathway expertise in both jurisdictions.
For Market Incumbents: Lock in hospital formulary positioning through dedicated iron portfolio depth and specialized nephrology sales forces that CSL Vifor and Sanofi have established. Defend against oral iron substitution threats by expanding home infusion service capabilities that bypass traditional IV clinic infrastructure. Capacity additions in the Munich medical corridor strengthen supply security for European reference products facing REACH compliance costs. For New Entrants and Emerging Players: Controlled-release iron nanoparticle suspensions offer a technology-first wedge into the perioperative anemia protocol segment outside traditional nephrology strongholds. Target NHS England's surgical prehabilitation programs and German hospital enhanced recovery after surgery initiatives where rapid repletion requirements favor innovative delivery kinetics. A go-to-market angle centered on same-day discharge protocols aligns with payor cost-containment targets in both markets. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap IV formulation specialists with nephrology concentration but limited homecare channel infrastructure. The five-to-ten year viability window favors manufacturers building site-of-care migration capabilities ahead of Medicare Advantage capitation expansion. WHO prequalification pathway progress for iron-folic acid combinations signals emerging market volume inflection worth monitoring.| Strategic Initiative | Industry Significance |
|---|---|
| Home Infusion Channel Expansion | Specialty pharmacy networks in Medicare Advantage populations capture hospital outpatient volume under site-neutral mandates. |
| REACH Excipient Supplier Qualification | German manufacturers reduce regulatory exposure by sourcing carbohydrate ligands from domestic qualified vendors. |
| Perioperative Anemia Protocol Integration | NHS England and German hospital mandates create procedural demand outside dialysis-dependent populations. |
| Hypersensitivity Monitoring Standardization | EMA pharmacovigilance frameworks streamline IV iron administration protocols across European nephrology clinics. |
| WHO Prequalification Pathway Pursuit | Iron-folic acid combination eligibility opens procurement access in low-income health systems with distinct packaging requirements. |
Research Approach
Bottom-up nephrology clinic and dialysis center modeling reconciled against top-down API manufacturing and formulation facility tracking forms the analytical core of this study. Primary interviews with hospital formulary directors, nephrology department heads, specialty pharmacy procurement managers, and home infusion nursing coordinators combined with secondary validation against FDA bioequivalence guidance documents, EMA pharmacovigilance reports, CMS Medicare reimbursement databases, and WHO prequalification listings. Triangulation between patient volume estimates from clinical trial registries and production capacity disclosures from pharmaceutical manufacturing clusters ensures consistency across supply and demand dimensions.
Input-output matrices map iron deficiency anemia treatment demand across product type, end user, application, and delivery mode segments, with growth trajectories derived from procedure volume elasticity to chronic kidney disease prevalence and surgical protocol adoption rates. The projection horizon incorporates dialysis center expansion in tier-one Chinese hospitals, Medicare Advantage penetration in US commercial payor markets, and NHS perioperative anemia protocol rollout timelines. Industry-specific forecast inputs include erythropoietin-stimulating agent co-therapy rates and bundled reimbursement incentive structures that mandate rapid hemoglobin correction protocols.
The model holds under stable regulatory frameworks for iron complex bioequivalence and hypersensitivity monitoring; deviation in FDA guidance timelines or REACH excipient authorization thresholds would shift generic entry assumptions and manufacturing cost structures. Forecasts reflect documented assumptions regarding site-of-care migration velocity and nursing workforce expansion constraints. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Peanut Allergy Treatment Market
Medical Treatment
Histiocytosis Treatment Market
Medical Treatment
Anemia Treatment Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
North America Breast Reconstruction Market
Medical Treatment
Europe Nerve Repair and Regeneration Market
Medical Treatment
Encephalitis Treatment Market
Medical Treatment
Influenza Treatment Market
Medical Treatment
Severe Asthma Treatment Market
Medical Treatment
Behcet's Disease Treatment Market
Medical Treatment
Global Hyperhidrosis Treatment Market
Medical Treatment
Scoliosis Management Market
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Cysticercosis (Taeniasis) Treatment Market
Medical Treatment
Laser Therapy Market
Medical Treatment
Nose Reconstruction Market