
 Global Hyperhidrosis Treatment Market | 2026-2036
Global Hyperhidrosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hyperhidrosis Treatment Market Foresight
Combination therapy bundling is consolidating treatment protocols across dermatology practices, merging topical regimens with device-based maintenance to improve patient retention and clinic throughput. AbbVie Inc. leverages its neuromodulator portfolio to anchor premium positioning in axillary and palmar segments. Eli Lilly and Company sustains R&D intensity across novel anticholinergic mechanisms. Dermavant Sciences Inc. specializes in topical formulation innovation for craniofacial presentations.
Hyperhidrosis treatment encompasses pharmacological, device-based, and surgical interventions targeting eccrine gland overactivity through anticholinergic blockade, chemodenervation, iontophoretic ion delivery, or glandular ablation, with botulinum toxin serotype A formulations typically dosed at 50 units per axilla. The primary purpose is restoring functional and social capacity for patients with focal or generalized sweating disorders. Injectable botulinum toxin occupies the highest margin pool due to recurring treatment cycles and physician-administered delivery. Iontophoresis devices compete on cumulative cost efficiency for palmar and plantar cases. Topical agents lead prescription volume in mild-to-moderate axillary cases across outpatient channels.
The FDA regulates botulinum toxin products under biologics licensing requirements with specific indication constraints, while the EU MDR reclassifies active therapeutic devices and intensifies clinical evidence standards for iontophoresis systems. Japan's PMDA maintains distinct approval pathways for imported neuromodulators that delay market entry relative to Western timelines. Stakeholders must monitor regulatory divergence across FDA, EMA, and PMDA frameworks when prioritizing geographic launch sequencing and clinical trial investment.
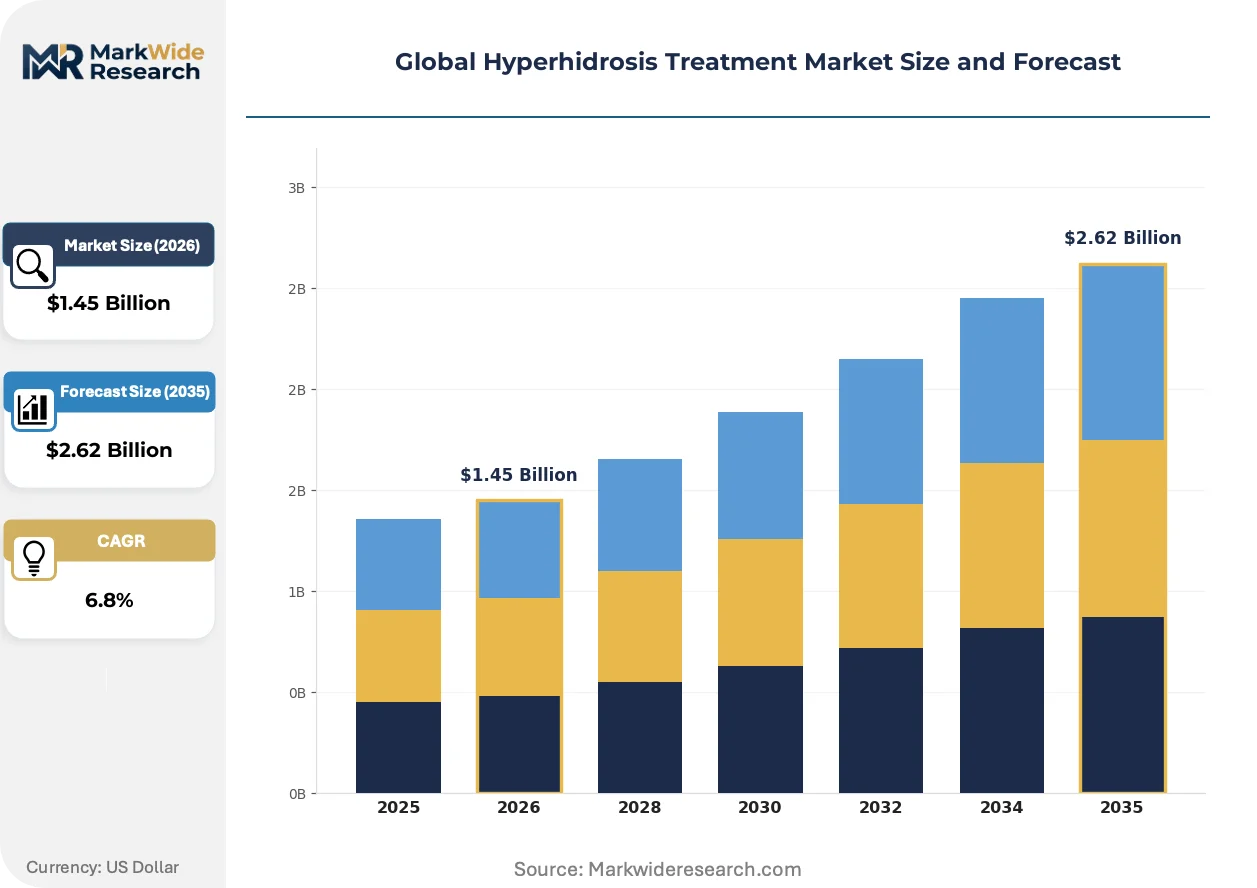
Market Dynamics
Device-based maintenance protocols are consolidating treatment economics across dermatology practices, compressing the traditional dominance of injectable neuromodulators through bundled service offerings that improve clinic throughput and patient retention cycles.
Growth Catalysts
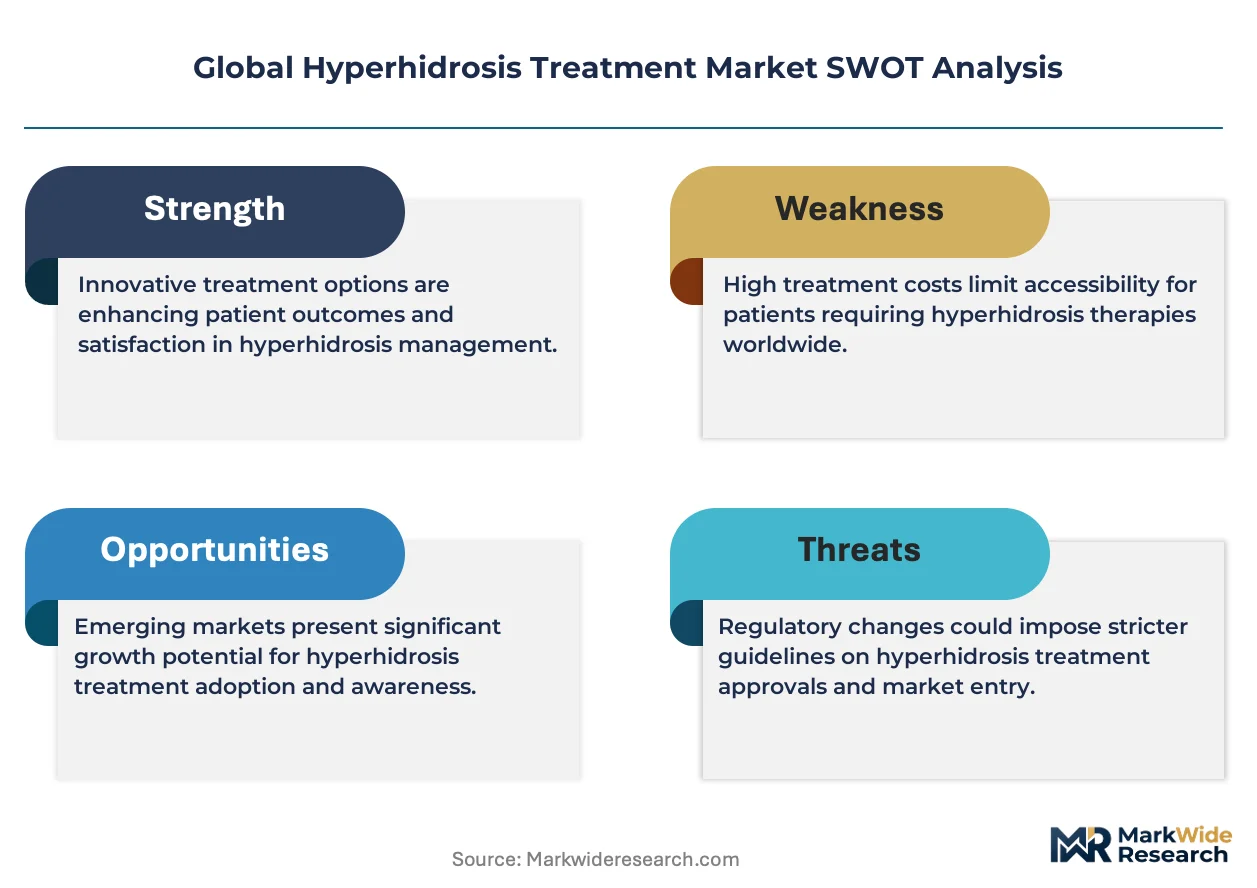
- EU MDR reclassification:The EU Medical Device Regulation intensifies clinical evidence standards for iontophoresis systems, accelerating quality differentiation and premium positioning among compliant manufacturers.
- Aesthetic medicine infrastructure:Dermatology clinics in Germany, Japan, and the United States are expanding device-based and injectable service lines to capture recurring revenue from focal hyperhidrosis presentations.
- Botulinum toxin indication expansion:FDA guidance evolution on neuromodulator indications is broadening reimbursable treatment sites beyond axillary to palmar and craniofacial segments.
Market Restraints
- High capital intensity of surgical ablation:Endoscopic thoracic sympathectomy requires specialized surgical infrastructure and carries compensatory hyperhidrosis risks that limit adoption to refractory cases.
- Supply concentration in toxin manufacturing:Fermentation-based botulinum toxin production concentrates among a limited supplier base, creating vulnerability to batch variability and capacity constraints.
- Anticholinergic systemic limitations:Oral glycopyrrolate and oxybutynin face tolerability ceilings from dry mouth and urinary retention that cap dose escalation in generalized hyperhidrosis.
Strategic Opportunities
- Underpenetrated plantar segment:Iontophoresis device manufacturers can target the plantar presentation where injectable toxin administration remains technically challenging and painful for patients.
- Topical formulation innovation:Novel anticholinergic creams and wipes offer physician-dispensed alternatives that bypass pharmacy benefit manager friction in the United States outpatient channel.
- Japan PMDA pathway optimization:Streamlined approval timelines for imported neuromodulators would accelerate market entry relative to historical Western lag patterns.
Industry Challenges
- Injection technique standardization:Consistent intradermal botulinum toxin delivery across axillary, palmar, and plantar sites requires specialized training that fragments treatment quality.
- Device reimbursement coding:Iontophoresis systems face heterogeneous coverage determinations across US commercial payers and Medicare Advantage plans, complicating patient access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hyperhidrosis Treatment Market |
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anticholinergics, Botulinum Toxin, Iontophoresis Devices, Surgical Solutions, Topical Agents Application: Axillary Hyperhidrosis, Palmar Hyperhidrosis, Plantar Hyperhidrosis, Craniofacial Hyperhidrosis, Generalized Hyperhidrosis End User: Dermatology Clinics, Specialty Centers, Ambulatory Surgery Centers, Academic Hospitals, Outpatient Clinics Treatment Delivery Mode: Injectable, Oral, Topical, Device-Based, Surgical Intervention |
| Companies Covered | AbbVie Inc., Eli Lilly and Company, Dermavant Sciences Inc., Kaken Pharmaceutical Co., Ltd., Hugel, Inc., Intas Pharmaceuticals Ltd., Avanor Healthcare Ltd., Dermadry Laboratories Inc., Brickell Biotech Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hyperhidrosis Treatment Market Shifts & Advancements
Combination therapy bundling is actively compressing standalone treatment economics, merging topical regimens with device-based maintenance to create stickier patient relationships and defensible clinic revenue streams.
Microwave-based glandular ablation technology is rewriting competitive positioning in the axillary segment. Dermatology practices in metropolitan United States markets are adopting these systems at accelerating pace. This modality is enabling procedure-based revenue capture that rivals injectable toxin cycles while reducing dependence on pharmaceutical supply chains.
The EU Medical Device Regulation intensification is reshaping clinical evidence requirements for active therapeutic devices. Manufacturers must now generate prospective data on iontophoresis efficacy and safety that exceeds historical predicate device standards. European dermatology device suppliers are responding by consolidating trial investments across Germany and France to achieve MDR certification ahead of competitor timelines.
Patient self-administration preferences are fragmenting traditional clinic-dependent models. Direct-to-consumer iontophoresis device sales through specialty medical retailers are displacing physician-mediated procurement in palmar and plantar cases. This shift is most visible in East Asian urban centers where aesthetic medicine infrastructure supports hybrid care pathways blending professional diagnosis with home-based maintenance.
Global Hyperhidrosis Treatment Market Segmentation
Hyperhidrosis treatment segmentation reveals distinct economic profiles across delivery mechanisms and anatomical targets. Product type stratification separates recurring pharmaceutical revenue from capital-intensive device and surgical modalities. Application-based segmentation exposes underpenetrated anatomical sites where technical barriers limit competitive entry.
Product Type:
Buyers in this category differentiate by treatment durability and clinic infrastructure requirements, with recurring revenue models commanding premium valuation multiples against one-time surgical procedures.
- Botulinum Toxin:Purified neurotoxin formulations derived from Clostridium botulinum fermentation, typically stabilized with human serum albumin or polysorbant excipients. Demand concentrates in metropolitan United States dermatology practices where physician-administered injection cycles generate recurring revenue streams and patient retention protocols.
- Iontophoresis Devices:Battery-powered or mains-connected systems delivering ionic current through tap water reservoirs to temporarily block eccrine gland secretion. Adoption accelerates in German and Japanese outpatient settings where patients self-administer maintenance protocols after initial clinical training, reducing per-treatment labor costs.
- Anticholinergics:Systemic agents including glycopyrrolate and oxybutynin targeting muscarinic acetylcholine receptors.
- Surgical Solutions:Endoscopic thoracic sympathectomy and localized glandular excision procedures.
- Topical Agents:Aluminum chloride formulations and emerging anticholinergic creams for mild-to-moderate presentations.
Botulinum toxin leads volumes today; iontophoresis devices are gaining share fastest.
Application:
Anatomical site selection drives reimbursement coding complexity and treatment modality suitability, with craniofacial and plantar presentations creating technical barriers that fragment competitive dynamics.
- Axillary Hyperhidrosis:Underarm presentations constitute the most clinically validated indication with established botulinum toxin dosing protocols at 50 units per axilla. United States metropolitan markets dominate procedural volume due to favorable FDA labeling and commercial payer coverage determinations.
- Palmar Hyperhidrosis:Hand presentations require precise intradermal injection technique or iontophoresis maintenance due to dense sensory innervation. Japanese dermatology clinics report highest iontophoresis penetration rates where patient self-administration preferences reduce clinical dependency.
- Plantar Hyperhidrosis:Foot presentations remain technically challenging for injectable delivery due to pain tolerance thresholds and skin thickness.
- Craniofacial Hyperhidrosis:Scalp and facial sweating with limited approved pharmacological interventions.
- Generalized Hyperhidrosis:Whole-body presentations typically managed with systemic anticholinergics rather than localized interventions.
Axillary applications dominate current revenue; plantar presentations show steepest expansion trajectory as device manufacturers target underserved technical barriers.
End User:
Facility type determines capital equipment purchasing authority and reimbursement pathway complexity, with integrated health systems favoring bundled service contracts over standalone device procurement.
- Dermatology Clinics:Private practice and group settings with direct patient relationships and aesthetic medicine cross-selling capabilities. German clinic chains in Munich and Hamburg are consolidating iontophoresis device fleets to standardize maintenance protocols across regional networks.
- Specialty Centers:Dedicated hyperhidrosis and sweat disorder facilities with concentrated procedural expertise.
- Ambulatory Surgery Centers:Outpatient surgical facilities with endoscopic thoracic sympathectomy capabilities.
- Academic Hospitals:Teaching institutions with research protocols and trainee education missions.
- Outpatient Clinics:General medical settings with limited specialized equipment.
Dermatology clinics capture the majority of non-surgical volume today; specialty centers are expanding most quickly as destination models concentrate expertise.
Treatment Delivery Mode:
Route of administration shapes patient compliance profiles and regulatory pathway requirements, with invasive modalities carrying distinct FDA biologics licensing versus EU MDR device classification frameworks.
- Injectable:Intradermal and subcutaneous delivery requiring sterile technique and anatomical expertise. United States practices leverage this mode for premium positioning despite supply concentration risks in fermentation-based manufacturing.
- Device-Based:Electromechanical systems including iontophoresis and microwave ablation technologies. EU MDR reclassification is intensifying clinical evidence requirements for European market access.
- Topical:Patient-applied formulations with lower barriers to initiation but adherence challenges.
- Oral:Systemic pharmacological delivery with dose-limiting anticholinergic side effects.
- Surgical Intervention:Definitive glandular or sympathetic nerve disruption with irreversible outcomes.
Injectable delivery generates highest revenue per patient today; device-based modalities are climbing the fastest as home-use configurations expand addressable populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The hyperhidrosis treatment industry traces its commercial origins to botulinum toxin development in the United States and subsequent device innovation across German and Japanese dermatology markets. These three countries established the foundational infrastructure for injectable neuromodulators and iontophoresis systems that now define global treatment protocols.
United States
FDA labeling for botulinum toxin axillary indications and commercial payer coverage determinations drive metropolitan procedural volume. The agency's evolving guidance on palmar and craniofacial expansion broadens reimbursable treatment sites. Dermatology practices in New York, Los Angeles, and Miami concentrate device-based and injectable service lines to capture recurring revenue from focal presentations.
Germany
EU Medical Device Regulation intensification accelerates quality differentiation among iontophoresis manufacturers seeking MDR certification. The regulation's clinical evidence standards exceed historical predicate device requirements. Clinic chains in Munich and Hamburg consolidate device fleets to standardize maintenance protocols across regional networks.
Japan
PMDA maintains distinct approval pathways for imported neuromodulators that delay market entry relative to Western timelines. Patient self-administration preferences reduce clinical dependency in palmar cases. Tokyo and Osaka dermatology clinics report highest iontophoresis penetration rates where hybrid care pathways blend professional diagnosis with home-based maintenance.
United Kingdom
NICE technology appraisals and NHS commissioning frameworks shape access to botulinum toxin therapies for severe axillary cases. Private aesthetic medicine infrastructure in London and Manchester expands device-based service offerings. The Medicines and Healthcare products Regulatory Agency aligns with EMA guidance on neuromodulator safety monitoring.
South Korea
MFDS approval pathways for medical devices support domestic iontophoresis manufacturing alongside imported toxin formulations. Aesthetic medicine clusters in Seoul and Busan integrate hyperhidrosis treatment into broader cosmetic dermatology portfolios. The regulator's streamlined device classification accelerates market entry for novel electromechanical systems.
Global Hyperhidrosis Treatment Market Competitive Landscape
The competitive structure tilts toward pharmaceutical neuromodulator specialists with fermentation-based manufacturing capabilities and device manufacturers pursuing MDR compliance premiums. Three archetypes dominate: established biologics licensors with toxin portfolios, topical formulation innovators targeting outpatient channels, and electromechanical device suppliers competing on cumulative cost efficiency. Capacity expansion in German and Japanese device manufacturing and strategic partnerships between toxin suppliers and dermatology clinic networks represent the dominant competitive moves.
Within the biologics-specialist tier, AbbVie Inc. and Eli Lilly and Company exemplify the R&D-intensive archetype anchoring premium positioning in injectable segments. Dermavant Sciences Inc. occupies a distinct position among topical formulation innovators. Kaken Pharmaceutical Co., Ltd. and Hugel, Inc. represent the Asia-Pacific geographic concentration of neuromodulator development. Intas Pharmaceuticals Ltd. and Avanor Healthcare Ltd. sit within the diversified pharmaceutical manufacturing segment. Dermadry Laboratories Inc. exemplifies the device-manufacturing archetype competing on home-use accessibility.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Eli Lilly and Company |
| Dermavant Sciences Inc. |
| Kaken Pharmaceutical Co., Ltd. |
| Hugel, Inc. |
| Intas Pharmaceuticals Ltd. |
| Avanor Healthcare Ltd. |
| Dermadry Laboratories Inc. |
| Brickell Biotech Inc. |
| Others |
Supply & Pricing Matrix
Patient self-administration preferences in Japan and Germany are compressing clinic-dependent procurement models and forcing device manufacturers to restructure downstream economics around direct-to-consumer channels. This shift redraws margin capture away from physician-mediated distribution toward specialty medical retailers and hybrid care platforms.
Pricing Analysis
Recurring revenue models anchored to botulinum toxin injection cycles command premium positioning against one-time capital equipment sales. Price differentiation rests on FDA labeling tier and EU MDR certification status, with compliant manufacturers capturing margin premiums. Pricing pressure stems from iontophoresis device commoditization in East Asian markets. Dermatology clinics show highest price sensitivity; academic hospital systems demonstrate lowest.
Supply Chain Analysis
Freight cost volatility for temperature-controlled botulinum toxin shipments from United States and European fermentation facilities elevates landed cost in Asia-Pacific markets. Manufacturing concentrates in United States, Ireland, and South Korea. Raw material dependencies include Clostridium botulinum seed stocks, pharmaceutical-grade excipients, and iontophoresis electrode metals. Single-source vulnerability in toxin fermentation capacity feeds distribution through specialty pharmaceutical wholesalers and direct clinic contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR compliance investments in Germany create regulatory moats that Japanese and South Korean device manufacturers must replicate at higher cost to access European clinic networks.
For Market Incumbents: Anchor premium positioning through backward integration into fermentation capacity and captive supply of botulinum toxin serotypes. Defend against microwave ablation substitution by bundling injectable protocols with maintenance device placements. Prioritize EU MDR certification ahead of competitor timelines to lock in German clinic chain procurement. For New Entrants and Emerging Players: Novel anticholinergic cream formulations offer a technology-first wedge against oral systemic agents with dose-limiting tolerability ceilings. Target the plantar presentation where injectable delivery remains technically challenging and iontophoresis penetration lags axillary adoption. Pursue physician-dispensed models that bypass United States pharmacy benefit manager friction. For Investors and Strategic Acquirers: Asymmetric upside sits with topical formulation specialists possessing dermatology channel relationships and pipeline assets in craniofacial indications. Long-term viability favors platforms spanning device and pharmaceutical modalities rather than single-mechanism exposure. Watch FDA guidance evolution on palmar and craniofacial toxin indications as inflection signal for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Accelerates German clinic network access ahead of non-compliant competitors. |
| Combination Therapy Bundling | Merges toxin injection cycles with iontophoresis maintenance to improve retention. |
| Direct-to-Consumer Channel Launch | Captures Japanese patient self-administration preferences reducing clinical dependency. |
| Topical Formulation Pipeline Expansion | Targets craniofacial presentations with limited approved pharmacological interventions. |
| Hospital System Partnership | Secures formulary placement for systemic anticholinergics in generalized cases. |
Research Methodology
Bottom-up dermatology clinic throughput modeling reconciled against top-down pharmaceutical and device shipment tracking forms the analytical core. Primary interviews with regulatory affairs leads, hospital procurement managers, GPO contracts managers, and formulary directors combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases. Cross-referencing bottom-up patient flow estimates with top-down manufacturer revenue disclosures ensures segmentation integrity.
Input-output matrices map treatment modality adoption rates against anatomical site prevalence and reimbursement pathway accessibility across the projection horizon. Segmentation dimensions include product type, application site, end-user facility, and treatment delivery mode. CAGRs derive from logistic diffusion curves fitted to historical adoption patterns and adjusted for regulatory milestone probabilities. Forecast inputs incorporate PMDA approval timeline differentials and EU MDR compliance cost pass-through assumptions.
The model holds under stable regulatory frameworks and intact reimbursement coding; deviation in FDA indication expansion timing or EU MDR enforcement intensity would shift volume trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Andersen Tawil Syndrome Treatment Market
Medical Treatment
Japan Radiotherapy Market
Medical Treatment
Hemorrhagic Shock Treatment Market
Medical Treatment
Lice Treatment Market
Medical Treatment
CINV Treatment Market
Medical Treatment
Dengue Fever Treatment Market
Medical Treatment
Nasopharyngeal Carcinoma Treatment Market
Medical Treatment
Global Uterine Fibroids Treatment Market
Medical Treatment
Cervical Cancer Treatment Market
Medical Treatment
Basal Cell Carcinoma Treatment Market
Medical Treatment
Tauopathies Treatment Market
Medical Treatment
Urea Cycle Disorders Treatment Market
Medical Treatment
Trauma and Extremities Market
Medical Treatment
Yellow Fever Treatment Market
Medical Treatment
Systemic Mastocytosis Treatment Market
Medical Treatment
Intensity Modulated Radiation Therapy Market