
 Anemia Treatment Market | 2026-2036
Anemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Anemia Treatment Market Intelligence
Revenue from legacy erythropoiesis-stimulating agents is narrowing as new therapeutic classes gain regulatory approval and physician acceptance. CSL Vifor specializes in intravenous iron therapies, maintaining a strong position in the iron deficiency anemia segment. Akebia Therapeutics, Inc. competes with novel oral HIF-PH inhibitors, directly challenging the dominance of injectable treatments. Meanwhile, Pfizer leverages its global commercial infrastructure to support a diverse portfolio addressing various anemia etiologies across multiple countries.
Anemia treatment involves a range of pharmaceutical and biological interventions designed to restore hemoglobin levels and red blood cell production. These therapies include iron formulations engineered for high bioavailability and erythropoiesis-stimulating agents (ESAs) that biochemically mimic the function of natural erythropoietin. Iron supplements and ESAs represent the largest product type categories, primarily addressing iron deficiency anemia associated with chronic conditions. While the intravenous delivery mode remains critical in hospital settings, oral therapies are expanding their share, driven by patient convenience and adoption in specialized clinics.
Market access is governed by rigorous approval processes from agencies such as the US FDA, the European Medicines Agency (EMA), and Japan's PMDA. These regulatory bodies establish the clinical trial requirements and safety standards for all new treatments, including next-generation oral drugs and biosimilar products. Stakeholders must now evaluate investment in novel oral drug development versus lifecycle management strategies for established injectable therapies.
Market Dynamics
The central dynamic in the anemia treatment market is the technological displacement of injectable biologics by novel oral therapies. The introduction of hypoxia-inducible factor prolyl hydroxylase inhibitors is fundamentally altering treatment algorithms, shifting the point of care and challenging established commercial models.
Growth Catalysts
- Novel Oral Formulations:The development of oral HIF-PH inhibitors improves patient convenience and adherence compared to injectable ESAs, driving adoption in chronic care settings for conditions like CKD.
- Public Health Initiatives:National health programs in countries like India are expanding access to diagnostics and essential medicines, increasing the diagnosed prevalence of iron-deficiency anemia and subsequent treatment rates.
- Chronic Disease Prevalence:A rising global incidence of chronic kidney disease and cancers, which frequently cause anemia as a comorbidity, expands the addressable patient population requiring supportive care in specialized clinics.
Market Restraints
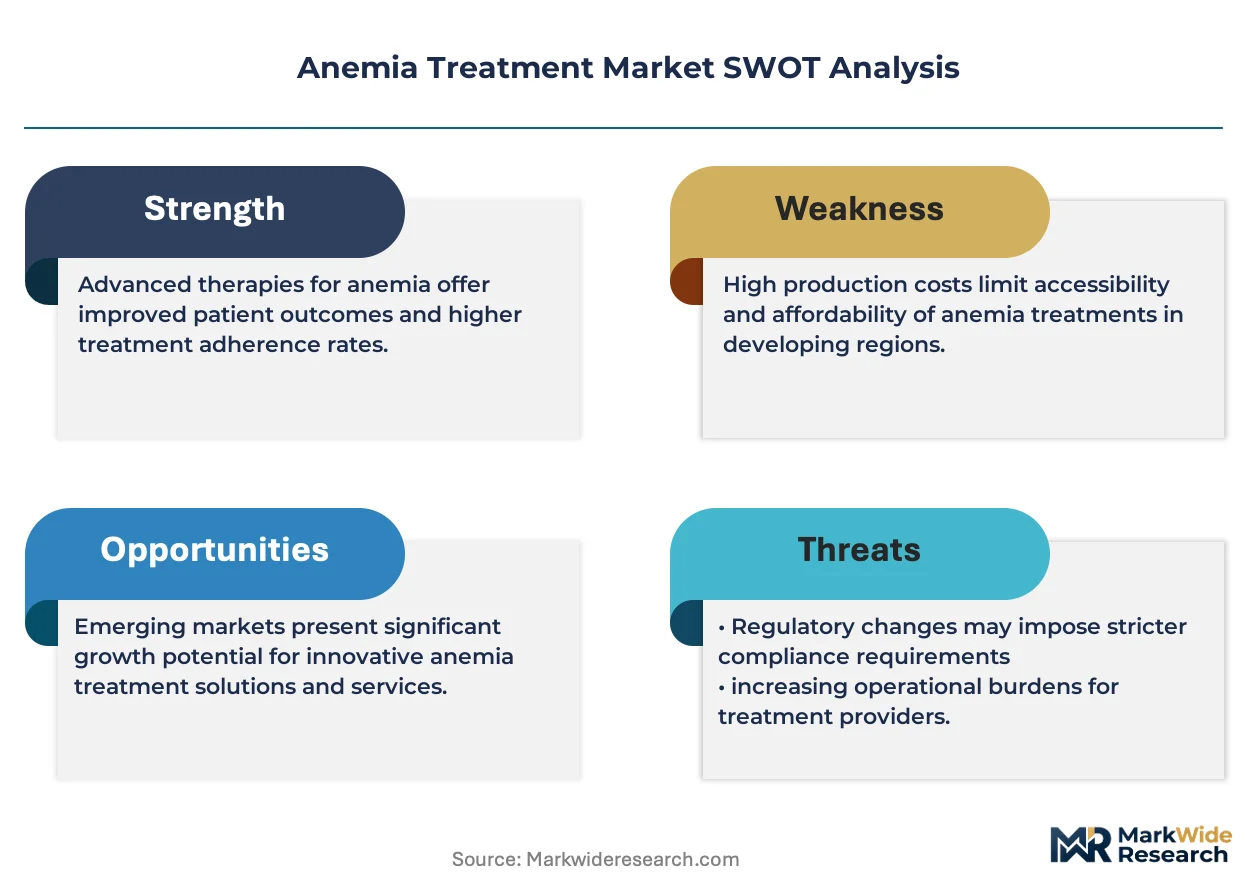
- High Treatment Costs:The premium pricing of new biologic drugs and novel oral therapies limits accessibility, particularly in markets with less comprehensive public or private reimbursement frameworks.
- Stringent Regulatory Hurdles:Rigorous and lengthy clinical trial requirements mandated by agencies like the US FDA and EMA for demonstrating long-term safety and efficacy can significantly delay new product launches.
- Biosimilar Competition:The availability of lower-cost biosimilar erythropoiesis-stimulating agents and generic intravenous iron creates intense price pressure, making it difficult for novel, higher-priced therapies to gain formulary acceptance.
Strategic Opportunities
- Underserved Geographies:Markets in Southeast Asia and Latin America represent significant growth areas as healthcare infrastructure and diagnostic capabilities for chronic conditions improve, uncovering latent demand for anemia therapies.
- Orphan Anemia Indications:Focusing drug development on rare forms of anemia or specific patient subgroups that are refractory to existing treatments provides a pathway for obtaining orphan drug designations and premium pricing.
- Pediatric Formulations:Developing and securing approval for formulations specifically dosed and designed for pediatric populations with chronic kidney disease or chemotherapy-induced anemia addresses a clear unmet medical need.
Industry Challenges
- Cold Chain Logistics:Maintaining the integrity of the cold chain for injectable biologics like ESAs from manufacturing to administration remains a significant operational and financial burden for distributors and providers.
- Physician Treatment Inertia:Overcoming established prescribing habits and educating clinicians on the risk-benefit profile of new therapeutic classes is a critical barrier to the adoption of innovative anemia treatments.
- Complex Lifecycle Management:Manufacturers must balance investment in pioneering next-generation oral drugs against the need to defend market share for legacy injectable products facing erosion from biosimilar entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anemia Treatment Market |
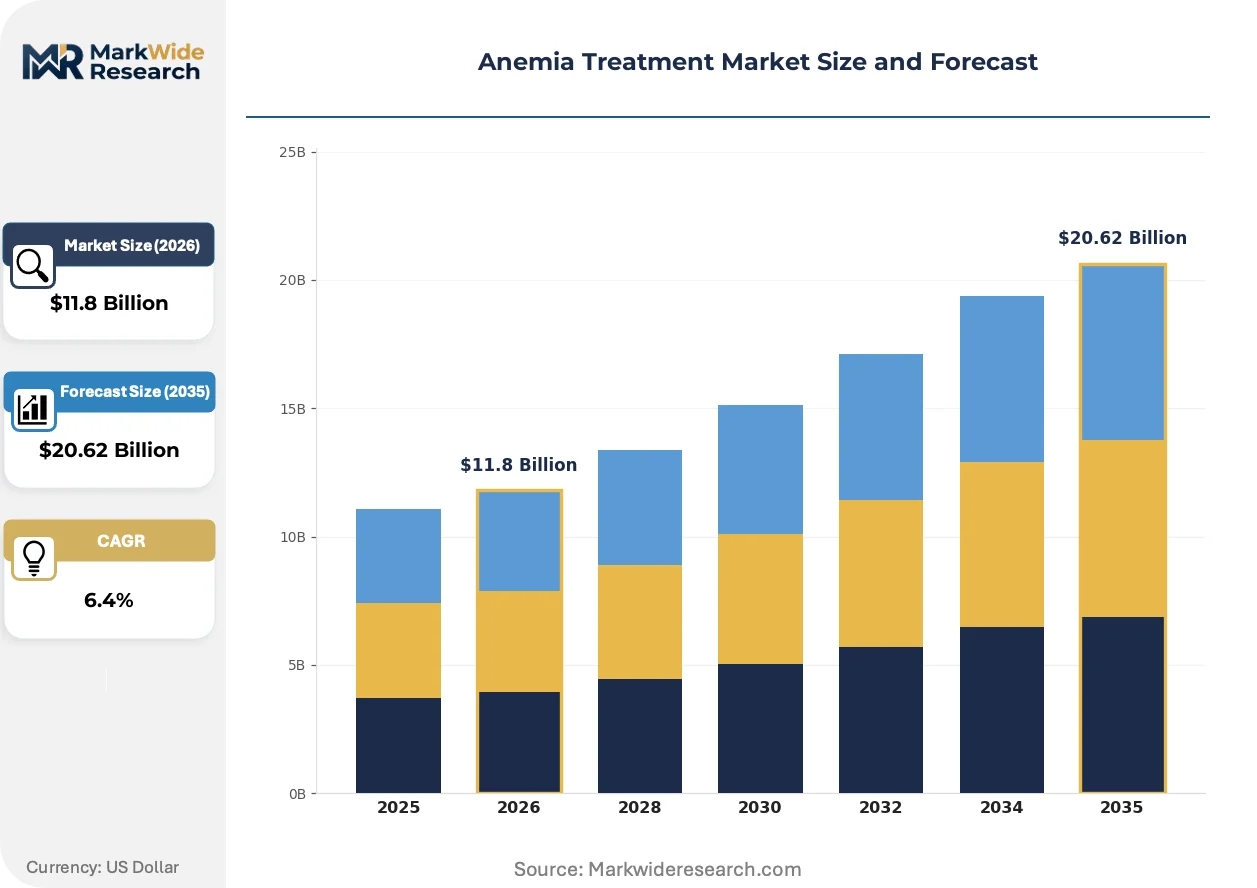
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iron Supplements, Vitamin B12 Injections, Erythropoiesis-Stimulating Agents, Folic Acid Tablets, Blood Transfusion Products Therapy Area: Iron Deficiency Anemia, Megaloblastic Anemia, Aplastic Anemia, Hemolytic Anemia, Sickle Cell Anemia End User: Hospitals, Diagnostic Laboratories, Specialized Clinics, Homecare Settings, Blood Banks Delivery Mode: Oral, Intravenous, Intramuscular, Subcutaneous, Transfusion |
| Companies Covered | Sanofi, AbbVie Inc., CSL Vifor, Pharmacosmos A/S, Akebia Therapeutics, Inc., Pfizer Inc., Johnson & Johnson Services, Inc., Fresenius Kabi AG, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anemia Treatment Market Strategic Shifts & Innovations
Treatment paradigms are shifting from institutionally-based care towards patient-centric models. This evolution is driven by innovations in drug delivery that favor oral administration and enable management outside of traditional hospital settings, particularly for chronic patient populations.
Novel oral HIF-PH inhibitors provide a less invasive alternative to injectable ESAs. Specialized nephrology and oncology clinics are the primary adopters of these new agents. The combination of oral delivery with connected health tools is digitizing patient management, shifting it from episodic interventions to more continuous monitoring of therapeutic response and adherence.
Regulatory frameworks for biosimilars, established by agencies like the US FDA and the European Medicines Agency, have accelerated price competition. This directly impacts originator biologics, particularly first-generation ESAs, which now face significant revenue erosion. The segment most affected is established large-molecule therapeutics, forcing manufacturers to compete on value-added services and lifecycle management.
A clear behavioral shift is underway, with treatment administration moving from large hospitals to specialized outpatient clinics and even home-care environments. This disrupts historical distribution channels centered on hospital pharmacies, creating an advantage for oral drugs or therapies suitable for clinic-based infusion. This trend is most advanced in North America and Europe, especially for the management of anemia in chronic kidney disease patients.
Anemia Treatment Market Segmentation
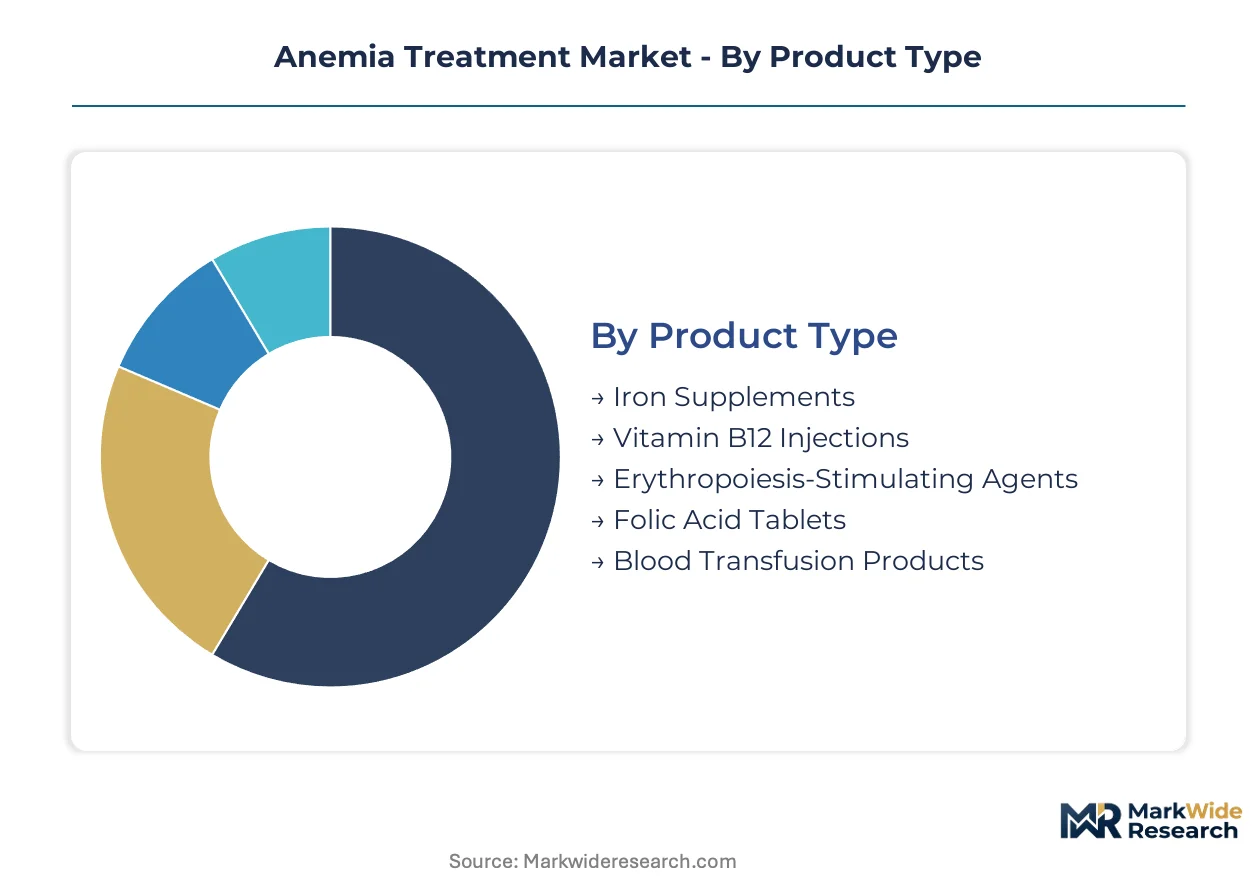
The anemia treatment market categorizes therapeutic interventions and patient populations to better understand demand patterns and clinical needs. This segmentation highlights the diverse approaches required to manage various forms of anemia, from nutritional deficiencies to chronic disease-related conditions. Analyzing these distinct segments reveals where innovation and investment are most concentrated.
Product Type:
The use-case spectrum for anemia treatments spans from basic nutritional supplementation to complex biological interventions, each addressing specific etiologies and severity levels.
- Iron Supplements:These formulations provide elemental iron to correct iron deficiency, commonly available in oral forms but also administered intravenously for rapid repletion or malabsorption issues. Demand is concentrating in public health initiatives in countries like India, driven by high prevalence of nutritional anemia.
- Erythropoiesis-Stimulating Agents:ESAs are recombinant proteins that mimic natural erythropoietin, stimulating red blood cell production, primarily used in anemia associated with chronic kidney disease and certain cancers. Adoption is growing in specialized nephrology clinics due to the need for precise hemoglobin management.
- Vitamin B12 Injections:Administered to treat megaloblastic anemia caused by vitamin B12 deficiency, typically due to malabsorption or dietary inadequacy.
- Folic Acid Tablets:Essential for DNA synthesis and red blood cell maturation, these are prescribed for folate deficiency anemia.
- Blood Transfusion Products:Used for acute or severe anemia when rapid hemoglobin increase is critical, often in hospital settings for trauma or severe blood loss.
The dominant share belongs to Iron Supplements, while Erythropoiesis-Stimulating Agents are closing the gap fastest.
Therapy Area:
Therapy areas define treatment by the underlying patient population and specific anemia etiology, guiding drug development and clinical practice.
- Iron Deficiency Anemia:This is the most common form of anemia, treated with iron supplementation, often linked to chronic blood loss or inadequate dietary intake. Global prevalence drives substantial demand for accessible and effective iron therapies.
- Sickle Cell Anemia:A genetic blood disorder characterized by abnormal hemoglobin, requiring specialized treatments to manage pain crises and prevent complications. Research and development efforts focus on gene therapies and novel disease-modifying agents for this condition.
- Megaloblastic Anemia:Caused by deficiencies in vitamin B12 or folate, leading to the production of abnormally large red blood cells.
- Aplastic Anemia:A rare condition where the bone marrow fails to produce enough blood cells, often requiring immunosuppressants or bone marrow transplantation.
- Hemolytic Anemia:Occurs when red blood cells are destroyed faster than they can be produced, necessitating therapies that address the underlying cause of hemolysis.
Therapeutic interventions for Iron Deficiency Anemia represent the largest segment, with significant innovation targeting Sickle Cell Anemia.
End User:
End user segments reflect the evolving care settings where anemia treatments are administered, impacting distribution channels and patient access.
- Hospitals:These institutions manage severe anemia cases, administer intravenous therapies, and conduct blood transfusions, acting as critical hubs for acute care. Hospital pharmacies remain central for complex or inpatient treatments.
- Specialized Clinics:Including nephrology and oncology clinics, these facilities provide ongoing management for chronic anemia conditions, increasingly adopting novel oral therapies. The shift towards outpatient care benefits these specialized centers.
- Diagnostic Laboratories:These facilities play a foundational role in identifying anemia types and monitoring treatment efficacy through blood tests.
- Homecare Settings:A growing segment for self-administered oral therapies and some injectable treatments, enhancing patient convenience and reducing healthcare costs.
- Blood Banks:Essential for providing blood and blood products for transfusion, supporting severe anemia cases and surgical needs.
Hospitals maintain a foundational role in anemia treatment, while Specialized Clinics are expanding their patient volume for chronic disease management.
Delivery Mode:
Delivery mode considers the method of administration, influencing patient convenience, adherence, and the suitability for different clinical scenarios.
- Oral:Oral therapies offer patient convenience and are increasingly preferred for chronic management outside of hospital settings, particularly for conditions like chronic kidney disease. Novel oral HIF-PH inhibitors are reshaping treatment paradigms.
- Intravenous:This mode ensures rapid drug delivery and high bioavailability, critical for acute cases or patients with malabsorption, commonly used in hospital and specialized clinic environments. CSL Vifor specializes in intravenous iron therapies.
- Intramuscular:Used for certain vitamin injections, providing a sustained release of medication into the muscle tissue.
- Subcutaneous:Involves injecting medication under the skin, often for self-administration of biologics like erythropoiesis-stimulating agents.
- Transfusion:Direct infusion of blood or blood components into the bloodstream, reserved for severe anemia or acute blood loss.
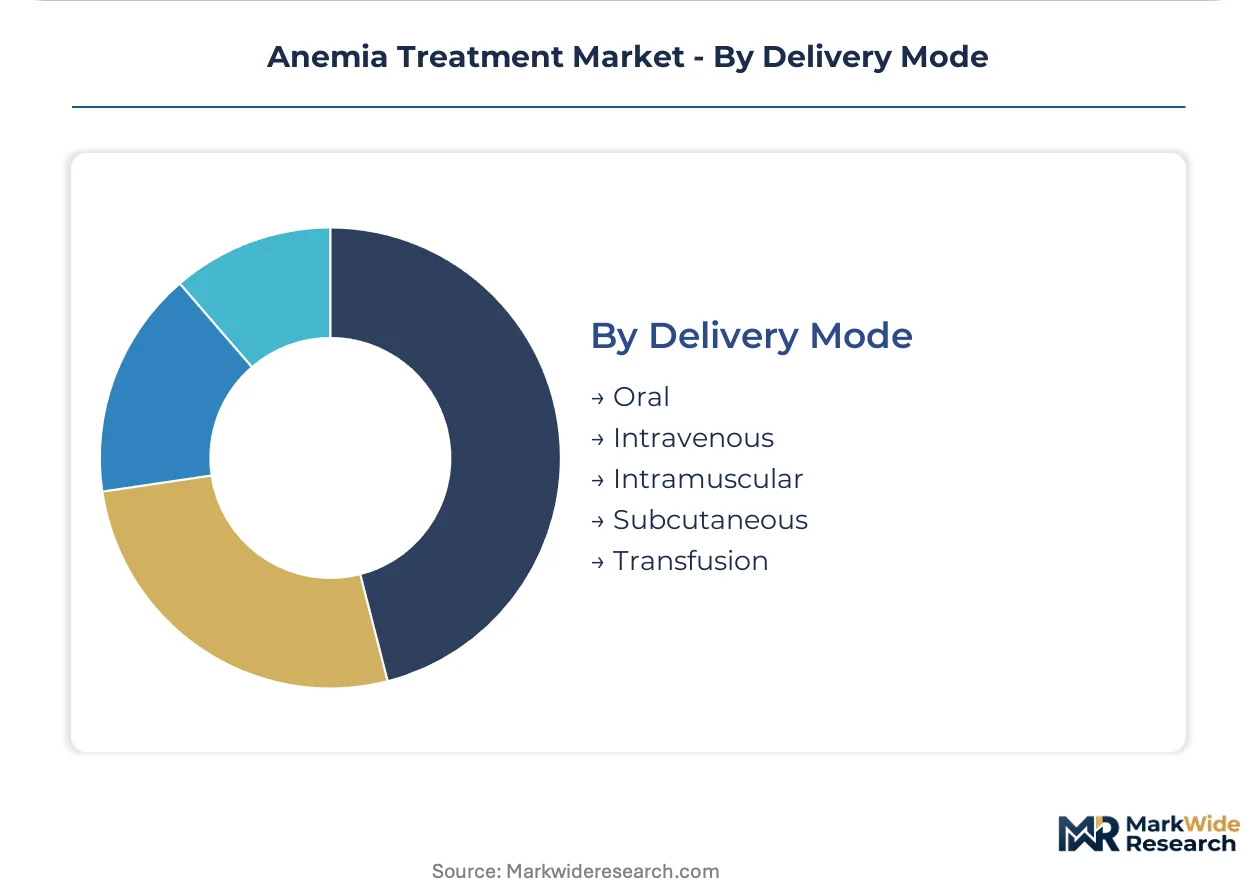
Oral delivery modes are gaining significant traction, challenging the traditional dominance of Intravenous treatments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global anemia treatment market exhibits varied supply-side concentration, reflecting diverse healthcare infrastructures and regulatory environments. This shapes the availability and adoption of novel therapies across different regions. Specialized clinics and public health programs influence regional market dynamics.
India
India's demand for anemia treatments is driven by extensive public health initiatives and improving diagnostic infrastructure. The country's National Health Mission actively promotes screening and treatment for nutritional anemia, particularly among women and children. The Delhi-NCR region, with its expanding network of healthcare facilities, sees increased demand for accessible iron therapies.
United States
The United States market sees significant demand for anemia treatments due to a high incidence of chronic kidney disease and oncology-related anemia. The US FDA's rigorous approval processes govern the market entry for novel biological drugs and oral therapies. The Boston-Cambridge biotech hub drives significant innovation in next-generation oral drugs, attracting substantial investment.
Germany
Germany benefits from a robust healthcare system and substantial investment in specialized nephrology clinics, fostering demand for advanced anemia treatments. The European Medicines Agency (EMA) sets high safety and efficacy standards for new therapies entering the German market. The Frankfurt Rhine-Main region, a major pharmaceutical center, supports the development and distribution of advanced therapies.
Japan
Japan's market for anemia treatments is influenced by its aging population and a rising incidence of chronic diseases, alongside a strong focus on patient convenience with oral therapies. Japan's PMDA regulates the market, ensuring stringent quality and safety for all pharmaceutical products. The Osaka-Kyoto area, a hub for pharmaceutical R&D, sees concentrated efforts in novel drug development.
China
China's market is characterized by expanding healthcare access and a rising chronic disease burden, coupled with government support for domestic pharmaceutical innovation. China's NMPA oversees drug approvals, increasingly streamlining processes for innovative therapies to reach patients. Shanghai's biomedical industry cluster is attracting investment for both local and international anemia treatment manufacturers.
Anemia Treatment Market Key Industry Players
Established pharmaceutical giants and specialized biotech firms split the anemia treatment market, reflecting a tiered competitive structure. The strategic archetypes include diversified global players, focused intravenous iron specialists, and novel oral therapy developers. Companies pursue portfolio diversification and strategic partnerships to maintain market presence.
Within the specialized treatment archetype, CSL Vifor and Akebia Therapeutics, Inc. exemplify distinct approaches. CSL Vifor represents established expertise in intravenous iron therapies, maintaining a strong position in the iron deficiency segment. Akebia Therapeutics, Inc. occupies a position among innovators, challenging traditional injectable treatments with novel oral HIF-PH inhibitors. Pfizer Inc., a large multinational entity, anchors the diversified global player segment, leveraging its extensive commercial infrastructure across various anemia etiologies.
| Leading Market Players |
|---|
| Sanofi |
| AbbVie Inc. |
| CSL Vifor |
| Pharmacosmos A/S |
| Akebia Therapeutics, Inc. |
| Pfizer Inc. |
| Johnson & Johnson Services, Inc. |
| Fresenius Kabi AG |
| GlaxoSmithKline plc |
Cost & Logistics Intelligence
Specialized biotech firms developing novel oral therapies command premium pricing, capturing significant margin pools downstream in specialized clinics. This shift fundamentally alters the economic landscape for legacy injectable treatments.
Pricing Analysis
Value-added patient support programs drive long-term revenue for chronic anemia treatments. Value-based pricing is gaining traction for novel oral therapies, reflecting clinical outcomes. Regulatory approval status and demonstrated clinical efficacy drive significant price differentiation. Pricing softness stems from biosimilar competition, particularly for first-generation erythropoiesis-stimulating agents. Public health initiatives in developing markets are highly price-sensitive, while specialized clinics seeking advanced treatments exhibit lower sensitivity.
Supply Chain Analysis
Manufacturing capacity for complex biologics and novel oral drugs concentrates within specialized facilities in the United States and Europe. Raw material dependencies include recombinant proteins for ESAs and specific chemical precursors for novel oral therapies. Cold chain logistics for injectable biologics represent a significant operational and financial burden. Distribution runs through a dual model, with hospitals handling acute cases and specialized clinics managing chronic patient populations, increasingly for oral therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anemia treatment market is experiencing high-growth disruption, driven by the technological displacement of injectable biologics by novel oral therapies. This shift fundamentally alters treatment algorithms and commercial models.
For Market Incumbents:Pre-empt further revenue erosion from novel oral HIF-PH inhibitors by accelerating investment in next-generation oral drug development. Leverage global commercial infrastructure to defend market share for established injectable therapies against biosimilar competition. Pursue strategic partnerships to expand presence in underserved geographies like Southeast Asia. Focus R&D on orphan anemia indications to secure premium pricing and mitigate pricing pressure.
For New Entrants and Emerging Players:Markets in Southeast Asia and Latin America represent significant underpenetration for advanced anemia treatments. Target pediatric formulations for chronic kidney disease, a clear unmet medical need. Develop cost-effective oral therapies tailored for public health initiatives in countries like India, focusing on high bioavailability. A direct-to-clinic sales model, emphasizing patient convenience, can accelerate adoption in specialized outpatient settings.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with specialized biotech firms developing novel oral HIF-PH inhibitors, offering attractive long-term viability over a 5-10 year window. Target companies with strong patent portfolios and established regulatory approvals for next-generation oral drugs. Acquisition of firms with robust clinical trial pipelines for orphan anemia indications presents growth opportunities. The signal to watch is the rate of physician adoption of new oral therapies in chronic care settings.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market entry for novel oral HIF-PH inhibitors, challenging established injectable treatments and expanding patient convenience. |
| Regulatory Approval Pathway | Secures market access for biosimilar erythropoiesis-stimulating agents, intensifying price competition for originator biologics. |
| Manufacturing Scale-Up | Ensures sufficient supply of high-bioavailability iron formulations to meet demand from public health initiatives. |
| Licensing Agreement | Expands geographic reach for specialized anemia therapies into underserved markets in Southeast Asia and Latin America. |
| Pipeline Diversification | Addresses unmet medical needs in rare forms of anemia or specific pediatric populations, securing orphan drug designations. |
Research Approach
Desk research of US FDA filings, EMA submissions, and ClinicalTrials.gov preceded structured interviews with drug development executives, regulatory affairs leads, and hospital procurement managers. Primary interviews validated market dynamics and pricing trends, complementing secondary data sources. This approach combined bottom-up market sizing with top-down validation of revenue projections.
Assumptions regarding chronic disease prevalence rates and regulatory approval timelines were held fixed across the analysis window. The analytical framework modeled market segmentation across product type, therapy area, end user, delivery mode, and regional regulatory cluster. Compound annual growth rates were derived from historical trends and projected adoption rates of novel oral therapies. Forecast inputs included evolving treatment guidelines and public health initiative expansion.
The forecast holds incumbent behavior within observed patterns; aggressive moves by novel oral therapy developers or biosimilar manufacturers would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and clinical trial success rates. Quarterly review of therapeutic adoption rates and regulatory approvals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Infertility Treatment Market
Medical Treatment
Molluscum Contagiosum (MC) Treatment Market
Medical Treatment
Hyponatremia Treatment Market
Medical Treatment
Rett Syndrome Treatment Market
Medical Treatment
Uterine Fibroid Treatment Drugs Market
Medical Treatment
Transplantation Market
Medical Treatment
Spain Hair Transplant Market
Medical Treatment
Hypercalcemia Treatment Market
Medical Treatment
Parathyroid Disease Treatment Market
Medical Treatment
Hypogonadism Treatment Market
Medical Treatment
Basal Cell Carcinoma Treatment Market
Medical Treatment
Isovaleric Acidemia Treatment Market
Medical Treatment
Bloch-Sulzberger Treatment Market
Medical Treatment
Prion Disease Treatment Market
Medical Treatment
Histiocytosis Treatment Market
Medical Treatment
Intensity Modulated Radiation Therapy Market