
 Peanut Allergy Treatment Market | 2026-2036
Peanut Allergy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Peanut Allergy Treatment Market Analytics
The United States is tilting toward expanded manufacturing capacity for peanut protein extracts and biologic formulations. Aimmune Therapeutics leverages its FDA-approved Palforzia platform to anchor commercial supply chains domestically. DBV Technologies competes through patch-based epicutaneous delivery systems that reduce systemic exposure risks. Sanofi sustains broader immunology infrastructure spanning biologics and emergency epinephrine devices.
Peanut allergy treatment encompasses clinical interventions designed to reduce hypersensitivity reactions through controlled antigen exposure, biologic modulation, or acute symptom management. Oral immunotherapy protocols administer precisely calibrated peanut protein doses to induce desensitization, with maintenance regimens typically targeting 300–600 mg daily protein thresholds. Immunotherapy products command premium positioning due to prolonged treatment duration and specialized compounding requirements, while emergency kits retain defensive margin pools through recurring replacement cycles driven by expiration protocols. Subcutaneous delivery modes occupy narrower clinical niches given anaphylaxis risk profiles, whereas sublingual formats attract development interest for pediatric tolerability advantages.
FDA oversight shapes product approval pathways through allergen-specific guidance documents and risk evaluation frameworks for immunotherapy agents. EMA and national European regulators enforce divergent standards for biologic manufacturing and pediatric trial endpoints, fragmenting market access conditions across jurisdictions. Stakeholders must monitor evolving FDA label expansions and EMA pediatric investigation plans to align development timelines with regulatory precedent rather than speculative indication breadth.
Market Dynamics
FDA approval pathways for oral immunotherapy have compressed clinical trial timelines while elevating manufacturing standards for peanut protein extracts, forcing developers to build specialized production infrastructure ahead of commercial scale.
Growth Catalysts
- Pediatric prevalence concentration:United States school districts mandate epinephrine availability, creating institutional demand for desensitization protocols that reduce acute incident rates.
- Biologic manufacturing advances:Recombinant protein engineering enables standardized allergen dosing with reduced batch-to-batch variability, improving clinical protocol reproducibility.
- Insurance coverage expansion:CMS reimbursement codes for oral immunotherapy office visits remove cost barriers for middle-income families seeking treatment.
Market Restraints
- Specialized facility capital requirements:Peanut protein compounding demands HEPA filtration and segregated production lines, concentrating manufacturing among contract organizations with existing allergen infrastructure.
- Anaphylaxis liability exposure:Product liability frameworks in the United States impose litigation costs that deter smaller developers from immunotherapy program initiation.
- Maintenance regimen adherence:Daily dosing requirements stretching across years generate dropout rates that compress lifetime patient value calculations.
Strategic Opportunities
- Home dosing enablement:Telemedicine platforms paired with remote monitoring devices allow maintenance phase administration outside clinical settings, expanding addressable geography beyond urban hospital catchments.
- Combination biologic protocols:Anti-IgE monoclonal antibody pretreatment permits faster dose escalation, shortening the buildup phase that currently consumes clinical resources.
- Adult indication expansion:Current labeling concentrates on pediatric populations, leaving untreated adult allergic patients as an accessible adjacent segment.
Industry Challenges
- Pediatric allergist workforce scarcity:Fellowship program graduation rates lag behind desensitization program expansion, creating appointment backlogs that limit patient throughput.
- Supply chain allergen cross-contamination protocols:Dedicated logistics networks for peanut protein extracts add cost layers that squeeze margin at commercial scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peanut Allergy Treatment Market |
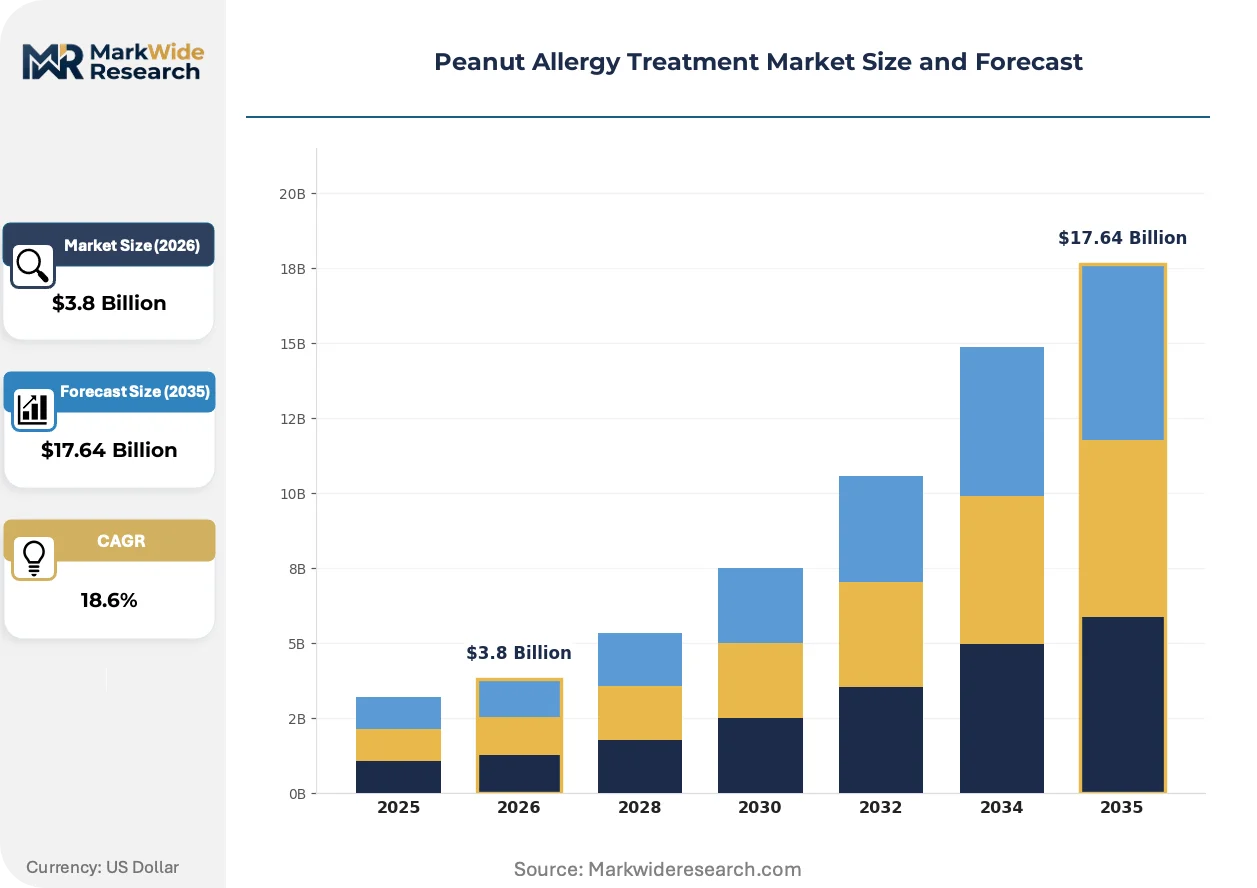
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunotherapy, Antihistamines, Corticosteroids, Emergency Kits Delivery Mode: Subcutaneous, Sublingual, Oral, Injectable End User: Hospitals, Clinics, At-Home, Pharmacies Age Group: Pediatrics, Adolescents, Adults, Seniors |
| Companies Covered | Aimmune Therapeutics, DBV Technologies, Sanofi, ALK-Abelló, Prota Therapeutics, Camallergy, Aravax, Genentech, Regeneron Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peanut Allergy Treatment Market Evolving Landscape
Epicutaneous delivery systems and precision biologics are fragmenting the historical dominance of avoidance strategies and emergency epinephrine, creating parallel treatment paradigms with divergent clinical infrastructure requirements.
Microarray-based epitope mapping enables personalized immunotherapy formulations calibrated to individual IgE binding profiles. Allergy diagnostic laboratories in Germany and the Netherlands are integrating these platforms into standard workups. Patient-specific allergen cocktails are rendering obsolete the one-size-fits-all peanut protein extracts that dominated early oral immunotherapy protocols.
EMA pediatric investigation plans now mandate long-term safety follow-up for immunotherapy agents seeking approval in European markets. This regulatory requirement extends development timelines by eighteen to twenty-four months compared to adult-only indications. Biologic developers are responding by front-loading juvenile toxicity studies to preserve European market access eligibility.
Direct-to-patient subscription models for maintenance-phase products are emerging as alternatives to hospital-based pharmacy dispensing. Parents of allergic children in suburban United States markets prefer home delivery of calibrated doses with integrated symptom logging apps. This channel shift reduces clinical overhead but introduces cold chain integrity risks that manufacturers must warranty.
Peanut Allergy Treatment Market Segmentation
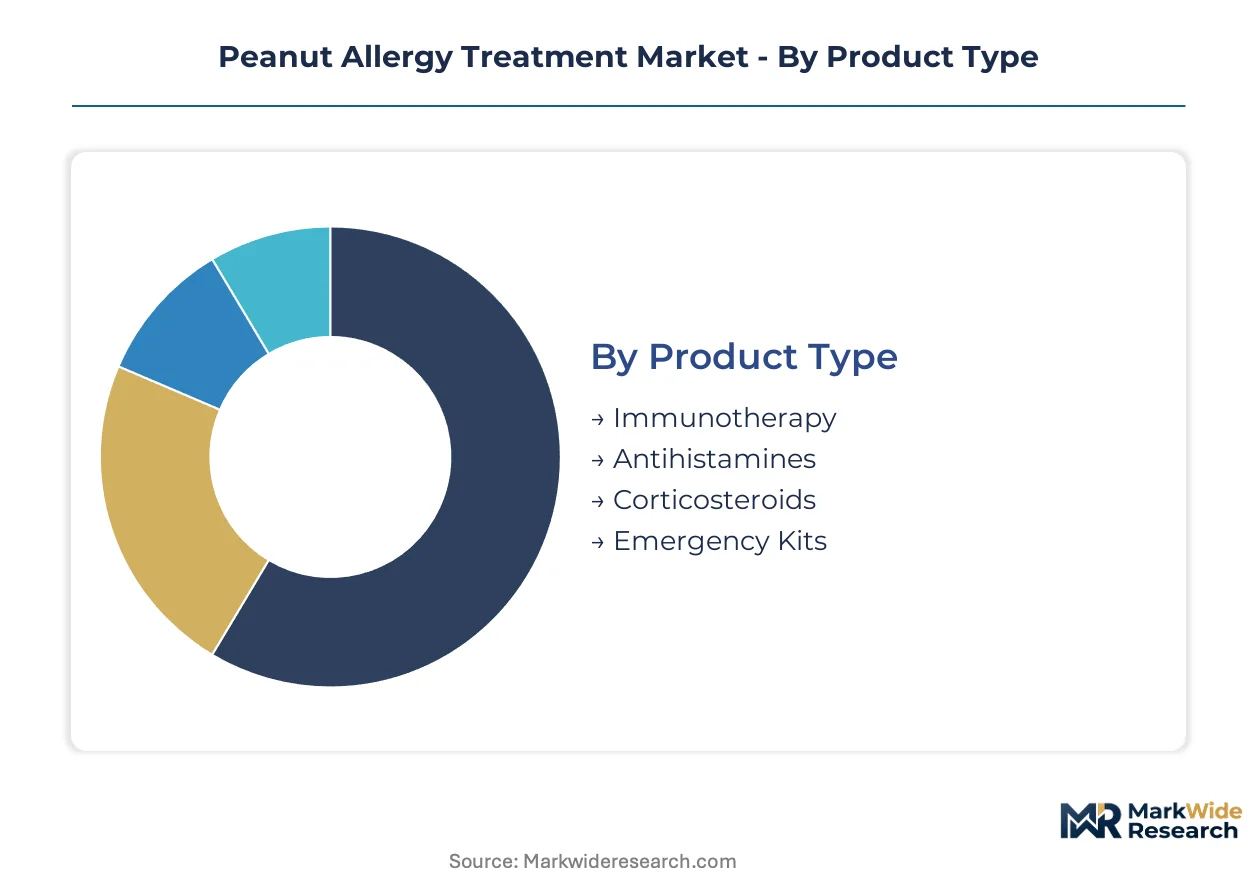
Treatment modality selection in the peanut allergy market hinges on risk tolerance, patient age, and clinical infrastructure availability. Segmentation reveals how commercial investment concentrates in immunotherapy platforms while emergency preparedness products sustain defensive revenue pools.
Product Type:
Cost tier stratification separates chronic disease-modifying interventions from acute symptom management, with capital requirements and reimbursement intensity diverging sharply across these brackets.
- Immunotherapy:Oral and epicutaneous protocols administer calibrated peanut protein doses to induce desensitization. Demand concentrates in pediatric specialty clinics across the United States, where FDA-approved products command premium positioning through prolonged treatment duration. Insurance coverage expansion for office-based administration removes cost barriers for middle-income families.
- Emergency Kits:Epinephrine auto-injectors and adjunctive medications provide acute anaphylaxis intervention. Replacement cycles driven by expiration protocols sustain recurring revenue in school districts and institutional settings where epinephrine availability is mandated.
- Antihistamines:Second-generation H1 antagonists manage mild cutaneous and gastrointestinal symptoms.
- Corticosteroids:Systemic formulations address refractory inflammatory reactions following allergen exposure.
Immunotherapy commands the established base. The steepest expansion runs through Emergency Kits.
Delivery Mode:
Application context determines route selection, with safety profiles and patient compliance requirements dictating clinical versus home administration feasibility.
- Oral:Daily peanut protein dosing in capsule or food matrix formats constitutes the dominant immunotherapy modality. Pediatric tolerability advantages drive protocol adherence in United States desensitization programs, though buildup phase supervision demands specialist availability.
- Epicutaneous:Patch-based delivery systems reduce systemic exposure risks through dermal antigen presentation. European regulatory frameworks under EMA pediatric investigation plans favor this modality for its safety profile in juvenile populations.
- Subcutaneous:Direct tissue injection occupies narrow clinical niches given anaphylaxis risk profiles.
- Injectable:Emergency epinephrine administration remains the standard of care for acute reactions.
Oral delivery anchors current clinical practice. Epicutaneous formats are gaining share fastest among risk-averse prescribers.
End User:
Customer type fragmentation reflects care setting economics, with reimbursement codes and liability frameworks channeling patients toward specific access points.
- Hospitals:Academic medical centers and children's hospitals house specialized allergology departments with infrastructure for supervised dose escalation. United States pediatric allergist workforce scarcity creates appointment backlogs that limit throughput despite program expansion.
- At-Home:Telemedicine platforms paired with remote monitoring devices enable maintenance phase administration outside clinical settings. Subscription models for calibrated doses with integrated symptom logging apps attract suburban United States parents seeking convenience.
- Clinics:Community-based allergy practices deliver protocol initiation and monitoring.
- Pharmacies:Retail dispensing channels support emergency kit distribution and replacement.
Hospitals retain the protocol initiation monopoly. At-Home administration shows the steepest trajectory as remote monitoring technology matures.
Age Group:
Volume concentration in pediatric populations shapes clinical trial design and regulatory submission strategies across jurisdictions.
- Pediatrics:Children aged 4-17 constitute the primary addressable population for immunotherapy labeling. United States school district mandates for epinephrine availability create institutional demand for desensitization protocols that reduce acute incident rates in this cohort.
- Adults:Untreated allergic patients beyond pediatric labeling represent an accessible adjacent segment. Current FDA approvals concentrate on younger populations, leaving diagnostic and treatment gaps in adult allergy practices.
- Adolescents:Transitional care requirements bridge pediatric and adult protocol administration.
- Seniors:Comorbidity profiles and polypharmacy constraints limit immunotherapy candidacy.
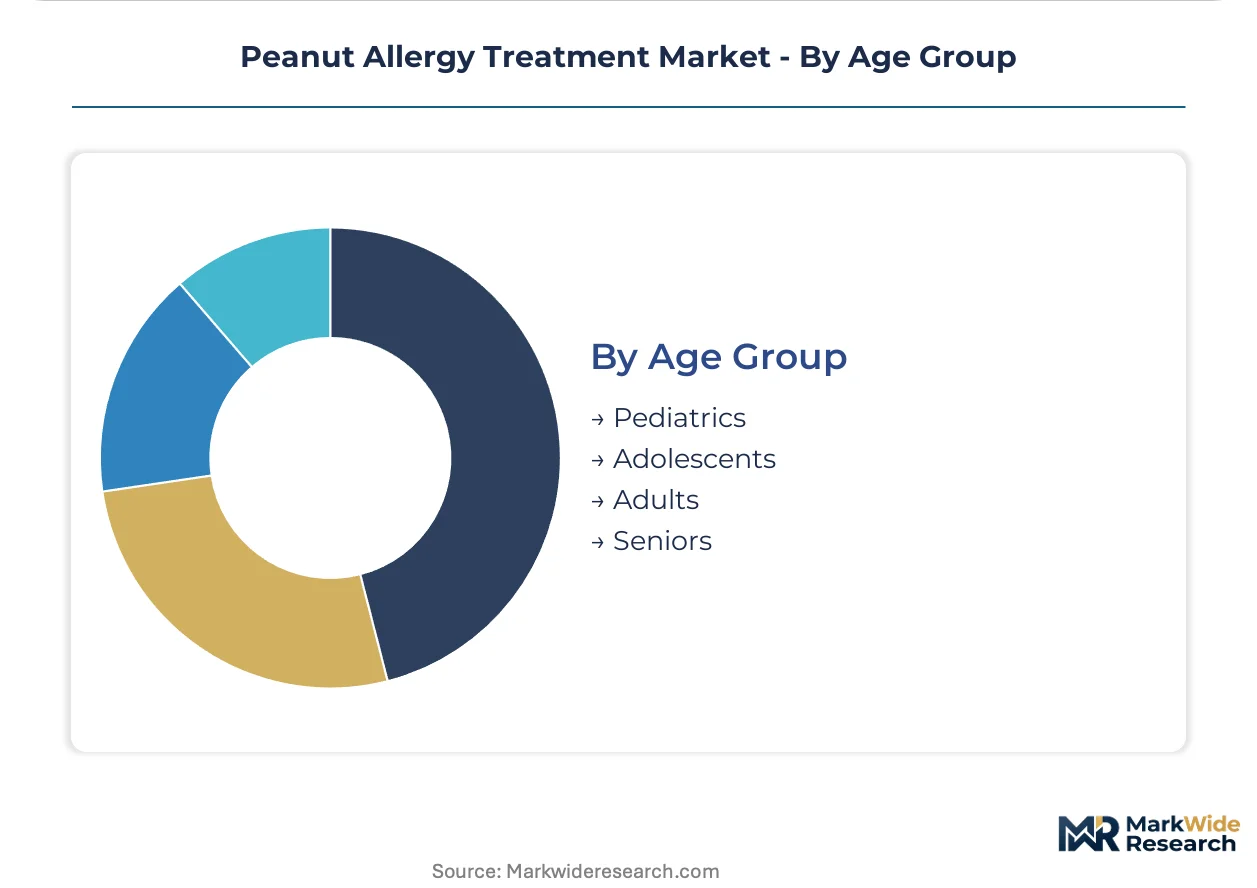
Pediatrics commands the established base. Adults represent the most accessible expansion frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized manufacturing capacity for peanut protein extracts clusters in the United States and select Western European markets, with regulatory divergence fragmenting commercialization timelines across jurisdictions. Pediatric allergist workforce density and insurance reimbursement frameworks determine regional adoption velocity.
United States
Pediatric prevalence rates and school district epinephrine mandates drive institutional demand for desensitization protocols. FDA approval pathways for oral immunotherapy have compressed clinical trial timelines while elevating manufacturing standards. Major hospital systems in Boston and Philadelphia are expanding dedicated allergology departments to accommodate program growth.
Germany
Microarray-based epitope mapping platforms are integrating into standard diagnostic workups at allergy laboratories in Munich and Heidelberg. EMA pediatric investigation plans mandate extended safety follow-up, stretching development timelines. The country's national pharmaceutical regulator enforces divergent standards for biologic manufacturing compared to FDA frameworks.
United Kingdom
NHS reimbursement decisions for oral immunotherapy office visits shape patient access economics. The country's national pharmaceutical regulator aligns with EMA guidance on juvenile toxicity study requirements. Research clusters in London and Cambridge are advancing personalized allergen cocktail formulations.
France
ANSM oversight of biologic manufacturing creates compliance complexity for patch-based delivery system developers. Pediatric allergist training programs in Paris and Lyon are expanding fellowship slots to address workforce gaps. National insurance frameworks are evaluating coverage for maintenance-phase telemedicine platforms.
Canada
Health Canada review timelines for immunotherapy agents lag FDA precedents by twelve to eighteen months. Provincial health authority reimbursement decisions vary across Ontario, Quebec, and British Columbia. Vancouver and Toronto house emerging epicutaneous delivery research programs.
Peanut Allergy Treatment Market Competitive Landscape
Biologic-focused developers and emergency preparedness incumbents split the market into parallel value pools with divergent margin structures. The competitive terrain exhibits moderate consolidation around FDA-approved platforms, with specialized manufacturing requirements limiting new entrant viability. Two archetypes dominate: vertically integrated pharmaceutical conglomerates with immunology infrastructure, and narrowly focused immunotherapy specialists with platform-specific expertise. Capacity expansion into dedicated allergen production facilities and strategic licensing of combination biologic protocols represent the dominant competitive moves.
Among the platform-specialist tier, Aimmune Therapeutics and DBV Technologies exemplify divergent delivery-mode strategies, with the former anchoring oral immunotherapy commercialization and the latter occupying epicutaneous patch development. Sanofi sits within the diversified pharmaceutical conglomerate archetype, leveraging broader immunology infrastructure spanning biologics and emergency devices. These three entities represent the competitive core around which smaller developers position for acquisition or partnership outcomes.
| Leading Market Players |
|---|
| Aimmune Therapeutics |
| DBV Technologies |
| Sanofi |
| ALK-Abelló |
| Prota Therapeutics |
| Camallergy |
| Aravax |
| Genentech |
| Regeneron Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Single-source dependency on FDA-inspected peanut protein extract facilities determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic clustering of contract manufacturing organizations. This concentration creates asymmetric pricing power for holders of dedicated allergen infrastructure while forcing developers into captive supply relationships.
Pricing Analysis
FDA allergen-specific guidance documents dictate the pricing tier structure for immunotherapy products, with Palforzia-equivalent oral protocols commanding premium positioning against unstandardized compounding alternatives. Certification tier differentiation separates GMP-validated biologic formulations from hospital pharmacy-compounded preparations, while volume scale advantages accrue to developers with multi-product allergen facilities. Cost compression in maintenance-phase subscriptions is intensifying because telemedicine platforms reduce clinical overhead capture. School districts and institutional buyers exhibit highest price sensitivity, whereas pediatric specialty clinics demonstrate lowest sensitivity due to liability-driven preference for validated protocols.
Supply Chain Analysis
Export-control restrictions on recombinant protein engineering platforms limit technology transfer to contract manufacturing organizations outside the United States and select Western European markets. Peanut protein extract production draws from specialized facilities in the United States, Germany, and the United Kingdom, with recombinant allergen inputs resting on bioreactor capacity anchored in Switzerland and the Netherlands. Single-source vulnerability concentrates in HEPA-filtered compounding suites with segregated production lines. Distribution runs through hospital-based pharmacy dispensing and emerging direct-to-patient subscription channels with cold chain integrity requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The peanut allergy treatment market functions as a service-attach opportunity where maintenance-phase telemedicine platforms and symptom logging apps expand addressable revenue faster than hardware-centric emergency devices.
For Market Incumbents: Pre-empt patch-based epicutaneous competitors by securing exclusive hospital system partnerships for combination biologic protocols before EMA pediatric investigation plan deadlines force protocol redesign. Backward integration into dedicated allergen production facilities in the United States preserves margin against contract manufacturing cost escalation. FDA label expansion for adult indications represents the priority defensive lever against generic erosion in pediatric populations. For New Entrants and Emerging Players: Establish a beachhead in adult allergy practices where current FDA approvals concentrate on younger populations and diagnostic gaps persist. Telemedicine-enabled home dosing platforms for maintenance-phase administration offer the most penetrable white space, with suburban United States parents demonstrating willingness to adopt subscription models. A go-to-market angle anchored on personalized epitope mapping from German diagnostic laboratories differentiates against standardized extract protocols. For Investors and Strategic Acquirers: FDA approval of anti-IgE monoclonal antibody pretreatment protocols reshapes the acquisition landscape by validating combination biologic platforms as commercially viable. Long-term viability over the projection horizon rests on developers with front-loaded juvenile toxicity studies preserving European market access eligibility. The acquisition target archetype centers on platform-specialist immunotherapy developers with manufacturing infrastructure already validated under FDA allergen guidance. The signal to monitor is Health Canada review timeline acceleration as provincial reimbursement decisions converge.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | HEPA-filtered allergen facilities in the United States secure supply against contract manufacturing bottlenecks. |
| Regulatory Approval Pathway | EMA pediatric investigation plan compliance preserves European market access eligibility for immunotherapy developers. |
| Licensing Agreement | Anti-IgE monoclonal antibody pretreatment permits faster dose escalation and shortened buildup phases. |
| Pipeline Diversification | Adult indication expansion addresses untreated allergic patients beyond current pediatric labeling concentration. |
| Clinical Trial Advancement | Microarray-based epitope mapping enables personalized immunotherapy formulations calibrated to individual IgE profiles. |
Research Methodology
A spread of perspectives from pediatric allergists, formulary directors at hospital systems, regulatory affairs leads, and payer access specialists converged on the working assumptions underlying this analysis. Primary interviews with allergy diagnostic laboratory directors in Germany and the Netherlands supplemented secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS reimbursement code databases. Bottom-up patient volume estimates and top-down market sizing triangulated on segment-level figures across the projection horizon.
Demand-supply balance framing anchored the analytical framework, with pediatric prevalence rates, specialist appointment capacity constraints, and insurance coverage expansion patterns modeled across treatment modality, delivery mode, and end-user segments. CAGRs were derived from patient volume trajectories and pricing tier evolution rather than macroeconomic extrapolation. Forecast inputs incorporated allergist workforce graduation rates, EMA pediatric investigation plan timeline impacts, and telemedicine platform adoption curves in suburban United States markets.
Stress conditions across regulatory approval delays, anaphylaxis liability litigation frequency, and maintenance regimen adherence rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about FDA label expansion timing and EMA pediatric safety follow-up requirements. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Single-Dose Therapy Market
Medical Treatment
Hereditary Amyloidosis Treatment Market
Medical Treatment
Menstrual Cramps Treatment Market
Medical Treatment
Severe Asthma Treatment Market
Medical Treatment
Global Medication Management Market
Medical Treatment
Basal Cell Carcinoma Treatment Market
Medical Treatment
Mesotherapy Market
Medical Treatment
House Dust Mite Allergy Treatment Market
Medical Treatment
Hypercoagulability Treatment Market
Medical Treatment
Filariasis Treatment Market
Medical Treatment
Influenza Treatment Market
Medical Treatment
Anaphylaxis Treatment Market
Medical Treatment
Systemic Sclerosis Treatment Market
Medical Treatment
Global Systemic Lupus Erythematosus Treatment Market
Medical Treatment
Endovenous Laser Therapy Market
Medical Treatment
Global Von Willebrand Disease Treatment Market