
 Global Erythropoietin Stimulating Agents Market | 2026-2036
Global Erythropoietin Stimulating Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Erythropoietin Stimulating Agents Market Foresight
China is narrowing its reliance on imported erythropoietin stimulating agents through domestic biomanufacturing scale-up. Amgen Inc. anchors North American supply with integrated recombinant protein production. F. Hoffmann-La Roche Ltd differentiates through darbepoetin alfa specialization in oncology-linked anemia. Biocon Ltd competes aggressively in biosimilars across emerging markets.
Erythropoietin stimulating agents are glycoprotein hormones produced via recombinant DNA technology in mammalian cell culture, formulated for parenteral administration to stimulate red blood cell production in bone marrow. The primary commercial purpose centers on correcting anemia in chronic kidney disease patients and chemotherapy recipients with hemoglobin deficits below 10 g/dL. Biosimilars command accelerating volume share as regulatory parity with originator molecules expands prescriber confidence. Chronic kidney disease therapy area sustains the largest revenue pool given dialysis center dependency and recurring administration cycles. Prefilled syringe delivery mode captures preference for self-administration and reduced clinical workload.
FDA, EMA, and WHO prequalification programs govern manufacturing standards, bioequivalence thresholds, and post-market surveillance for erythropoietin stimulating agents. These frameworks elevate compliance costs for new entrants while protecting established suppliers with validated quality systems. Stakeholders must monitor evolving biosimilar interchangeability designations and their impact on procurement contracting structures.
Market Dynamics
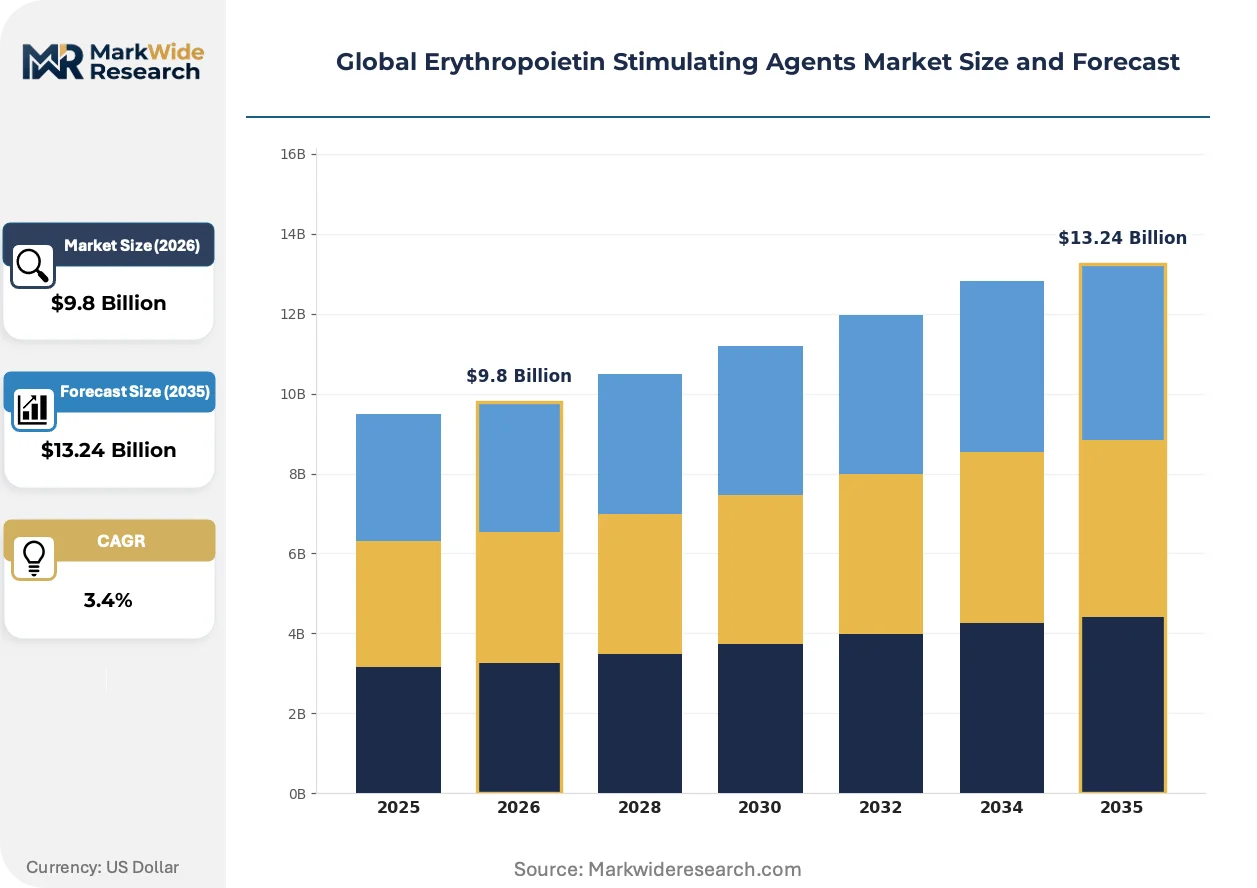
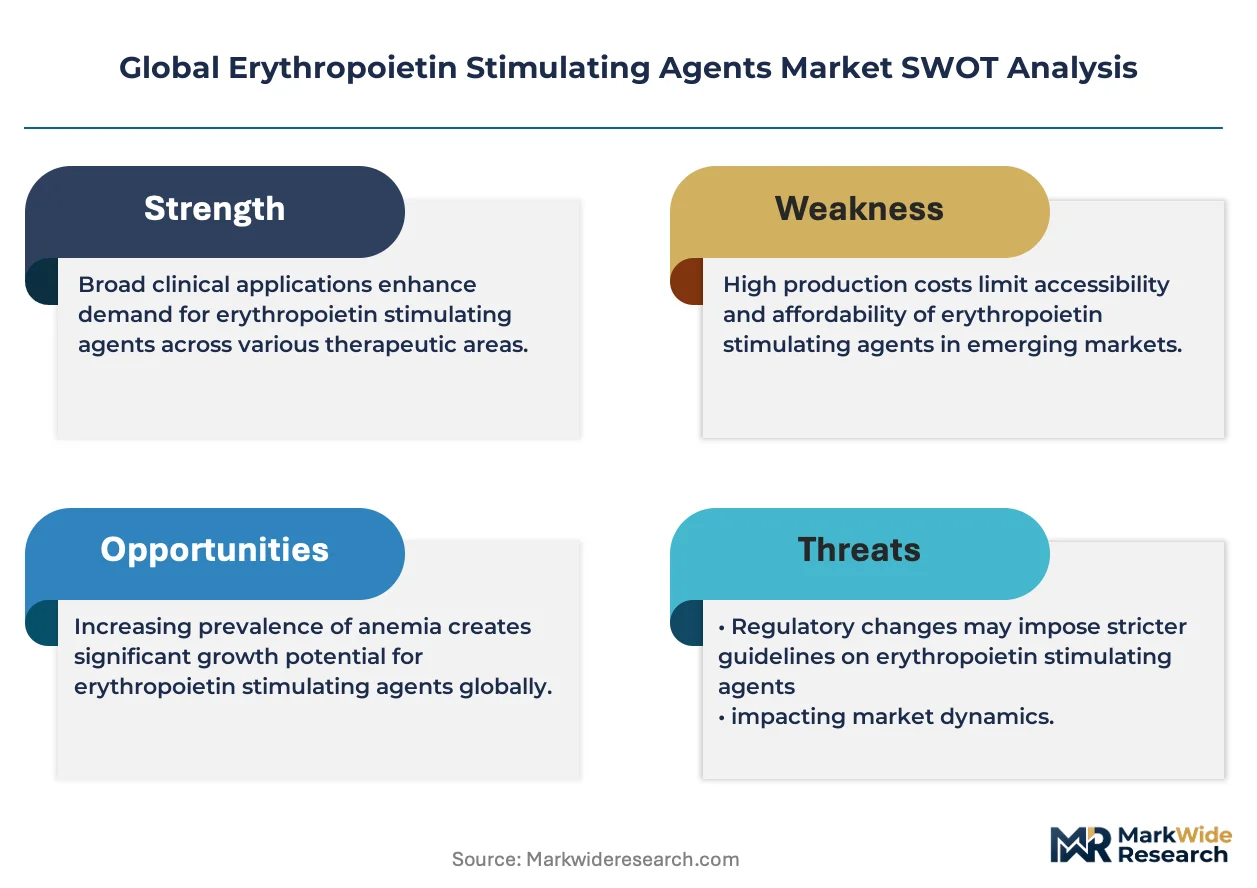
Biosimilar interchangeability designations from FDA and EMA are compressing originator pricing power while expanding prescriber choice in dialysis and oncology settings. This regulatory convergence with manufacturing scale economics is redistributing volume toward lower-cost alternatives without compromising therapeutic equivalence standards.
Growth Catalysts
- FDA Interchangeability Pathway:Designated biosimilars gain automatic substitution rights at pharmacy level, accelerating volume capture in US dialysis chains.
- Chronic Kidney Disease Prevalence:Rising diabetes-driven nephrology caseloads in Germany and Japan sustain recurring ESA administration cycles.
- Prefilled Syringe Delivery:Self-administration formats reduce clinical nursing burden and expand home dialysis adoption.
Market Restraints
- Plasma-Derived Raw Material Volatility:Mammalian cell culture media costs fluctuate with serum albumin supply constraints.
- Manufacturing Concentration Risk:Bulk drug substance production clusters in Puerto Rico and Ireland, creating hurricane and geopolitical exposure.
- Immunogenicity Surveillance Burden:EMA pharmacovigilance requirements for pure red cell aplasia reporting extend post-market compliance timelines.
Strategic Opportunities
- Sub-Saharan Africa Dialysis Infrastructure:WHO prequalification enables tender access where chronic kidney disease diagnostics are expanding.
- Long-Acting ESA Formulations:Monthly dosing intervals reduce clinic visit frequency and improve hematologic stability.
- India PLI Scheme for Biologics:Production-linked incentives attract contract manufacturing investment for export-oriented biosimilar supply.
Industry Challenges
- Bioanalytical Method Transfer:Biosimilar developers face immunogenicity assay validation complexity when bridging to originator reference products.
- Cold Chain Integrity:Parenteral protein stability demands complicate last-mile distribution to rural dialysis centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Erythropoietin Stimulating Agents Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $13.24 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant Human Erythropoietin, Darbepoetin Alfa, Methoxy Polyethylene Glycol-Epoetin Beta, Biosimilars Therapy Area: Chronic Kidney Disease, Chemotherapy-Induced Anemia, HIV-Associated Anemia, Prematurity-Related Anemia End User: Dialysis Centers, Oncology Clinics, Hematology Laboratories, Neonatal Care Units Delivery Mode: Subcutaneous Injection, Intravenous Injection, Intramuscular Injection, Prefilled Syringes |
| Companies Covered | Amgen Inc., F. Hoffmann-La Roche Ltd, Johnson & Johnson, Pfizer Inc., Thermo Fisher Scientific, Sandoz Group AG, Teva Pharmaceutical Industries Ltd, Biocon Ltd., Dr. Reddy's Laboratories Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Erythropoietin Stimulating Agents Market Shifts & Advancements
Recombinant protein engineering and regulatory science are converging to extend dosing intervals while compressing manufacturing costs. These advances are reshaping competitive differentiation beyond molecular similarity toward delivery convenience and supply reliability.
Continuous manufacturing platforms for mammalian cell culture are hybridizing batch and perfusion methodologies to increase volumetric productivity. Dialysis center procurement teams in the United States are piloting these outputs for supply security. This hybridizing approach is compressing capital intensity per gram of active pharmaceutical ingredient while maintaining glycosylation consistency.
EMA's revised biosimilar guidelines for erythropoietins clarify extrapolation rules across indications, reducing regulatory uncertainty for developers. Manufacturers are restructuring clinical trial programs to leverage oncology anemia data for chronic kidney disease approvals. European nephrology societies are updating treatment protocols to reflect expanded therapeutic equivalence confidence.
Consolidated purchasing by dialysis provider networks is displacing fragmented hospital procurement in volume concentration. Large operators in Germany negotiate direct manufacturer contracts, bypassing wholesale intermediaries. This channel compression is most advanced in integrated care systems where reimbursement bundles align drug and service payments.
Global Erythropoietin Stimulating Agents Market Segmentation
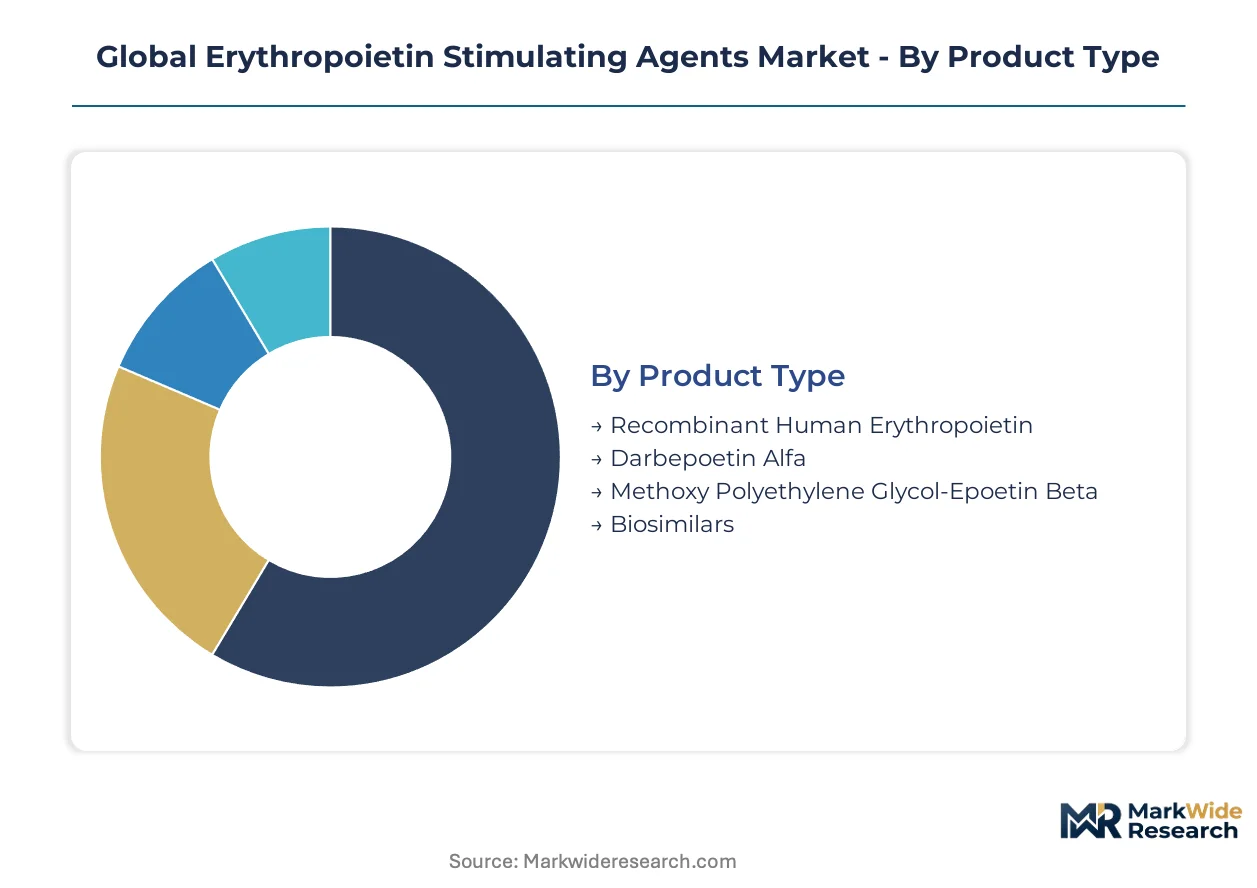
Erythropoietin stimulating agents fragment across molecular generations, clinical settings, and administration formats. Each dimension carries distinct reimbursement logic, regulatory requirements, and manufacturing constraints that reshape procurement decisions.
Product Type:
Mature recombinant platforms coexist with emerging biosimilar alternatives across pricing tiers.
- Recombinant Human Erythropoietin:First-generation molecules produced via Chinese hamster ovary cell culture retain established pharmacokinetic profiles. Dialysis centers in the United States specify these agents for patients with stable hemoglobin maintenance protocols.
- Darbepoetin Alfa:Hyperglycosylated variants extend half-life through additional N-linked carbohydrate chains. Oncology clinics in Germany favor this format for reduced dosing frequency in chemotherapy regimens.
- Methoxy Polyethylene Glycol-Epoetin Beta:PEGylated constructs enable monthly administration intervals. The extended dosing window appeals to home dialysis programs seeking to minimize clinic visits.
- Biosimilars:FDA and EMA-approved alternatives replicate originator glycosylation patterns through validated cell line engineering. Tender processes in Japan increasingly designate these agents for automatic substitution.
Recombinant human erythropoietin retains volume leadership; biosimilars hold the steepest expansion curve.
Therapy Area:
Application concentration varies by disease prevalence, reimbursement bundling, and treatment duration.
- Chronic Kidney Disease:Anemia correction in dialysis-dependent patients consumes the largest absolute volume. Bundled payment models in the United States align drug reimbursement with treatment episode costs.
- Chemotherapy-Induced Anemia:Platinum-based regimens in lung and ovarian cancer drive prophylactic ESA use. Oncology clinics in Japan prioritize hemoglobin thresholds above 10 g/dL for quality-of-life maintenance.
- HIV-Associated Anemia:Antiretroviral therapy complications sustain niche demand. Treatment protocols in South Africa integrate ESA support for zidovudine-related myelosuppression.
- Prematurity-Related Anemia:Neonatal intensive care units administer micro-doses to reduce transfusion exposure. German pediatric hematology societies specify weight-based algorithms for preterm infants.
Chronic kidney disease commands the dominant revenue pool; chemotherapy-induced anemia shows the fastest volume gain in oncology settings.
End User:
Channel structure determines procurement scale, inventory requirements, and cold chain investment.
- Dialysis Centers:Integrated provider networks in the United States negotiate multi-year supply agreements directly with manufacturers. These facilities administer ESAs three times weekly during hemodialysis sessions.
- Oncology Clinics:Outpatient chemotherapy suites require flexible dosing schedules aligned with treatment cycles. Japanese cancer centers maintain separate ESA inventories for platinum-sensitive tumor protocols.
- Hematology Laboratories:Hospital-based transfusion services manage ESA therapy for non-dialysis anemia. German university hospitals coordinate these programs with nephrology and oncology departments.
- Neonatal Care Units:Specialized dosing equipment and pharmacy compounding capabilities constrain participation to tertiary facilities. Preterm infant protocols in Ireland specify erythropoietin for birth weights below 1,500 grams.
Dialysis centers anchor procurement volume; oncology clinics are expanding most quickly through outpatient service growth.
Delivery Mode:
Administration format selection balances pharmacokinetic requirements with patient self-management capacity.
- Subcutaneous Injection:Home administration by peritoneal dialysis patients reduces facility burden. Prefilled pen devices in Japan incorporate dose memory and injection tracking.
- Intravenous Injection:Hemodialysis circuit integration enables nurse-administered dosing without additional venipuncture. United States dialysis chains specify IV formulations for in-center treatment.
- Intramuscular Injection:Limited contemporary use persists in settings lacking vascular access. Some German rehabilitation facilities retain this route for post-surgical anemia.
- Prefilled Syringes:Single-use formats minimize dosing errors and reduce pharmacy preparation time. Oncology clinics in France prioritize these devices for patient self-administration training.
Intravenous injection retains volume leadership in dialysis; prefilled syringes show the steepest adoption trajectory in home care expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA interchangeability designations anchor the United States as the dominant geography, with EMA and PMDA frameworks shaping competitive entry across Europe and Japan. Country-specific reimbursement bundling and biosimilar substitution rules create divergent procurement dynamics.
United States
Medicare bundled payment models sustain recurring ESA administration in dialysis-dependent populations. FDA interchangeability pathways grant automatic substitution rights at pharmacy level, accelerating biosimilar volume capture. Puerto Rico hosts concentrated bulk drug substance manufacturing, exposing supply chains to hurricane disruption.
Germany
Rising diabetes-driven chronic kidney disease caseloads expand dialysis center capacity requirements. EMA pharmacovigilance rules mandate pure red cell aplasia reporting, extending post-market compliance timelines. Integrated care systems in North Rhine-Westphalia negotiate direct manufacturer contracts, bypassing wholesale intermediaries.
Japan
PMDA accelerated approval frameworks for biosimilars expand prescriber confidence in oncology-linked anemia therapy. Prefilled pen devices with dose memory functions capture preference for self-administration. Tokyo metropolitan dialysis networks pilot long-acting ESA formulations to minimize clinic visit frequency.
China
Domestic biomanufacturing scale-up narrows reliance on imported erythropoietin stimulating agents. NMPA biosimilar guidelines align with ICH standards, streamlining regulatory convergence. Yangtze River Delta production clusters attract contract manufacturing investment under biologics-focused production-linked incentives.
India
CDSCO accelerated biosimilar approvals enable aggressive emerging market expansion. PLI scheme for biologics attracts export-oriented manufacturing investment. Hyderabad and Bangalore clusters specialize in recombinant protein engineering for cost-competitive supply.
Global Erythropoietin Stimulating Agents Market Competitive Landscape
Originator biologics specialists and biosimilar developers split the market across pricing tiers and regulatory complexity. The structure concentrates volume among integrated recombinant protein manufacturers with validated mammalian cell culture platforms. Three archetypes dominate: vertically integrated originators, emerging market biosimilar specialists, and contract manufacturing organizations. Competitive moves center on manufacturing scale expansion and regulatory pathway optimization for interchangeability designation.
Within the originator tier, Amgen Inc. and F. Hoffmann-La Roche Ltd occupy positions defined by recombinant protein production heritage and oncology anemia specialization. Biocon Ltd exemplifies the emerging market biosimilar archetype, competing through cost-engineered manufacturing scale.
| Leading Market Players |
|---|
| Amgen Inc. |
| F. Hoffmann-La Roche Ltd |
| Johnson & Johnson |
| Pfizer Inc. |
| Thermo Fisher Scientific |
| Sandoz Group AG |
| Teva Pharmaceutical Industries Ltd |
| Biocon Ltd. |
| Dr. Reddy's Laboratories Ltd. |
| Others |
Supply & Pricing Matrix
Puerto Rico's recombinant protein manufacturing cluster concentrates bulk drug substance output for North American dialysis chains, translating capacity scarcity into sustained pricing leverage for originator molecules against biosimilar encroachment. Mammalian cell culture facility utilization rates in this hub directly influence contract pricing tiers across integrated provider networks.
Pricing Analysis
Originator-biosimilar price spreads diverge most sharply between United States dialysis chains and German integrated care systems. Three-tier pricing structure across originator premium, designated-interchangeable biosimilars, and non-interchangeable alternatives captures reimbursement bundling differentials. Cost compression in the biosimilar tier is intensifying because FDA interchangeability designations accelerate automatic substitution. Dialysis center procurement teams show highest price sensitivity; oncology clinics maintaining hemoglobin protocols above 10 g/dL demonstrate lowest.
Supply Chain Analysis
Export-control regimes limiting recombinant protein technology transfer constrain capacity expansion in emerging manufacturing destinations. Bulk drug substance production clusters in Puerto Rico, Ireland, and Singapore, with fill-finish operations distributed across United States, Germany, and Japan. Chinese hamster ovary cell lines and serum-free culture media constitute critical input dependencies. Single-source vulnerability concentrates in hurricane-exposed Caribbean facilities. Distribution runs through direct manufacturer contracts with dialysis provider networks, displacing wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through dialysis provider network consolidation in the United States and Germany, shifting procurement leverage toward integrated systems capable of multi-year direct contracting. This fragmentation-to-consolidation dynamic restructures margin capture away from originators.
For Market Incumbents: Build regulatory moat through FDA interchangeability designation pursuit and EMA pharmacovigilance system mastery. Secure mammalian cell culture capacity in hurricane-resilient geographies to mitigate Puerto Rico concentration risk. Deepen backward integration into serum-free media production to buffer raw material volatility. For New Entrants and Emerging Players: Pursue WHO prequalification pathway for Sub-Saharan Africa tender access where chronic kidney disease diagnostics expansion outpaces supply infrastructure. Target home dialysis self-administration segments in Japan and Germany where prefilled syringe formats command premium positioning. Anchor go-to-market strategy through contract manufacturing partnerships with established cell culture platforms rather than greenfield facility investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biosimilar developers with validated glycosylation engineering capabilities and regulatory submission momentum. Long-term viability hinges on interchangeability designation achievement within the next technology refresh window. Acquisition target archetype: emerging market specialists with CDSCO or NMPA approvals and export-oriented manufacturing scale. Signal to monitor: FDA biosimilar interchangeability designation velocity for erythropoietin molecules.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA interchangeability designation unlocks automatic substitution rights in United States dialysis chains. |
| Manufacturing Scale-Up | Continuous perfusion cell culture platforms reduce capital intensity per gram of active pharmaceutical ingredient. |
| Long-term Supply Agreement | Direct contracts with German integrated care systems bypass wholesale intermediaries and secure volume. |
| Pipeline Diversification | Long-acting PEGylated formulations extend dosing intervals and capture home dialysis preference. |
| Strategic Partnership | Collaboration with Yangtze River Delta clusters leverages NMPA-aligned regulatory convergence for export supply. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA biosimilar approval databases, EMA assessment reports, and dialysis provider procurement records. Interviews with regulatory affairs leads, nephrology formulary directors, and mammalian cell culture facility operators informed supply-side dynamics. Hospital procurement managers and GPO contracts specialists provided demand-side validation. Bottom-up patient-volume modeling triangulated against top-down manufacturer revenue disclosures.
Forecast inputs incorporate therapy area prevalence trajectories, reimbursement bundling evolution, and biosimilar substitution elasticity across the analysis window. Segmentation dimensions span molecular generation, delivery mode, end-user channel, and regional regulatory cluster. CAGRs derive from logarithmic trend fitting of historical volume data adjusted for patent expiry and interchangeability designation timelines. Manufacturing capacity utilization and plasma-derived raw material cost indices feed industry-specific forecast sensitivity.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates, EMA pharmacovigilance stringency, or Chinese biologics export policy would shift the trajectory. Forecasts reflect documented assumptions on biosimilar uptake curves and dialysis center consolidation pace. Material shifts in FDA interchangeability designation criteria or hurricane-induced manufacturing disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Anthrax Treatment Market
Pharmaceuticals
Global Polio Vaccines Market
Pharmaceuticals
Pharmacy and Drug Store Franchises Market
Pharmaceuticals
Azathioprine API Market
Pharmaceuticals
Oral Antiviral Market
Pharmaceuticals
Peptide Therapeutics Market
Pharmaceuticals
Short-Acting Insulin Market
Pharmaceuticals
Global Preventive Vaccines Market
Pharmaceuticals
OX40 Receptor Agonist Market
Pharmaceuticals
Global Bendamustine Injection Market
Pharmaceuticals
Organ Transplant Immunosuppressant Drugs Market
Pharmaceuticals
Ceftriaxone Sodium (API) Market
Pharmaceuticals
Infliximab Market
Pharmaceuticals
Pharmacovigilance (PV) Market
Pharmaceuticals
Flumazenil Market
Pharmaceuticals
Rosuvastatin Market