
 Encephalitis Treatment Market | 2026-2036
Encephalitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Encephalitis Treatment Market Foresight
Good Clinical Practice certification under ICH E6(R2) is reorganizing which manufacturers can supply pivotal trial data for encephalitis therapeutics. Pfizer Inc. leverages its antiviral manufacturing scale to secure hospital formulary placement across North American neurocritical care networks. Roche Holding AG anchors its position through centralized laboratory diagnostics paired with therapeutic development. Merck & Co., Inc. competes on corticosteroid formulations optimized for blood-brain barrier penetration.
Encephalitis treatment encompasses pharmaceutical and supportive interventions targeting inflammation of the brain parenchyma, typically involving intravenous acyclovir at doses adjusted for renal function alongside adjunctive corticosteroid protocols to manage cerebral edema. The primary purpose is reduction of mortality and neurological sequelae through pathogen-specific antiviral action and immunomodulation. Antivirals command the largest revenue share due to mandatory empiric administration in suspected herpes simplex encephalitis before laboratory confirmation. Autoimmune encephalitis represents the fastest-expanding indication segment as diagnostic antibody panels improve detection of anti-NMDA receptor and other paraneoplastic syndromes. Intravenous delivery dominates hospital settings where therapeutic levels must be achieved rapidly in deteriorating patients.
FDA orphan drug designation and EMA PRIME eligibility criteria shape development prioritization for encephalitis indications by offering market exclusivity and accelerated assessment pathways. WHO prequalification standards influence procurement decisions in low-resource settings where Japanese encephalitis and tick-borne causes predominate. Stakeholders must monitor evolving biomarker-guided trial endpoints that could redefine regulatory evidence requirements for neuroprotective adjunct therapies.
Market Dynamics
FDA orphan drug designation and EMA PRIME eligibility are compressing development timelines for encephalitis therapeutics while concentrating manufacturing investment in facilities capable of producing intravenous immunoglobulin at clinical scale.
Growth Catalysts
- Accelerated Regulatory Pathways:FDA breakthrough therapy designation and EMA PRIME eligibility reduce time-to-market for novel encephalitis therapeutics by enabling rolling review processes.
- Autoimmune Diagnostic Expansion:Commercialization of anti-NMDA receptor antibody panels is expanding addressable patient populations beyond infectious etiologies.
- Neurocritical Care Infrastructure:Hospital construction of specialized neuro-ICU units in the United States, Germany, and Japan creates dedicated channels for advanced therapeutic administration.
Market Restraints
- Plasma Supply Concentration:Intravenous immunoglobulin production depends on fractionation facilities concentrated in the United States and European Union, creating geographic supply vulnerability.
- Blood-Brain Barrier Penetration:Large-molecule biologics face fundamental pharmacokinetic limitations restricting CNS bioavailability below therapeutic thresholds.
- Reimbursement Compression:Hospital formulary committees in Germany and Japan impose stringent cost-effectiveness thresholds on high-priced immunomodulatory therapies.
Strategic Opportunities
- Biomarker-Guided Trial Design:CSF neurofilament light chain quantification enables patient stratification for neuroprotective adjunct trials, potentially satisfying FDA accelerated approval endpoints.
- Subcutaneous Formulation Development:Transition from intravenous to subcutaneous immunoglobulin delivery opens outpatient administration channels and reduces hospital dependency.
- Tick-Borne Encephalitis Vaccination Integration:WHO prequalification pathways for Japanese encephalitis and tick-borne vaccines in Central European endemic regions create preventive-revenue streams alongside treatment markets.
Industry Challenges
- Neurocritical Care Specialist Shortage:Fellowship-trained neurointensivists remain concentrated in academic medical centers, limiting protocol standardization across community hospital systems.
- Laboratory Turnaround Variability:CSF metagenomic sequencing and autoimmune antibody panel processing times vary from 24 hours to 14 days, complicating empiric treatment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Encephalitis Treatment Market |
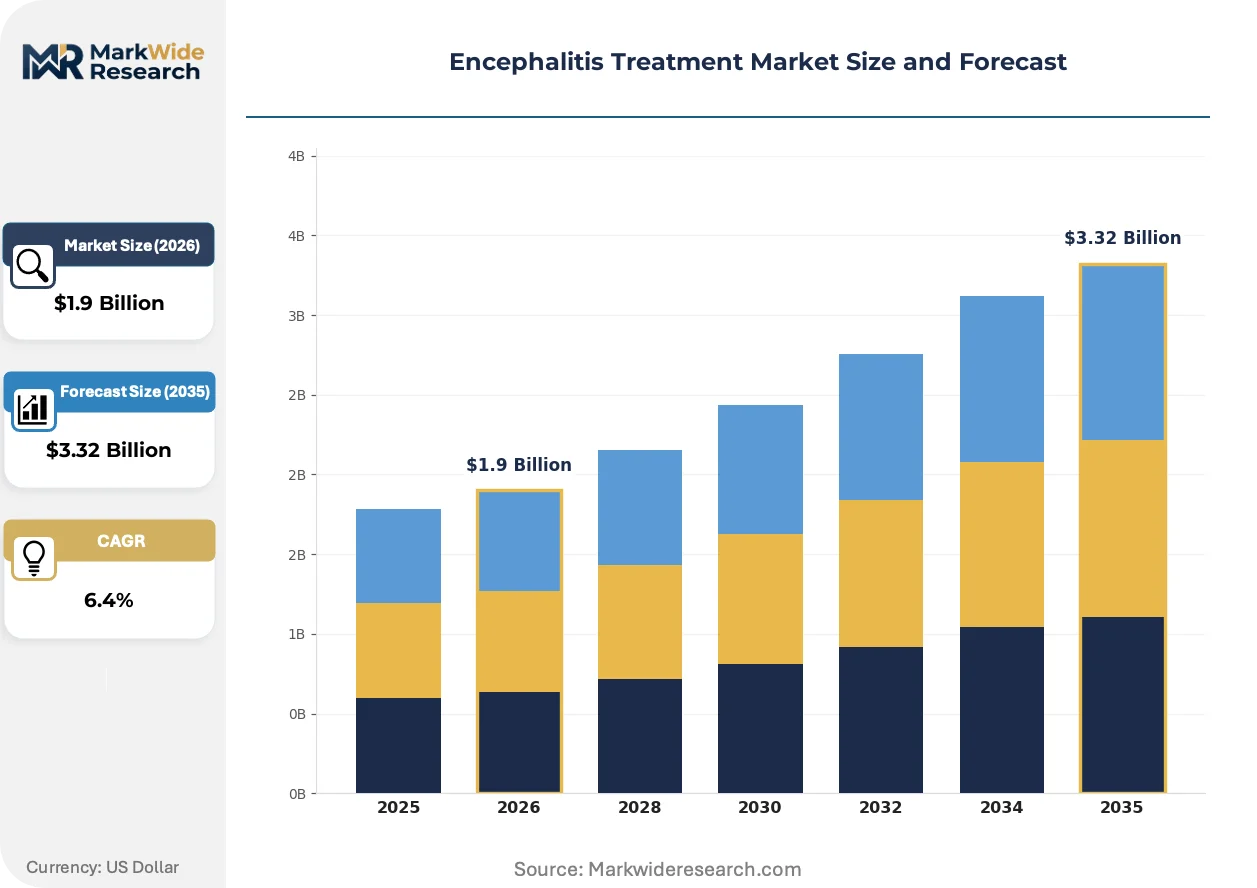
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $3.32 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antivirals, Corticosteroids, Immunoglobulins, Supportive Care Delivery Mode: Intravenous, Oral, Intraosseous, Intramuscular End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Indication: Viral Encephalitis, Autoimmune Encephalitis, Bacterial Encephalitis, Others |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Roche Holding AG, GlaxoSmithKline plc, Sanofi, Johnson & Johnson, Novartis AG, Abbott Laboratories, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Encephalitis Treatment Market Shifts & Advancements
Encephalitis therapeutics are converging on precision diagnostic integration and delivery modality innovation, with biomarker-guided protocols and alternative administration routes compressing traditional hospital-centric models.
Next-generation sequencing of cerebrospinal fluid is supplanting conventional viral culture and PCR panels as the frontline diagnostic modality in tertiary neurocritical care units. Academic medical centers in the United States and Germany are adopting metagenomic platforms capable of detecting bacterial, viral, fungal, and parasitic pathogens within 24-hour turnaround windows. This technology is compressing the diagnostic-therapeutic gap from days to hours, enabling pathogen-directed therapy initiation before laboratory confirmation.
EMA's Medical Device Regulation (MDR) and FDA's Software as a Medical Device (SaMD) guidance are tightening validation requirements for algorithmic diagnostic tools used in encephalitis differential diagnosis. Manufacturers of AI-assisted EEG interpretation and automated CSF analysis platforms must now submit clinical performance data demonstrating non-inferiority to neurologist interpretation. European hospital procurement committees are prioritizing MDR-certified devices, creating competitive separation between compliant and non-compliant suppliers.
Neurocritical care networks are consolidating purchasing decisions through centralized pharmacy and therapeutics committees rather than individual physician preference. Hospital systems in Japan and the United States are negotiating multi-year supply agreements for intravenous acyclovir and immunoglobulin products, displacing spot-market procurement. This concentration is most pronounced in integrated delivery networks controlling multiple neuro-ICU facilities across metropolitan regions.
Encephalitis Treatment Market Segmentation
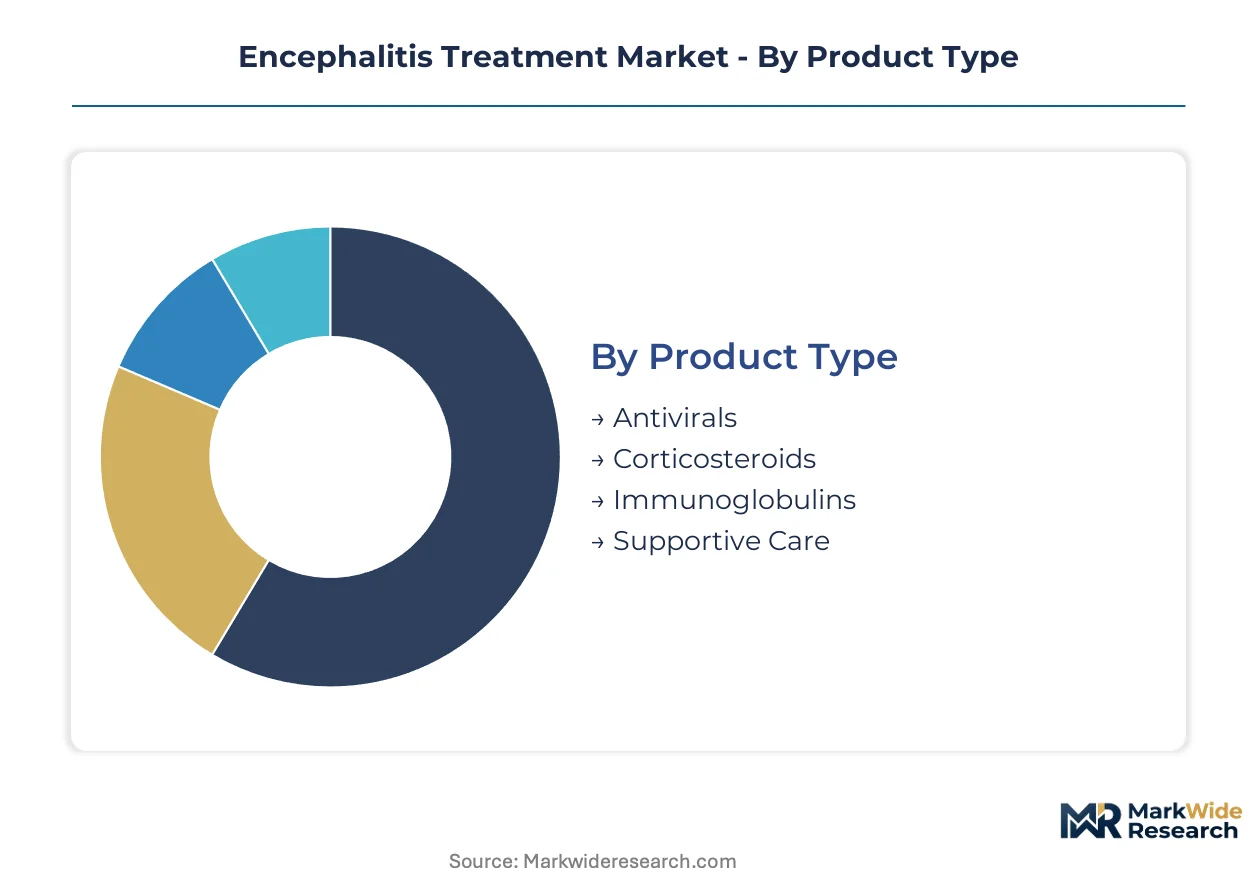
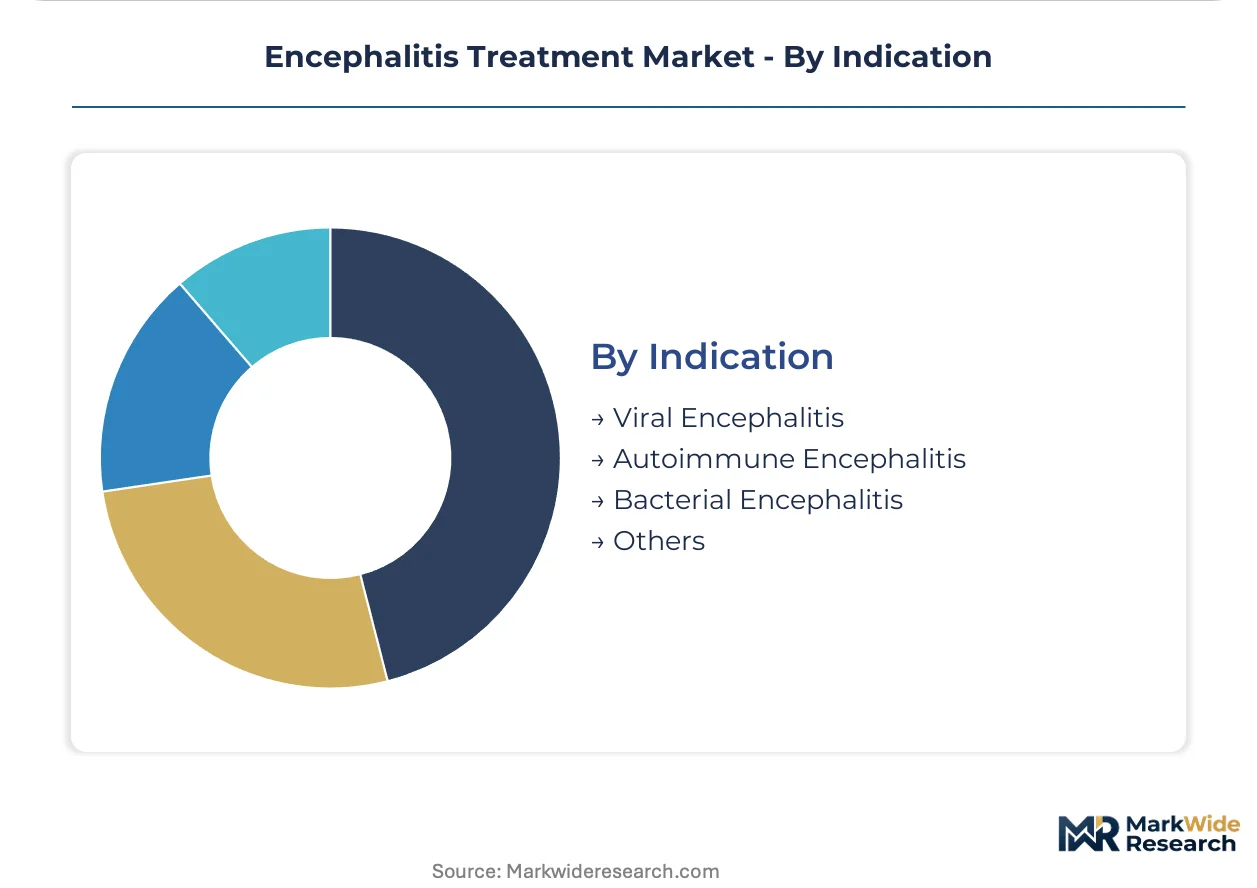
Encephalitis treatment segmentation reveals divergent margin structures across therapeutic modalities and care settings. Product type and indication categories concentrate value capture in hospital-based acute interventions, while delivery mode and end-user segments expose shifting economics toward outpatient channels.
Product Type:
Margin pools concentrate in immunomodulatory therapies where plasma-derived manufacturing creates supply-constrained pricing power.
- Antivirals:Acyclovir and ganciclovir formulations dominate empiric therapy protocols, with intravenous preparations commanding premium hospital pricing. United States neurocritical care networks mandate immediate administration before laboratory confirmation, locking in formulary placement.
- Immunoglobulins:Intravenous immunoglobulin fractionation requires specialized plasma collection infrastructure concentrated in the United States and European Union. Supply bottlenecks sustain elevated pricing despite biosimilar pressure.
- Corticosteroids:Dexamethasone and methylprednisolone protocols target cerebral edema management.
- Supportive Care:Anticonvulsants, sedatives, and fluid management adjuncts complete therapeutic regimens.
The dominant share belongs to Antivirals, while Immunoglobulins is closing the gap fastest as autoimmune indication detection expands.
Delivery Mode:
Volume concentration follows hospital admission patterns, though formulation innovation is redistributing economic value toward ambulatory-compatible routes.
- Intravenous:Hospital neuro-ICU administration achieves rapid therapeutic levels in deteriorating patients. German and Japanese reimbursement frameworks favor inpatient infusion for immunoglobulin therapies, preserving channel concentration.
- Oral:Valacyclovir prodrug formulations enable step-down therapy after initial stabilization. Outpatient conversion protocols in United States integrated delivery networks reduce length-of-stay costs.
- Intraosseous:Emergency vascular access for pediatric and hemodynamically unstable patients.
- Intramuscular:Limited application for specific antiviral and immunoglobulin loading doses.
Intravenous retains the largest volume position, though Oral formulations are gaining share fastest through early-discharge protocols.
End User:
Customer economics stratify sharply between capital-intensive acute facilities and distributed lower-acuity settings.
- Hospitals:Tertiary neurocritical care units in the United States, Germany, and Japan concentrate advanced therapeutic administration. Specialized infrastructure requirements—continuous EEG monitoring, mechanical ventilation, intracranial pressure management—create high barriers to entry.
- Home Care:Subcutaneous immunoglobulin and oral antiviral maintenance therapies expand addressable settings. United States home infusion providers negotiate direct contracts with payers for post-acute immunomodulatory administration.
- Clinics:Outpatient neurology practices manage stable autoimmune encephalitis patients.
- Rehabilitation Centers:Post-acute neurological recovery and sequelae management.
Hospitals command the dominant revenue share, while Home Care is expanding most quickly through subcutaneous formulation adoption.
Indication:
Diagnostic technology diffusion is resegmenting addressable populations between infectious and immune-mediated etiologies.
- Viral Encephalitis:Herpes simplex virus dominates confirmed cases, with mandatory empiric acyclovir administration driving treatment incidence. Japanese encephalitis and tick-borne causes concentrate in Central European and Asia-Pacific endemic regions per WHO surveillance.
- Autoimmune Encephalitis:Anti-NMDA receptor and anti-LGI1 antibody syndromes expand detectable populations as commercial diagnostic panels proliferate. Academic medical centers in Germany and the United States lead specialized testing volume.
- Bacterial Encephalitis:Listeria and mycobacterial causes in immunocompromised hosts.
- Others:Paraneoplastic, toxic-metabolic, and idiopathic etiologies.
Viral Encephalitis maintains the largest patient base, while Autoimmune Encephalitis shows the steepest expansion trajectory through diagnostic panel commercialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Johns Hopkins Hospital neurocritical care network anchors North American capacity for advanced encephalitis intervention. Germany's dense concentration of plasma fractionation facilities supplies intravenous immunoglobulin across European neuro-ICU networks. Japan's metropolitan hospital construction programs create dedicated channels for immunomodulatory therapy administration.
United States
FDA breakthrough therapy designation accelerates novel antiviral development timelines for herpes simplex encephalitis. The Orphan Drug Act grants seven-year market exclusivity for rare neurological indications, concentrating R&D investment in Massachusetts and California biotech clusters. Boston's Longwood Medical Area hosts specialized neurocritical care units that standardize empiric acyclovir protocols.
Germany
EMA PRIME eligibility enables rolling scientific advice for autoimmune encephalitis therapeutics, compressing regulatory assessment periods. The German Federal Institute for Drugs and Medical Devices enforces Good Manufacturing Practice standards for plasma-derived products manufactured in Marburg and Heidelberg. Bavaria's university hospital networks coordinate multi-site immunoglobulin trials through the German Center for Neurodegenerative Diseases.
Japan
PMDA's Sakigake designation system prioritizes review of innovative encephalitis diagnostics and therapeutics for rapid market entry. METI's healthcare infrastructure investment programs fund neuro-ICU construction in Tokyo, Osaka, and Nagoya metropolitan regions. The Kanto area concentrates specialized neurology referral centers that manage anti-NMDA receptor encephalitis case volumes.
United Kingdom
NICE technology appraisals impose cost-effectiveness thresholds on high-priced immunomodulatory therapies for autoimmune encephalitis. The Medicines and Healthcare products Regulatory Agency streamlined post-Brexit recognition pathways for EMA-approved neurological indications. London's National Hospital for Neurology and Neurosurgery anchors specialized diagnostic antibody testing capacity.
India
CDSCO accelerated approval pathways for Japanese encephalitis vaccines address endemic disease burden in Bihar and Uttar Pradesh. The National Viral Hepatitis Control Programme infrastructure extends to arboviral encephalitis surveillance in high-transmission districts. Maharashtra's public health laboratory network deploys metagenomic sequencing platforms for rapid pathogen identification.
Encephalitis Treatment Market Competitive Landscape
Listed leaders compete with private specialists across plasma supply security and diagnostic integration dimensions. The vendor base stratifies between diversified pharmaceutical conglomerates with antiviral manufacturing scale and specialized biologics producers focused on immunoglobulin fractionation. Three archetypes dominate: plasma-derived biologics specialists, antiviral API manufacturers, and integrated diagnostic-therapeutic platforms. Competitive moves center on securing hospital formulary placement through multi-year supply agreements and acquiring metagenomic sequencing capabilities for precision diagnostic bundling.
Within the integrated pharmaceutical tier, Pfizer Inc., Merck & Co., Inc., and Roche Holding AG exemplify divergent strategic positioning. Pfizer leverages manufacturing scale to secure North American neurocritical care network contracts. Merck occupies a position emphasizing corticosteroid formulation expertise for cerebral edema management. Roche anchors its presence through centralized laboratory diagnostics paired with therapeutic development pipelines. These three entities represent distinct competitive vectors: manufacturing scale, formulation specialization, and diagnostic integration.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Roche Holding AG |
| GlaxoSmithKline plc |
| Sanofi |
| Johnson & Johnson |
| Novartis AG |
| Abbott Laboratories |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Supply & Pricing Matrix
FDA orphan drug designation and EMA PRIME eligibility gates both supply qualification and price differentiation simultaneously, concentrating manufacturing investment in facilities capable of clinical-scale intravenous immunoglobulin production while enabling premium pricing for accelerated-approval therapeutics.
Pricing Analysis
Volume-discount tiering structures separate plasma-derived immunoglobulin lots by purity grade and collection source geography, with United States-sourced fractionated products commanding premium positioning over European alternatives. Price differentiation hinges on FDA lot-release certification and hospital formulary exclusivity duration. Cost compression in standard-grade acyclovir generics is intensifying because of Indian API manufacturer entry. Community hospital systems exhibit highest price sensitivity, while academic medical centers prioritize supply security over unit cost.
Supply Chain Analysis
The United States and Germany anchor plasma collection and fractionation infrastructure, producing clinical-scale immunoglobulin for neurocritical care networks. Manufacturing draws from specialized donor plasma, viral inactivation reagents, and cold-chain logistics capacity. Single-source vulnerability concentrates in United States plasma collection centers exposed to regional health disruptions. Distribution runs through hospital centralized pharmacy committees negotiating multi-year supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autoimmune encephalitis diagnostic expansion represents a high-growth disruption, with anti-NMDA receptor antibody panel commercialization compressing diagnostic-therapeutic timelines and expanding addressable patient populations beyond infectious etiologies.
For Market Incumbents: Secure plasma supply contracts through backward integration into collection center networks, insulating against United States geographic concentration risk. Acquire metagenomic sequencing capabilities to bundle precision diagnostics with therapeutic portfolios, defending against diagnostic-therapeutic platform competitors.
For New Entrants and Emerging Players: FDA breakthrough therapy designation fast-tracks enable rolling review processes for novel neuroprotective adjuncts, opening regulatory pathways. Target subcutaneous immunoglobulin formulation development as the most penetrable segment, leveraging outpatient administration channels to bypass hospital formulary gatekeeping.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across plasma-derived biologics manufacturing, favoring scaled incumbents. Five-to-ten year viability favors integrated diagnostic-therapeutic platforms with hospital system partnerships. Monitor CSF neurofilament light chain biomarker adoption rates as inflection indicator for neuroprotective adjunct market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | United States and German fractionation facilities secure supply-constrained immunoglobulin pricing power. |
| Metagenomic Diagnostic Integration | CSF sequencing platforms enable pathogen-directed therapy before laboratory confirmation. |
| Subcutaneous Formulation Development | Outpatient immunoglobulin administration reduces hospital dependency and length-of-stay costs. |
| Autoimmune Antibody Panel Partnership | Anti-NMDA receptor testing expands addressable patient populations beyond viral etiologies. |
| Neurocritical Care Network Contracting | Multi-year supply agreements with integrated delivery networks lock in formulary placement. |
Research Methodology
Desk research of FDA orphan drug filings, EMA PRIME eligibility databases, and hospital procurement records preceded structured interviews with neurocritical care pharmacists, plasma fractionation operations directors, and autoimmune diagnostic laboratory managers. Secondary validation drew from ClinicalTrials.gov entries, formulary database extracts, and WHO prequalification standards. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Variance-decomposition across product type, indication category, delivery mode, and end-user segments shaped the analytical framework throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Forecast inputs incorporated neuro-ICU construction pipeline data and autoimmune diagnostic panel commercialization timelines.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory pathway acceleration and plasma supply stability; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding reimbursement framework continuity and diagnostic technology diffusion rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Lysosomal Storage Disease Treatment Market
Medical Treatment
US and Japan Platelet Rich Plasma Market
Medical Treatment
Isovaleric Acidemia Treatment Market
Medical Treatment
Avian Flu Treatment Market
Medical Treatment
Mast Cell Tumors Treatment Market
Medical Treatment
Non-Invasive Surgery Market
Medical Treatment
Lysosomal Acid Lipase (LAL) Deficiency Treatment Market
Medical Treatment
Facial Spasm Treatment Market
Medical Treatment
Kidney Stones Management Market
Medical Treatment
Europe Lysosomal Disease Treatment Market
Medical Treatment
Neglected Tropical Disease Treatment Market
Medical Treatment
Hypogonadism Treatment Market
Medical Treatment
Disseminated Intravascular Coagulation (DIC) Treatment Market
Medical Treatment
Mesenteric Penniculitis Treatment Market
Medical Treatment
Rett Syndrome Treatment Market
Medical Treatment
Vulvodynia Treatment Market