
 Anaphylaxis Treatment Market | 2026-2036
Anaphylaxis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Anaphylaxis Treatment Market Analysis
Market Context
North American pharmaceutical manufacturing capacity is repositioning toward high-volume epinephrine auto-injector production. Viatris Inc. leverages vertical integration across generic injectables to sustain cost competitiveness in institutional channels. Teva Pharmaceutical Industries Ltd. anchors its position through specialized manufacturing of complex parenteral formulations. ALK-Abelló A/S differentiates via concentrated R&D in immunotherapy adjuvants alongside emergency treatment portfolios.
Technical Definition and Segment Structure
Anaphylaxis treatment encompasses pharmacological interventions designed to counteract acute systemic allergic reactions, primarily through epinephrine formulations delivered via auto-injectors containing precise concentrations such as 0.15 mg or 0.3 mg doses calibrated by patient weight. These therapies function to reverse bronchoconstriction, vasodilation, and cardiovascular collapse within minutes of administration. Auto-injectors command the dominant product position due to reliability in non-clinical settings, while intravenous solutions capture concentrated margin pools within hospital resuscitation protocols. Subcutaneous and intramuscular delivery modes lead volume flows, though intramuscular administration is gaining preference for faster systemic absorption in emergency protocols.
Regulatory Framework
FDA device classification rules, EMA MDR requirements, and ISO 11608 needle-based injection system standards collectively shape auto-injector design validation and post-market surveillance obligations. These frameworks elevate barriers for new entrants while compelling incumbents to maintain dedicated regulatory affairs capacity across multiple jurisdictions. Stakeholders must monitor evolving pediatric dosing guidelines and school-based access legislation as determinants of replacement volume and brand loyalty.
Market Dynamics
Hospital emergency departments are expanding epinephrine administration training protocols, creating a structural pull that is reshaping device specifications and procurement volumes across institutional channels. This force is compressing replacement cycles while elevating performance requirements for auto-injector reliability.
Growth Catalysts
- School-Based Access Mandates:State-level legislation in the United States requires stockpiled epinephrine in educational institutions, institutionalizing replacement demand and expanding addressable patient populations beyond diagnosed individuals.
- ISO 11608 Design Standards:Harmonized international needle-based injection system specifications are streamlining cross-border device approvals, reducing regulatory friction for manufacturers pursuing multi-jurisdictional launches.
- Pediatric Allergy Prevalence:Diagnostic expansion in North American clinical settings is generating sustained demand for weight-calibrated 0.15 mg and 0.3 mg dose formulations across ambulatory care networks.
Market Restraints
- API Supply Concentration:Epinephrine active pharmaceutical ingredient production clusters in a limited number of specialized chemical synthesis facilities, exposing finished device manufacturers to input volatility and qualification delays.
- FDA Device Classification Rigor:Combination product designation for auto-injectors triggers dual Center for Drug Evaluation and Research and Center for Devices and Radiological Health review pathways, extending development timelines and elevating compliance costs.
- Thermal Stability Requirements:Epinephrine degradation sensitivity necessitates cold chain infrastructure and temperature excursion monitoring, constraining distribution reach into resource-limited settings.
Strategic Opportunities
- Connected Device Integration:Bluetooth-enabled auto-injectors with dose confirmation and caregiver notification capabilities are opening premium positioning in pediatric and geriatric segments where supervision gaps persist.
- Pre-Hospital Emergency Services:Expanded paramedic scope-of-practice protocols in several United States jurisdictions are creating dedicated procurement channels for high-dose intramuscular formulations outside traditional pharmacy distribution.
- EMA MDR Transition Window:Stricter European Medical Device Regulation conformity assessment requirements are accelerating market exit of non-compliant suppliers, concentrating share among established notified body relationships.
Industry Challenges
- Needle Retraction Engineering:Passive safety mechanism design complexity is extending product development cycles and elevating failure-mode testing burdens for mechanical engineering teams.
- Human Factors Validation:FDA human factors engineering guidance demands extensive user studies across age, dexterity, and stress-condition cohorts, compressing margins on pipeline products.
- Legacy Device Obsolescence:Established installed bases of first-generation auto-injectors require careful phase-out management to maintain patient continuity while transitioning to enhanced-format replacements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anaphylaxis Treatment Market |
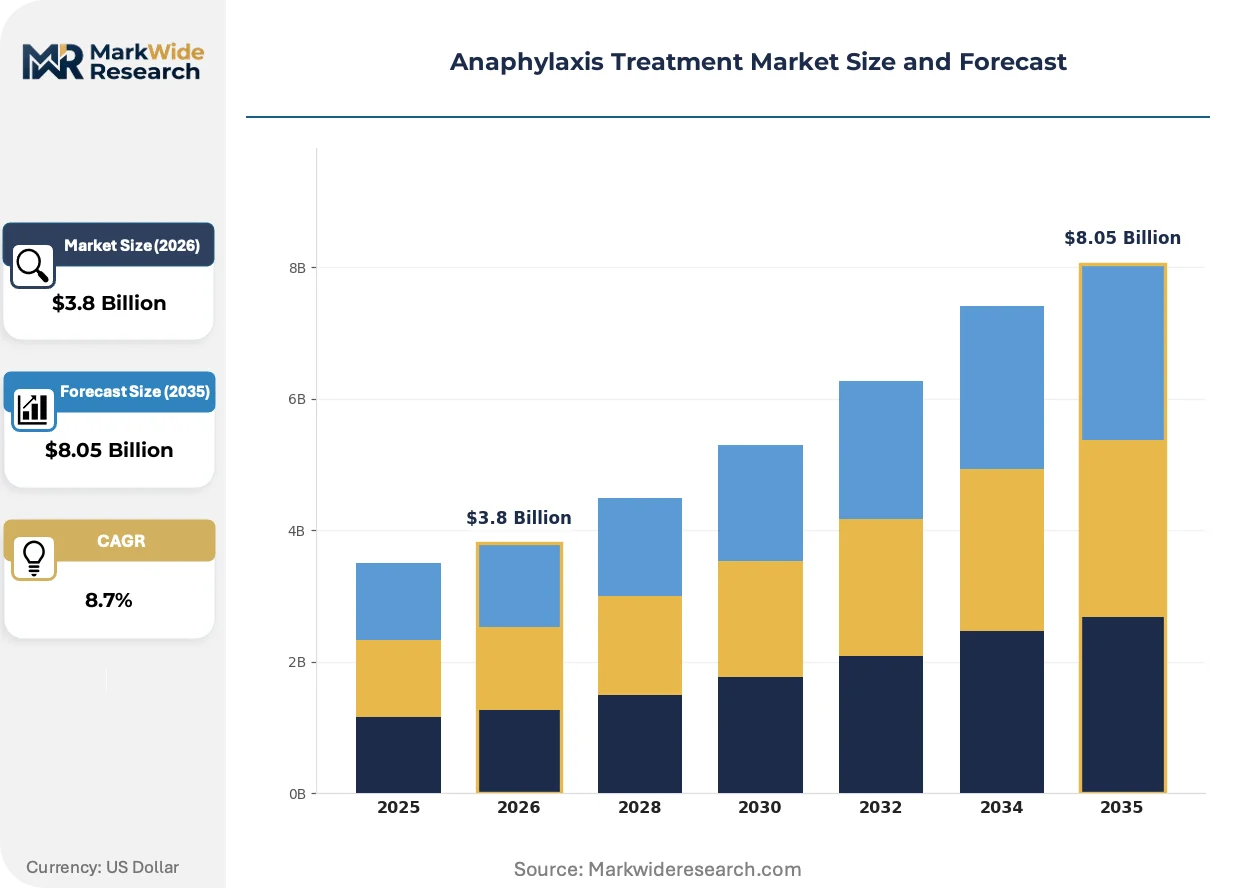
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Auto-Injectors, Inhalers, Oral Tablets, Intravenous Solutions Delivery Mode: Subcutaneous, Intramuscular, Oral, Intravenous End User: Hospitals, Clinics, Emergency Services, Home Care Age Group: Adults, Children, Infants, Elderly |
| Companies Covered | Viatris Inc., Teva Pharmaceutical Industries Ltd., GlaxoSmithKline Plc., Pfizer Inc., Amneal Pharmaceuticals Inc., Merck & Co., Inc., Adamis Pharmaceutical Corporation, ALK-Abelló A/S, Amphastar Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anaphylaxis Treatment Market Emerging Trajectories
Digital connectivity and dose-precision engineering are converging to redefine patient and caregiver interaction models with emergency allergy therapeutics. These developments are compressing the window between symptom onset and effective intervention while generating new data assets for clinical outcome tracking.
Electromechanical auto-injector platforms with integrated sensors and dose-confirmation feedback are automating the injection process for patients with limited manual dexterity or cognitive impairment. Pediatric allergy specialists in United States academic medical centers are piloting these devices for school-age patients. The technology is automating adherence verification and reducing caregiver anxiety around proper administration technique.
EMA MDR Article 10 post-market surveillance requirements are mandating systematic device performance monitoring and periodic safety update reporting across European Economic Area markets. Manufacturers must now maintain dedicated pharmacovigilance infrastructure capable of capturing real-world failure events. Hospital procurement committees in Germany and France are prioritizing suppliers with demonstrated post-market data transparency.
Direct-to-patient subscription models for auto-injector replacement and expiration management are disrupting traditional pharmacy-centric dispensing patterns. Allergy immunology practices in the United States are consolidating device procurement through specialty distributor arrangements that bundle training and inventory management. This channel evolution is most visible in suburban metropolitan markets where patient density supports consolidated delivery logistics.
Anaphylaxis Treatment Market Segmentation
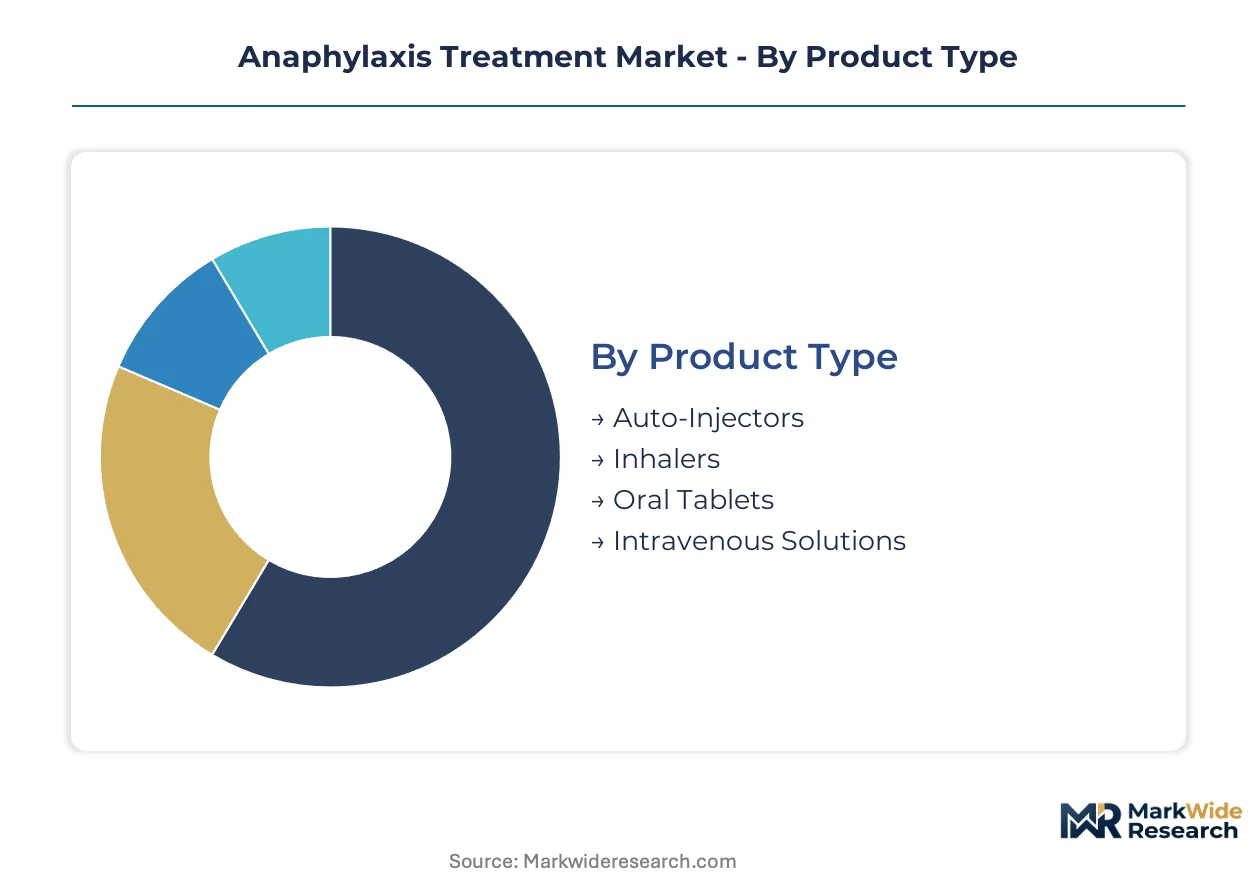
Segmentation in the anaphylaxis treatment market reveals how device specifications, delivery protocols, and patient demographics create distinct procurement channels. Manufacturers calibrate production capacity across these dimensions to match replacement cycles driven by expiration management and pediatric diagnostic expansion.
Product Type:
Replacement cycles vary sharply by product format, with auto-injectors commanding the shortest refresh intervals due to mandated expiration dates and school stockpile requirements.
- Auto-Injectors:Spring-loaded mechanical devices containing pre-measured epinephrine doses of 0.15 mg or 0.3 mg calibrated by patient weight. Demand concentrates in United States K-12 institutional procurement channels where state legislation mandates stockpiled inventory and drives systematic replacement programs.
- Intravenous Solutions:Hospital-grade concentrated epinephrine formulations for emergency department resuscitation protocols. United States academic medical centers are expanding centralized pharmacy compounding of these solutions to reduce per-dose costs amid formulary pressure.
- Inhalers:Bronchodilator adjunct therapies for respiratory symptom management in anaphylaxis cascades.
- Oral Tablets:Antihistamine and corticosteroid follow-on medications for secondary symptom suppression post-epinephrine administration.
Auto-Injectors sit at the top of the volume ranking, with Intravenous Solutions climbing the fastest as hospital emergency departments expand epinephrine administration training protocols.
Delivery Mode:
Cost tier differentiation separates high-reliability mechanical systems from simpler pharmaceutical formats, with reimbursement rates scaling to intervention speed and administration setting.
- Intramuscular:Thigh-delivered injection achieving peak plasma concentration within 5-15 minutes through vastus lateralis or anterolateral thigh muscle absorption. United States emergency medical services protocols are expanding paramedic scope-of-practice to include high-dose intramuscular administration outside hospital settings.
- Subcutaneous:Slower-absorption injection method historically standard for epinephrine delivery, now being displaced by intramuscular protocols in updated clinical guidelines.
- Intravenous:Direct vascular delivery reserved for cardiac arrest presentations in hospital resuscitation bays.
- Oral:Delayed-onset pharmaceutical delivery for non-critical symptom management following primary epinephrine intervention.
Intramuscular administration captures the dominant share of new device approvals, while Intravenous delivery maintains premium positioning in critical care margin pools.
End User:
Application context determines device specification requirements, with pre-hospital settings demanding mechanical reliability under stress conditions and institutional settings prioritizing inventory integration.
- Emergency Services:Paramedic and emergency medical technician deployment of high-dose formulations in ambulance and field settings. Several United States jurisdictions are revising scope-of-practice regulations to expand epinephrine administration authority beyond traditional physician oversight.
- Hospitals:Emergency department and inpatient unit stocking of multi-dose vials and auto-injectors for immediate anaphylaxis response.
- Clinics:Allergy specialist offices and urgent care centers maintaining on-site emergency epinephrine for immunotherapy and diagnostic procedure complications.
- Home Care:Patient and caregiver-controlled auto-injector possession for known allergen exposure risk management.
Emergency Services is expanding most quickly through pre-hospital protocol expansion, with Hospitals retaining the largest absolute procurement volumes.
Age Group:
Customer type segmentation drives dose calibration and human factors engineering requirements, with pediatric populations necessitating specialized device formats and training ecosystems.
- Children:School-age patients requiring weight-calibrated 0.15 mg auto-injector doses and caregiver supervision protocols. United States pediatric allergy prevalence is generating sustained replacement demand through diagnostic expansion in suburban metropolitan clinical networks.
- Adults:Working-age patients with occupational and environmental allergen exposures managing self-administration in workplace and travel contexts.
- Infants:Highest-risk population requiring precise dosing and parental administration training with specialized device formats.
- Elderly:Growing segment with comorbid cardiovascular conditions complicating epinephrine risk-benefit calculations and dosing decisions.
Children represents the fastest-growing addressable population through school-based access mandates, with Adults maintaining the largest installed base of diagnosed patients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing auto-injector manufacturing capacity toward jurisdictions with streamlined combination-product review pathways, as FDA dual-center oversight elevates compliance costs relative to EMA MDR transition windows.
United States
School-based epinephrine stockpile mandates in 46 states institutionalize replacement demand through systematic procurement cycles. FDA Center for Drug Evaluation and Research maintains stringent human factors validation requirements for pediatric dose formats. Boston's cluster of allergy immunology academic medical centers pilots connected-device protocols for school-age patient monitoring.
Germany
EMA MDR Article 10 post-market surveillance obligations concentrate market share among manufacturers with established notified body relationships. BfArM pharmacovigilance infrastructure captures real-world device failure events with systematic rigor. The Rhine-Ruhr industrial corridor hosts specialized mechanical engineering suppliers for auto-injector safety mechanism components.
United Kingdom
MHRA post-Brexit regulatory autonomy permits accelerated approval pathways for ISO 11608-compliant devices with existing EMA certifications. NHS England allergy service expansion drives diagnostic capacity in suburban clinical networks. The Cambridge-Oxford-London triangle concentrates pediatric allergy research capacity and connected-device pilot programs.
Japan
PMDA combination product designation rules align with FDA rigor, limiting new entrant penetration in favor of established multinational submissions. METI industrial policy supports domestic pharmaceutical manufacturing capacity for critical emergency medicines. The Osaka-Kobe pharmaceutical production zone maintains specialized parenteral formulation capabilities.
Australia
TGA priority review pathways for essential medicines accelerate market access for epinephrine auto-injectors with demonstrated thermal stability profiles. Federal school medication authority guidelines expand institutional procurement beyond diagnosed patient populations. Melbourne's biomedical research precinct advances human factors engineering studies for geriatric administration scenarios.
Anaphylaxis Treatment Market Vendor Landscape
United States producers anchor the high-volume institutional tier; European specialists hold premium positioning through immunotherapy-adjacent portfolios. The market exhibits moderate consolidation around vertically integrated generic injectable manufacturers and dedicated allergy therapeutic developers. Three archetypes dominate: scale-driven pharmaceutical conglomerates with auto-injector line extensions, mid-cap device engineering specialists, and immunology-focused biotech firms with emergency treatment adjacencies. Capacity expansion and strategic portfolio diversification constitute the dominant competitive moves, as incumbents broaden dose-format ranges and geographic label claims.
Among United States-based pharmaceutical manufacturers, Viatris Inc., Teva Pharmaceutical Industries Ltd., and Amphastar Pharmaceuticals Inc. exemplify the scale-driven archetype through captive supply chain control over generic injectable production. These entities occupy positions where vertical integration into active pharmaceutical ingredient sourcing and specialized parenteral formulation manufacturing supports cost competitiveness in high-volume institutional channels. Their market presence reflects the structural advantage of dedicated regulatory affairs capacity spanning FDA and EMA jurisdictions.
| Leading Market Players |
|---|
| Viatris Inc. |
| Teva Pharmaceutical Industries Ltd. |
| GlaxoSmithKline Plc. |
| Pfizer Inc. |
| Amneal Pharmaceuticals Inc. |
| Merck & Co., Inc. |
| Adamis Pharmaceutical Corporation |
| ALK-Abelló A/S |
| Amphastar Pharmaceuticals Inc. |
| Others |
Supply Flow & Price Mechanics
Family-owned API synthesis specialists in India and China anchor epinephrine bulk manufacturing, their concentrated ownership structures enabling long-term supply contracts that buffer finished-device manufacturers from spot-market volatility while constraining pricing flexibility for downstream formulation players.
Pricing Analysis
Distributor margin compression in United States institutional channels is intensifying as GPOs consolidate procurement volumes for auto-injector replacement programs. Three-tier pricing structure across premium connected devices, standard mechanical auto-injectors, and economy generic alternatives separates hospital formulary tiers, with ISO 11608 certification level and thermal stability profile serving as primary differentiation drivers. Pricing pressure stems from Medicaid rebate obligations and 340B program expansion, squeezing net realized prices for manufacturers serving public-sector channels. School district procurement committees exhibit highest price sensitivity, while pediatric allergy specialists in academic medical centers prioritize device reliability over unit cost.
Supply Chain Analysis
Expired auto-injector return flows through reverse logistics networks are concentrated in United States pharmaceutical reverse distributors, whose refurbishment capabilities remain limited due to FDA combination product designation restrictions on device reuse. API production clusters in India, China, and the United States, with epinephrine bitartrate synthesis drawing from specialized catecholamine chemical processing infrastructure. Single-source vulnerability pervades spring mechanism and needle assembly component supply, with precision metal stamping concentrated in German and Swiss industrial zones. Distribution runs through specialty pharmaceutical wholesalers with cold chain certification, bypassing general merchandise channels due to temperature excursion liability exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, where FDA and EMA device classification milestones institutionalize replacement demand through mandated expiration cycles and post-market surveillance obligations.
For Market Incumbents: Deploy human factors engineering capacity as a defensive moat against emerging connected-device entrants, accelerating pediatric dose-format validation to preempt regulatory headroom capture. Consolidate positions through backward integration into API synthesis, securing qualified supply against Indian and Chinese input volatility. Counter margin compression in institutional channels by bundling training and inventory management services with device procurement contracts. For New Entrants and Emerging Players: EMA MDR Article 10 post-market surveillance requirements in Germany and France open a window for compliance-native entrants to displace legacy suppliers lacking systematic pharmacovigilance infrastructure. Target pre-hospital emergency services procurement channels in United States jurisdictions expanding paramedic scope-of-practice, where established pharmacy-centric distribution relationships carry less weight. Pursue direct-to-patient subscription models in suburban metropolitan markets, bypassing traditional GPO-dominated hospital procurement. For Investors and Strategic Acquirers: Generic injectable conglomerates are the most active acquirer in this space, seeking device engineering capabilities to complement parenteral formulation expertise. Five-to-ten year viability hinges on regulatory affairs capacity depth across FDA and EMA jurisdictions, making mid-cap specialists with dual-center submission experience prime acquisition targets. Monitor state-level school stockpile legislation expansion as inflection indicator for replacement volume acceleration beyond diagnosed patient populations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Combination Product Submission | Dual CDER/CDRH review pathway secures pediatric auto-injector market access in United States academic medical centers. |
| EMA MDR Notified Body Engagement | Established conformity assessment relationships concentrate European market share among compliant manufacturers in Germany and France. |
| Hospital System Partnership | Integrated procurement contracts with GPOs lock in replacement volume through mandated expiration management programs. |
| Connected Device Software Development | Bluetooth-enabled dose confirmation opens premium positioning in pediatric segments where caregiver notification gaps persist. |
| Reimbursement Strategy Formulation | Medicaid and commercial payer coverage expansion determines addressable patient population beyond self-pay segments. |
Methodological Framework
Multiple input streams — primary interviews with regulatory affairs directors, hospital procurement managers, and allergy immunology specialists; secondary validation against FDA 510(k) filings, EMA MDR submissions, and ClinicalTrials.gov records; and bottom-up and top-down triangulation — were reconciled to construct segment-level demand estimates and competitive positioning assessments.
Historical shipment data were cross-referenced against panel input from device engineering executives and GPO contract administrators to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product format, delivery mode, end-use setting, and age-specific dosing requirements, with CAGRs derived from replacement cycle analysis and pediatric diagnostic expansion trajectories. Thermal stability profile validation and ISO 11608 compliance status served as industry-specific forecast modifiers.
Revisions become necessary when API supply disruptions, regulatory guidance shifts on pediatric dosing, or school stockpile mandate repeals materialize beyond baseline assumptions. Practitioners should monitor notified body capacity constraints in Europe and FDA combination product review timeline extensions for early signals of market access friction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Ligament Repair and Reconstruction Market
Medical Treatment
Migraine Treatment Market
Medical Treatment
Hypothermia Management Market
Medical Treatment
Angelman Syndrome Treatment Market
Medical Treatment
Global Rotator Cuff Treatment Market
Medical Treatment
Necrotizing Skin Infections Treatment Market
Medical Treatment
Non-Invasive Surgery Market
Medical Treatment
Influenza Treatment Market
Medical Treatment
Single Dose Radiotherapy Services Market
Medical Treatment
Dementia Treatment Market
Medical Treatment
Anti-Fungal Treatment Market
Medical Treatment
Non-Infectious Diarrhea Treatment Market
Medical Treatment
Nose Reconstruction Market
Medical Treatment
Encephalitis Treatment Market
Medical Treatment
Amyloidosis Treatment Market
Medical Treatment
Global Plasma Therapy Market