
 Iron and Steel Slag Market | 2026-2036
Iron and Steel Slag Market Size, Share, and Industry Trends Forecast 2026-2036
Iron and Steel Slag Market Analysis
Aftermarket service revenue from slag processing and beneficiation is fragmenting across regional operators and captive steel mill units. ArcelorMittal leverages its integrated European processing network to retain value from blast furnace slag. Tata Steel anchors South Asian supply through dedicated granulation facilities serving cement partners. Nippon Steel Corporation differentiates via advanced air-cooled product lines for high-specification construction applications.
Iron and steel slag comprises calcium-aluminosilicate residues generated during pyrometallurgical reduction and refining, with blast furnace slag typically containing 35-40% calcium oxide and exhibiting latent hydraulic properties when finely ground. Blast furnace slag dominates value capture in cement production, where its pozzolanic reactivity reduces clinker substitution costs. Steelmaking slag occupies a narrower but expanding niche in road base applications, driven by aggregate scarcity and specifications favoring high-friction surface courses. Granulation technology leads processing investment, though air-cooled output still commands premium pricing in select geotechnical fill markets.
EPA beneficial use determinations under the Resource Conservation and Recovery Act shape US market access for slag-derived construction materials. REACH registration requirements and the EU Green Deal circular economy action plan govern European material classification and cross-border shipment protocols. China's MEE solid waste management standards and dual carbon goals are tightening disposal pathways while incentivizing qualified reuse. Stakeholders must monitor evolving carbon accounting methodologies that could recategorize slag from waste to coproduct, altering liability structures and offtake contracting terms.
Market Dynamics
The Iron and Steel Slag Market is being fundamentally restructured by the EU Green Deal's carbon border adjustment mechanism, which reclassifies slag from waste to regulated coproduct and redirects steel mill output streams toward cement industry offtake under circular economy mandates.
Growth Catalysts
- EU Green Deal Circular Economy Action Plan:Binding reuse targets for industrial byproducts are forcing cement manufacturers across Germany, France, and Poland to secure granulated blast furnace slag supply contracts, displacing clinker imports.
- India's infrastructure buildout:Dedicated freight corridors, metro rail expansion, and highway construction are concentrating demand for slag-based Portland pozzolana cement in Maharashtra, Gujarat, and Tamil Nadu.
- Granulation technology deployment:Dry granulation systems are capturing latent hydraulic value from blast furnace slag that previously entered unprocessed landfill streams, unlocking material for high-specification concrete applications.
Market Restraints
- Blast furnace capacity concentration:European steel production consolidation around integrated coastal mills in Belgium and the Netherlands is narrowing slag source diversity and amplifying supply disruption risk for inland cement plants.
- Natural aggregate price volatility:River sand mining restrictions across Southeast Asia are compressing slag price competitiveness in road base applications where unprocessed steelmaking slag competes directly with crushed stone.
- Heavy metal leaching thresholds:EPA beneficial use determinations under RCRA Subtitle D impose batch-testing burdens on slag-derived construction materials that delay project approvals and elevate compliance costs for US distributors.
Strategic Opportunities
- Carbon capture integration:Mineral carbonation of steelmaking slag is hybridizing with existing granulation infrastructure to produce carbon-negative aggregates, attracting offtake interest from net-zero committed developers in Sweden and Finland.
- Underpenetrated geographies:Vietnam, Indonesia, and the Philippines lack domestic granulation capacity despite accelerating steel output, creating import substitution potential for regional processors with blast furnace slag beneficiation expertise.
- Geotechnical fill specification expansion:Japan's MLIT is revising harbor and coastal defense material standards to permit air-cooled slag in marine environments, opening volume outlets for high-density slag products previously limited to land-based construction.
Industry Challenges
- Metallurgical quality control:Free lime and iron oxide variability in steelmaking slag requires real-time XRF monitoring and batch segregation that strains operator technical capacity at smaller processing facilities.
- Cross-border shipment protocols:REACH registration gaps for slag-derived products moving between EU member states and candidate countries are generating customs delays and forcing redundant testing expenditures.
- Legacy disposal liability:Historical slag dumps in industrial regions of Pennsylvania and Ohio carry unresolved groundwater monitoring obligations that complicate site redevelopment and deter new processing investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iron and Steel Slag Market |
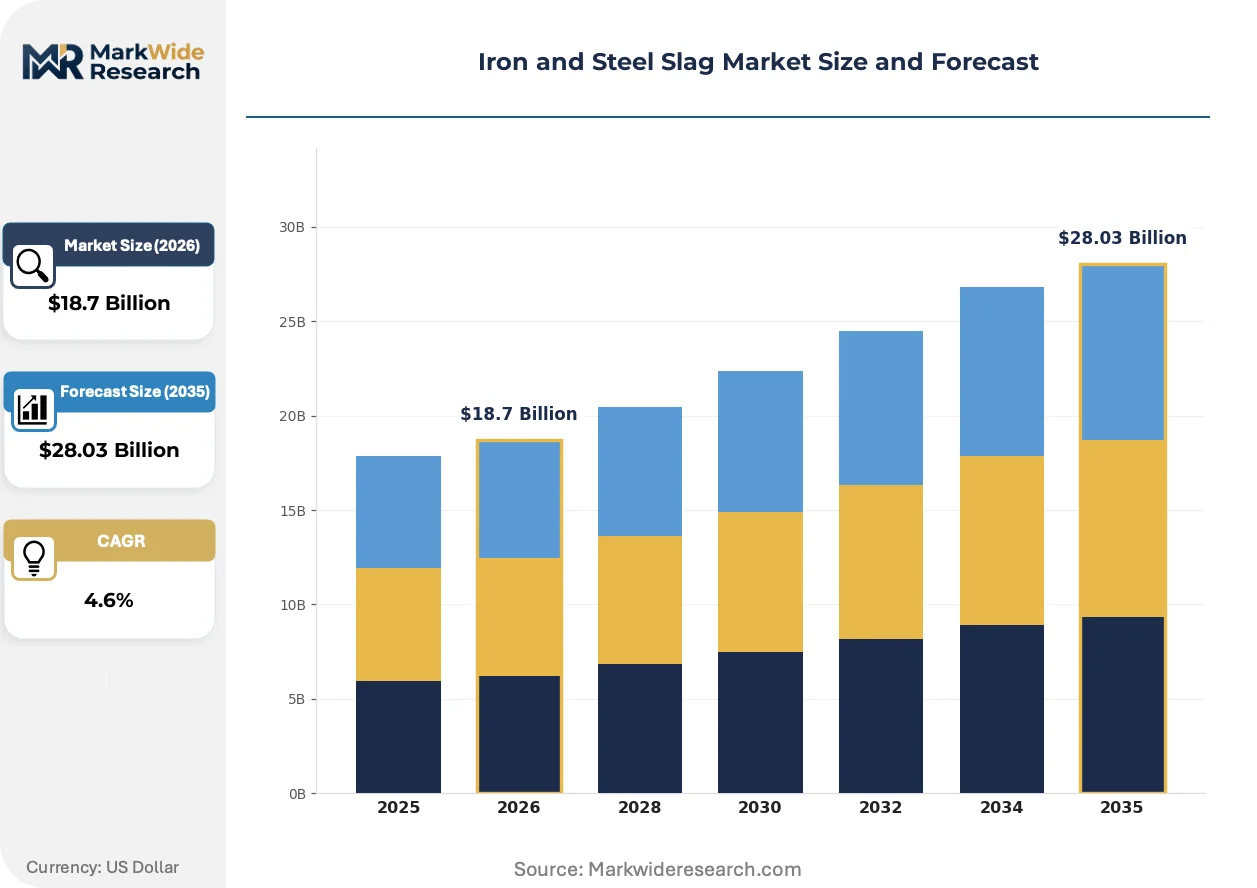
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blast Furnace Slag, Steelmaking Slag, Ferroalloy Slag, Ladle Furnace Slag Application: Cement Production, Construction, Road Base, Fill Material End User: Construction Industry, Cement Manufacturers, Road Contractors, Mining Companies Technology: Granulation, Air-Cooled, Vitrification, Stabilization |
| Companies Covered | China Baowu Steel Group Corporation, Tata Steel, ArcelorMittal, JSW Steel Limited, HBIS Group, Nippon Steel Corporation, JFE Steel Corporation, Steel Authority of India Limited, POSCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iron and Steel Slag Market Emerging Trajectories
Slag valorization is pivoting from volume displacement to carbon-accounting integration, with processing technology and regulatory classification converging to recategorize metallurgical residues as engineered construction inputs rather than waste streams requiring disposal.
Dry granulation technology is hybridizing conventional water-quenching methods with mechanical cooling systems that recover waste heat for power generation. Cement producers in South Korea and Taiwan are piloting these hybrid units to secure both material supply and Scope 2 emissions reductions. The technology is compressing energy intensity benchmarks for slag cement production while expanding viable source material to lower-grade blast furnace outputs.
REACH registration requirements for slag-based construction products are tightening substance characterization obligations across the European Economic Area. ECHA's 2023 update to Annex XVII restricted substance thresholds is forcing granulation facilities to implement expanded leaching test protocols. German and Dutch steel mills are responding by consolidating slag processing under captive chemical compliance divisions rather than outsourcing to independent traders.
Buyer concentration among multinational cement groups is consolidating procurement authority at regional headquarters level, displacing decentralized sourcing from individual plant managers. LafargeHolcim and HeidelbergCement are centralizing slag contract negotiations in Zurich and Heidelberg respectively, compressing supplier margins through volume aggregation. This shift is most visible in Western Europe where integrated steel mills now face single-point price pressure from buyers controlling multiple clinker substitution programs.
Iron and Steel Slag Market Segmentation
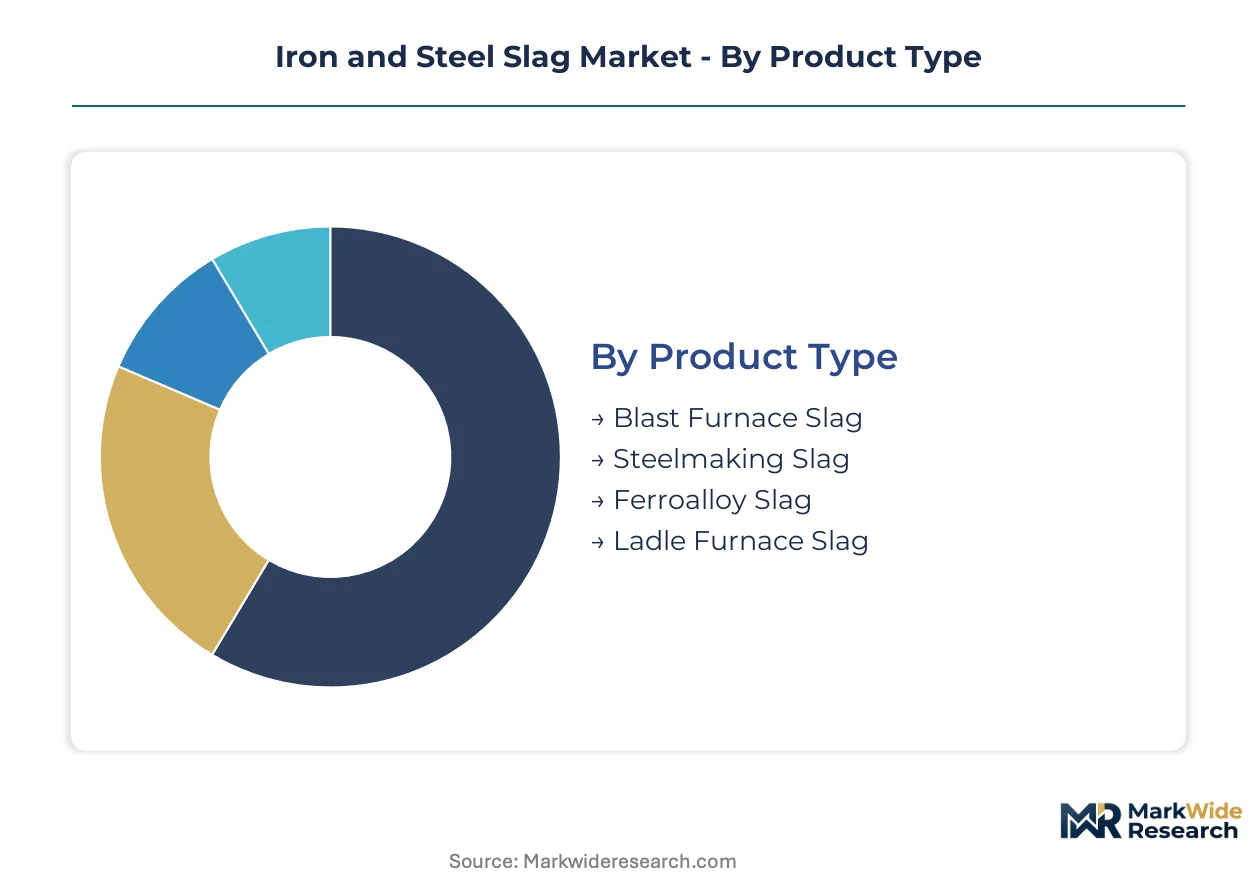
Segmentation in the Iron and Steel Slag Market reveals how material chemistry, processing technology, and end-use specifications create distinct value tiers. Procurement patterns diverge sharply between cement substitution programs and geotechnical applications, with regulatory classification determining accessible market channels for each slag category.
Product Type:
The maturity spectrum spans from established blast furnace outputs to emerging ferroalloy valorization pathways, with calcium-aluminosilicate chemistry dictating viable downstream markets.
- Blast Furnace Slag:Contains 35-40% calcium oxide and exhibits latent hydraulic properties when finely ground. Demand concentrates in Germany, France, and Poland where EU Green Deal mandates force cement manufacturers to secure granulated supply contracts for clinker displacement.
- Steelmaking Slag:Higher free lime and iron oxide variability requires real-time XRF monitoring for quality control. Road base applications in Maharashtra, Gujarat, and Tamil Nadu absorb volume as India's infrastructure buildout accelerates, though aggregate scarcity compresses price competitiveness against crushed stone.
- Ferroalloy Slag:Specialized manganese and silicon-rich residues from alloy production serve niche refractory and fertilizer markets.
- Ladle Furnace Slag:Secondary refining residues with elevated alumina content find limited but expanding use in high-performance concrete admixtures.
Blast Furnace Slag handles the majority of throughput; Steelmaking Slag is the fastest mover on share.
Application:
Cost tier differentiation separates premium-specification cement substitution from commodity-grade fill displacement, with carbon accounting increasingly determining margin capture.
- Cement Production:Pozzolanic reactivity enables clinker substitution ratios up to 50% in Portland pozzolana cement blends. South Korean and Taiwanese producers pilot hybrid dry granulation units to secure Scope 2 emissions reductions alongside material supply.
- Construction:High-specification concrete applications in Sweden and Finland attract carbon-negative aggregates from mineral carbonation of steelmaking slag, commanding premium offtake from net-zero committed developers.
- Road Base:Unprocessed steelmaking slag competes directly with natural aggregates where river sand mining restrictions across Southeast Asia alter procurement economics.
- Fill Material:Air-cooled products command premium pricing in geotechnical fill markets, with Japan's MLIT revising harbor standards to permit marine deployment of high-density slag products.
Cement Production commands the dominant revenue share; Construction applications are expanding most quickly on carbon-accounting integration.
End User:
Customer type concentration among multinational cement groups is consolidating procurement authority at regional headquarters level, compressing supplier margins through volume aggregation.
- Construction Industry:General contractors and developers in net-zero committed markets specify slag-derived materials for embodied carbon reduction in building certifications.
- Cement Manufacturers:LafargeHolcim and HeidelbergCement centralize slag contract negotiations in Zurich and Heidelberg respectively, displacing decentralized sourcing from individual plant managers.
- Road Contractors:Public infrastructure agencies in India specify slag-based materials for dedicated freight corridors and highway construction, creating concentrated offtake volumes.
- Mining Companies:Backfill and tailings management applications absorb lower-grade steelmaking slag in underground operations.
Cement Manufacturers drive the largest contract values; Road Contractors are gaining share fastest on infrastructure stimulus deployment.
Technology:
Supply concentration around integrated steel mill processing networks favors captive granulation facilities over independent traders, with dry systems emerging as the capability differentiator.
- Granulation:Water-quenching produces glassy, reactive material for cement applications. Dry granulation systems hybridizing mechanical cooling with waste heat recovery are capturing latent hydraulic value from previously landfilled blast furnace outputs.
- Air-Cooled:Slower crystallization yields dense, crystalline products for high-friction surface courses and marine geotechnical fill, commanding premium pricing in select markets.
- Vitrification:Controlled thermal treatment produces glass-ceramic aggregates for specialized abrasion-resistant applications.
- Stabilization:Chemical fixation of free lime and heavy metals enables compliance with EPA beneficial use determinations and REACH leaching thresholds.
Granulation handles the dominant processing volume; Dry granulation variants are climbing the fastest on energy recovery integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies. European cement manufacturers prioritize granulated blast furnace slag for clinker substitution under carbon border regulations. Indian road contractors absorb unprocessed steelmaking slag for aggregate-scarce infrastructure projects. East Asian processors pursue dry granulation systems that recover waste heat alongside material beneficiation.
Germany
Cement producers in the Rhine-Ruhr industrial corridor secure granulated blast furnace slag contracts to meet EU Green Deal circular economy binding reuse targets. The country's national environmental regulator enforces strict leaching test protocols under REACH Annex XVII updates. Duisburg's integrated steel-processing complex anchors supply concentration for inland cement plants displacing clinker imports.
India
Road base applications in Maharashtra, Gujarat, and Tamil Nadu concentrate demand as dedicated freight corridors and metro rail expansion accelerate. The Bureau of Indian Standards mandates slag-based Portland pozzolana cement specifications for public infrastructure tenders. JSW Steel Limited's Vijayanagar complex maintains captive granulation facilities serving cement partners across South India.
China
Blast furnace slag valorization tightens under MEE solid waste management standards and dual carbon goals that restrict unprocessed disposal. The Ministry of Ecology and Environment incentivizes qualified reuse through carbon accounting recategorization. Baowu Steel's Shanghai-area processing network captures latent hydraulic value previously lost to landfill streams.
Japan
Air-cooled slag products command premium positioning in geotechnical fill markets as MLIT revises harbor and coastal defense material standards for marine deployment. The Ministry of Land, Infrastructure, Transport and Tourism specification expansion opens volume outlets for high-density products. Chubu region steel mills supply Nagoya-area port reconstruction projects under updated technical criteria.
United States
EPA beneficial use determinations under RCRA Subtitle D shape market access for slag-derived construction materials through batch-testing requirements. The Environmental Protection Agency's evolving carbon accounting methodologies threaten liability recategorization from waste to coproduct. Pennsylvania and Ohio legacy slag dumps carry unresolved groundwater monitoring obligations that complicate site redevelopment in the Great Lakes industrial belt.
Iron and Steel Slag Market Vendor Landscape
Capability concentration sits with integrated steel mills operating captive granulation networks; scale advantage sits with diversified metallurgical groups spanning multiple continents. The vendor base organizes around three strategic archetypes: coastal integrated mills with dedicated cement partnerships, regional processors serving road construction contractors, and technology licensors deploying dry granulation systems. Dominant competitive moves include backward integration into beneficiation infrastructure and strategic partnerships with multinational cement groups centralizing procurement authority.
Within the integrated mill tier, ArcelorMittal and Nippon Steel Corporation exemplify operators leveraging captive European and Japanese processing networks to retain value from blast furnace outputs. Tata Steel anchors South Asian supply positioning through dedicated granulation facilities. These three represent archetypes of metallurgical groups converting waste stream liability into contracted construction material revenue under tightening circular economy mandates.
| Leading Market Players |
|---|
| China Baowu Steel Group Corporation |
| Tata Steel |
| ArcelorMittal |
| JSW Steel Limited |
| HBIS Group |
| Nippon Steel Corporation |
| JFE Steel Corporation |
| Steel Authority of India Limited |
| POSCO |
| Others |
Supply Flow & Price Mechanics
The Rhine-Alpine freight corridor links blast furnace complexes in Belgium and the Netherlands to inland cement plants across Germany and France, with its cost dynamics amplifying supply concentration effects while downstream price differentiation separates granulated blast furnace slag from unprocessed steelmaking residues.
Pricing Analysis
Long-term offtake contracts dominate procurement between integrated steel mills and multinational cement groups, though spot transactions persist for road base applications where project-based demand fluctuates. Price differentiation rests on granulation quality and REACH Annex XVII compliance certification, with premium tiers capturing carbon-accounting benefits for net-zero committed developers. Cost compression in standard-grade road base materials is intensifying because aggregate scarcity across Southeast Asia compresses slag competitiveness against crushed stone. Cement manufacturers exhibit lowest price sensitivity due to clinker substitution economics, while independent road contractors face acute margin pressure from natural aggregate volatility.
Supply Chain Analysis
Extended payment terms from multinational cement groups force regional processors to utilize supply-chain finance facilities, stretching working capital cycles for independent traders. Geographic supply concentrates in China, India, and the European Union, with blast furnace slag output drawing from integrated coastal steel complexes. Raw material dependencies center on metallurgical coal quality, limestone flux chemistry, and iron ore grade consistency. Single-source vulnerability runs through concentrated blast furnace capacity in Belgium and the Netherlands, where European steel production consolidation narrows source diversity. Distribution runs through captive granulation facilities at integrated mill sites, displacing independent traders from premium cement supply channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Slag beneficiation services and carbon-accounting certification layers are expanding faster than raw material throughput, creating recurring-revenue attach opportunities for processors with technical compliance capabilities.
For Market Incumbents: Entrench market position through backward integration into dry granulation infrastructure with waste heat recovery, while investing in REACH Annex XVII expanded leaching test protocols to preempt regulatory displacement. Consolidate procurement relationships with LafargeHolcim and HeidelbergCement as these groups centralize slag contract authority at regional headquarters, compressing margins for non-integrated suppliers. For New Entrants and Emerging Players: Establish a beachhead in Vietnam, Indonesia, and the Philippines where domestic granulation capacity lags accelerating steel output, creating import substitution demand for blast furnace slag beneficiation expertise. Target road base applications in India's Maharashtra and Tamil Nadu states, where infrastructure stimulus concentrates volume offtake and Bureau of Indian Standards mandates create specification barriers for unqualified competitors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified steel groups spinning non-core slag processing units under circular economy mandate pressure, particularly in European jurisdictions where EU Green Deal reclassification from waste to coproduct alters liability structures. Monitor carbon accounting methodology evolution as the inflection signal—recategorization of slag from waste to coproduct would unlock contracted offtake premiums and transform valuation multiples for processing assets.| Strategic Initiative | Industry Significance |
|---|---|
| Dry Granulation Capacity Buildout | Hybrid mechanical cooling systems capture waste heat for power generation while expanding processable feedstock grades. |
| Carbon Capture Integration | Mineral carbonation of steelmaking slag produces carbon-negative aggregates attracting Swedish and Finnish net-zero developers. |
| REACH Compliance Consolidation | German and Dutch steel mills are consolidating slag processing under captive chemical compliance divisions rather than outsourcing. |
| Long-term Cement Partnership | Centralized procurement at LafargeHolcim and HeidelbergCement headquarters compresses supplier margins through volume aggregation. |
| Marine Geotechnical Specification Expansion | Japan's MLIT harbor standard revisions open volume outlets for high-density air-cooled slag products. |
Methodological Framework
The analysis maps blast furnace slag, steelmaking slag, ferroalloy slag, and ladle furnace slag sub-sectors, each validated through granulation facility operators, cement plant procurement directors, road construction contractors, and environmental compliance officers. Primary interviews with these stakeholders combined with secondary validation from EPA beneficial use determinations, ECHA REACH registration databases, Bureau of Indian Standards specifications, and China MEE solid waste management standards. Bottom-up capacity and throughput estimates triangulated against top-down cement industry clinker substitution demand projections.
Assumptions held fixed include EU Green Deal circular economy binding reuse targets, China dual carbon policy enforcement intensity, and India infrastructure buildout execution rates; variables stress-tested included blast furnace capacity retirement schedules, natural aggregate price volatility, and carbon accounting recategorization timing. The analytical framework modeled product type, application, end user, and processing technology segmentation dimensions across the analysis window. CAGRs derived from segment-level volume and value buildups incorporating cement industry clinker ratio trends and road construction aggregate substitution elasticities.
Stress conditions across carbon border adjustment implementation pace, REACH Annex XVII enforcement stringency, and granulation technology deployment rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
United Kingdom Architectural Coatings Market
Building Materials
Rapid Strength Concrete Market
Building Materials
North America Architectural Coatings Market
Building Materials
Global Pozzolan Market
Building Materials
Long Steel Market
Building Materials
Stone Coated Steel Roofing Market
Building Materials
India Aluminum Door and Window Market
Building Materials
Solar Control Window Film Market
Building Materials
Europe Acrylic Resin Dispersion Based Primers in Construction Market
Building Materials
US Cement Tiles Market
Building Materials
Radiant Barriers and Reflective Insulation Market
Building Materials
Asia-Pacific Dry-Mix Mortar Market
Building Materials
Building Asphalt Market
Building Materials
Engineered Wood Product Market
Building Materials
Ductile Iron Pipe Market
Building Materials
US Contract Glazing Market