
 Asia-Pacific Dry-Mix Mortar Market | 2026-2036
Asia-Pacific Dry-Mix Mortar Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Dry-Mix Mortar Market Outlook
Pre-mixed formulation technology is narrowing the performance gap between site-mixed and factory-controlled mortar, compressing tolerances for water retention, open time, and bond strength across tropical and temperate construction zones. Sika AG leverages its polymer-modified additive portfolio to anchor premium positioning in facade and flooring applications. MUHU (China) Construction Materials Co., Ltd. dominates cost-engineered masonry mortar supply through captive raw-material sourcing in Shandong province. UltraTech sustains distribution breadth across India's secondary cities via direct-to-contractor channels and bulk logistics infrastructure.
Dry-mix mortar denotes a factory-blended combination of cement, dried aggregates, functional additives, and polymers that requires only water addition at the job site, with formulations typically achieving compressive strength ratings from 5 MPa for bedding applications to 30 MPa for structural repair. The product category eliminates batch-to-batch variability inherent in site mixing while accelerating project schedules through controlled setting times and reduced curing dependency. Tile adhesive commands the widest margin pool among product type segments, driven by porcelain and large-format tile specifications in commercial and high-end residential builds. Repair mortar represents the fastest-expanding application category as aging building stock across East Asian megacities generates structural rehabilitation contracts. Masonry mortar retains the largest volume footprint but faces margin compression from commoditized supply in inland Chinese and Indian markets.
China's SAMR enforces GB standards for dry-mix mortar labeling and performance claims, while India's BIS mandates certification for cement-based construction chemicals under compulsory registration requirements. The EU Green Deal's embodied-carbon tracking mechanisms, referenced by Australian and South Korean project financiers, are beginning to influence material procurement specifications for institutional developments. Stakeholders must monitor how ASEAN member states harmonize national building codes with China's technical standards, as this alignment will determine cross-border supplier qualification costs and factory location decisions.
Market Dynamics
China's dual carbon goals and India's BIS compulsory registration scheme are compressing margins for commodity-grade suppliers while rewarding polymer-modified formulation specialists with certified production lines.
Growth Catalysts
- GB Standard 25181-2019:China's SAMR-enforced dry-mix mortar labeling requirements eliminate substandard producers from government-procured infrastructure tenders, consolidating demand toward certified manufacturers.
- Prefabricated construction:Southeast Asian residential developers are specifying factory-blended tile adhesive for panelized wall systems, accelerating adoption of controlled-setting formulations.
- Yangtze River Delta clustering:Urban renewal contracts in Shanghai and Suzhou are absorbing structural repair mortar volumes as aging commercial stock triggers facade rehabilitation mandates.
Market Restraints
- White cement supply concentration:Shandong province's captive limestone reserves give select Chinese producers input cost advantages that inland Indian manufacturers cannot replicate without bulk import exposure.
- Redispersible powder import dependency:South Korean and Australian formulators rely on European and Chinese polymer additive supply, creating working capital intensity from ocean freight inventory cycles.
- Site-mix substitution persistence:Cost-sensitive Indian housing contractors in tier-3 cities continue batching sand-cement blends manually, delaying dry-mix penetration in price-elastic rural segments.
Strategic Opportunities
- Vietnam's northern industrial corridor:Foreign manufacturing relocation from China is generating greenfield plant construction demand for masonry mortar in Bac Ninh and Hai Phong provinces.
- EU Green Deal alignment:Australian and South Korean project financiers are beginning to reference embodied-carbon tracking for institutional developments, creating specification advantages for low-clinker formulations.
- Direct-to-contractor digital platforms:Indian distributors are piloting app-based ordering with bulk logistics scheduling, bypassing traditional dealer networks in secondary cities.
Industry Challenges
- Polymer formulation expertise scarcity:Qualified technicians for redispersible powder dosing and rheology control remain concentrated in coastal Chinese and Western European technical centers.
- BIS certification timeline compression:India's compulsory registration scheme requires 90-120 day laboratory validation cycles that delay new product launches during peak construction seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Dry-Mix Mortar Market |
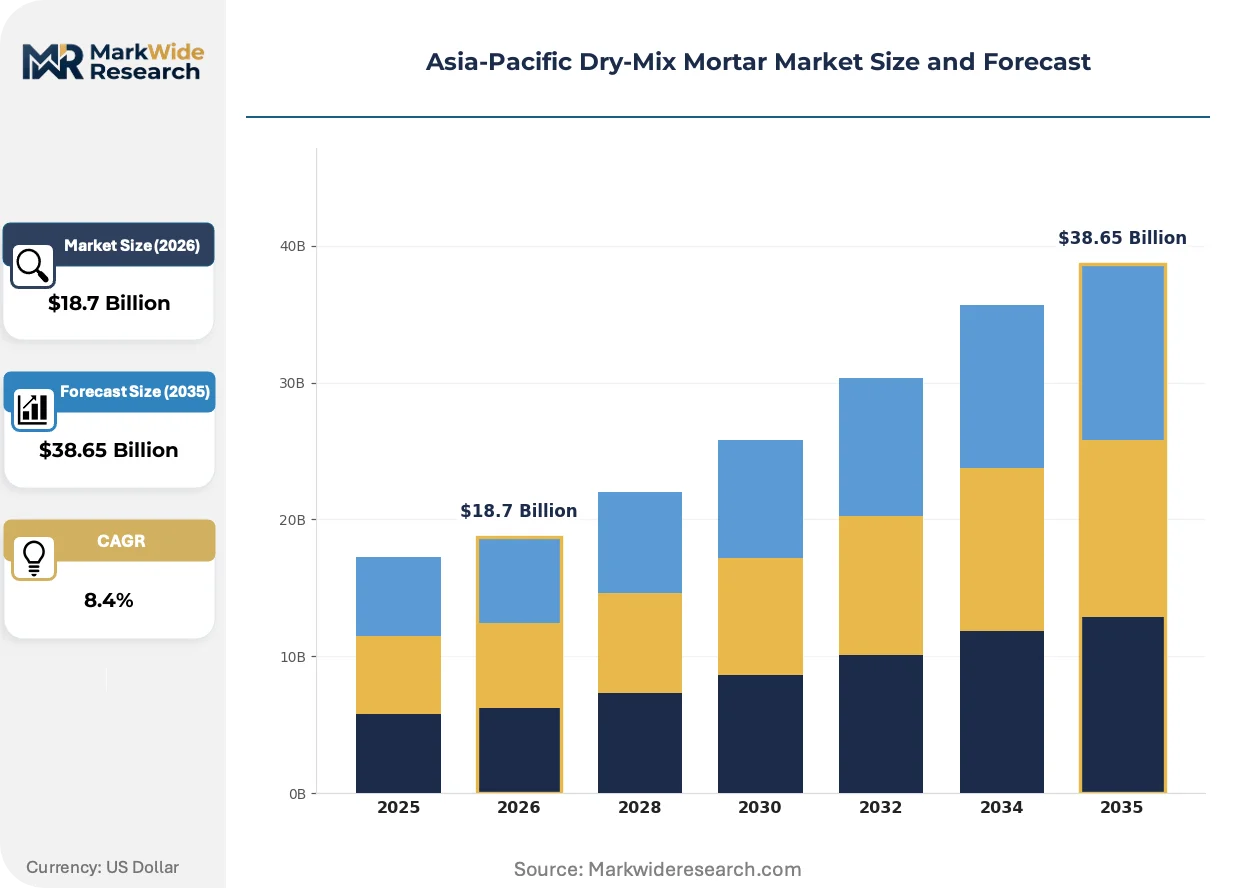
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Masonry Mortar, Tile Adhesive, Floor Mortar, Repair Mortar End User: Construction Industry, DIY Consumers, Institutional Projects, Residential Projects Application: Interior Walls, Exterior Walls, Floors, Facades Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Wholesale |
| Companies Covered | HANIL HOLDINGS CO., LTD., BASF SE, Saint-Gobain, MUHU (China) Construction Materials Co., Ltd., LafargeHolcim Ltd, Sika AG, Oriental Yuhong, UltraTech, SCG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Dry-Mix Mortar Market Strategic Shifts
Formulation chemistry and procurement digitization are compressing the traditional separation between commodity masonry supply and specification-driven repair systems.
Redispersible polymer powder technology is migrating from premium tile adhesive applications toward standard-grade masonry mortars as Vietnamese and Indonesian producers achieve consistent glass transition temperature control in tropical humidity conditions. Regional contractors are accepting polymer-modified bedding layers for mid-rise residential frames. The performance gap between site-mixed and factory-controlled compressive strength tolerances is narrowing from 15% variance to under 5%.
China's GB 18588-2020 limits on formaldehyde content in construction adhesives are forcing reformulation of low-cost tile adhesives previously reliant on urea-formaldehyde resin binders. Domestic additive suppliers are accelerating VAE emulsion polymer investments to maintain cost positioning. India's western states are experiencing the tightest compliance timelines as BIS expands compulsory registration from cement to cement-based construction chemicals.
Specification authority is consolidating with facade engineering consultants who now mandate certified open-time and bond-strength documentation for large-format porcelain installations. Direct procurement relationships between mortar producers and flooring specialty contractors are displacing generalist distributor networks in Australia's commercial high-rise segment. This channel compression is most visible in Melbourne and Sydney where design-build contracts dominate institutional development.
Asia-Pacific Dry-Mix Mortar Market Segmentation
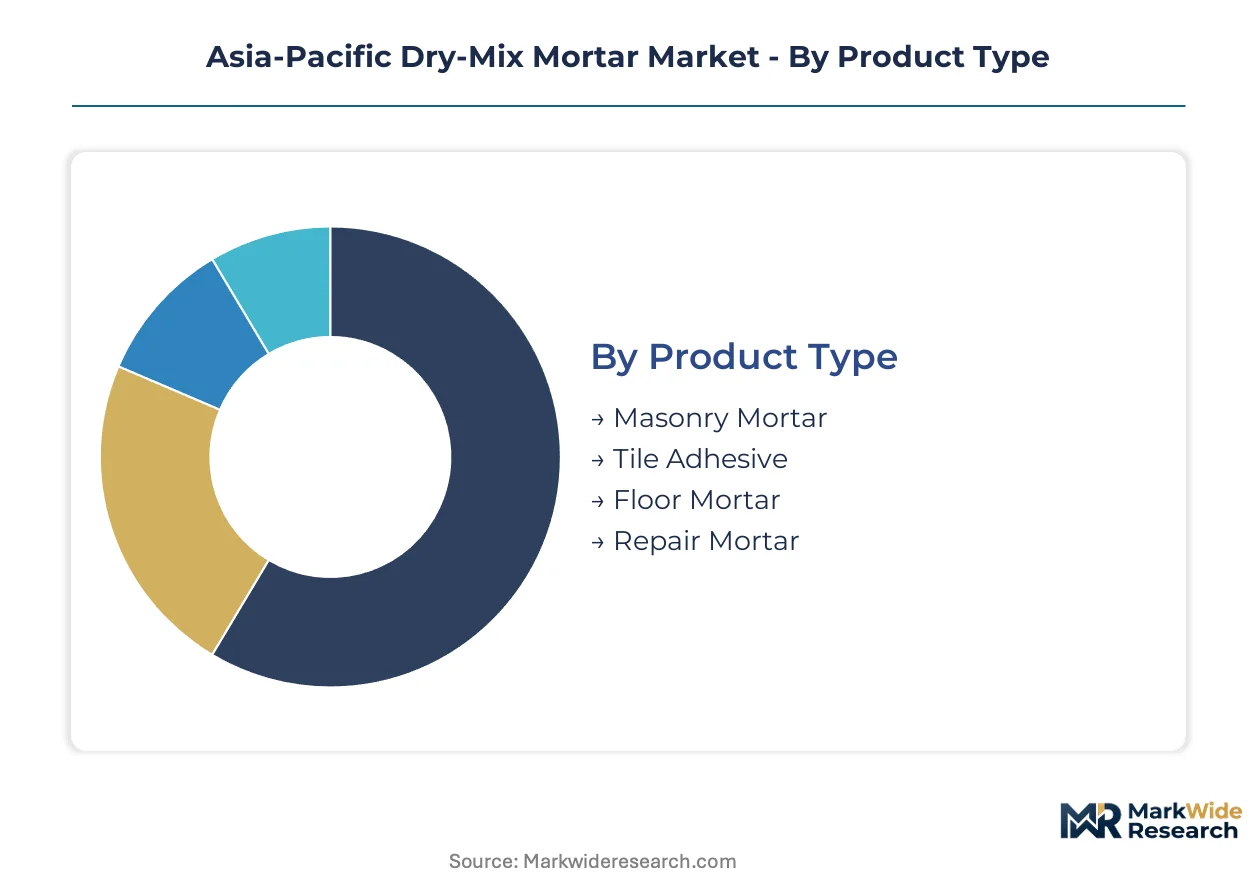
Dry-mix mortar segmentation reveals how formulation chemistry and procurement channels intersect with construction methodology shifts across tropical and temperate zones. Category boundaries are blurring as polymer-modified products migrate from premium niches toward standard-grade applications.
Product Type:
Mature masonry formulations coexist with emerging polymer-modified systems as cost-engineered and specification-grade products diverge in margin structure.
- Tile Adhesive:Polymer-modified cementitious binders with redispersible powder additives achieve open times exceeding 30 minutes for large-format porcelain installations. Demand concentrates in Southeast Asian prefabricated residential projects where factory-blended consistency eliminates site-mix variability for panelized wall systems.
- Repair Mortar:High-early-strength formulations with microsilica and shrinkage-compensating chemistry address structural rehabilitation of aging commercial stock in Shanghai and Suzhou urban renewal corridors. BIS compulsory registration timelines compress supplier response windows during peak construction seasons.
- Masonry Mortar:Standard-grade cement-lime blends for brick and block laying face margin pressure from inland Chinese and Indian commoditized supply.
- Floor Mortar:Self-leveling underlayments with controlled flow characteristics support polished concrete and resilient flooring specifications in Australian commercial high-rise developments.
Masonry mortar retains volume leadership; repair mortar holds the steepest expansion curve.
End User:
Customer type determines formulation complexity and certification requirements across institutional, commercial, and residential procurement channels.
- Construction Industry:General contractors and specialty flooring firms drive bulk procurement of certified formulations with documented compressive strength and bond performance. Yangtze River Delta infrastructure tenders enforce GB Standard 25181-2019 labeling compliance that eliminates uncertified suppliers.
- Residential Projects:High-rise and villa developments in India's western states specify polymer-modified tile adhesive for porcelain installations as BIS expands compulsory registration to cement-based construction chemicals.
- Institutional Projects:Government and educational facilities reference EU Green Deal embodied-carbon tracking mechanisms in Australian and South Korean procurement specifications.
- DIY Consumers:Small-format retail packaging for home renovation remains underdeveloped outside Australia's mature hardware channels.
Construction industry channels absorb the largest formulation volumes; residential projects are climbing fastest as prefabrication spreads.
Application:
Exposure conditions dictate polymer loading levels and durability testing protocols across interior and exterior building envelopes.
- Facades:Weather-resistant renders and external thermal insulation composite systems require hydrophobic additives and alkali-resistant glass fiber reinforcement. Melbourne and Sydney design-build contracts consolidate specification authority with facade engineering consultants who mandate certified bond-strength documentation.
- Interior Walls:Standard gypsum and cement-based plasters for dry environments face substitution from prefabricated panel systems in Vietnamese industrial corridor developments.
- Exterior Walls:Rainscreen cladding support systems and external insulation demand frost-resistant formulations with controlled capillary absorption.
- Floors:Screeds and self-leveling compounds for commercial wear surfaces specify rapid-setting chemistry to accelerate construction schedules.
Facade applications command premium formulation values; interior wall systems are gaining share fastest through panelized construction adoption.
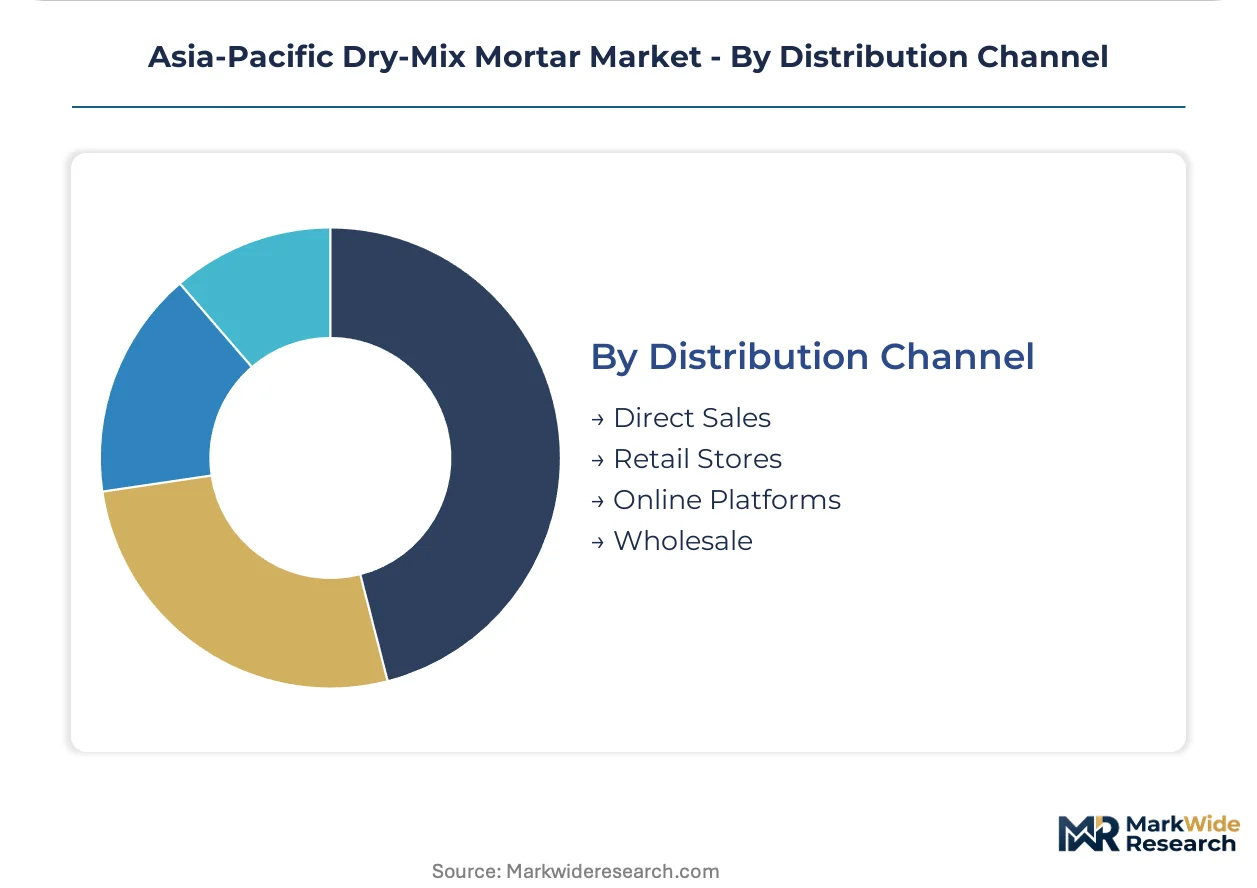
Distribution Channel:
Channel structure varies with customer scale, certification documentation requirements, and logistics infrastructure maturity across the region.
- Direct Sales:Bulk supply relationships between manufacturers and large contractors bypass dealer networks, particularly in India's secondary cities where UltraTech maintains dedicated logistics infrastructure. Direct-to-contractor digital platforms pilot app-based ordering with bulk scheduling capabilities.
- Wholesale:Regional distributors stock commodity masonry mortars for tier-2 and tier-3 construction markets with price-elastic demand.
- Retail Stores:Hardware and building material outlets serve renovation contractors and advanced DIY segments in Australian urban centers.
- Online Platforms:E-commerce penetration remains limited to specialty additives and small-format repair products due to freight economics for cementitious materials.
Direct sales channels dominate certified formulation volumes; wholesale retains the broadest geographic coverage for standard-grade supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction contractors and specialty flooring firms drive procurement concentration across the Asia-Pacific region. Prefabrication adoption and urban renewal mandates concentrate demand in coastal manufacturing belts and secondary inland cities. Regulatory tightening around cement-based products is reshaping supplier qualification requirements.
China
Shanghai and Suzhou urban renewal contracts absorb structural repair mortar volumes as aging commercial stock triggers facade rehabilitation mandates. SAMR enforces GB Standard 25181-2019 labeling requirements that eliminate substandard producers from government-procured infrastructure tenders. Yangtze River Delta clustering concentrates certified manufacturing capacity near raw material sources and high-value project sites.
India
Western states specify polymer-modified tile adhesive for high-rise and villa developments as porcelain installations proliferate in premium residential segments. BIS compulsory registration schemes expand from cement to cement-based construction chemicals, compressing supplier response windows during peak construction seasons. UltraTech sustains distribution breadth across secondary cities via direct-to-contractor channels and bulk logistics infrastructure.
Vietnam
Bac Ninh and Hai Phong provinces generate greenfield plant construction demand for masonry mortar as foreign manufacturing relocates from China. National building code harmonization with Chinese technical standards determines cross-border supplier qualification costs and factory location decisions. Northern industrial corridor developments absorb standard-grade formulations for panelized residential wall systems.
Australia
Melbourne and Sydney design-build contracts consolidate specification authority with facade engineering consultants who mandate certified open-time and bond-strength documentation. Project financiers reference EU Green Deal embodied-carbon tracking mechanisms for institutional developments, creating specification advantages for low-clinker formulations. Direct procurement relationships between mortar producers and flooring specialty contractors displace generalist distributor networks in commercial high-rise segments.
South Korea
Formulators rely on European and Chinese polymer additive supply for redispersible powder inputs, creating working capital intensity from ocean freight inventory cycles. Project financiers incorporate embodied-carbon tracking into material procurement specifications for government and educational facilities. Domestic producers face margin pressure from import dependency while seeking certification alignment with Australian and European green building standards.
Asia-Pacific Dry-Mix Mortar Market Competitive Environment
Channel-controlling players compete with product-specialist players across formulation tiers and distribution architectures. The market structures around three distinct layers: multinational chemical conglomerates with polymer-modified additive portfolios, regional cement majors leveraging captive raw-material sourcing and bulk logistics, and domestic specialists serving cost-engineered masonry segments. Strategic moves concentrate on backward integration into limestone reserves and redispersible powder production, alongside digital platform investments that bypass traditional dealer networks.
Within the multinational specialty tier, Sika AG anchors premium positioning through polymer-modified formulation expertise. BASF SE and Saint-Gobain occupy positions as diversified materials suppliers with construction chemical divisions. Among Asia-Pacific regional players, MUHU (China) Construction Materials Co., Ltd. exemplifies cost-engineered supply archetypes through Shandong-based operations, while UltraTech represents cement-major expansion into value-added dry-mix categories. LafargeHolcim Ltd and SCG sit within the integrated building materials tier with cross-product bundling capabilities. Korean conglomerate HANIL HOLDINGS CO., LTD. and Chinese waterproofing specialist Oriental Yuhong round out the competitive set as regional challengers with domestic market depth.
| Leading Market Players |
|---|
| HANIL HOLDINGS CO., LTD. |
| BASF SE |
| Saint-Gobain |
| MUHU (China) Construction Materials Co., Ltd. |
| LafargeHolcim Ltd |
| Sika AG |
| Oriental Yuhong |
| UltraTech |
| SCG |
| Others |
Value Chain & Pricing Dynamics
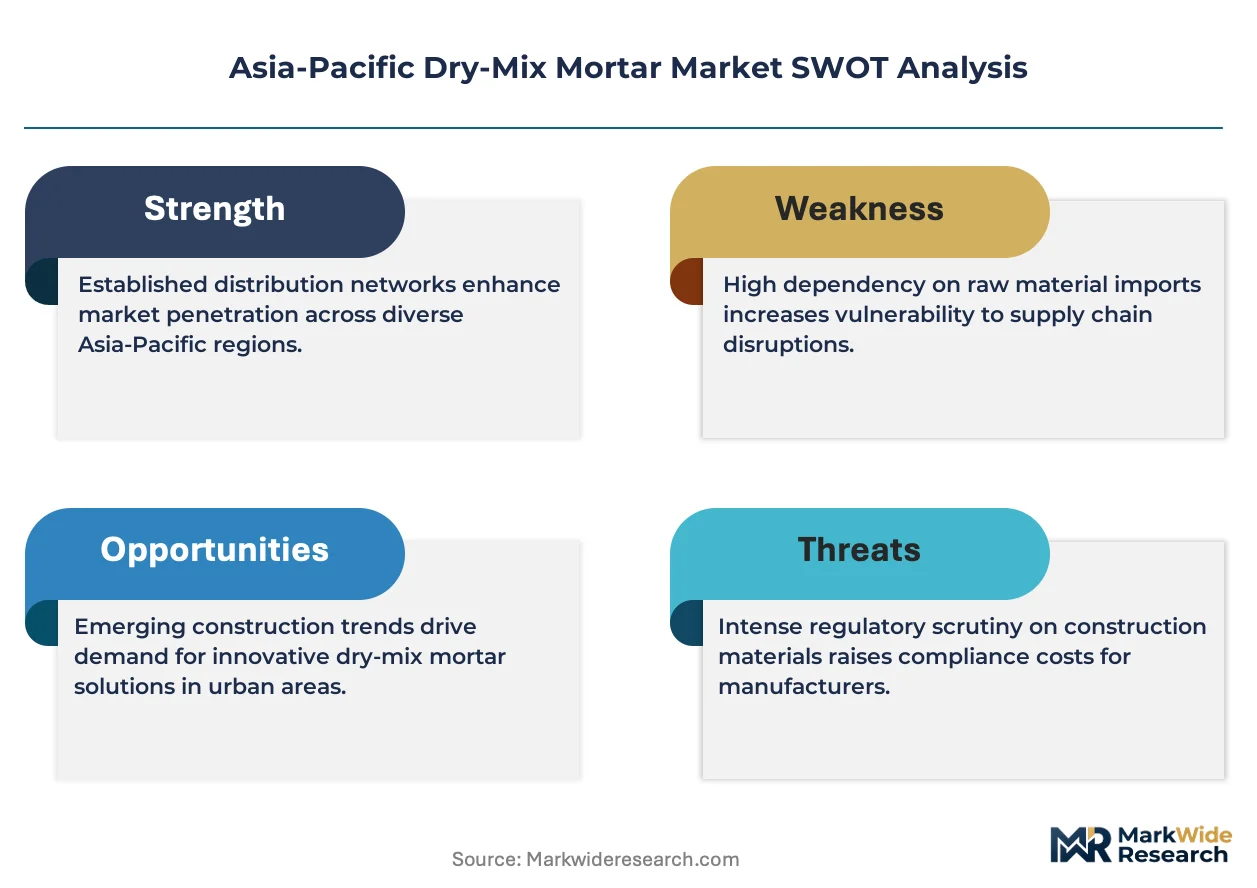
Shandong province's captive limestone reserves anchor input cost advantages for select Chinese producers, concentrating margin pools in polymer-modified formulation tiers where redispersible powder technology commands premium positioning. This upstream concentration forces inland Indian manufacturers into bulk import exposure for white cement, compressing their competitiveness in standard-grade masonry supply.
Pricing Analysis
Cost-plus contracts with cement and polymer additive indexation dominate procurement relationships across the Asia-Pacific region. Three-tier pricing structure across premium, standard, and economy levels separates certified polymer-modified systems from commodity masonry blends. Pricing pressure stems from BIS compulsory registration timelines compressing supplier response windows during peak construction seasons. Tier-3 Indian housing contractors exhibit highest price sensitivity, while Australian design-build contracts absorb premium formulations with documented bond-strength certification.
Supply Chain Analysis
Upstream feedstock concentration centers on Shandong province's limestone reserves, European redispersible powder production, and South Korean petrochemical inputs for VAE emulsion polymers. Formulators draw from Chinese cement clinker, imported polymer additives, and regional dried aggregate sources. Single-source vulnerability runs through ocean freight inventory cycles for redispersible powder dependent markets. Distribution runs through direct-to-contractor bulk logistics in India's secondary cities and facade engineering consultant channels in Australian commercial high-rise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific dry-mix mortar market represents high-growth disruption as prefabricated construction methods and GB Standard 25181-2019 enforcement eliminate substandard producers from government tenders. China's dual carbon goals and India's BIS expansion into cement-based construction chemicals accelerate consolidation toward certified manufacturing lines.
For Market Incumbents: Harden polymer-modified formulation expertise through captive redispersible powder production investments in coastal Chinese technical centers. Secure BIS certification capacity ahead of compulsory registration expansion into cement-based construction chemicals. Defensive consolidation must address site-mix substitution persistence among cost-sensitive Indian housing contractors through direct-to-contractor digital platform investments.
For New Entrants and Emerging Players: Establish a beachhead in Vietnam's northern industrial corridor greenfield plant construction demand for masonry mortar. Target Bac Ninh and Hai Phong provinces where foreign manufacturing relocation generates panelized residential wall system specifications. Go-to-market execution should leverage national building code harmonization with Chinese technical standards to minimize cross-border supplier qualification costs.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional cement majors expanding into value-added dry-mix categories through bulk logistics infrastructure investments. Long-term viability over the five-to-ten year window hinges on backward integration into limestone reserves and polymer additive production capabilities. Monitor ASEAN member state building code harmonization progress as inflection indicator for cross-border factory location economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Reserves | Shandong province's captive sourcing anchors cost-engineered masonry mortar competitiveness against inland Indian imports. |
| Redispersible Powder Production Investment | VAE emulsion polymer capacity in coastal Chinese technical centers reduces import dependency for South Korean formulators. |
| BIS Certification Capacity Expansion | Ninety-to-one-hundred-twenty day laboratory validation cycles must accelerate to match peak construction season demand windows. |
| Direct-to-Contractor Digital Platform Launch | App-based ordering with bulk logistics scheduling bypasses traditional dealer networks in India's secondary cities. |
| Low-Clinker Formulation Development | EU Green Deal embodied-carbon tracking mechanisms create specification advantages in Australian institutional project financier procurement. |
Study Parameters
A standing panel of plant managers at dry-mix mortar facilities, procurement leads at downstream construction contractors, distribution channel partners, and technical R&D directors provided ongoing calibration across primary interview cycles. Secondary validation drew from Chinese SAMR GB standard filings, Indian BIS compulsory registration databases, ASEAN customs and trade data, and cement industry association reports. Bottom-up capacity and demand modeling triangulated against top-down construction spend forecasts across the analysis window.
Scenario-bracketing framed volume and value outputs across product type, end user, application, and distribution channel segmentation dimensions. CAGRs were derived from regression analysis against historical construction output and forward projection of prefabrication adoption curves. Industry-specific inputs included urban renewal contract awards in the Yangtze River Delta, BIS certification timeline compression effects, and polymer additive import dependency ratios.
Stress conditions across cement price volatility, ocean freight rate spikes, and regulatory timeline delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions around prefabrication penetration rates and building code harmonization progress. Cross-checking against national construction output statistics and cement consumption data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Asia-Pacific Kinetic Tiles Market
Building Materials
Masonry Cement Market
Building Materials
Refractory Cement Market
Building Materials
Ireland Cement Market
Building Materials
Fireproof Cladding Market
Building Materials
Cement Board Market
Building Materials
Asia-Pacific Aluminum Door and Window Market
Building Materials
Europe Concealed Cistern Market
Building Materials
Qatar Facade Market
Building Materials
Building and Construction Plastics Market
Building Materials
Global Facade Market
Building Materials
Global Drywall and Building Plaster Market
Building Materials
Lightweight Precast Wall Panel Market
Building Materials
Thin Brick Market
Building Materials
United States Construction Materials Market
Building Materials
Europe Fireproof Cladding Market