
 India Aluminum Door and Window Market | 2026-2036
India Aluminum Door and Window Market Size, Share, and Industry Trends Forecast 2026-2036
India Aluminum Door and Window Market Insights
Aluminum is broadening its replacement of wood and uPVC in Indian fenestration as thermal-break technology narrows the cost-performance gap. Hindalco Industries anchors upstream supply through captive aluminum extrusion capacity. Fenesta differentiates via a nationwide dealer-installer network controlling last-mile service quality. Alupure specializes in architect-specified projects for luxury residential towers in Mumbai and Delhi.
India aluminum doors and windows comprise extruded aluminum alloy profiles, typically 6063-T5 or 6063-T6 grade, assembled with polyamide thermal breaks and EPDM gaskets to achieve air-permeability and water-tightness ratings under IS 4020. Their primary purpose spans weather protection, acoustic insulation, and structural glazing support in high-rise construction. Sliding doors dominate volume in mass residential towers where space efficiency governs layout economics, while casement windows command premium positioning in renovation segments where homeowners prioritize ventilation control. The commercial end user category is expanding fastest as Bangalore and Hyderabad office developments specify unitized curtain walls with integrated aluminum fenestration.
BIS mandates IS 4020 and IS 1948 testing for air infiltration, water penetration, and structural load resistance, compelling manufacturers to upgrade extrusion dies and gasket systems. The Energy Conservation Building Code, enforced by the Bureau of Energy Efficiency, drives low-emissivity and thermal-break specifications in commercial projects above specified floor areas. State-level real estate regulators including MahaRERA in Maharashtra and K-RERA in Karnataka enforce project timelines that compress installation windows and favor pre-fabricated aluminum systems. Stakeholders must monitor evolving state-level green building mandates and thermal-performance star ratings as these will determine which product configurations retain market access.
Market Dynamics
Thermal-break aluminum extrusion is compressing the cost-performance gap against uPVC across Indian high-rise construction, forcing a material substitution wave in Gujarat and Maharashtra residential towers.
Growth Catalysts
- BIS fenestration energy codes:The Bureau of Indian Standards revised IS 4020 and IS 1948 testing protocols, compelling developers to specify thermal-break compliant aluminum systems for air and water tightness certification.
- IT corridor commercial towers:Bangalore and Hyderabad office developments are specifying unitized curtain walls with integrated aluminum fenestration, creating specification pull for high-performance glazing support systems.
- Polyamide thermal break technology:Advances in thermal barrier extrusion are narrowing the insulation differential with uPVC, removing the primary performance objection to aluminum frames in residential applications.
Market Restraints
- Primary aluminum price volatility:Hindalco Industries and other domestic smelters face input cost pressure from alumina and power tariffs, compressing extrusion margins and destabilizing project quotations.
- Captive supply concentration:Upstream aluminum extrusion capacity concentrates with integrated metal producers, limiting independent fabricator access to alloy 6063-T5 and 6063-T6 billets at competitive terms.
- uPVC residual preference:Cost-sensitive developers in tier-2 and tier-3 cities continue specifying uPVC for low-rise residential projects, delaying aluminum penetration outside premium urban clusters.
Strategic Opportunities
- Redevelopment clusters in Mumbai:Premium residential tower replacements in Bandra and Lower Parel are creating specification windows for architect-grade aluminum systems with acoustic and thermal performance guarantees.
- Energy Conservation Building Code enforcement:The Bureau of Energy Efficiency mandate for low-emissivity glazing in commercial projects above specified floor areas is creating compliance-driven demand for thermally broken frames.
- Pre-fabricated system integration:MahaRERA and K-RERA compressed project timelines are favoring factory-finished aluminum fenestration modules over site-fabricated alternatives.
Industry Challenges
- Certified installer scarcity:IS 4020 compliance requires trained technician networks for gasket installation and water-tightness testing, constraining last-mile service quality at scale.
- Die and tooling capex cycles:Custom extrusion profiles for thermal-break configurations require multi-year tooling investments, freezing product portfolios during market transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Aluminum Door and Window Market |
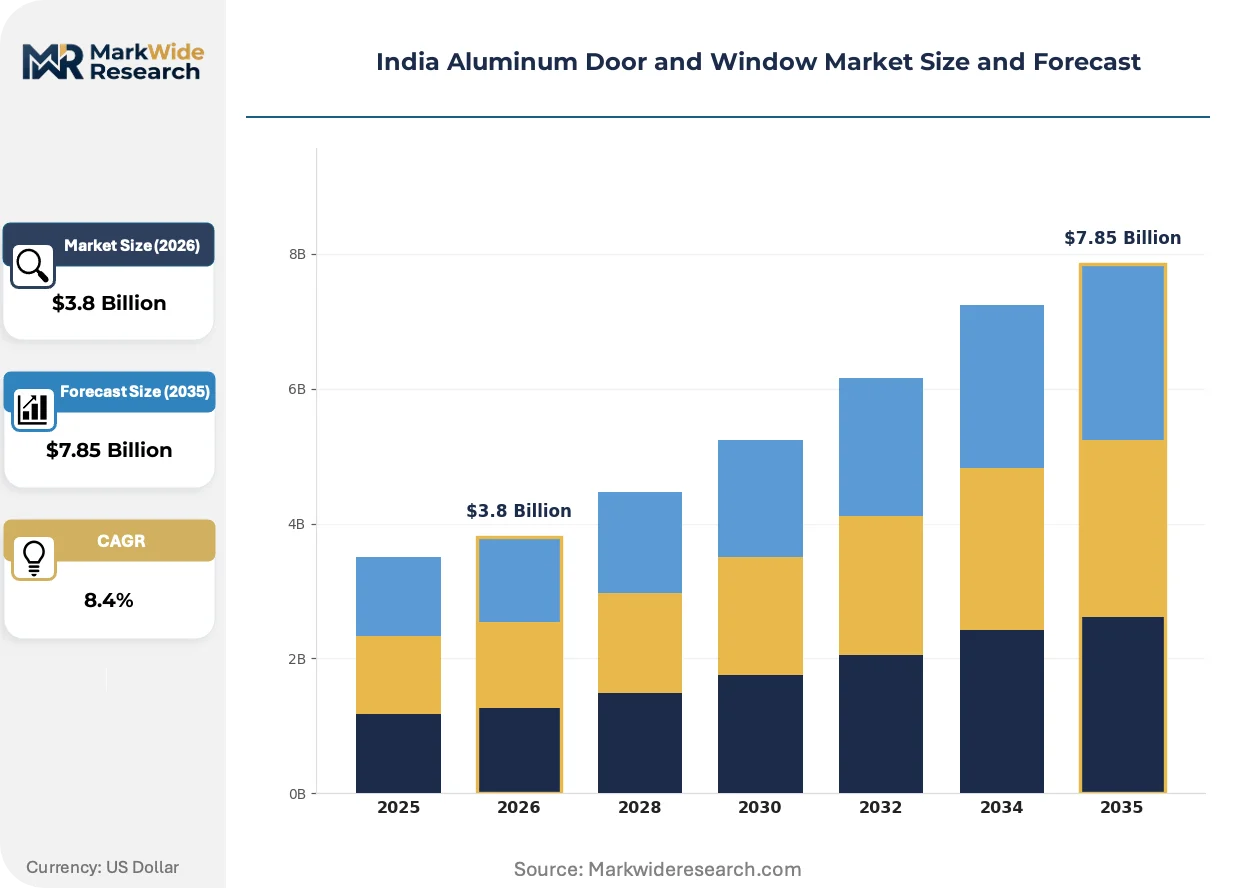
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Doors, Casement Windows, Bi-fold Doors, Fixed Windows End User: Residential, Commercial, Industrial, Government Installation Type: New Construction, Renovation, Retrofit, Modular Distribution Channel: Direct Sales, Retail, Online, Dealers |
| Companies Covered | Alteza, Alupure, Fenesta, Aluking, Reynaers Aluminium, Eternia Windows, Encraft India, Hindalco Industries, Tostem India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Aluminum Door and Window Market Trends and Innovations
Digital specification platforms and modular fabrication systems are compressing design-to-installation cycles across Indian fenestration, reshaping how architects, developers, and fabricators coordinate project delivery.
Thermal-break polyamide strip technology is decentralizing supply chain control in Indian aluminum fenestration. The technology enables regional fabricators to source standard extrusions locally and apply thermal barriers in-house, reducing dependence on integrated producers for finished profiles. Mid-size fabricators in Pune and Chennai are adopting this capability fastest, compressing delivery timelines for customized residential projects.
BIS mandates under IS 4020 and IS 1948 are tightening testing protocols for air infiltration, water penetration, and structural load resistance. The regulations force manufacturers to upgrade extrusion die precision and EPDM gasket compound formulations. Commercial tower developers in Bangalore and Hyderabad are responding by pre-qualifying fabricators based on certified test reports, shifting procurement criteria from price to verified performance documentation.
Architect specification behavior is consolidating around performance-guaranteed system suppliers. Developers of Mumbai premium redevelopment projects are bundling aluminum fenestration with acoustic and thermal performance warranties, displacing commodity procurement. This pattern concentrates specification authority with fabricators maintaining in-house testing laboratories and documented installation protocols, visible most clearly in Bandra-Kurla Complex and Lower Parel tower developments.
India Aluminum Door and Window Market Segmentation
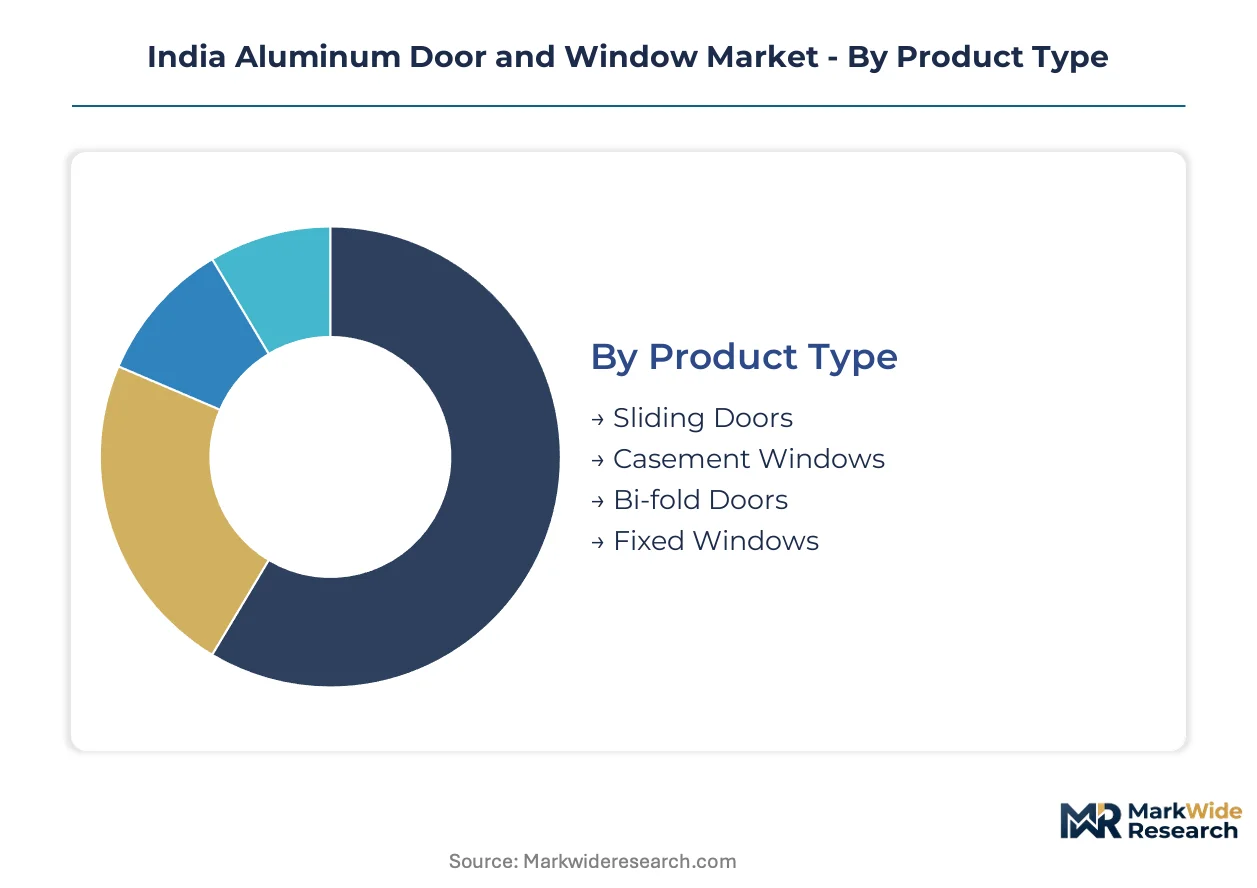
Aluminum fenestration in India fragments across four structural dimensions that determine pricing power, margin capture, and installation complexity. Product type and end-user concentration drive specification authority, while distribution channel structure dictates last-mile service quality and warranty enforcement.
Product Type:
Supply concentration in thermal-break extrusion capacity favors high-volume product configurations that amortize die costs across standardized production runs.
- Sliding Doors:Horizontal track systems using 6063-T5 alloy frames with twin-roller hardware dominate mass residential towers in Mumbai and Bangalore. Space efficiency governs layout economics in high-rise apartments where every square foot carries premium valuation.
- Casement Windows:Side-hinged configurations with multi-point locking and EPDM compression seals command specification pull in Gujarat and Maharashtra renovation segments. Homeowners prioritize ventilation control and acoustic dampening in premium redevelopment clusters.
- Bi-fold Doors:Concertina-fold systems with bottom-hung or top-hung hardware enable maximum aperture openings in luxury villa segments.
- Fixed Windows:Non-operable glazing support frames dominate commercial curtain wall specifications where structural load bearing trumps operability.
Today's leader: Sliding doors. Tomorrow's challenger: Casement windows.
End User:
Cost tier differentiation separates specification-intensive commercial projects from price-sensitive residential mass housing.
- Residential:High-rise apartments in Mumbai's Bandra-Kurla Complex and Delhi NCR specify thermal-break systems with acoustic performance guarantees. BIS IS 4020 compliance is becoming table stakes for developer pre-qualification.
- Commercial:IT corridor office towers in Bangalore and Hyderabad drive demand for unitized curtain walls with integrated aluminum fenestration. The Energy Conservation Building Code mandates low-emissivity glazing in projects above specified floor areas, forcing thermal-break frame adoption.
- Industrial:Factory and warehouse specifications prioritize structural durability over thermal performance, accepting non-thermal-break profiles at lower price points.
- Government:Public infrastructure projects follow Central Public Works Department schedules with standardized specifications and compressed bidding windows.
Commercial applications are climbing the fastest as compliance mandates harden.
Installation Type:
Volume concentration in new construction favors factory-finished systems over site-fabricated alternatives where MahaRERA and K-RERA timelines apply.
- New Construction:Greenfield residential and commercial towers in Pune and Chennai specify pre-fabricated aluminum modules installed during structural frame completion. Factory finishing ensures IS 4020 water-tightness certification before site delivery.
- Renovation:Premium tower replacements in Lower Parel and South Mumbai create specification windows for architect-grade systems with performance warranties. Existing structural openings constrain profile selection and drive custom extrusion requirements.
- Retrofit:Building envelope upgrades replace aging wood and steel fenestration with thermally broken aluminum across institutional and commercial assets.
- Modular:Prefabricated volumetric construction in affordable housing schemes specifies standardized window and door units for rapid site assembly.
New construction commands current volume. Renovation offers margin expansion.
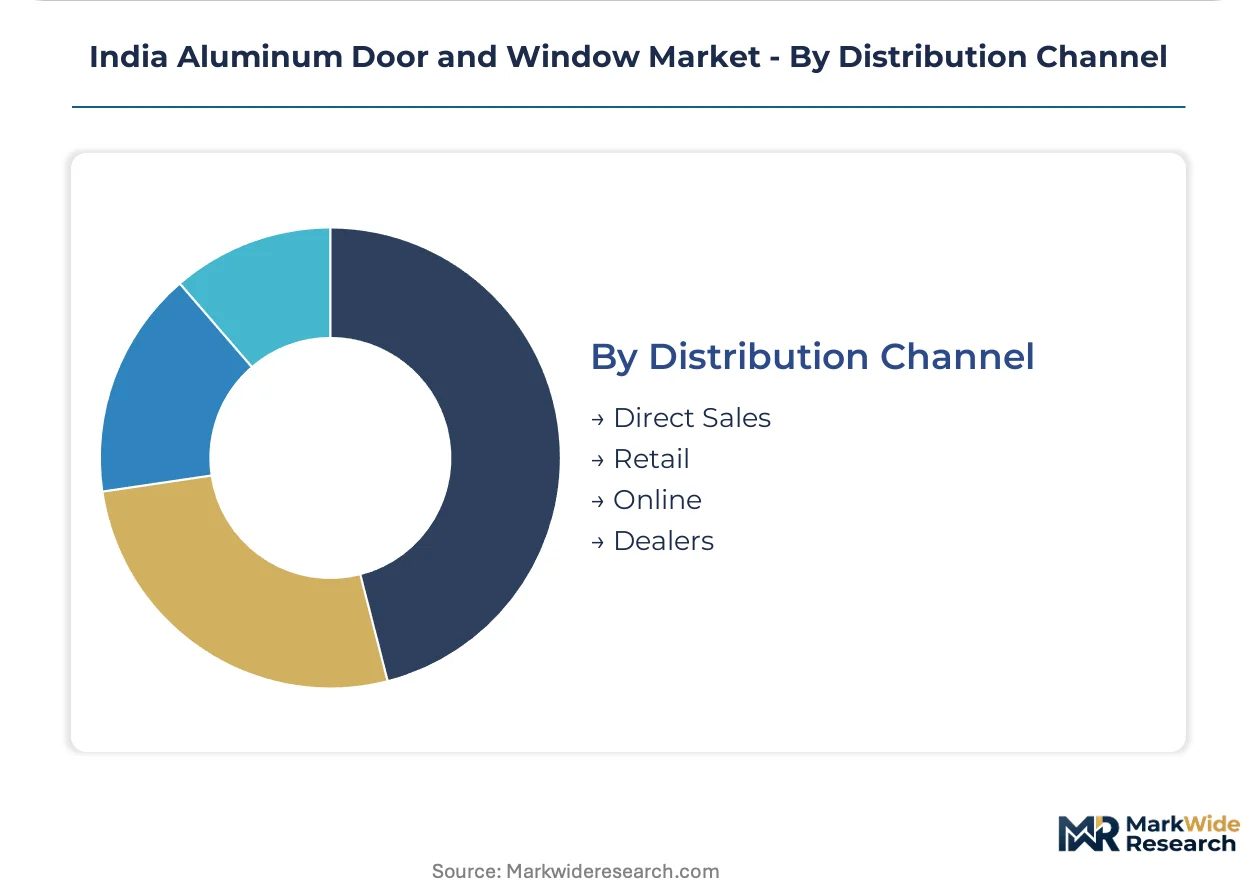
Distribution Channel:
Customer type stratification between project developers and individual homeowners determines channel economics and service intensity.
- Direct Sales:Large developers in Mumbai and Bangalore negotiate system supply contracts directly with fabricators maintaining in-house testing laboratories. Specification authority consolidates with performance-guaranteed suppliers.
- Retail:Individual homeowners in tier-2 cities access standard profiles through building material stores with limited installation support.
- Online:Digital platforms aggregate fabricator catalogs for architect specification research, though final procurement remains offline for warranty enforcement.
- Dealers:Fenesta and comparable networks control last-mile service quality through certified installer training for gasket installation and water-tightness testing.
Dealer networks defend service quality. Direct sales capture specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai's premium redevelopment clusters anchor Indian aluminum fenestration demand, with Maharashtra and Gujarat driving material substitution from uPVC to thermal-break systems in high-rise residential construction.
Maharashtra
Mumbai's Bandra-Kurla Complex and Lower Parel tower developments specify architect-grade aluminum systems with acoustic performance guarantees. MahaRERA enforces compressed project timelines that favor pre-fabricated fenestration modules over site-fabricated alternatives. Pune fabricators are adopting thermal-break polyamide technology fastest, reducing delivery cycles for customized residential projects.
Gujarat
Ahmedabad and Surat residential builders are shifting from uPVC to aluminum frames for high-rise balconies as thermal-break costs narrow. The state's urban development authority mandates energy-efficient building envelopes in commercial projects above specified floor areas. GIFT City commercial towers specify unitized curtain walls with integrated aluminum fenestration.
Karnataka
Bangalore's IT corridor commercial towers drive specification pull for high-performance glazing support systems. K-RERA timelines compress installation windows and favor factory-finished aluminum systems. Whitefield and Electronic City office developments are pre-qualifying fabricators based on certified IS 4020 test reports.
Telangana
Hyderabad's HITEC City and Gachibowli office clusters specify low-emissivity glazing with thermally broken frames under Energy Conservation Building Code mandates. The state's real estate regulator enforces project completion schedules that advantage pre-fabricated fenestration. Fabricators in the city are upgrading extrusion die precision to meet tightening BIS protocols.
Delhi-NCR
Gurugram and Noida commercial developments specify thermal-break aluminum for compliance with the Bureau of Energy Efficiency's low-emissivity glazing mandates. Delhi's premium residential renovation segment commands casement windows with multi-point locking and acoustic dampening. Noida fabricators are building certified installer networks for gasket installation and water-tightness testing.
India Aluminum Door and Window Market Competitive Landscape
Global majors compete with regional champions across specification authority and last-mile service quality in Indian aluminum fenestration. The vendor base stratifies into three tiers: integrated metal producers controlling upstream extrusion, nationwide dealer-network operators, and city-specific project specialists. Two dominant competitive moves are visible: captive supply consolidation among integrated producers and certified installer network expansion among fabricators competing on service quality.
Among integrated producers, Hindalco Industries anchors upstream supply through captive aluminum extrusion capacity. Within the dealer-network tier, Fenesta exemplifies nationwide coverage controlling last-mile service quality. Alupure occupies a specialist position in architect-specified projects for luxury residential towers. These three represent distinct competitive archetypes: upstream-integrated supply, service-network scale, and premium project specialization.
| Leading Market Players |
|---|
| Alteza |
| Alupure |
| Fenesta |
| Aluking |
| Reynaers Aluminium |
| Eternia Windows |
| Encraft India |
| Hindalco Industries |
| Tostem India |
| Others |
Pricing and Supply Chain Analysis
Thermal-break polyamide strip adoption is simultaneously compressing fabrication costs and fragmenting supply chain control across Indian aluminum fenestration. This technology shift enables regional fabricators to source standard 6063-T5 extrusions locally and apply thermal barriers in-house, reducing dependence on integrated producers like Hindalco Industries for finished profiles while intensifying price competition in mid-market residential segments.
Pricing Analysis
Input-cost pass-through from primary aluminum volatility shapes project quotation stability across the value chain. Pricing stratifies across architect-grade systems with IS 4020 certification, standard thermal-break configurations for mass residential towers, and non-certified economy profiles for tier-2 markets. Hindalco's captive smelter capacity and power tariff exposure compress extrusion margins, forcing fabricators to absorb cost swings or risk contract losses. Cost-sensitive developers in Surat and Ahmedabad exhibit highest price sensitivity, while Mumbai premium redevelopment projects prioritize performance guarantees over unit economics.
Supply Chain Analysis
Certification gating through BIS IS 4020 and IS 1948 testing protocols concentrates qualified supply among fabricators maintaining in-house testing laboratories. Raw material dependencies center on primary aluminum from domestic smelters, polyamide thermal break strips from European and East Asian suppliers, and EPDM gasket compounds from specialty chemical producers. Single-source vulnerability runs through polyamide strip supply, where specialized extruders in Germany and Japan dominate high-performance thermal barrier formulations. Distribution runs through dealer-installer networks for residential warranty enforcement and direct sales for commercial specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indian aluminum fenestration offers margin expansion as thermal-break technology cost-down curves and BIS compliance premiums reshape pricing power toward certified fabricators.
For Market Incumbents: Anticipate intensifying competition from regional fabricators in Pune and Chennai adopting in-house thermal-break capability by locking exclusive alloy 6063-T6 billet supply contracts with Hindalco Industries. Invest in certified installer network density ahead of IS 4020 enforcement expansion, as last-mile service quality becomes the primary differentiation lever against price-competitive entrants. For New Entrants and Emerging Players: The premium-economy price gap in tier-2 Gujarat and Maharashtra residential construction creates white-space for mid-tier thermal-break systems with streamlined certification paths. Target Surat and Ahmedabad high-rise balcony specifications where uPVC displacement accelerates but architect-grade Mumbai pricing remains unachievable. Pursue fabricator partnerships with existing extrusion capacity rather than greenfield die investments. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators with certified testing infrastructure and undeveloped dealer network scale. The five-to-ten-year viability window favors acquisition targets with demonstrated IS 4020 compliance and installed base in Bangalore or Hyderabad IT corridor commercial towers. Watch polyamide thermal break technology licensing agreements as inflection indicators for supply chain control shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Billet Casting | Hindalco Industries secures alloy 6063-T5 supply continuity against primary aluminum volatility. |
| Certified Installer Network Expansion | Fenesta controls last-mile service quality for IS 4020 water-tightness warranty enforcement. |
| In-House Testing Laboratory Investment | Fabricators pre-qualify for Bangalore commercial tower specifications requiring documented performance. |
| Polyamide Thermal Break Technology Licensing | Regional fabricators in Pune reduce delivery cycles for customized residential projects. |
| Direct Developer Contracting | Large Mumbai and Bangalore developers consolidate procurement with performance-guaranteed system suppliers. |
Research Methodology
Direct dialogue with extrusion plant managers, architect specification leads, dealer-installer network heads, and Bureau of Energy Efficiency compliance officers grounded this analysis in operational reality. Secondary validation drew from BIS notification records, MahaRERA and K-RERA project registration databases, Hindalco Industries annual disclosures, and customs data on polyamide strip imports. Bottom-up fabrication capacity estimates triangulated against top-down construction sector aluminum consumption trends.
Segment-level value and volume trajectories across the projection horizon reflect modeled interactions between product type substitution patterns, end-user compliance mandates, and channel structure evolution. The analytical framework incorporated thermal-break adoption curves, IS 4020 certification penetration rates by state, and commercial floor area growth in IT corridor clusters. CAGRs derived from regression against historical construction completion data and regulatory phase-in schedules.
Caveats apply where BIS enforcement timing, primary aluminum price spikes, or polyamide supply disruptions could materially shift the outlook. Forecasts rest on assumptions regarding MahaRERA and K-RERA timeline adherence and Energy Conservation Building Code expansion to smaller commercial thresholds. A model refresh is warranted upon material change in thermal-break technology cost curves or state-level green building mandate adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Fireproof Cladding Market
Building Materials
Blind Bolts Market
Building Materials
Global Magnesia Chrome Brick Market
Building Materials
Cross Laminated Timber (CLT) Market
Building Materials
Solar Control Window Film Market
Building Materials
Global Facade Market
Building Materials
Europe Fiber Cement Market
Building Materials
Global Corrugated Steel Sheets Market
Building Materials
Europe Building and Construction Sheets Market
Building Materials
Europe Concrete Admixtures Market
Building Materials
Concrete and Cement Market
Building Materials
Facade Gasket Market
Building Materials
Sprayed Concrete Market
Building Materials
Southeast Asia Concrete Admixtures Market
Building Materials
Engineered Wood Product Market
Building Materials
Cementitious Waterproofing Market