
 Intravascular Warming Systems Market | 2026-2036
Intravascular Warming Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Intravascular Warming Systems Market Intelligence
A shift from outsourced catheter manufacturing toward in-house production of disposable warming sets is repositioning supply economics across the intravascular warming systems landscape. Stryker leverages its orthopedic and surgical ecosystem to bundle temperature management with procedure-specific workflows. BD anchors its position through deep vascular access expertise that extends into integrated warming catheter platforms. Geratherm Medical AG specializes in precision thermal control technologies that differentiate its offerings in European and Asian markets.
Intravascular warming systems are closed-loop temperature management devices that circulate warmed sterile fluid through indwelling catheters to maintain normothermia, typically operating within 37°C to 42°C output ranges with feedback-controlled flow rates. These systems serve primarily to prevent perioperative hypothermia, reduce surgical site infections, and stabilize trauma patients in acute care settings. Heating devices and catheters together capture the dominant share of product value, while hybrid systems that combine convective and resistive elements represent the fastest-expanding technology category. Hospitals command the largest end-user segment by installed base, though ambulance services are emerging as a high-velocity channel driven by pre-hospital trauma protocols.
The FDA enforces 510(k) clearance pathways for thermal regulation devices, while the EU Medical Device Regulation mandates clinical evidence for Class IIa warming systems under its expanded scope. ISO 80601-2-35 establishes particular requirements for patient warming equipment, shaping design standards that manufacturers must satisfy for multi-regional market access. Stakeholders should monitor how evolving FDA guidance on reusable versus disposable components reshapes total cost-of-ownership models and procurement criteria across health system buyers.
Market Dynamics
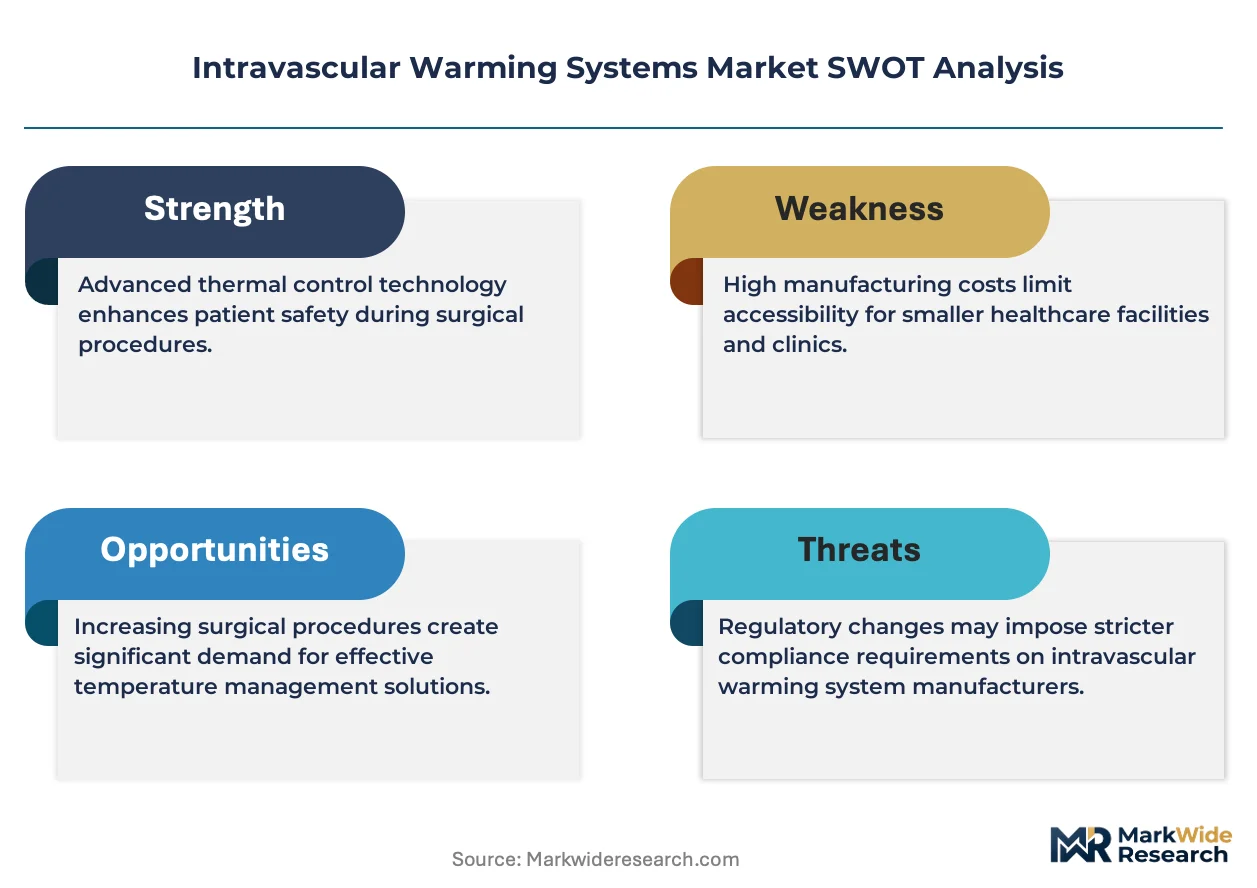
Supply chain reconfiguration toward captive catheter production is compressing margins for contract manufacturers while locking device makers into vertically integrated cost structures that reshape procurement economics across hospital systems.
Growth Catalysts
- Perioperative Protocol Mandates:The Joint Commission's surgical care improvement standards now require active temperature management for qualifying procedures, embedding intravascular warming into routine anesthesia workflows across US health systems.
- Trauma Care Expansion:Pre-hospital emergency medicine protocols in Germany and Japan are incorporating portable warming systems into ambulance fleets, extending addressable demand beyond traditional operating theaters.
- Resistive-Convective Hybrid Designs:Next-generation heating platforms combining fluid circulation with direct thermal transfer achieve faster core temperature restoration, cutting recovery times in cardiac and transplant surgeries.
Market Restraints
- Polymer Cost Volatility:Medical-grade polyurethane and silicone prices fluctuate with petrochemical feedstock markets, squeezing disposable catheter margins without corresponding pricing power.
- Single-Source Component Risk:Precision heating elements and flow sensors concentrate among Taiwanese and South Korean suppliers, creating vulnerability to regional trade disruptions.
- Reusable Component Scrutiny:FDA guidance tightening validation requirements for reprocessed warming circuits extends regulatory timelines and elevates compliance costs for hospitals seeking cost recovery.
Strategic Opportunities
- Ambulatory Surgical Centers:Outpatient facilities in the United States remain underpenetrated relative to inpatient surgical volumes, presenting expansion targets for compact, single-patient warming platforms.
- EU MDR Clinical Evidence Pathways:Manufacturers investing early in post-market clinical follow-up studies for Class IIa warming devices secure preferential positioning as notified body capacity tightens.
- Vascular Access Integration:Convergence of central line insertion kits with embedded temperature monitoring creates bundled procedure economics that favor integrated platform vendors.
Industry Challenges
- Bioengineer Talent Scarcity:Cross-functional expertise spanning thermal engineering, hemocompatibility, and regulatory science remains concentrated among a narrow cohort of specialists, inflating R&D compensation costs.
- 510(k) Substantial Equivalence Burden:FDA's evolving predicate device requirements for next-generation warming systems demand increasingly sophisticated comparative testing, extending time-to-market for iterative improvements.
- Legacy EMR Integration:Temperature data capture into electronic health records requires custom interface development across heterogeneous hospital IT environments, complicating deployment scalability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intravascular Warming Systems Market |
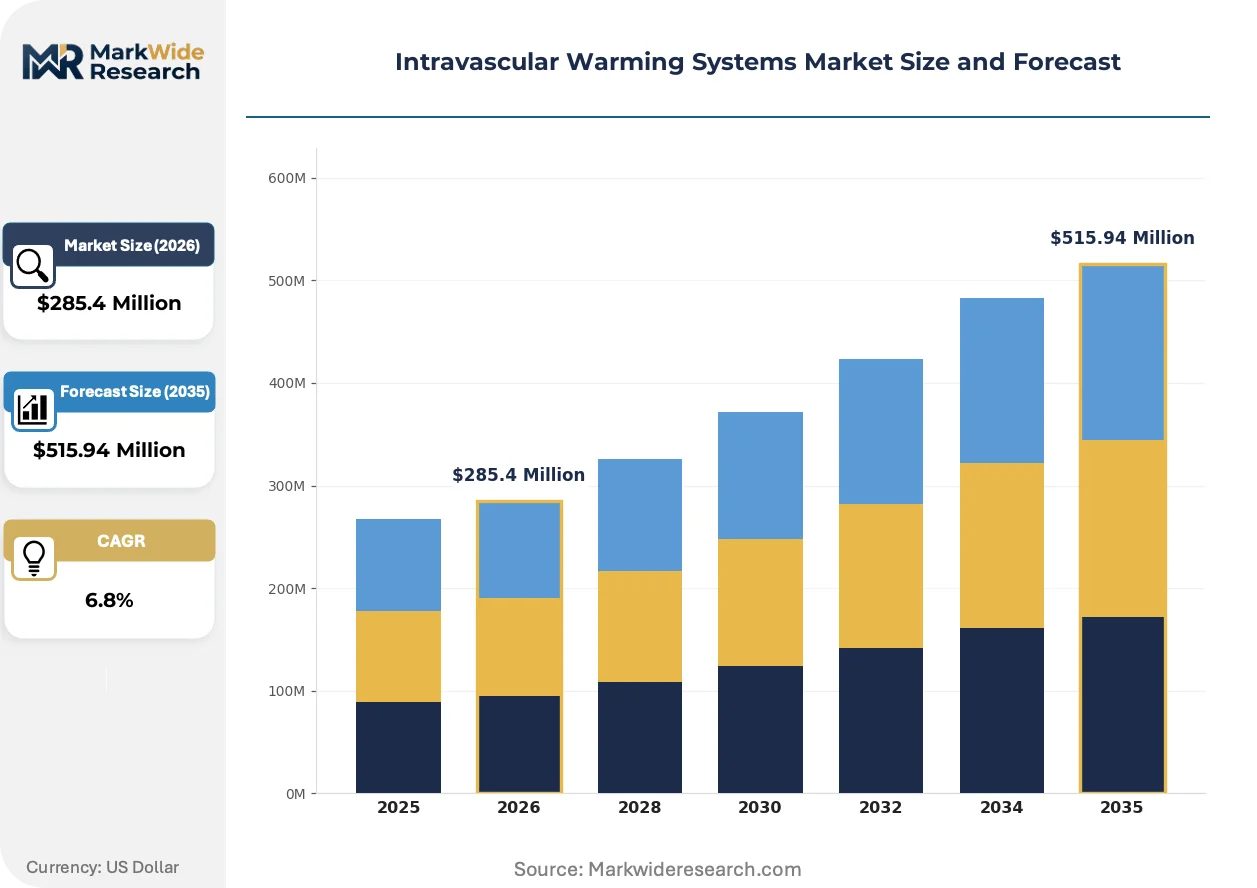
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heating Devices, Catheters, Accessories, Control Units End User: Hospitals, Emergency Rooms, Clinics, Ambulance Services Technology: Convective Heating, Resistive Heating, Hybrid Systems, Infrared Heating Application: Surgical Procedures, Trauma Care, Hypothermia Treatment, Cardiac Care |
| Companies Covered | 3M, Stryker, BD, ZOLL Medical Corporation, Geratherm Medical AG, Smiths Medical, Medtronic, Inspiration Healthcare Group plc, Estill Medical Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intravascular Warming Systems Market Strategic Shifts & Innovations
Technology convergence and regulatory compression are accelerating product lifecycle velocity while forcing manufacturers to embed compliance architecture earlier in development pipelines.
Closed-loop feedback systems with embedded machine learning algorithms for predictive thermal response are overtaking fixed-setpoint controllers in premium system configurations. Academic medical centers in the United States and Switzerland are piloting these adaptive platforms for complex multi-hour procedures. The shift is compressing demand for conventional proportional-integral controllers and elevating software validation to critical path status in product development.
The EU Medical Device Regulation's expanded clinical evidence requirements for patient warming equipment are forcing manufacturers to redesign post-market surveillance infrastructure. Notified bodies now demand systematic literature reviews and PMCF studies for 510(k)-cleared predicates seeking CE marking renewal. German and French health technology assessment bodies are incorporating this clinical data into procurement scoring, advantaging vendors with established European trial networks.
Hospital purchasing committees are consolidating temperature management device selection under perioperative service line contracts rather than capital equipment budgets. This shift transfers ownership risk to manufacturers while compressing upfront hardware margins into recurring disposable revenue streams. The transition is most advanced in US integrated delivery networks and NHS England supply chains, where total cost-of-ownership modeling dominates vendor evaluation.
Intravascular Warming Systems Market Segmentation
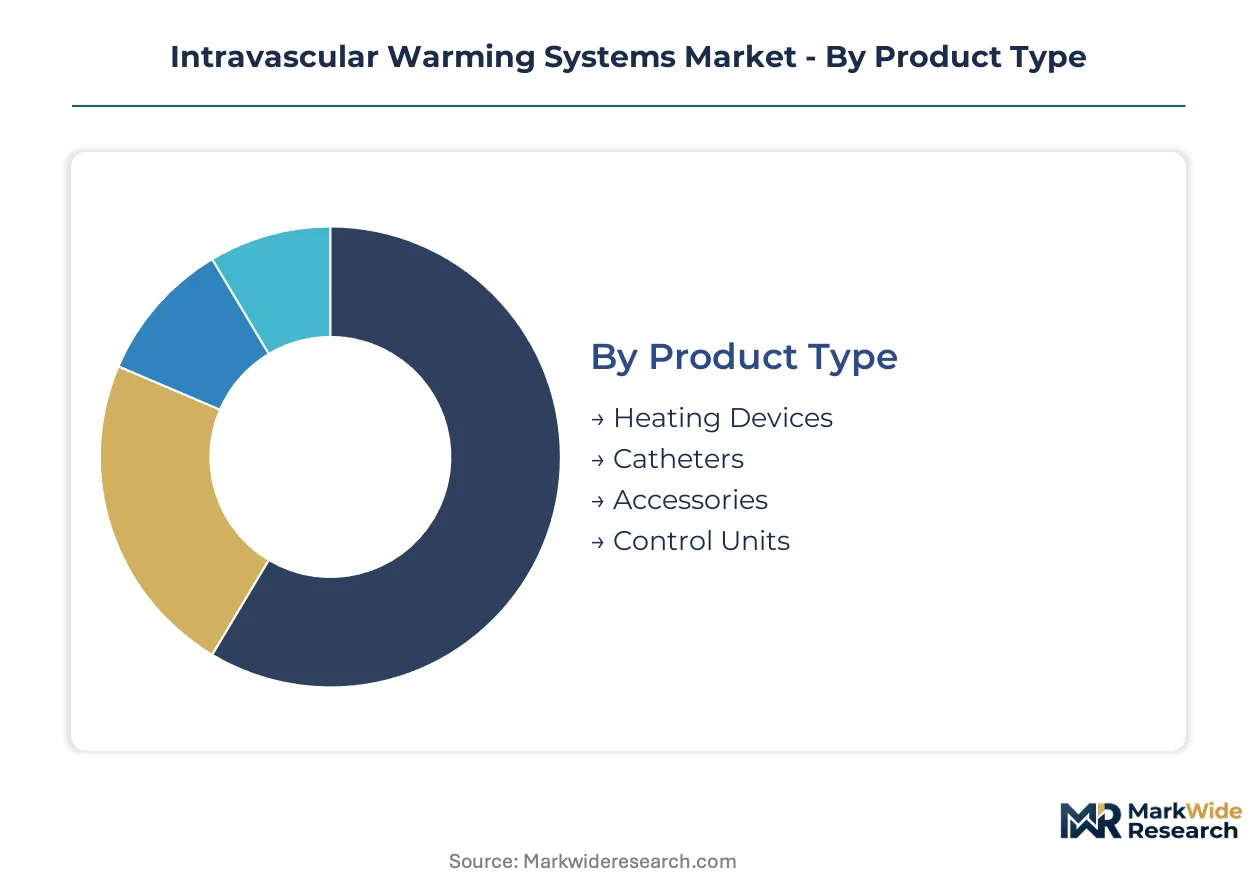
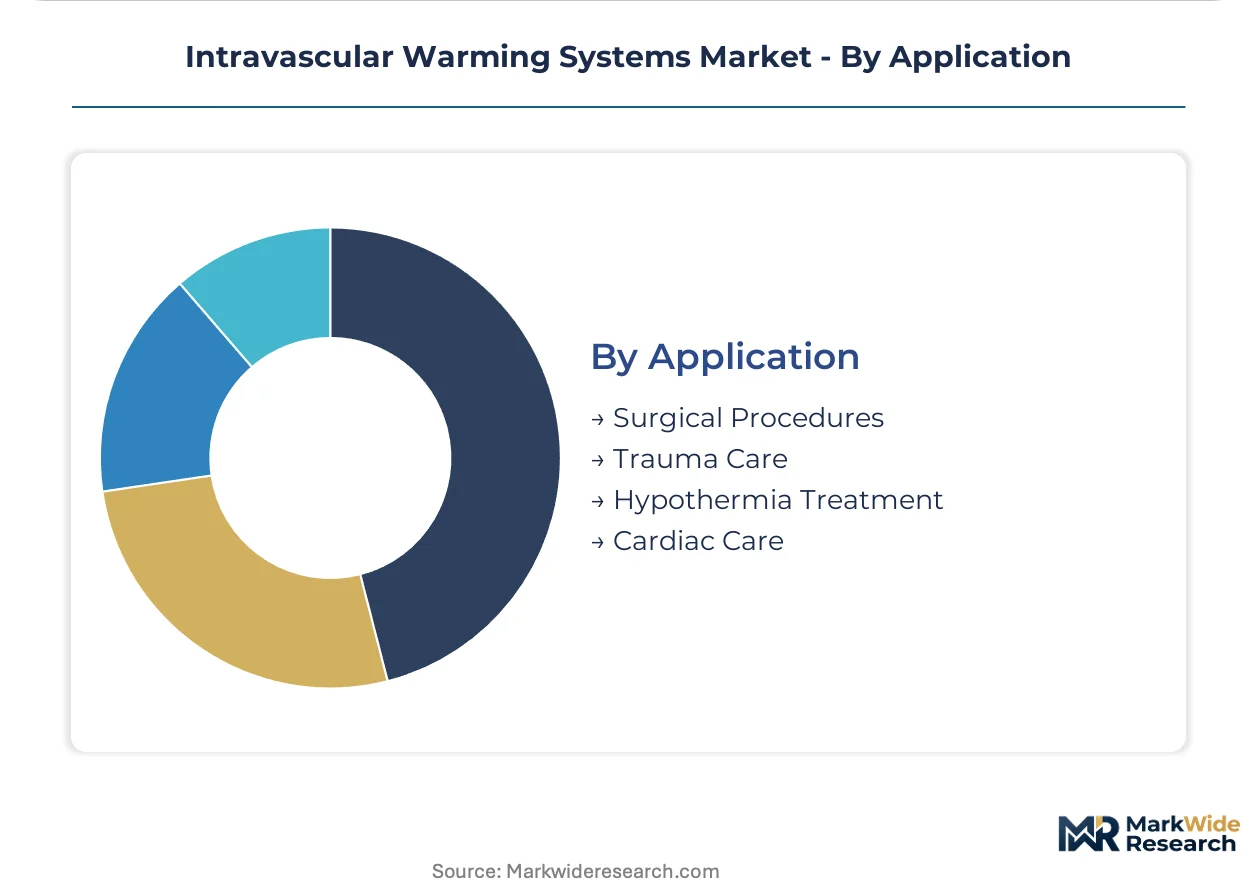
Intravascular warming systems segment across multiple dimensions that shape procurement economics and clinical deployment strategies. Product configuration, care setting, thermal technology, and procedure type each create distinct value pools with divergent margin profiles and regulatory pathways.
Product Type:
Supply concentration for precision heating elements and flow sensors among Taiwanese and South Korean suppliers compresses margins for catheter-dependent product lines while favoring integrated platform vendors with captive component sourcing.
- Heating Devices:These units generate and regulate warmed sterile fluid circulation through closed-loop thermal management, typically incorporating resistive or convective heating chambers with feedback-controlled output. Demand concentrates in United States hospital systems where The Joint Commission's perioperative temperature mandates have standardized active warming protocols across surgical service lines. Supply chain reconfiguration toward in-house catheter production is locking device makers into vertically integrated cost structures.
- Catheters:Single-use indwelling warming circuits constructed from medical-grade polyurethane or silicone deliver thermal transfer directly to the patient's vascular system. German and Japanese ambulance fleets are driving pre-hospital adoption of portable catheter configurations for trauma stabilization outside traditional operating theaters.
- Accessories:Disposable tubing sets, connection adapters, and sterile drapes complete the warming circuit assembly. These components face polymer cost volatility that squeezes margins without corresponding pricing power.
- Control Units:Interface modules manage temperature setpoints, flow rates, and alarm thresholds. FDA 510(k) clearance pathways for these embedded software systems demand increasingly sophisticated validation documentation.
Heating devices absorb the bulk of installed capacity; catheters are expanding most quickly as disposable revenue streams displace capital equipment sales.
End User:
Procurement authority is consolidating under perioperative service line contracts rather than capital equipment budgets, transferring ownership risk to manufacturers and compressing upfront hardware margins.
- Hospitals:Inpatient surgical departments command the largest installed base of intravascular warming platforms, with integrated delivery networks in the United States deploying these systems across cardiac, transplant, and major abdominal procedure portfolios. NHS England supply chains have advanced total cost-of-ownership modeling that dominates vendor evaluation.
- Emergency Rooms:Acute care bays utilize portable warming configurations for rapid core temperature restoration in hemodynamically unstable patients. These settings prioritize compact footprint and rapid deployment over sophisticated monitoring integration.
- Clinics:Outpatient surgical facilities remain underpenetrated relative to inpatient volumes, presenting expansion targets for single-patient warming platforms with simplified operational requirements.
- Ambulance Services:Pre-hospital emergency medicine protocols in Germany and Japan are incorporating portable warming systems into fleet equipment standards, extending addressable demand beyond traditional hospital walls.
Hospitals retain dominant procurement volume; ambulance services are climbing the fastest as pre-hospital trauma protocols mature.
Technology:
Technology convergence is accelerating product lifecycle velocity while forcing manufacturers to embed compliance architecture earlier in development pipelines.
- Convective Heating:Fluid circulation systems transfer thermal energy through warmed saline or crystalloid solutions circulating at controlled flow rates. These established platforms face displacement pressure from hybrid configurations.
- Resistive Heating:Direct electrical resistance elements warm circulating media without combustion or open flame, offering precise temperature control with rapid response characteristics.
- Hybrid Systems:Next-generation platforms combining fluid circulation with direct thermal transfer achieve faster core temperature restoration, cutting recovery times in cardiac and transplant surgeries. Academic medical centers in the United States and Switzerland are piloting these adaptive configurations.
- Infrared Heating:Non-contact thermal radiation systems offer alternative warming modalities with reduced fluid management requirements. These technologies occupy niche applications where fluid volume restriction is clinically paramount.
Convective and resistive platforms hold established installed bases; hybrid systems are gaining share fastest as procedure time compression becomes a competitive priority.
Application:
Clinical evidence requirements under EU MDR are forcing manufacturers to redesign post-market surveillance infrastructure for procedure-specific warming indications.
- Surgical Procedures:Perioperative normothermia maintenance represents the core application, with The Joint Commission standards embedding active temperature management into routine anesthesia workflows across US health systems.
- Trauma Care:Pre-hospital and emergency department deployment for hypothermic trauma patients drives demand for portable, rapid-deployment configurations. German emergency medical services have standardized warming protocols for severe hemorrhage cases.
- Hypothermia Treatment:Therapeutic temperature management for accidental or environmental hypothermia requires precise controlled rewarming capabilities to avoid afterdrop and cardiac instability.
- Cardiac Care:Cardiopulmonary bypass and interventional cardiac procedures demand high-capacity thermal exchange with integrated temperature monitoring. These applications command premium pricing for specialized catheter configurations.
Surgical procedures anchor current utilization; trauma care is expanding most quickly as pre-hospital protocols extend warming initiation earlier in the care continuum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems command the dominant share of installed intravascular warming capacity, with perioperative hypothermia protocols now standard across major surgical networks. Germany and Japan are accelerating pre-hospital adoption through ambulance fleet modernization. Supply chain reconfiguration toward captive catheter production is compressing margins for contract manufacturers in Taiwan and South Korea.
United States
The Joint Commission's surgical care improvement standards mandate active temperature management for qualifying procedures, embedding intravascular warming into routine anesthesia workflows across integrated delivery networks. FDA 510(k) clearance pathways govern thermal regulation devices with tightening validation requirements for reusable components. The Greater Boston and Pacific Northwest medical device clusters host concentrated R&D activity for next-generation hybrid heating platforms.
Germany
Pre-hospital emergency medicine protocols incorporate portable warming systems into ambulance fleet equipment standards, extending addressable demand beyond traditional operating theaters. EU Medical Device Regulation mandates clinical evidence for Class IIa warming systems under expanded scope requirements. The Baden-Württemberg and Bavaria industrial corridors concentrate precision thermal control engineering expertise for European market supply.
Japan
Trauma care expansion drives adoption of rapid-deployment warming configurations for severe hemorrhage cases in metropolitan emergency medical services. METI and PMDA oversee medical device approval pathways with particular attention to hemocompatibility testing standards. The Kansai region around Osaka anchors domestic manufacturing of vascular access components integrated with temperature management functions.
Switzerland
Academic medical centers pilot adaptive closed-loop feedback systems with embedded machine learning algorithms for complex multi-hour procedures. Swissmedic regulates thermal regulation devices with emphasis on software validation documentation. The Basel and Zurich life sciences clusters concentrate cross-functional expertise spanning thermal engineering and regulatory science.
South Korea
Precision heating elements and flow sensors concentrate among domestic suppliers, creating single-source component risk for global device manufacturers. MFDS oversees medical device quality management system requirements aligned with international standards. The Seoul Capital Area hosts concentrated electronics manufacturing capacity for medical-grade sensor components.
Intravascular Warming Systems Market Key Industry Players
Strategic partnerships dominate the current landscape as manufacturers seek to bundle temperature management with procedure-specific workflows and vascular access platforms. The vendor base concentrates among diversified medical device conglomerates with established perioperative service line relationships and specialized thermal control technology firms with regional expertise. Three archetypes define competitive positioning: orthopedic and surgical ecosystem integrators, vascular access platform specialists, and precision thermal control technology developers. M&A activity and backward integration into catheter production represent the dominant competitive moves reshaping supply economics.
Among diversified medical device conglomerates, Stryker and BD exemplify contrasting strategic positions. Stryker leverages its orthopedic and surgical ecosystem to anchor bundled temperature management offerings within procedure-specific workflows. BD occupies a position extending deep vascular access expertise into integrated warming catheter platforms. Geratherm Medical AG represents the precision thermal control specialist archetype, with its AG suffix indicating German corporate structure and European market orientation.
| Leading Market Players |
|---|
| 3M |
| Stryker |
| BD |
| ZOLL Medical Corporation |
| Geratherm Medical AG |
| Smiths Medical |
| Medtronic |
| Inspiration Healthcare Group plc |
| Estill Medical Technologies |
| Others |
Cost & Logistics Intelligence
Medical-grade polyurethane and silicone feedstock costs cascade through catheter manufacturing into three-tier pricing structures that separate premium FDA-validated systems from standard CE-marked configurations and economy-tier regional alternatives. Contract manufacturers in Taiwan and South Korea absorb margin compression as device makers accelerate backward integration into captive catheter production, locking in supply security at the expense of pricing flexibility downstream.
Pricing Analysis
Capital equipment sales absorb volume while recurring disposable revenue streams capture margin expansion across the installed base. Three-tier pricing structure across premium, standard, and economy levels differentiates systems by FDA 510(k) validation tier, ISO 80601-2-35 certification depth, and bundled service integration. Pricing pressure stems from polymer cost volatility without corresponding hospital pricing power. Ambulatory surgical centers exhibit highest price sensitivity; cardiac surgery suites demonstrate lowest sensitivity due to procedure-critical thermal management requirements.
Supply Chain Analysis
Reverse-logistics flows for reprocessed warming circuits face FDA guidance tightening that extends validation timelines and elevates compliance burdens for hospitals seeking cost recovery. Precision heating elements and flow sensors concentrate in Taiwan, South Korea, and Japan, creating single-source vulnerability to regional trade disruptions. The supply chain draws from medical-grade polyurethane, silicone elastomers, and embedded temperature sensors. Tariff exposure on Taiwanese electronics components threatens margin stability. Distribution runs through hospital GPO contracts, integrated delivery network procurement committees, and specialized medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intravascular warming systems market has become a vertical-integration race as manufacturers pursue upstream control over catheter production to escape contract manufacturer margin compression and secure supply continuity.
For Market Incumbents: Deploy perioperative service line bundling as the primary defensive lever. Stryker and BD should deepen hospital system partnership density to lock out emerging platform competitors, while accelerating software companion development for EMR integration to raise switching costs. The threat of hybrid resistive-convective systems from specialized thermal control firms demands rapid certification investment to maintain predicate device advantages under evolving FDA substantial equivalence requirements. For New Entrants and Emerging Players: Ambulance service procurement channels offer the most penetrable entry vector for portable warming configurations, given German and Japanese fleet modernization timelines and lower incumbent saturation outside hospital walls. Target outpatient surgical centers in the United States with compact single-patient platforms that bypass capital committee approval cycles. A reimbursement strategy emphasizing total cost-of-ownership modeling aligns with NHS England and integrated delivery network evaluation frameworks. For Investors and Strategic Acquirers: FDA 510(k) clearance for machine learning-enabled closed-loop feedback systems is the leading indicator that adaptive thermal platforms will command premium positioning. The five-to-ten year viability window favors acquisition targets with established European trial networks and post-market clinical follow-up infrastructure under EU MDR. Monitor notified body capacity constraints as the signal for which vendors will secure preferential CE marking renewal positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catheter Production | Captive supply of disposable warming circuits locks margin capture and insulates against Taiwanese sensor supply volatility. |
| FDA 510(k) Submission for Hybrid Systems | Resistive-convective platform clearance secures predicate advantages as The Joint Commission mandates tighten. |
| Hospital System Partnership | Perioperative service line contracts transfer ownership risk to manufacturers while embedding systems across cardiac and transplant workflows. |
| Software Companion Development | EMR integration modules address legacy IT heterogeneity and raise competitive switching costs for hospital buyers. |
| CE Marking Pathway Investment | EU MDR clinical evidence preparation secures preferential positioning as notified body capacity tightens across German and French assessment bodies. |
Research Approach
Independent corroboration across primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and ISO 80601-2-35 technical standards. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators to ensure consistency across volume and value outputs.
Comparable-period anchoring to historical surgical procedure volumes and thermal management device installations established the forecast baseline across the projection horizon. The analytical framework models demand by product configuration, care setting, thermal technology platform, and procedure type specificity. CAGRs derive from segmented growth rate reconciliation against aggregate market expansion. Forecast inputs incorporate The Joint Commission protocol adoption curves, EU MDR transition timelines, and ambulance fleet modernization schedules.
Several conditions sit outside the modeled scope, including unforeseen regulatory guidance revisions on reusable component validation, acute polymer feedstock price shocks, and geopolitical trade disruptions affecting Taiwanese sensor supply. Forecasts reflect assumptions about perioperative protocol standardization continuity and reimbursement stability. Practitioners should monitor FDA guidance evolution on machine learning-enabled devices and notified body capacity announcements for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Vascular Guidewires Market
Medical Devices
In Vitro Fertilization Monitoring System Market
Medical Devices
Medical Device Connectivity Market
Medical Devices
Micro Syringes Market
Medical Devices
Digital Sphygmomanometer Market
Medical Devices
Submucosal Injections Market
Medical Devices
Kirschner Wires Market
Medical Devices
Cervical Spine System Market
Medical Devices
Global Asthma and Copd Devices Market
Medical Devices
Mexico Artificial Organs and Bionic Implants Market
Medical Devices
Global Wheelchair Market
Medical Devices
Waterproof Orthotics Market
Medical Devices
Next Generation Implants (NGI) Market
Medical Devices
Veterinary Ultrasound Scanners Market
Medical Devices
Endoscope Procedure Kits Market
Medical Devices
Global Neurology Ultrasonic Aspirators Market