
 In Vitro Fertilization Monitoring System Market | 2026-2036
In Vitro Fertilization Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
In Vitro Fertilization Monitoring System Market Foresight
Modular platform bundling is pivoting how fertility clinics evaluate capital investments in monitoring infrastructure. Vitrolife leverages integrated workflow designs spanning incubation through imaging to sustain premium positioning in European markets. CooperSurgical anchors its portfolio through consumable-recurring revenue ties to hardware placements. Esco Medical competes on cost-engineered configurations for mid-tier clinic networks across Asia-Pacific expansion corridors.
An in vitro fertilization monitoring system comprises time-lapse imaging platforms, sperm analyzers, and embryo culture workstations operating at 37°C with 5-6% CO2 control, designed to maintain viability while capturing morphokinetic data for selection algorithms. The technology segment splits across microscopy hardware, software-driven image analysis, and genetic testing integration, with software solutions capturing expanding margin pools as clinics prioritize predictive embryo scoring over standalone imaging. Fertility clinics dominate end-user demand, though research laboratories represent the fastest-growing installation base as preclinical toxicology studies adopt human embryo models under revised OECD testing frameworks.
The FDA regulates IVF monitoring devices as Class II medical products requiring 510(k) premarket notification, while the EMA's Medical Device Regulation imposes post-market surveillance obligations across European fertility networks. ISO 13485 quality management certification functions as a baseline market-access filter for manufacturers serving regulated jurisdictions. Stakeholders must track evolving reimbursement coding for time-lapse embryo monitoring as health technology assessment bodies in Germany and Japan evaluate cost-effectiveness against conventional morphology evaluation.
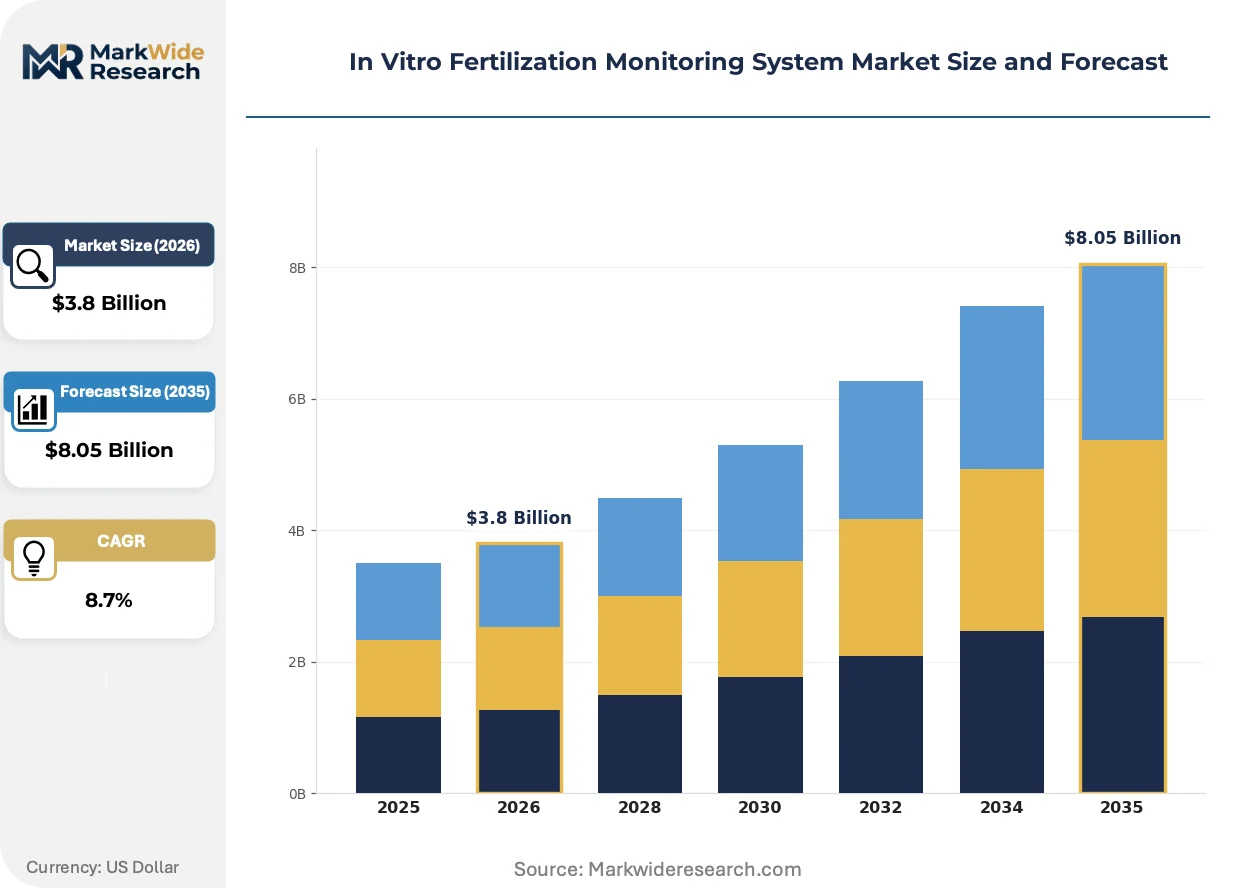
Market Dynamics
Time-lapse embryo imaging platforms are consolidating multiple discrete workflow steps into unified capital investments, forcing fertility clinics to reassess supplier relationships around total cost of ownership rather than device-by-device procurement.
Growth Catalysts
- EMA Medical Device Regulation post-market surveillance:Manufacturers achieving ISO 13485 certification gain accelerated access across European fertility networks, creating compliance-based competitive moats for quality-certified suppliers.
- Preclinical toxicology laboratories:Revised OECD testing frameworks drive adoption of human embryo models, expanding the addressable installation base beyond clinical fertility centers.
- Morphokinetic selection algorithms:Clinics prioritize predictive embryo scoring capabilities, elevating software-driven image analysis above standalone microscopy hardware in purchasing hierarchies.
Market Restraints
- Precision optical component supply:German and Japanese specialty lens manufacturers concentrate critical sensor supply, exposing downstream device makers to single-source vulnerability.
- FDA 510(k) premarket notification:Class II medical device classification imposes 12-18 month clearance timelines, compressing first-mover advantage windows for novel imaging modalities.
- Conventional morphology evaluation:Established low-cost assessment protocols retain reimbursement preference in budget-constrained public healthcare systems, slowing premium platform penetration.
Strategic Opportunities
- Mid-tier clinic networks across Asia-Pacific:Cost-engineered monitoring configurations address capital constraints in expanding fertility markets outside premium reimbursement zones.
- Genetic testing integration:Convergence of time-lapse imaging with preimplantation genetic testing workflows creates bundled service revenue streams for integrated platform vendors.
- German health technology assessment bodies:Pending cost-effectiveness evaluations for time-lapse monitoring may unlock statutory reimbursement codes, accelerating clinic adoption decisions.
Industry Challenges
- Embryology laboratory workflow integration:Legacy incubator systems require extensive retrofitting to accommodate continuous imaging hardware, extending installation timelines and staff training burdens.
- ISO 13485 quality management certification:Documentation intensity and audit frequency impose sustained operational overhead on manufacturers serving regulated jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Vitro Fertilization Monitoring System Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Time-Lapse System, Ovulation Predictor Kit, Sperm Analyzer, Embryo Imaging System Technology: Microscopy, Software Solutions, Imaging Technology, Genetic Testing End User: Fertility Clinics, Hospitals, Research Laboratories, Diagnostic Centers Application: Embryo Culture, Sperm Retrieval, Fertility Testing, Genetic Screening |
| Companies Covered | Vitrolife, CooperSurgical, Esco Medical, Carl Zeiss AG, Nikon Corporation, Olympus, FUJIFILM Irvine Scientific, Hamilton Thorne, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Vitro Fertilization Monitoring System Market Shifts & Advancements
Software-driven predictive capabilities are displacing hardware-centric competitive differentiation, while regulatory bodies recalibrate reimbursement frameworks around demonstrated clinical utility rather than technological novelty alone.
Time-lapse embryo monitoring hardware is modularizing around interchangeable imaging cores and standardized culture chamber interfaces. Fertility clinics in Japan and Germany are adopting platform architectures that permit incremental capability upgrades without full system replacement. This shift is compressing replacement cycles while elevating software licensing and predictive algorithm subscriptions above capital equipment margins in vendor revenue models.
The FDA's oversight of assisted reproductive technology devices as Class II medical products shapes product development pathways in the United States. Premarket notification requirements enforce clinical validation standards that delay market entry but establish durable regulatory barriers against uncertified competitors. United States-based manufacturers concentrate 510(k) clearance resources on integrated platforms rather than standalone imaging modules.
Service unbundling is fragmenting traditional capital-plus-consumable bundling models. Fertility clinic buyers in reimbursement-constrained markets are demanding hardware-agnostic software licenses and third-party maintenance contracts. This pattern is most visible in Spain and Italy where independent service organizations now compete directly with original equipment manufacturers for multi-vendor platform support contracts.
In Vitro Fertilization Monitoring System Market Segmentation
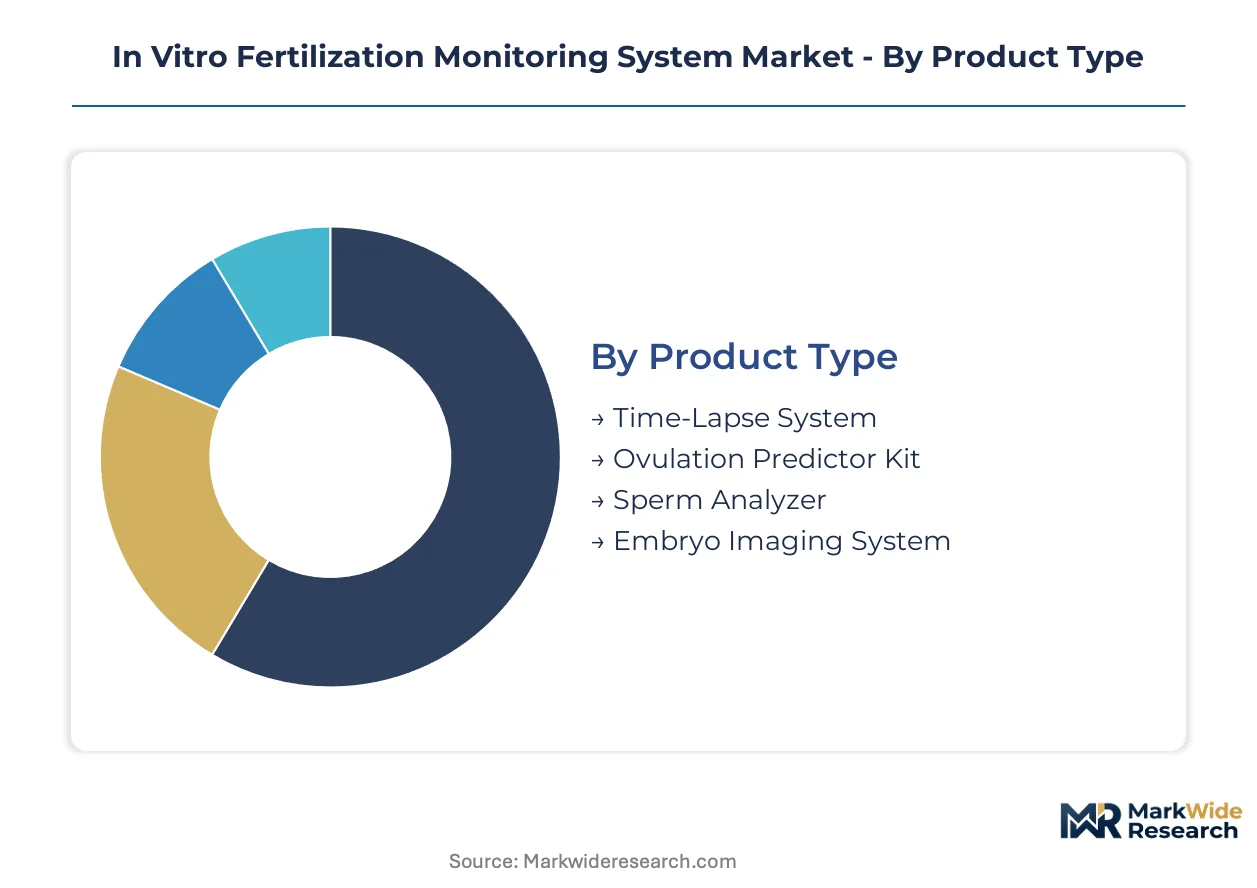
Segmentation in the IVF monitoring market determines capital allocation priorities for fertility clinics navigating bundled platform investments versus modular procurement strategies. Technology convergence across imaging, software, and genetic testing is collapsing traditional category boundaries.
Product Type:
Hardware specifications define workflow integration requirements and replacement cycle economics.
- Time-Lapse System:Continuous embryo imaging platforms capture morphokinetic data at 5-15 minute intervals without culture disturbance. Demand concentrates in Germany and Japan where reimbursement frameworks support premium platform adoption against conventional morphology protocols.
- Embryo Imaging System:Static microscopy workstations with digital image capture enable documentation-driven selection workflows. Fertility clinics in the United States prioritize these systems where FDA 510(k) pathways favor established imaging modalities over novel continuous monitoring hardware.
- Sperm Analyzer:Computer-assisted semen analysis devices quantify motility, morphology, and concentration parameters.
- Ovulation Predictor Kit:Home-use hormonal detection devices for luteinizing hormone surge identification.
Mature deployment sits with Embryo Imaging System. Newer deployment is concentrated in Time-Lapse System.
Technology:
Capability layering determines margin capture and vendor competitive positioning.
- Software Solutions:Predictive embryo scoring algorithms process morphokinetic datasets to generate implantation probability rankings. Research laboratories in Japan are adopting these tools fastest under revised OECD toxicology testing frameworks requiring standardized human embryo model analysis.
- Genetic Testing:Preimplantation genetic testing integration with time-lapse workflows enables simultaneous morphological and chromosomal assessment. Fertility clinics in Germany bundle these capabilities where statutory reimbursement evaluation is pending for combined diagnostic protocols.
- Imaging Technology:Optical sensor arrays and LED illumination systems for embryo visualization.
- Microscopy:Conventional brightfield and phase-contrast optical systems for embryological assessment.
Established revenue concentration rests with Microscopy. Capability expansion is climbing the fastest in Software Solutions.
End User:
Procurement authority and reimbursement access shape purchasing behavior across installation sites.
- Fertility Clinics:Specialized reproductive medicine centers with dedicated embryology laboratories and direct patient billing relationships. These facilities in the United States drive platform adoption where private insurance coverage for advanced IVF procedures exceeds public system reimbursement rates.
- Research Laboratories:Academic and contract research organizations conducting preclinical toxicology and developmental biology studies. Installations in Japan are expanding most quickly under regulatory pressure to replace animal models with human embryo-based screening protocols.
- Hospitals:General medical centers with obstetrics and gynecology departments offering fertility services.
- Diagnostic Centers:Independent testing facilities providing fertility assessment and referral services.
Volume leadership belongs to Fertility Clinics. Addressable base expansion is gaining share fastest in Research Laboratories.
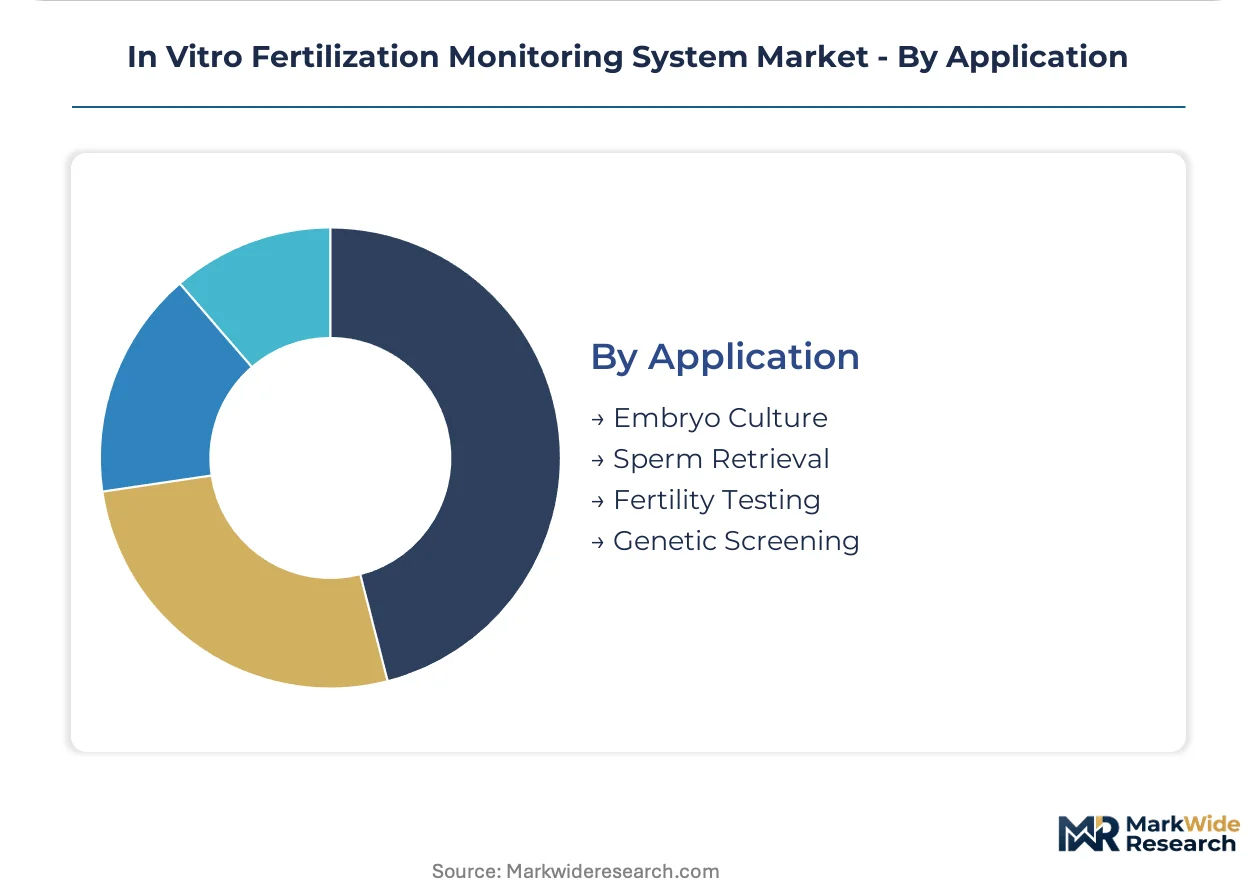
Application:
Clinical utility validation determines reimbursement coding and platform prioritization.
- Embryo Culture:Controlled environment maintenance and developmental progression monitoring from fertilization through blastocyst formation. Demand in Germany concentrates on platforms demonstrating cost-effectiveness against conventional incubation under health technology assessment review.
- Genetic Screening:Chromosomal abnormality detection and single-gene disorder identification integrated with embryo selection workflows. Fertility clinics in the United States deploy these capabilities where patient self-pay tolerance supports premium service pricing outside insurance coverage constraints.
- Sperm Retrieval:Surgical and non-surgical specimen collection procedures with immediate quality assessment.
- Fertility Testing:Diagnostic evaluation of ovarian reserve, tubal patency, and semen parameters.
Standardized deployment sits with Fertility Testing. Technology upgrading is concentrated in Embryo Culture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and Japan where precision optical component suppliers feed device assembly, while consumption clusters in the United States and fertility-focused European markets where reimbursement frameworks enable premium platform adoption.
United States
Fertility clinics in metropolitan corridors drive platform procurement where private insurance coverage exceeds public reimbursement rates for advanced IVF procedures. FDA Class II medical device classification enforces 12-18 month 510(k) clearance timelines that compress first-mover windows for novel imaging modalities. Boston and San Francisco research clusters anchor preclinical toxicology laboratory expansion under revised OECD testing frameworks.
Germany
Health technology assessment bodies evaluate cost-effectiveness of time-lapse embryo monitoring against conventional morphology protocols, pending statutory reimbursement decisions. EMA Medical Device Regulation post-market surveillance obligations shape procurement criteria across European fertility networks. Baden-Württemberg precision optics manufacturers concentrate critical sensor supply for downstream device assembly.
Japan
Research laboratories adopt human embryo models fastest under regulatory pressure to replace animal-based toxicology screening protocols. METI standards coordination supports platform interoperability requirements for fertility clinic networks. Tokyo and Osaka metropolitan areas concentrate both device consumption and embryology research infrastructure investment.
United Kingdom
Fertility clinics navigate post-Brexit regulatory divergence between domestic medical device standards and retained EU MDR obligations. London and Southeast England clusters concentrate private fertility service providers targeting self-pay patient segments. Health technology assessment bodies evaluate embryo monitoring cost-effectiveness within National Health Service budget constraints.
Spain
Independent service organizations compete directly with original equipment manufacturers for multi-vendor platform maintenance contracts in reimbursement-constrained markets. Barcelona and Madrid fertility networks drive demand for hardware-agnostic software licensing arrangements. Regional health authorities maintain budgetary pressure on capital equipment procurement decisions.
In Vitro Fertilization Monitoring System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated structure where scale-driven portfolios face capability-intensive niche positioning. Market concentration remains moderate with no single vendor commanding dominant share across all product categories. Three archetypes define competitive positioning: integrated workflow platform vendors, consumable-recurring revenue specialists, and cost-engineered configuration suppliers. Strategic moves center on portfolio bundling to capture total cost-of-ownership evaluations and geographic expansion into mid-tier clinic networks.
Within the integrated platform tier, Vitrolife exemplifies workflow-spanning positioning from incubation through imaging, while CooperSurgical anchors consumable-recurring revenue ties to hardware placements. Esco Medical occupies the cost-engineered configuration segment targeting capital-constrained clinic networks. These three representations illustrate how competitive differentiation fragments across pricing, capability depth, and service integration vectors.
| Leading Market Players |
|---|
| Vitrolife |
| CooperSurgical |
| Esco Medical |
| Carl Zeiss AG |
| Nikon Corporation |
| Olympus |
| FUJIFILM Irvine Scientific |
| Hamilton Thorne |
| Thermo Fisher Scientific |
| Others |
Supply & Pricing Matrix
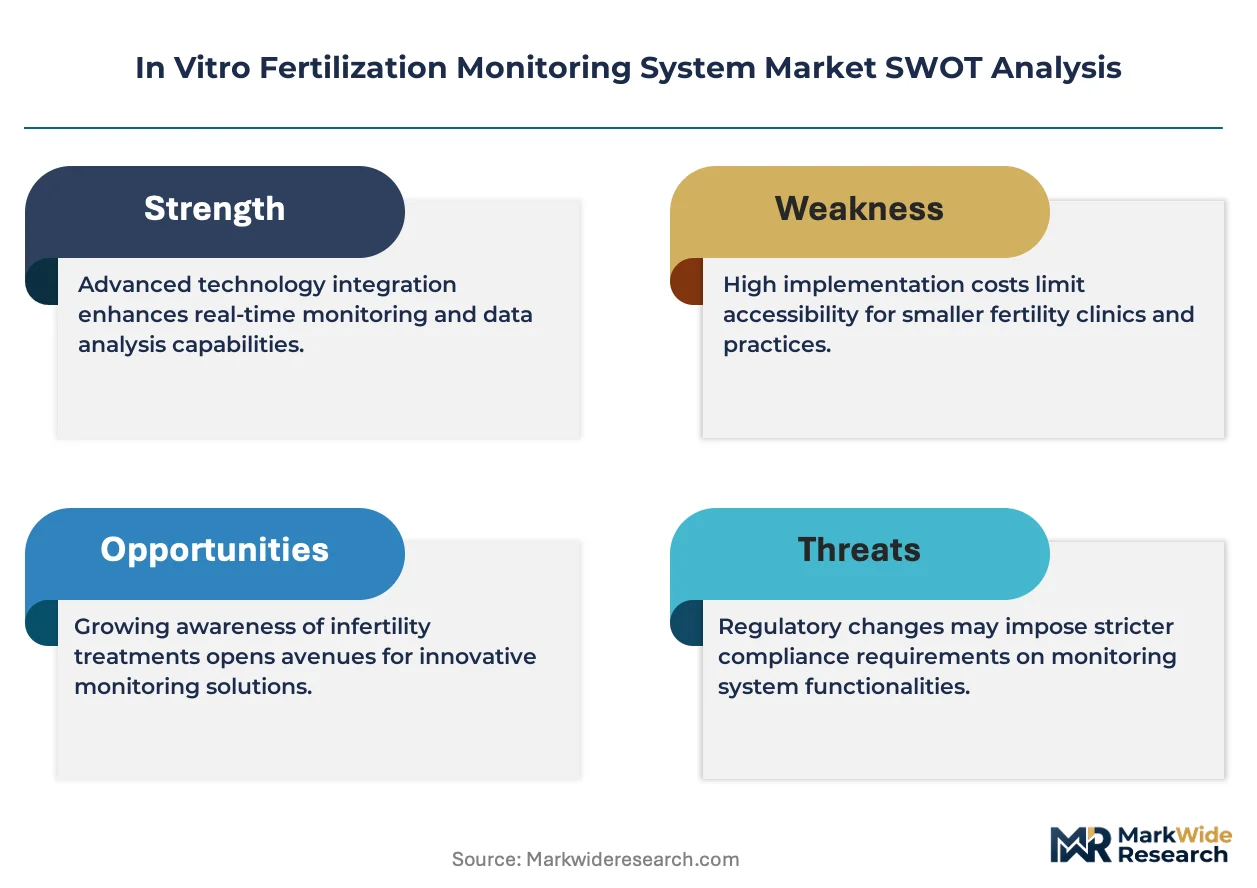
ISO 13485 quality management certification gates qualified supply access and premium-tier pricing power, as fertility clinics in Germany and Japan restrict procurement to certified vendors while mid-tier Asia-Pacific buyers prioritize cost-engineered configurations from uncertified suppliers.
Pricing Analysis
Margin tightening in mid-tier configurations reflects aggressive cost-engineering by Asia-Pacific suppliers targeting capital-constrained clinic networks. Three-tier pricing structure across premium, standard, and economy levels separates integrated workflow platforms from modular imaging hardware and standalone software licenses. Price differentiation rests on FDA 510(k) clearance status and ISO 13485 certification tier. Cost-down pressure on economy-tier systems accelerates because independent service organizations in Spain and Italy now compete for multi-vendor maintenance contracts.
Supply Chain Analysis
Regional distribution centers in Baden-Württemberg and Tokyo prefecture anchor hub-and-spoke patterns serving European and Asia-Pacific fertility networks. Manufacturing concentrates in Germany and Japan where Carl Zeiss and Nikon precision optical facilities feed downstream device assembly. Critical sensor supply draws from specialty lens manufacturers in these countries, creating single-source vulnerability for time-lapse imaging platforms. Distribution runs through authorized dealer networks in reimbursement-rich markets and direct procurement channels in cost-sensitive regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's Class II medical device classification creates a cost-of-compliance story where 12-18 month 510(k) clearance timelines erect durable barrier-to-entry moats for certified incumbents against uncertified competitors.
For Market Incumbents: Deepen consumable-recurring revenue ties to hardware placements to defend against software unbundling trends in Spain and Italy. Escalate ISO 13485 certification investment as competitive moat against emerging cost-engineered entrants from Asia-Pacific. Prioritize backward integration into precision optical component supply to mitigate German and Japanese single-source vulnerability. For New Entrants and Emerging Players: The price-point gap between premium integrated platforms and economy-tier modular systems offers white-space entry for cost-engineered configurations. Target mid-tier clinic networks across Asia-Pacific expansion corridors where capital constraints exceed reimbursement access. Pursue hardware-agnostic software licensing as go-to-market angle to bypass FDA 510(k) hardware clearance barriers. For Investors and Strategic Acquirers: Pending German health technology assessment reimbursement decisions are the leading indicator that statutory coding for time-lapse embryo monitoring will accelerate clinic adoption decisions. Long-term viability over the next decade favors platform vendors with integrated workflow capabilities spanning incubation through genetic testing integration. Monitor EMA Medical Device Regulation post-market surveillance compliance costs as signal for margin compression among sub-scale manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Accelerates European market access under EMA Medical Device Regulation post-market surveillance obligations. |
| Software Companion Development | Captures expanding margin pools as clinics prioritize predictive embryo scoring algorithms over standalone imaging. |
| Reimbursement Strategy | Unlocks statutory coding for time-lapse monitoring pending German health technology assessment cost-effectiveness evaluation. |
| Hospital System Partnership | Anchors platform adoption in United States metropolitan corridors where private insurance coverage exceeds public rates. |
| CE Marking Pathway | Enables European fertility network procurement under retained EU MDR obligations for United Kingdom clinics. |
Research Methodology
Independent corroboration across embryology laboratory directors, biomedical engineers at fertility clinics, GPO contracts managers, and regulatory affairs specialists at device manufacturers underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, EMA medical device registration databases, hospital procurement records, and OECD testing framework revision documents. Bottom-up installation base enumeration triangulates against top-down expenditure estimates from reimbursement claims data.
Rate-of-change decomposition separates hardware replacement cycle compression from software licensing expansion across the analysis window. Segmentation dimensions modeled include product type, technology capability layer, end-user procurement authority, and application clinical utility. CAGRs derive from logistic diffusion curves fitted to adoption data across reimbursement environments. Forecast inputs incorporate health technology assessment timeline probabilities and preclinical toxicology laboratory expansion under revised OECD frameworks.
Inputs from regulatory filings and procurement databases were available through the study window; gaps in real-time clinic-level pricing data introduce uncertainty bands around premium-tier penetration assumptions. Forecasts reflect documented assumptions regarding reimbursement coding evolution and optical component supply stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Alpha Emitter Market
Medical Devices
Global Pacemakers Market
Medical Devices
Global Tumor Tracking Systems Market
Medical Devices
External Defibrillator Market
Medical Devices
Global Glaucoma Surgery Devices Market
Medical Devices
Percutaneous Nephrostomy Catheters Market
Medical Devices
Non-Invasive Ultrasound Stimulation Market
Medical Devices
Artificial Pancreas Market
Medical Devices
Global IVF Devices Market
Medical Devices
Nonvascular Interventional Radiology Devices Market
Medical Devices
Global Portable Oxygen Concentrators Market
Medical Devices
Autorefractor Keratometer Market
Medical Devices
Europe Clear Aligners Market
Medical Devices
Blood Collection Devices Market
Medical Devices
US Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Suction Catheters Market