
 Global NICU Catheter Market | 2026-2036
Global NICU Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Global NICU Catheter Market Foresight
Silicone is broadening its share against polyurethane in neonatal catheter construction as manufacturers prioritize biocompatibility and dwell-time performance. Cardinal Health Inc. leverages integrated distribution networks across North American hospital systems. Vygon SA anchors its position through specialized neonatal product lines developed in France. B. Braun Melsungen AG competes on manufacturing scale across European and Asian production facilities.
A NICU catheter is a sterile, flexible tube inserted into neonatal vasculature for medication delivery, fluid management, or hemodynamic monitoring, typically manufactured from polyurethane, silicone, or PVC with French sizes ranging from 1.0 to 5.0 Fr and radiopaque striping for placement verification. Peripheral vascular catheters dominate procedure volume due to lower complication profiles and broader nursing accessibility. Umbilical catheters command premium positioning in critical care applications where central venous access must be established within minutes of birth.
FDA 510(k) clearance pathways and EU MDR Class IIa certification requirements shape product development timelines and sterilization validation protocols for manufacturers seeking commercial access. ISO 80369 small-bore connector standards reduce misconnection risks in neonatal settings. WHO prequalification initiatives for essential medical devices expand addressable markets in low-resource health systems. Stakeholders must monitor evolving material toxicity thresholds and regional reimbursement shifts to align R&D portfolios with emerging clinical expectations.
Market Dynamics
Silicone material migration is compressing polyurethane's installed base as FDA and EU MDR toxicity thresholds force reformulation cycles across catheter portfolios. This material transition cascades through sterilization validation, supply contracts, and clinical training protocols.
Growth Catalysts
- EU MDR Class IIa certification mandates:Stricter biocompatibility documentation is accelerating silicone adoption among European manufacturers seeking market access.
- Neonatal intensive care unit expansion:Tertiary hospital construction in India and Brazil is creating dedicated catheter procurement channels.
- WHO prequalification pathways:Essential medical device listings are opening institutional purchasing in low-resource health systems.
Market Restraints
- Medical-grade silicone supply concentration:German and Japanese chemical suppliers control specialty elastomer feedstocks.
- Ethylene oxide sterilization capacity:EPA emission restrictions in the United States are constraining terminal sterilization throughput.
- Peripherally inserted central catheter substitution:PICC lines are capturing medication delivery cases from traditional umbilical catheters.
Strategic Opportunities
- ISO 80369-1 small-bore connector compliance:Misconnection prevention standards are creating upgrade cycles across installed catheter bases.
- Rural Indian district hospital networks:Central government health mission funding is penetrating underserved birth centers.
- Antimicrobial surface coatings:Silver-ion and chlorhexidine integration is differentiating premium catheter tiers.
Industry Challenges
- Neonatal vascular access specialist training:Critical care nursing certification programs face curriculum lag against device complexity.
- 510(k) predicate device pathways:FDA substantial equivalence determinations are slowing novel material submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global NICU Catheter Market |
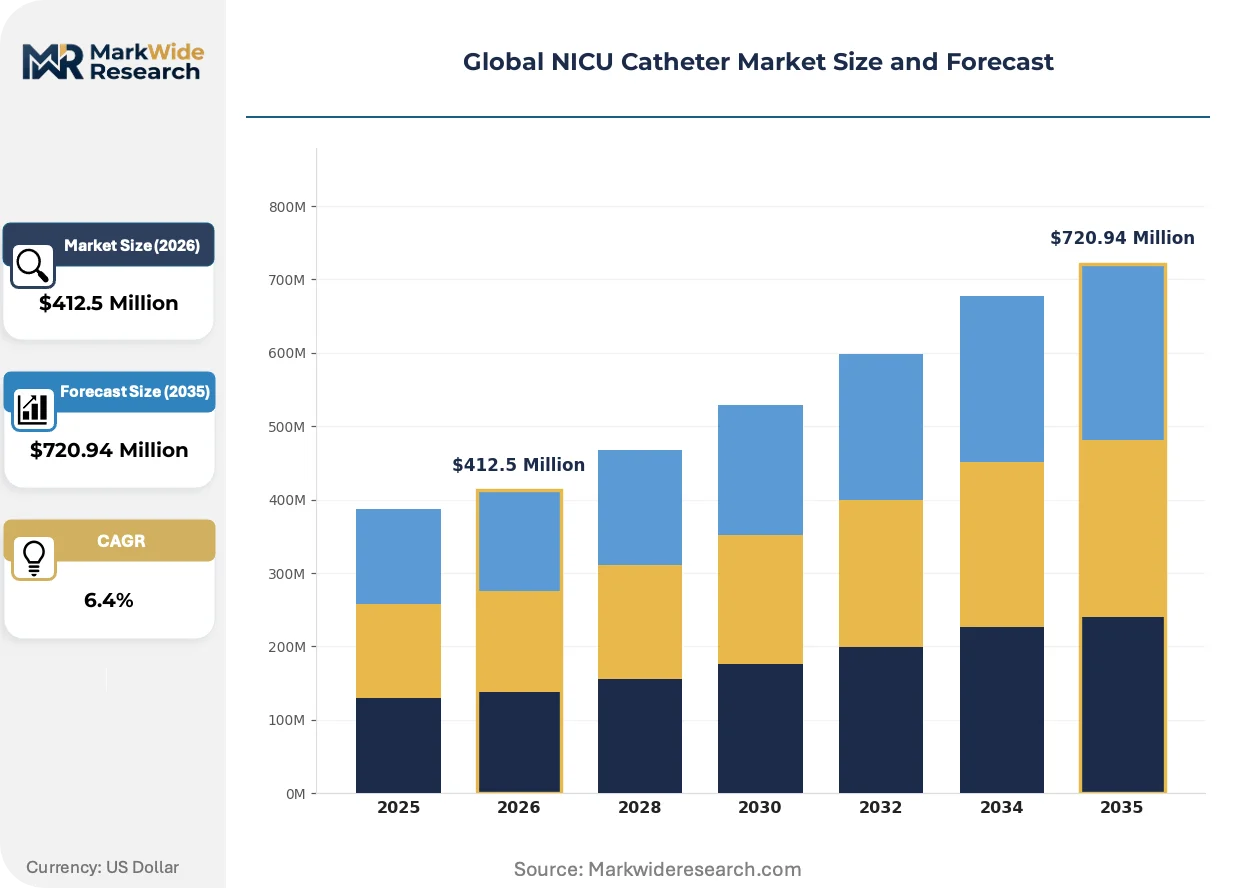
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Umbilical Catheters, Peripherally Inserted Central Catheters, Intraosseous Devices, Peripheral Vascular Catheters Application: Critical Care, Blood Transfusion, Fluid Management, Medication Delivery End User: Neonatal Intensive Care Units, Pediatric Hospitals, Maternity Wards, Research Laboratories Material: Polyurethane, PVC, Silicone, Polyethylene |
| Companies Covered | Cardinal Health Inc., ICU Medical Inc., Vygon SA, Utah Medical Products, Inc., B. Braun Melsungen AG, NeoMedical Inc., Footprint Medical Incorporated, Teleflex Inc., Smiths Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global NICU Catheter Market Shifts & Advancements
Catheter construction is fragmenting across material platforms as clinical evidence accumulates for dwell-time performance. Manufacturers are repositioning R&D portfolios around biocompatibility metrics rather than mechanical durability alone.
Antimicrobial-impregnated silicone is decentralizing infection control responsibility from central pharmacy protocols to device-level engineering. Level III NICUs in the United States are adopting these catheters at replacement-cycle velocity. The technology is decentralizing procurement authority toward infection prevention committees and away from general materials management.
EU MDR technical documentation requirements are extending product development timelines by mandating clinical performance data for legacy catheter lines. Manufacturers must retrospectively compile biocompatibility studies for predicates previously cleared under Medical Device Directive frameworks. French and German notified bodies are prioritizing neonatal device submissions, compressing review queues for these applications relative to general surgery portfolios.
Hospital value analysis committees are consolidating vendor relationships around single-source contracts with performance guarantees. Group purchasing organizations are displacing individual hospital negotiations in the United States, compressing price points for standard catheter configurations. This concentration is most visible in integrated delivery networks across Texas and Florida, where birth volume justifies direct manufacturer agreements.
Global NICU Catheter Market Segmentation
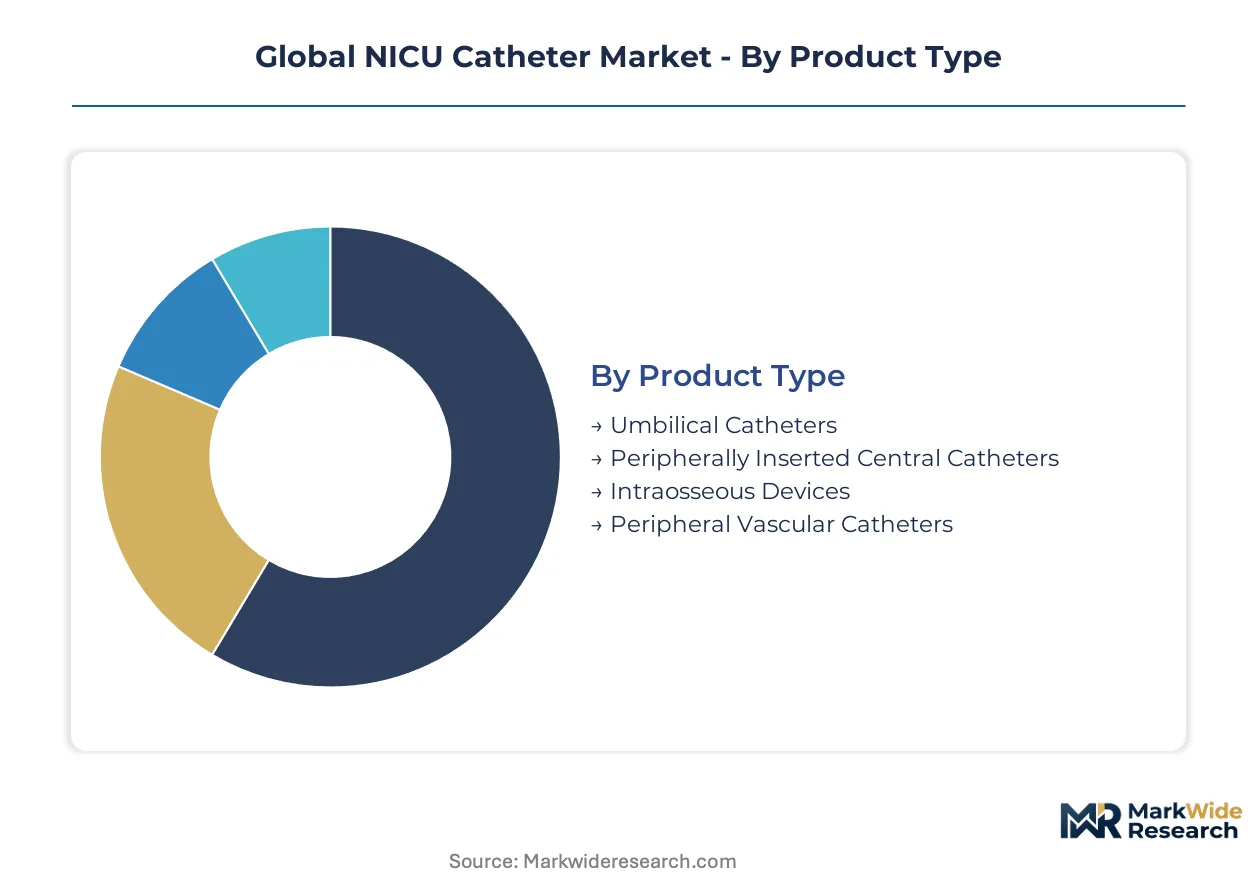
Neonatal catheter procurement fragments across clinical use cases, vascular access sites, and material platforms. Manufacturers configure production lines around these axes to align with hospital value analysis committees and regulatory filing pathways.
Product Type:
Capital intensity peaks in umbilical catheter manufacturing where multi-lumen construction and radiopaque integration demand precision extrusion equipment. Peripheral vascular catheters require less specialized tooling but scale through high-volume automation.
- Umbilical Catheters:Dual-lumen or single-lumen designs in 3.5-5.0 Fr sizes enable simultaneous arterial pressure monitoring and venous infusion. Demand clusters in Level III NICUs across the United States, Germany, and India where emergency central access protocols activate within minutes of delivery. FDA 510(k) predicates for these devices carry extensive clinical performance dossiers that extend development timelines.
- Peripherally Inserted Central Catheters:Silicone or polyurethane construction with integrated fixation wings supports extended dwell times for parenteral nutrition. Adoption is displacing traditional umbilical lines in stable neonates across tertiary centers in Brazil and South Africa. EU MDR Class IIa technical documentation requirements are compressing supplier margins on legacy PICC portfolios.
- Intraosseous Devices:Rigid needles with trocar tips for sternal or tibial access during vascular collapse scenarios.
- Peripheral Vascular Catheters:Short-term venous access in 24-24 gauge sizes for routine medication bolus and hydration.
Most installed capacity flows through Peripheral Vascular Catheters. Expansion is steepest in Peripherally Inserted Central Catheters.
Application:
Procedure reimbursement codes and nursing specialization requirements segment demand across clinical workflows. Critical care applications command premium pricing through bundled payment structures.
- Critical Care:Hemodynamic monitoring, emergency resuscitation, and vasoactive drug infusion in unstable neonates. Concentration in university-affiliated NICUs across Texas, Florida, and São Paulo drives specification for antimicrobial-coated configurations. Staffing ratios and specialist certification requirements limit addressable facility count.
- Medication Delivery:Antibiotic, analgesic, and parenteral nutrition administration through indwelling lines. District hospital networks in rural India and Indonesia are expanding access as WHO prequalification pathways reduce procurement friction. Central pharmacy compounding protocols influence catheter selection for compatibility with high-osmolarity solutions.
- Blood Transfusion:Exchange transfusion and packed red cell administration in hemolytic disease protocols.
- Fluid Management:Maintenance hydration and electrolyte correction in premature infants with renal immaturity.
Critical Care absorbs the highest unit value per procedure. Medication Delivery is climbing the fastest as ambulatory neonatal services expand.
End User:
Facility accreditation tiers and birth volume thresholds determine catheter specification complexity and contract negotiation leverage.
- Neonatal Intensive Care Units:Dedicated Level II-IV facilities with 24-hour neonatology coverage and surgical capability. Procurement in the United States flows through integrated delivery network contracts with performance guarantees for infection rates. Silicone material adoption is most advanced in these settings where extended dwell times justify premium pricing.
- Pediatric Hospitals:General pediatric wards with step-down capacity from intensive care. Expansion in Delhi, Mumbai, and Bangalore follows government health mission funding for dedicated children's facilities. Staff training programs lag device complexity, creating demand for simplified insertion protocols.
- Maternity Wards:Labor and delivery units with basic neonatal stabilization capacity.
- Research Laboratories:Preclinical and clinical trial sites for device safety and pharmacokinetic studies.
Neonatal Intensive Care Units command manufacturer attention through consolidated purchasing. Pediatric Hospitals are gaining share fastest as infrastructure investment outpaces specialist workforce growth.
Material:
Biocompatibility documentation burdens and sterilization validation costs stratify supplier competitive positions across polymer platforms.
- Silicone:Platinum-cured elastomer with superior thromboresistance and flexibility for extended indwelling periods. EU MDR toxicity threshold enforcement is accelerating formulation shifts among German and French manufacturers. FDA scrutiny of platinum catalyst residues is extending validation protocols for new product submissions.
- Polyurethane:Aromatic or aliphatic formulations with higher tensile strength for thin-wall construction. Cost-sensitive procurement in Southeast Asian and Latin American markets sustains volume despite biocompatibility limitations. Ethylene oxide sterilization capacity constraints in the United States are compressing throughput for polyurethane portfolios.
- PVC:Plasticized formulations for short-term peripheral access with lowest unit cost position.
- Polyethylene:High-density options for rigid intraosseous and selected vascular applications.
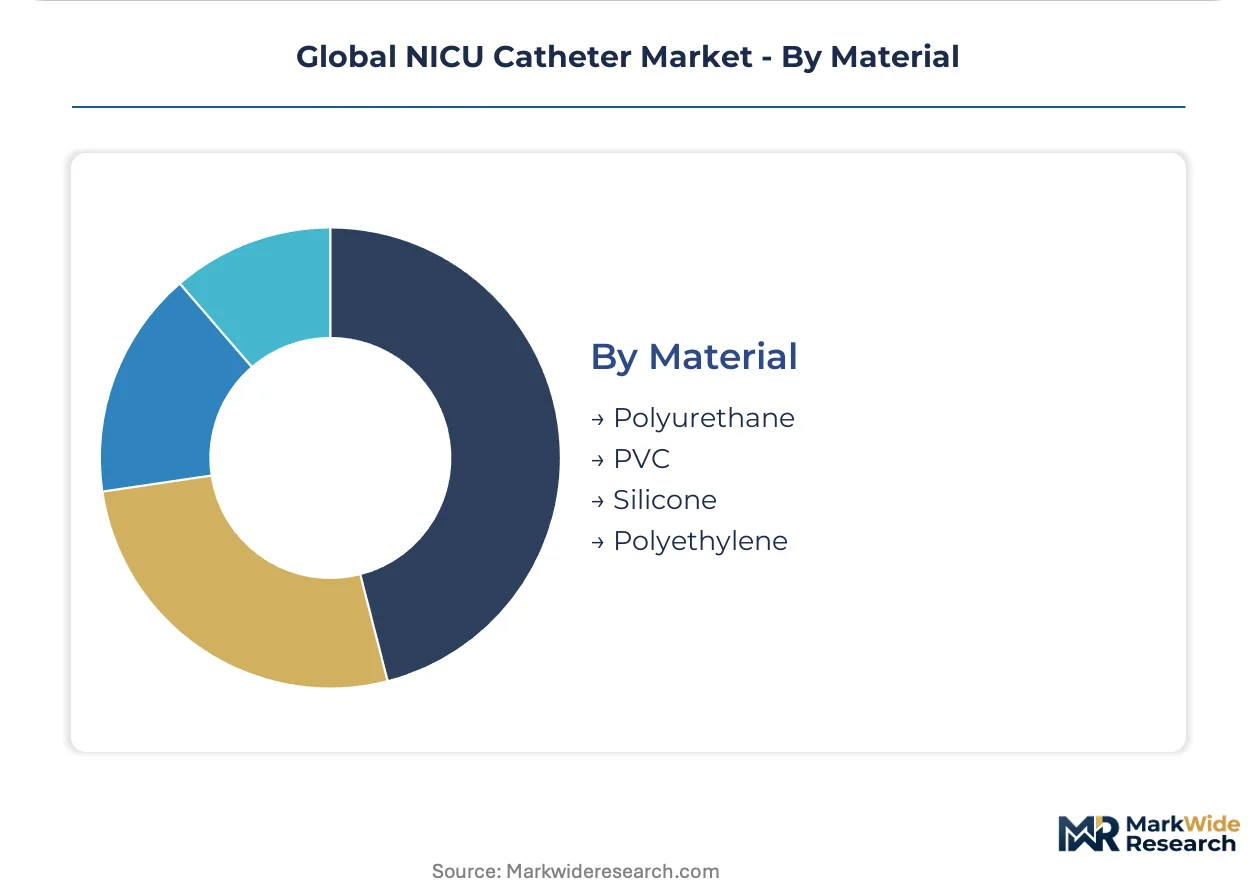
Polyurethane retains the largest installed base. Silicone is expanding most quickly as regulatory thresholds force material migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical suppliers anchor medical-grade silicone feedstock production for catheter manufacturers worldwide. FDA and EU MDR toxicity mandates are redrawing procurement maps across three continents. Birth volume concentration in Texas, São Paulo, and Maharashtra determines where catheter specifications tighten first.
United States
Level III NICU construction in Texas and Florida drives antimicrobial-coated catheter procurement through integrated delivery networks. EPA ethylene oxide emission restrictions constrain terminal sterilization capacity for polyurethane portfolios. Dallas-Fort Worth hospital systems negotiate direct manufacturer contracts leveraging birth volume thresholds above 15,000 annually.
Germany
Specialty elastomer production clusters around Leverkusen and Ludwigshafen supply platinum-cured silicone to European catheter fabricators. EU MDR Class IIa technical documentation requirements extend development timelines for legacy device lines. Bavarian notified bodies prioritize neonatal submissions, compressing review queues relative to general surgery portfolios.
India
Central government health mission funding penetrates rural district hospital networks in Maharashtra and Karnataka. CDSCO medical device rules align with ISO 80369 connector standards for misconnection prevention. Mumbai pediatric hospitals expand dedicated neonatal infrastructure faster than specialist nursing certification programs can supply trained staff.
Brazil
Tertiary hospital construction in São Paulo and Rio de Janeiro creates dedicated catheter procurement channels for critical care applications. ANVISA regulatory harmonization with FDA 510(k) pathways accelerates product registration for multinational suppliers. Southeast Brazilian birth centers adopt peripherally inserted central catheters for stable neonates, displacing traditional umbilical lines.
Japan
PMDA biocompatibility documentation requirements match EU MDR stringency for silicone material validation. Osaka-based chemical suppliers compete with German and Japanese feedstock producers for medical-grade elastomer supply. Tokyo metropolitan NICUs concentrate demand for extended-dwell catheters with thromboresistant surface properties.
Global NICU Catheter Market Competitive Landscape
Global majors compete with regional champions across distribution network depth and regulatory filing velocity. The vendor base stratifies into three tiers: integrated health systems suppliers with GPO contracts, specialized neonatal device developers with clinical education capabilities, and regional distributors with sterilization service attachments. Scale-driven players pursue backward integration into silicone compounding. Portfolio diversifiers acquire antimicrobial coating technologies through technology licensing arrangements.
Among diversified health systems suppliers, Cardinal Health Inc. and ICU Medical Inc. occupy positions shaped by North American hospital network consolidation. Vygon SA exemplifies the specialized neonatal archetype through French-developed product lines. B. Braun Melsungen AG anchors the European manufacturing scale tier with production facilities spanning multiple continents. These three patterns—integrated distribution, clinical specialization, and geographic scale—define competitive positioning across procurement committee evaluations.
| Leading Market Players |
|---|
| Cardinal Health Inc. |
| ICU Medical Inc. |
| Vygon SA |
| Utah Medical Products, Inc. |
| B. Braun Melsungen AG |
| NeoMedical Inc. |
| Footprint Medical Incorporated |
| Teleflex Inc. |
| Smiths Medical |
| Others |
Supply & Pricing Matrix
EU MDR Class IIa certification mandates for silicone biocompatibility documentation are forcing manufacturers to absorb reformulation costs and extended validation timelines, compressing margins on legacy polyurethane portfolios while enabling premium positioning for compliant product lines.
Pricing Analysis
Medical-grade silicone feedstock costs pass through directly to catheter unit economics as German and Japanese chemical suppliers control specialty elastomer production. Pricing stratifies across antimicrobial-coated premium tiers, standard silicone configurations, and economy polyurethane lines. Cost compression in standard tiers is intensifying because ethylene oxide sterilization capacity constraints in the United States limit throughput. Group purchasing organizations exhibit lowest price sensitivity; rural Indian district hospitals demonstrate highest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with German chemical suppliers in Leverkusen and Ludwigshafen for platinum-cured silicone feedstocks. Manufacturing draws from Germany, Japan, and the United States for specialty elastomers; catheter extrusion and assembly concentrates in Malaysia, Mexico, and Ireland. Tariff exposure on Chinese-sourced radiopaque additives presents structural risk. Distribution runs through integrated delivery networks in Texas and Florida, group purchasing organizations across North America, and government procurement channels in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone material migration toward extended-dwell applications creates margin-expansion potential as antimicrobial surface coatings command premium positioning against commodity polyurethane alternatives.
For Market Incumbents: Anchor market position through backward integration into silicone compounding capabilities in Germany or Japan, securing captive supply of medical-grade elastomers against feedstock concentration risk. Defend against peripherally inserted central catheter substitution by embedding clinical training protocols within hospital system contracts, creating switching costs that lock in umbilical catheter procurement for critical care applications. For New Entrants and Emerging Players: Direct-to-clinic digital procurement platforms offer the lowest-friction route into rural Indian district hospital networks, bypassing established distributor relationships that incumbent suppliers control. Target medication delivery applications in Brazilian and Indonesian tertiary centers where WHO prequalification pathways reduce regulatory friction and hospital value analysis committees lack consolidated vendor consolidation seen in North American integrated delivery networks. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized neonatal device developers possessing proprietary antimicrobial coating technologies and established clinical education infrastructures. The five-to-ten-year viability window favors acquisition targets with EU MDR technical documentation already compiled for silicone catheter portfolios. Monitor FDA 510(k) clearance velocity for novel material submissions as the inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Coating Integration | Silver-ion and chlorhexidine surface treatments differentiate premium tiers in Level III NICU procurement. |
| EU MDR Technical Documentation | Retrospective biocompatibility dossiers for legacy lines secure continued market access across European notified bodies. |
| Silicone Compounding Backward Integration | In-house production of medical-grade elastomers insulates against German and Japanese supplier concentration. |
| WHO Prequalification Pathway | Essential medical device listings unlock institutional purchasing in Maharashtra and Karnataka district hospitals. |
| ISO 80369-1 Connector Compliance | Small-bore misconnection prevention standards drive replacement cycles across installed catheter bases. |
Research Methodology
Direct dialogue with neonatology department heads, hospital procurement committee chairs, biomedical engineering directors, and group purchasing organization contract managers grounded the qualitative foundation. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body submission records, CMS Medicare reimbursement schedules, and WHO prequalification listings. Bottom-up catheter shipment estimates triangulated against top-down tertiary NICU construction forecasts across the analysis window.
Segment-level value outputs emerged from modeling across product type, material platform, application severity, and end-user facility tier dimensions. CAGRs were derived through regression analysis of historical adoption curves calibrated against regulatory filing velocity and sterilization capacity expansion. Forecast inputs incorporated silicone material migration rates and antimicrobial coating penetration assumptions across United States, German, and Indian hospital systems.
The model assumes a particular technology adoption path; alternative pathways for polyurethane reformulation under evolving FDA toxicity thresholds would alter the outlook. Forecasts reflect assumptions about EU MDR review queue prioritization and ethylene oxide sterilization capacity recovery trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
Neonatal and Prenatal Devices Market
Neonatal Care
North America Fetal and Neonatal Care Equipment Market
Neonatal Care
Preterm Birth Prevention and Management Market
Neonatal Care
India Fetal and Neonatal Care Equipment Market
Neonatal Care
North America Fetal and Neonatal Monitoring Market
Neonatal Care
Neonatal Critical Care Equipment Market
Neonatal Care
Global Neonatal Thermoregulation Market
Neonatal Care
Spain Neonatal and Prenatal Devices Market
Neonatal Care
Necrotising Enterocolitis (NEC) Market
Neonatal Care
Germany Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Phototherapy Market
Neonatal Care
Japan Neonatal and Prenatal Devices Market
Neonatal Care
Europe Fetal and Neonatal Care Equipment Market
Neonatal Care
Umbilical Market
Neonatal Care
Neonatal Ventilators Market
Neonatal Care
Neonatal and Infant Care Equipment Market