
 Cervical Spine System Market | 2026-2036
Cervical Spine System Market Size, Share, and Industry Trends Forecast 2026-2036
Cervical Spine System Market Outlook
Aftermarket service revenue is rewriting profitability expectations for device manufacturers. Medtronic leverages its expansive surgical navigation ecosystem to lock in recurring instrument service contracts. Stryker Corporation anchors its cervical portfolio through dedicated sales teams embedded in top orthopedic hospitals. Globus Medical differentiates via vertically integrated manufacturing of patient-specific interbody spacers.
A cervical spine system comprises implants, instrumentation, and biologics designed to stabilize, decompress, or restore motion across the seven cervical vertebrae, typically manufactured from titanium alloys or polyether ether ketone to achieve modulus-matched bone integration and radiolucent imaging compatibility. These systems treat degenerative disc disease, trauma fractures, and spondylotic myelopathy through anterior, posterior, or combined surgical approaches. Fusion devices dominate current revenue owing to established reimbursement codes and long-term clinical data, while dynamic stabilization systems represent the fastest-growing category as surgeons seek motion-preserving alternatives for younger patients. Hospitals remain the primary end-user channel, though ambulatory surgery centers are capturing share as anesthesia protocols and minimally invasive techniques compress length-of-stay requirements.
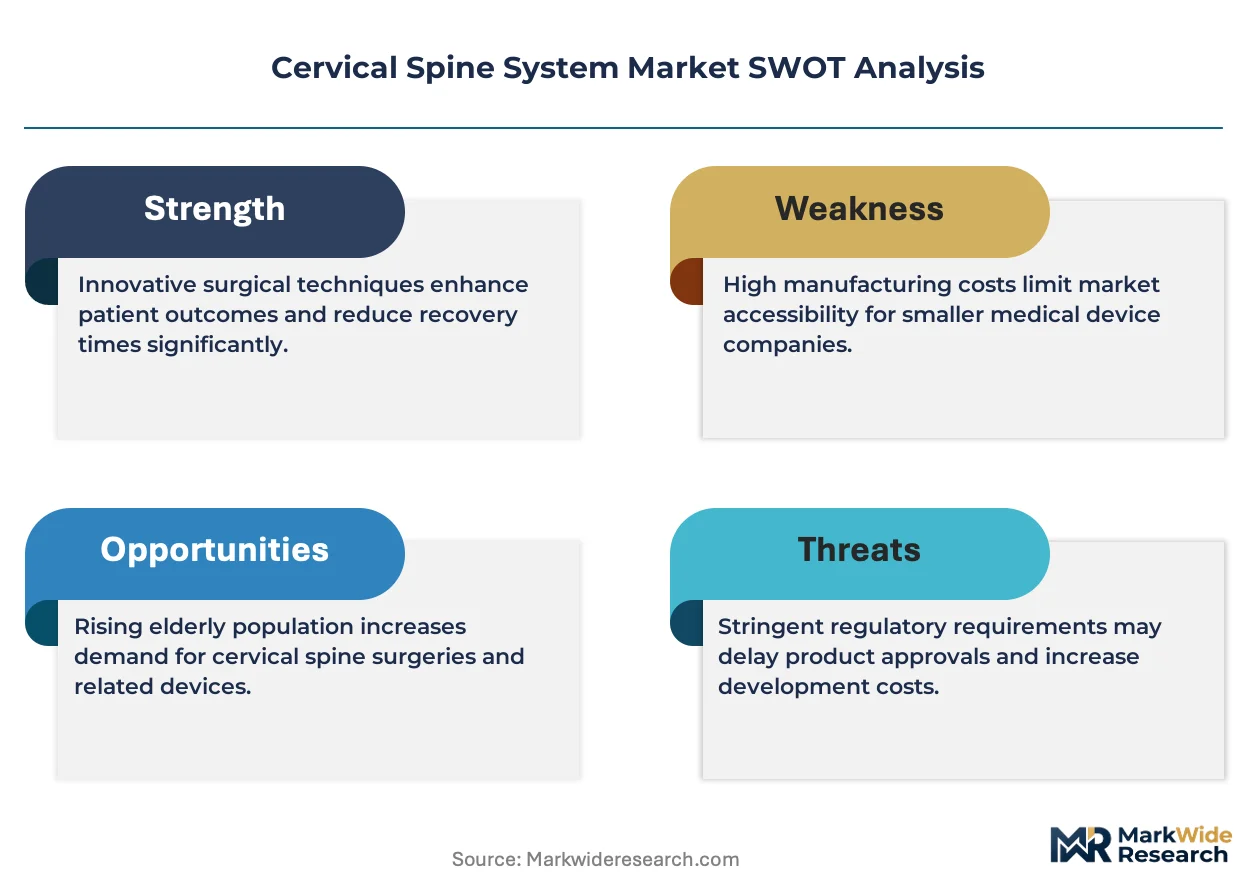
FDA 510(k) premarket notification and the European Union Medical Device Regulation govern implant biocompatibility, mechanical testing, and post-market surveillance, directly shaping R&D timelines and market access costs for manufacturers. The FDA's heightened scrutiny of metal-on-metal constructs and the EU MDR's expanded clinical evidence requirements for Class III devices are forcing portfolio rationalization among smaller competitors. Stakeholders must monitor evolving payer policies on outpatient cervical fusion and motion-preserving technologies to align capital deployment with shifting site-of-care economics.
Market Dynamics
The cervical spine system market pivots on site-of-care migration, where ambulatory surgery centers capture procedures once confined to inpatient settings through refined anesthesia protocols and same-day discharge pathways.
Growth Catalysts
- Commercial reimbursement expansion:Payers in the United States now cover motion-preserving cervical disc arthroplasty for active patients under 60, expanding addressable procedure volumes beyond fusion-limited cohorts.
- EU MDR clinical evidence pathways:The Medical Device Regulation's structured requirements for Class III implant biocompatibility documentation are accelerating adoption of titanium alloy platforms with established predicate histories.
- Minimally invasive corridor techniques:Surgeons deploy tubular retractor systems through muscle-sparing approaches, reducing blood loss and compressing recovery timelines for degenerative disc disease interventions.
Market Restraints
- Titanium alloy supply concentration:Aerospace and defense procurement absorbs capacity at primary mills, creating lead time volatility for implant-grade Ti-6Al-4V ELI bar stock.
- PEEK polymer crystallization defects:Subvisible inclusions in interbody spacer manufacturing trigger lot rejections and surgical kit fulfillment delays.
- FDA 510(k) substantial equivalence barriers:Novel surface-modified titanium constructs face predicate scarcity, extending premarket notification review cycles.
Strategic Opportunities
- Patient-specific interbody fabrication:Additive manufacturing of porous titanium cages from preoperative CT datasets matches endplate topography, reducing subsidence risk in osteoporotic vertebrae.
- Japan's super-aged society:METI reimbursement reforms for cervical spondylotic myelopathy surgery create demand for hybrid fixation systems combining rigid and dynamic elements.
- Direct-to-ASC distribution models:Manufacturers bypass hospital supply chain intermediaries, consigning instrument sets to high-volume ambulatory centers with usage-based replenishment.
Industry Challenges
- Biologics handling certification:Sales representatives require cold chain management credentials for demineralized bone matrix and cellular allograft products, constraining field force deployment.
- Legacy EMR integration:Surgical navigation platforms must interface with Cerner and Epic installations, demanding customized HL7 FHIR middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cervical Spine System Market |
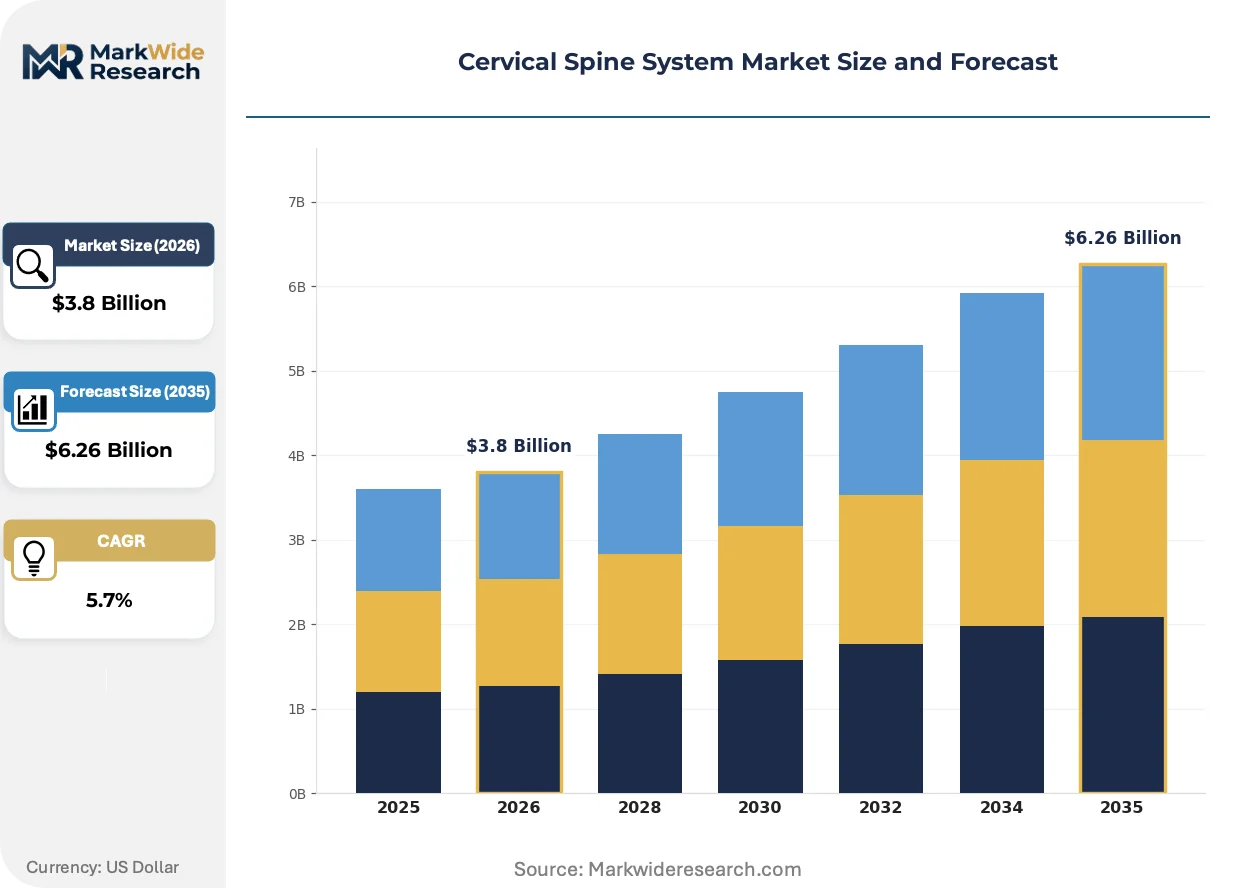
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Fusion Devices, Dynamic Stabilization Systems, Others End User: Hospitals, Ambulatory Surgery Centers, Orthopedic Clinics, Rehabilitation Centers Material: Polyether Ether Ketone, Titanium, Stainless Steel, Ceramic Therapy Area: Degenerative Disc Disease, Spinal Stenosis, Trauma, Tumors |
| Companies Covered | Medtronic, DePuy Synthes (Johnson & Johnson), Stryker Corporation, Zimmer Biomet, Globus Medical, NuVasive, B. Braun Melsungen AG, Orthofix International, Alphatec Spine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cervical Spine System Market Strategic Shifts
Biomaterial convergence and surgical workflow compression are redrawing competitive boundaries, with manufacturers racing to integrate navigation, robotics, and patient-matched implants into unified procedural ecosystems.
Surface-modified titanium is hybridizing osteoconductive coatings with subtractively manufactured lattice structures. Orthopedic surgeons at academic medical centers adopt these constructs for two-level anterior cervical corpectomy fusions. The technology is hybridizing hardware and biologics categories, forcing suppliers to recalibrate R&D resource allocation between mechanical and biological performance endpoints.
The EU MDR's expanded clinical evidence requirements for Class III cervical implants are compressing market access timelines for predicate-dependent 510(k) strategies. Manufacturers now commission prospective registry studies to satisfy notified body expectations for long-term survivorship data. Small and mid-cap competitors face portfolio rationalization pressure as quality management system upgrades consume capital reserves.
Hospital procurement committees are unbundling instrument service contracts from implant purchase agreements. Ambulatory surgery centers negotiate direct maintenance arrangements with third-party sterilization providers, bypassing original equipment manufacturer service networks. This pattern concentrates in the United States, where ASC joint ventures with private equity sponsors prioritize working capital efficiency over vendor-locked service dependencies.
Cervical Spine System Market Segmentation
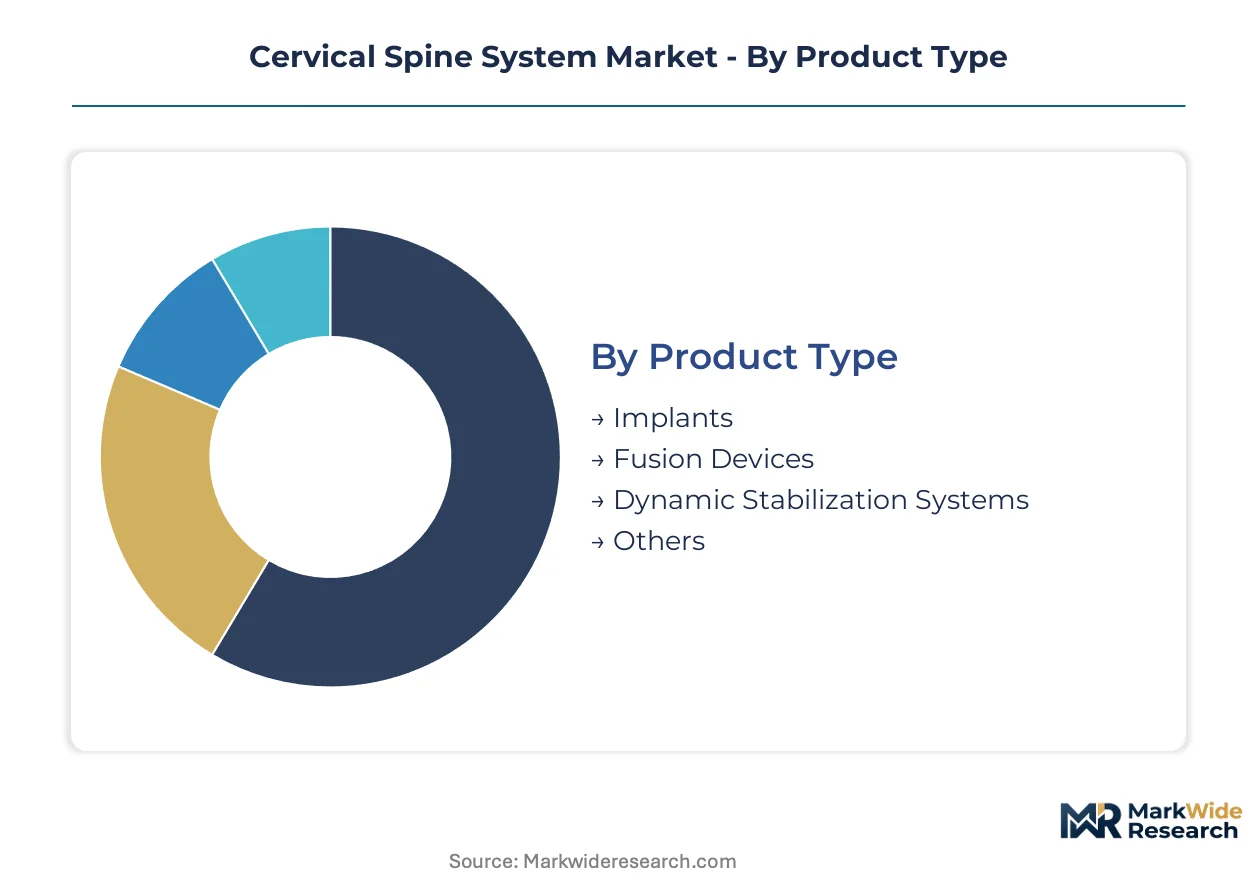
Cervical spine system manufacturers calibrate portfolio depth against reimbursement granularity and site-of-care economics. Segment-level resource allocation determines which product lines capture ASC volume versus academic hospital preference.
Product Type:
Application focus separates hardware categories by surgical goal — fusion versus motion preservation versus biologics augmentation.
- Implants:Anterior cervical plates, interbody spacers, and screw-rod constructs manufactured from titanium alloys or PEEK. Demand concentrates in United States academic medical centers where complex multi-level procedures require comprehensive instrumentation sets.
- Fusion Devices:Interbody cages and fixation systems promoting vertebral segment arthrodesis. United States hospitals drive volume through established CPT reimbursement codes for anterior cervical discectomy and fusion procedures.
- Dynamic Stabilization Systems:Motion-preserving alternatives including cervical disc arthroplasty and posterior dynamic stabilization.
- Others:Biologics carriers, bone graft delivery systems, and procedure-specific accessories.
Fusion Devices command the established base. The steepest expansion runs through Dynamic Stabilization Systems.
End User:
Customer type determines distribution infrastructure requirements and capital equipment deployment intensity.
- Hospitals:Inpatient surgical departments and dedicated spine centers with 24-hour recovery capabilities. United States health systems maintain preference for vendor-locked instrument service contracts covering navigation platform maintenance.
- Ambulatory Surgery Centers:Freestanding facilities performing same-day discharge cervical procedures. United States ASC joint ventures with private equity sponsors prioritize working capital efficiency over vendor-locked service dependencies.
- Orthopedic Clinics:Office-based settings managing preoperative evaluation and postoperative rehabilitation.
- Rehabilitation Centers:Post-acute facilities coordinating cervical collar fitting and physical therapy protocols.
Hospitals anchor implant revenue. ASCs are climbing the fastest as anesthesia protocols compress length-of-stay requirements.
Material:
Cost tier and performance specifications segment biomaterial selection for modulus matching and imaging compatibility.
- Polyether Ether Ketone:Radiolucent polymer with elastic modulus approximating cortical bone, enabling postoperative CT assessment without artifact. PEEK interbody spacers dominate United States anterior cervical procedures where subsidence risk in osteoporotic vertebrae drives material selection.
- Titanium:Ti-6Al-4V ELI alloy providing osseointegration through surface oxide layers and fatigue resistance for load-bearing applications. United States FDA 510(k) predicate abundance accelerates commercialization timelines for titanium platforms versus novel surface modifications.
- Stainless Steel:Lower-cost alternative for temporary fixation and emerging market price-sensitive segments.
- Ceramic:Alumina and zirconia compositions for bearing surfaces in motion-preserving constructs.
PEEK holds the volume base. Titanium is gaining share fastest through EU MDR predicate pathway advantages.
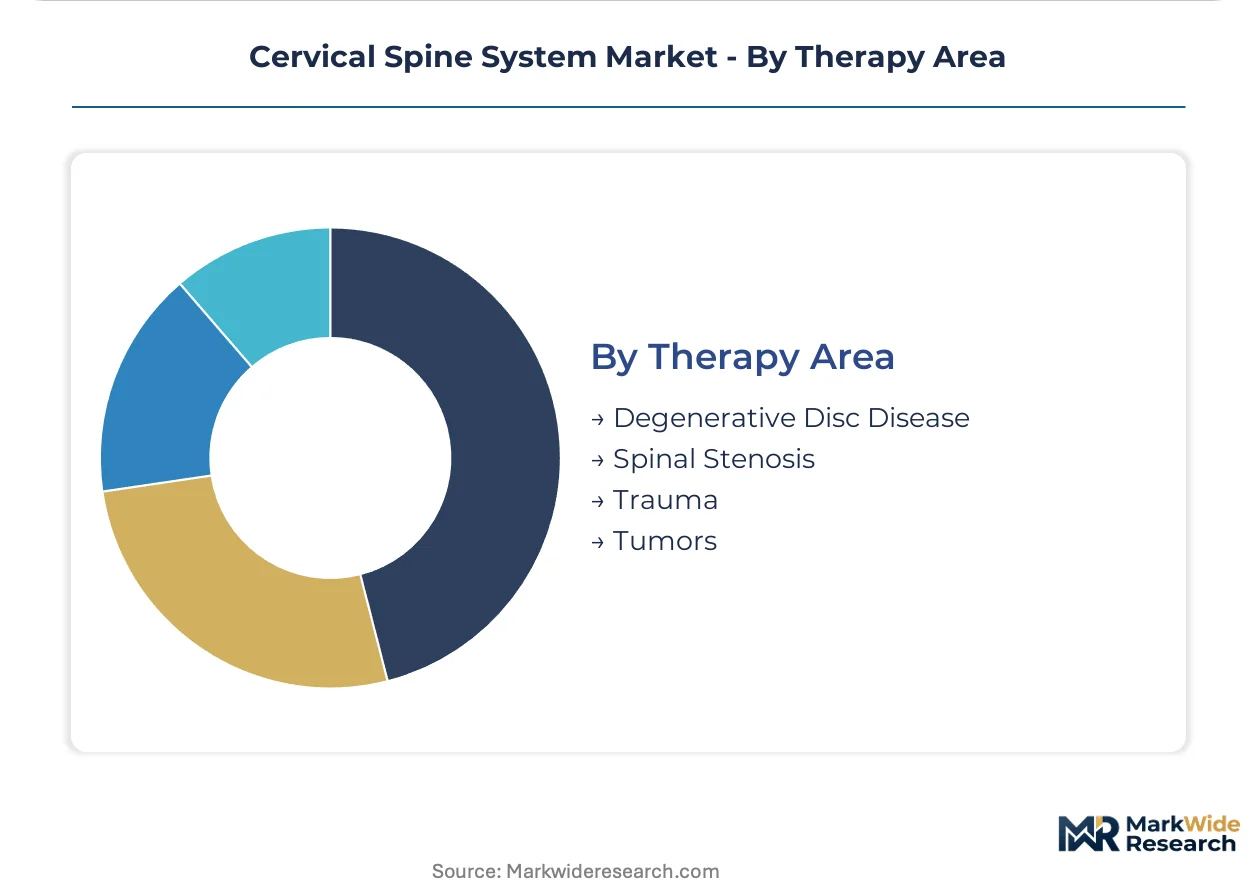
Therapy Area:
Volume concentration and procedure complexity vary by pathology indication.
- Degenerative Disc Disease:Cervical spondylosis and disc herniation requiring decompression and stabilization. United States commercial payers cover both fusion and disc arthroplasty for this indication, expanding addressable procedure volumes.
- Spinal Stenosis:Central and foraminal narrowing with myelopathy or radiculopathy. United States Medicare reimbursement for laminectomy and fusion sustains hospital-based procedure economics.
- Trauma:Fracture-dislocations and unstable injuries requiring emergent stabilization.
- Tumors:Metastatic and primary neoplasms demanding corpectomy and reconstruction.
Degenerative Disc Disease anchors procedure volume. Trauma represents the steepest expansion trajectory through emergency department protocol standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes cervical spine systems through ambulatory surgery centers at rates unmatched elsewhere, while Japan and Germany maintain hospital-centric pathways with distinct reimbursement architectures.
United States
Commercial payers now reimburse motion-preserving disc arthroplasty for patients under 60, expanding procedure volumes beyond fusion-limited cohorts. FDA 510(k) predicate abundance accelerates titanium platform commercialization timelines versus novel surface modifications. The Cleveland Clinic and Mayo Clinic anchor demand for patient-matched interbody spacers through embedded research collaborations.
Germany
Academic medical centers in Bavaria and Baden-Württemberg drive adoption of surface-modified titanium constructs for multi-level corpectomy fusions. EU MDR Class III clinical evidence requirements compress market access timelines for predicate-dependent strategies. The Berlin-Brandenburg cluster concentrates notified body interactions and quality management system upgrades for implant manufacturers.
Japan
METI reimbursement reforms for cervical spondylotic myelopathy surgery create demand for hybrid fixation systems combining rigid and dynamic elements. PMDA post-market surveillance requirements shape biocompatibility documentation for titanium alloys. The Kanto region around Tokyo anchors procedure volume through super-aged demographic concentration and university hospital networks.
China
Provincial centralized procurement drives price compression for standard interbody cages while premium motion-preserving devices remain hospital-negotiated. NMPA innovative device pathways accelerate review for 3D-printed porous titanium constructs. The Yangtze River Delta cluster concentrates domestic manufacturing capacity for Ti-6Al-4V ELI bar stock processing.
Switzerland
Swissmedic's alignment with EU MDR standards enables seamless market access for predicate-established titanium platforms. Private hospital groups in Zurich and Geneva prioritize vendor-locked instrument service contracts covering navigation platform maintenance. The Basel region anchors orthopedic research consortiums evaluating next-generation surface modifications.
Cervical Spine System Market Competitive Environment
Capability concentration sits with integrated manufacturers commanding surgical navigation ecosystems; scale advantage sits with diversified orthopedic conglomerates distributing across multiple spine segments. The vendor base stratifies into three tiers: navigation-locked full-line suppliers, spine-dedicated specialists, and regional fabricators serving price-sensitive markets. Dominant competitive moves include backward integration into additive manufacturing capacity and direct-to-ASC distribution models bypassing hospital supply chain intermediaries.
Within the navigation-locked tier, Medtronic and Stryker Corporation exemplify ecosystem strategies embedding recurring instrument service contracts. Globus Medical occupies a position among vertically integrated specialists controlling patient-specific interbody fabrication through captive additive manufacturing. These three anchors represent divergent archetypes: ecosystem platform, diversified orthopedic, and manufacturing-integrated specialist.
| Leading Market Players |
|---|
| Medtronic |
| DePuy Synthes (Johnson & Johnson) |
| Stryker Corporation |
| Zimmer Biomet |
| Globus Medical |
| NuVasive |
| B. Braun Melsungen AG |
| Orthofix International |
| Alphatec Spine |
| Others |
Value Chain & Pricing Dynamics
Ti-6Al-4V ELI bar stock concentration in the Yangtze River Delta and aerospace absorption at primary mills concentrates upstream pricing power, while downstream margin pools sit with manufacturers commanding captive additive manufacturing for patient-matched interbody spacers.
Pricing Analysis
Long-term offtake contracts dominate titanium alloy procurement, locking implant-grade feedstock pricing for 12-24 month windows against spot market volatility. Three-tier pricing structure across premium, standard, and economy levels separates surface-modified titanium constructs from conventional PEEK spacers and stainless steel alternatives. Pricing pressure stems from China's provincial centralized procurement compressing standard cage margins, while least price-sensitive buyers cluster in United States academic medical centers prioritizing predicate-established platforms for complex multi-level procedures.
Supply Chain Analysis
Contract manufacturing concentration rests with specialized orthopedic foundries in Switzerland, Germany, and the United States holding ISO 13485-certified titanium casting capacity. Raw material dependencies center on Ti-6Al-4V ELI bar stock, PEEK polymer resin, and demineralized bone matrix biologics. Single-source vulnerability runs through aerospace-dominated titanium mill capacity allocation. Distribution runs through hospital supply chain intermediaries in traditional channels, with direct-to-ASC consignment models bypassing these layers in high-volume United States ambulatory centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in ambulatory surgery center distribution, where site-of-care migration creates niches for manufacturers bypassing hospital procurement committees.
For Market Incumbents: Insulate service revenue streams by embedding surgical navigation platforms with multi-year instrument maintenance contracts. Consolidate backward integration into additive manufacturing capacity for patient-specific interbody fabrication. Lock in GPO purchasing agreements before ASC joint ventures with private equity sponsors finalize independent sterilization provider arrangements. For New Entrants and Emerging Players: Establish a beachhead in Japan's hybrid fixation systems segment, where METI reimbursement reforms for cervical spondylotic myelopathy surgery outpace incumbent portfolio adaptation. Target direct-to-ASC distribution in United States private equity-backed ambulatory ventures prioritizing working capital efficiency. Lead with EU MDR predicate pathway advantages for titanium platforms against novel surface modification competitors facing clinical evidence gaps. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists controlling captive additive manufacturing and patient-matched implant workflows. Long-term viability across the analysis window favors manufacturers with diversified biomaterial portfolios spanning PEEK, titanium, and emerging porous constructs. Monitor FDA 510(k) substantial equivalence clearance velocity as inflection indicator for predicate-dependent platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate pathway clearance accelerates titanium platform commercialization timelines versus novel surface modifications. |
| CE Marking Pathway | EU MDR Class III clinical evidence requirements compress market access for predicate-dependent strategies. |
| Hospital System Partnership | Embedded research collaborations at Cleveland Clinic and Mayo Clinic anchor demand for patient-matched interbody spacers. |
| Software Companion Development | Surgical navigation platforms must interface with Cerner and Epic installations through customized HL7 FHIR middleware. |
| Reimbursement Strategy | Commercial payer expansion for motion-preserving disc arthroplasty under 60 broadens addressable procedure volumes. |
Study Parameters
Cross-validation between surgeon interviews at academic medical centers and hospital purchasing committee records anchors the qualitative findings on procurement behavior. Primary fieldwork engaged spine surgeons, biomedical engineers, GPO contracts managers, and ASC operations directors across the United States, Germany, Japan, and China. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation converged on segment-level sizing.
Calibration against historical CAGR realization rates and macroeconomic sensitivity testing shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material, end-user channel, and therapy area, with regional regulatory clusters capturing FDA, EU MDR, PMDA, and NMPA pathway differences. CAGRs derived from procedure volume elasticity to reimbursement expansion, demographic aging curves, and site-of-care migration velocity. Industry-specific inputs incorporated ambulatory surgery center joint venture formation rates and titanium alloy mill capacity allocation patterns.
Stress conditions across aerospace titanium demand surges, EU MDR clinical evidence requirement stringency, and ASC reimbursement policy reversals were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on predicate device availability and payer coverage expansion timelines. Quarterly review of FDA 510(k) clearance velocity and ASC procedure migration rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Sternal Closure Systems Market
Medical Devices
Eye Massage Device Market
Medical Devices
Global Extremities Market
Medical Devices
External Pacemakers Market
Medical Devices
US Intrauterine Devices Market
Medical Devices
Surgical AR Systems Market
Medical Devices
Zygomatic and Pterygoid Implants Market
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
Skin Rejuvenation Devices Market
Medical Devices
Speech Generating Devices Market
Medical Devices
Global Vaginal Sling Market
Medical Devices
Global Female Stress Urinary Incontinence Treatment Devices Market
Medical Devices
Point-Of-Care Ultrasound (Pocus) Device Market
Medical Devices
Smart Wheelchairs Market
Medical Devices
Postpartum Hemorrhage (PPH) Devices Market
Medical Devices
South Africa Ultrasound Devices Market