
 Global Surgical Booms Market | 2026-2036
Global Surgical Booms Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Booms Market Foresight
Integrated power and data management is reconfiguring how surgical booms deliver utilities to the operative field, replacing standalone gas and electrical lines with consolidated service heads that reduce ceiling clutter and improve flexibility. Stryker leverages its broad hospital capital equipment portfolio to bundle boom sales with surgical tables and lighting systems. SKYTRON anchors its position through strong relationships with ambulatory surgical centers seeking cost-efficient ceiling-mounted configurations. Drägerwerk differentiates by specializing in anesthesia-integrated boom designs that merge gas delivery with patient monitoring infrastructure.
Surgical booms are ceiling-suspended or mobile structural arms engineered to route medical gases, electrical power, data lines, and video signals into sterile operative zones, typically supporting loads of 200–600 pounds with 360-degree rotation capability to maintain unobstructed access for surgical teams. Ceiling-mounted booms dominate installed base volumes in mature hospital systems where permanent infrastructure upgrades justify capital-intensive configurations, while mobile surgical booms capture faster expansion in emergency departments and temporary surgical facilities requiring rapid redeployment. Electric and automated technology segments command premium positioning as hospitals prioritize motorized positioning and collision-avoidance systems that reduce manual adjustment burden on clinical staff.
The FDA enforces electrical safety and electromagnetic compatibility standards under 21 CFR requirements for medical devices, compelling manufacturers to invest in certified component sourcing and documentation trails that lengthen product development cycles but raise barriers to low-cost import competition. The EU Medical Device Regulation mandates clinical evaluation and post-market surveillance for surgical booms sold in European member states, shifting compliance costs toward ongoing quality management rather than one-time registration. Stakeholders must monitor how IEC 60601-1 third edition amendments reshape grounding and leakage current specifications, as these technical changes will determine which existing product lines require redesign versus grandfathered market access.
Market Dynamics
Hospital infrastructure modernization is compressing replacement cycles for ceiling-mounted surgical booms as health systems consolidate capital planning around hybrid operating room investments. Electrification of positioning systems and collision-avoidance integration are raising technical specifications while lengthening vendor qualification timelines.
Growth Catalysts
- Hybrid OR Investment Wave:Hospital systems in the United States, Germany, and China are allocating capital budgets to integrated surgical suites that bundle imaging, lighting, and boom infrastructure into single procurement packages.
- IEC 60601-1 Third Edition:Updated electrical safety and electromagnetic compatibility standards are filtering out uncertified manufacturers and concentrating demand among established suppliers with documented compliance trails.
- Anesthesia-Integrated Designs:Boom configurations that merge gas delivery with patient monitoring infrastructure are capturing preference in tertiary care centers seeking consolidated service heads.
Market Restraints
- Stainless Steel Input Volatility:Boom chassis and arm fabrication depends on medical-grade stainless steel pricing, which fluctuates with nickel supply disruptions from Indonesian and Russian export channels.
- Certified Component Concentration:Electromagnetic interference shielding and motorized actuator supplies concentrate among German and Japanese specialty manufacturers, creating single-source vulnerabilities.
- EU MDR Compliance Friction:The Medical Device Regulation's clinical evaluation and post-market surveillance mandates impose recurring quality management costs that disproportionately burden mid-tier suppliers.
Strategic Opportunities
- Indian Hospital Modernization:CDSCO regulatory harmonization with international standards is opening procurement pathways for ceiling-mounted configurations in metro hospital expansions.
- Ambulatory Surgical Center Channel:Cost-efficient ceiling-mounted boom configurations are penetrating freestanding ASCs as outpatient procedure volumes migrate from inpatient settings.
- 5G-Enabled Remote Servicing:Integration of cellular telemetry into motorized boom systems is enabling predictive maintenance contracts that unbundle hardware sales from recurring service revenue.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Health systems face shortages of technicians qualified to troubleshoot integrated power, data, and gas delivery systems in ceiling-mounted configurations.
- Legacy OR Retrofit Complexity:Installing motorized booms in aging hospital infrastructure requires structural ceiling reinforcement and electrical capacity upgrades that extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Booms Market |
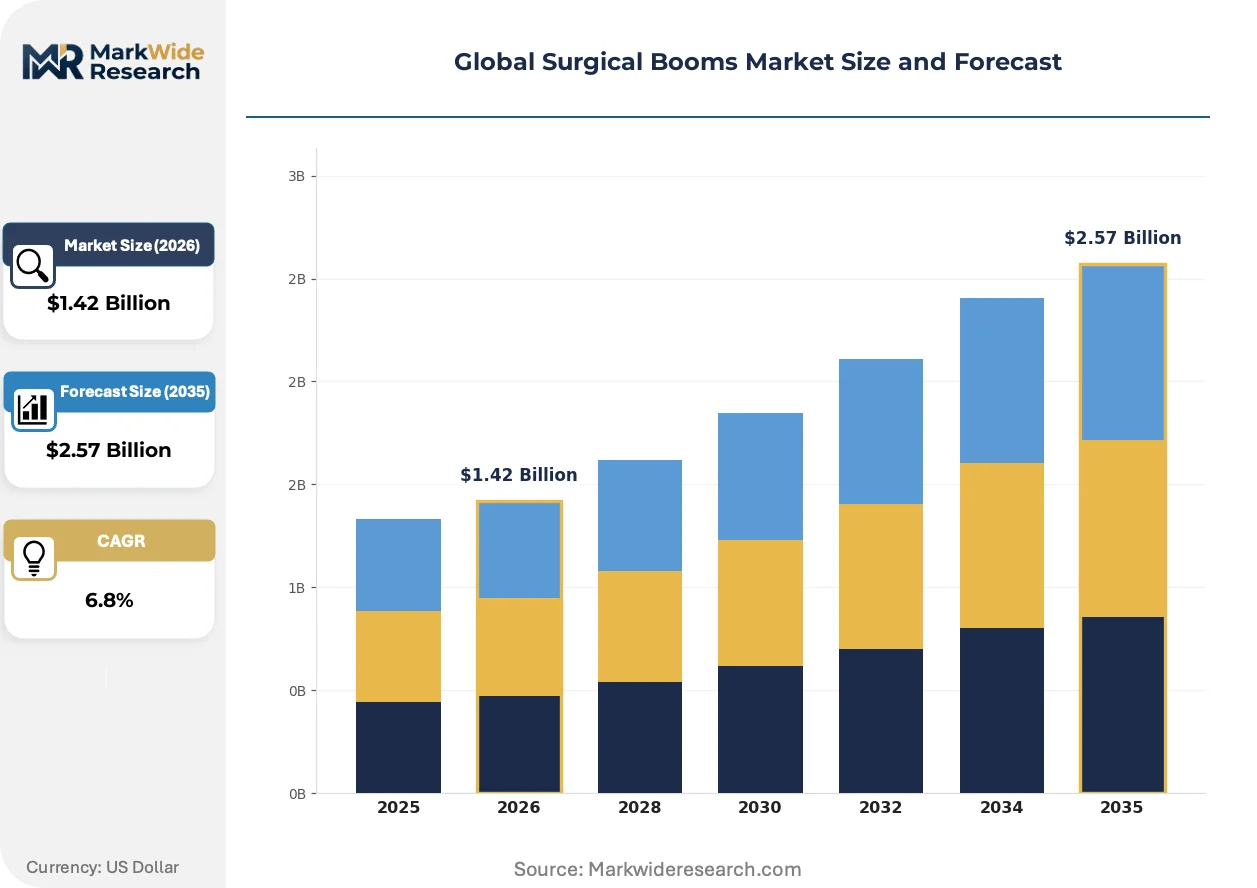
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulated Surgical Boom, Ceiling Mounted Boom, Mobile Surgical Boom, Modular Surgical Boom, Fixed Surgical Boom Technology: Hydraulic, Electric, Pneumatic, Manual, Automated Application: Surgical Procedures, Intensive Care, Emergency Rooms, Diagnostic Imaging, Sterile Processing Units End User: Hospitals, Ambulatory Surgical Centers, Specialized Clinics, Trauma Centers, Diagnostic Labs |
| Companies Covered | Hill-Rom Services, SKYTRON, Stryker, Drägerwerk, Ondal Medical Systems, STERIS, Amico Group of Companies, Trumpf Medical, Getinge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Booms Market Shifts & Advancements
Digital service integration is reconfiguring how surgical boom manufacturers capture value beyond hardware sales. Virtualization of system diagnostics, remote firmware management, and predictive maintenance algorithms are compressing the traditional break-fix service model.
Digital twin software is virtualizing pre-installation planning for ceiling-mounted boom configurations. Hospital construction teams in Germany and the United States are adopting 3D simulation platforms to map service head placement, rotation clearances, and collision zones before structural installation begins. This virtualization is reducing change-order costs and accelerating commissioning timelines for hybrid operating room projects.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic adverse event reporting and clinical follow-up for surgical booms sold in European member states. Manufacturers must maintain quality management systems that document design changes and field performance across product lifecycles. Class IIa and IIb device categories face heightened scrutiny of electromagnetic compatibility test data, pushing suppliers toward in-house certification capabilities rather than third-party laboratory dependencies.
After-sales service unbundling is disrupting traditional capital equipment purchasing in United States health systems. Hospital procurement teams are separating hardware acquisition from installation, training, and multi-year maintenance contracts, pressuring boom manufacturers to price components transparently. This shift is most visible in integrated delivery networks that centralize sourcing decisions across multiple surgical facilities and demand standardized service level agreements.
Global Surgical Booms Market Segmentation
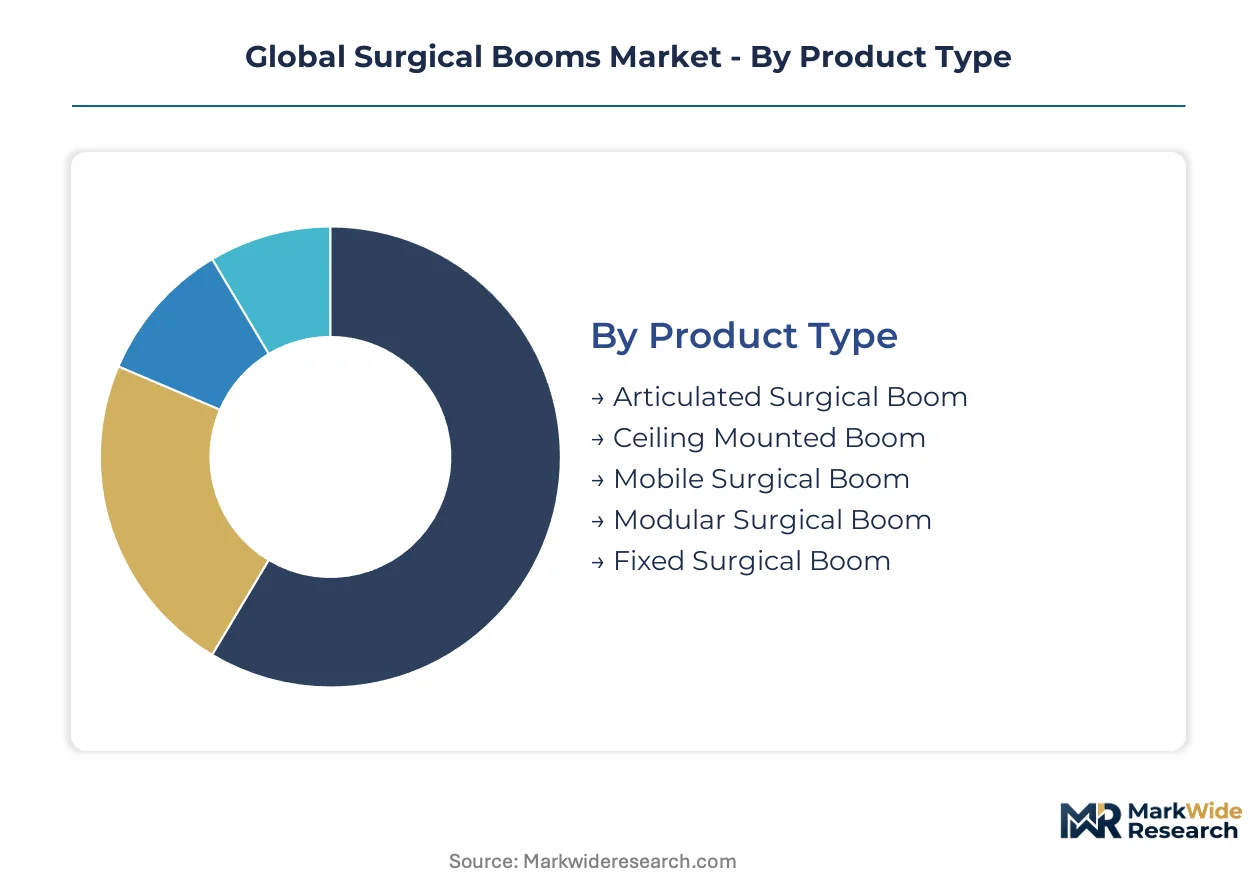
Surgical boom procurement patterns diverge sharply across facility types and technical specifications. Understanding these segment boundaries reveals where capital budgets concentrate and which configurations face replacement pressure versus greenfield demand.
Product Type:
Cost tier determines infrastructure commitment levels, with permanent ceiling installations commanding the highest capital allocation while mobile units serve contingency and overflow capacity.
- Ceiling Mounted Boom:Permanent structural installations support 360-degree rotation with 400–600 pound load ratings. United States health systems undergoing hybrid OR modernization drive replacement cycles for these configurations.
- Mobile Surgical Boom:Self-supporting units with integrated power and gas storage enable rapid deployment across emergency departments and temporary surgical facilities. Germany's hospital infrastructure investments include these units for surge capacity planning.
- Articulated Surgical Boom:Multi-jointed arm designs optimize positioning flexibility in constrained surgical suites.
- Modular Surgical Boom:Reconfigurable service heads allow gas, electrical, and data line customization per procedure type.
- Fixed Surgical Boom:Stationary configurations persist in legacy installations where structural retrofit costs prohibit motorized upgrades.
Ceiling Mounted Boom commands the established base. The steepest expansion runs through Mobile Surgical Boom.
Technology:
Application requirements dictate motorization levels, with automated positioning systems capturing preference in high-throughput surgical environments while manual systems retain cost-sensitive segments.
- Electric:Motorized actuators enable programmable positioning with collision-avoidance sensors. China's hospital modernization programs specify electric systems for new tertiary care centers.
- Automated:Integrated control systems synchronize boom movement with surgical table and lighting adjustments. United States integrated delivery networks prioritize these configurations for standardized OR protocols.
- Hydraulic:Fluid-powered positioning persists in heavy-load applications requiring smooth vertical translation.
- Pneumatic:Compressed gas systems dominate budget-conscious installations where electrical infrastructure upgrades are deferred.
- Manual:Counterbalanced mechanical positioning retains share in ambulatory settings with low procedure volumes.
Electric technology anchors current installed value. Automated systems are climbing the fastest as procurement specifications tighten.
Application:
Volume intensity varies by clinical setting, with surgical procedures generating the highest per-unit utilization rates while diagnostic imaging demands specialized cable management for data throughput.
- Surgical Procedures:Primary operative applications require integrated gas, suction, and electrosurgical routing with sterile field maintenance. United States hospital systems consolidate procurement around these high-utilization configurations.
- Intensive Care:Patient monitoring and ventilator support drive demand for consolidated service heads in critical care bays. Germany's ICU expansion programs specify ceiling-mounted booms for space optimization.
- Emergency Rooms:Rapid patient turnover and trauma protocols favor mobile and electric configurations for flexibility.
- Diagnostic Imaging:High-bandwidth data lines and electromagnetic shielding requirements distinguish imaging-integrated boom designs.
- Sterile Processing Units:Decontamination workflow integration creates specialized demand for corrosion-resistant finishes and sealed cable pathways.
Surgical Procedures retains the dominant revenue share. Intensive Care is expanding most quickly as critical care infrastructure scales.
End User:
Customer type shapes procurement authority and contract structure, with hospital central purchasing favoring bundled capital packages while ambulatory centers prioritize standalone cost efficiency.
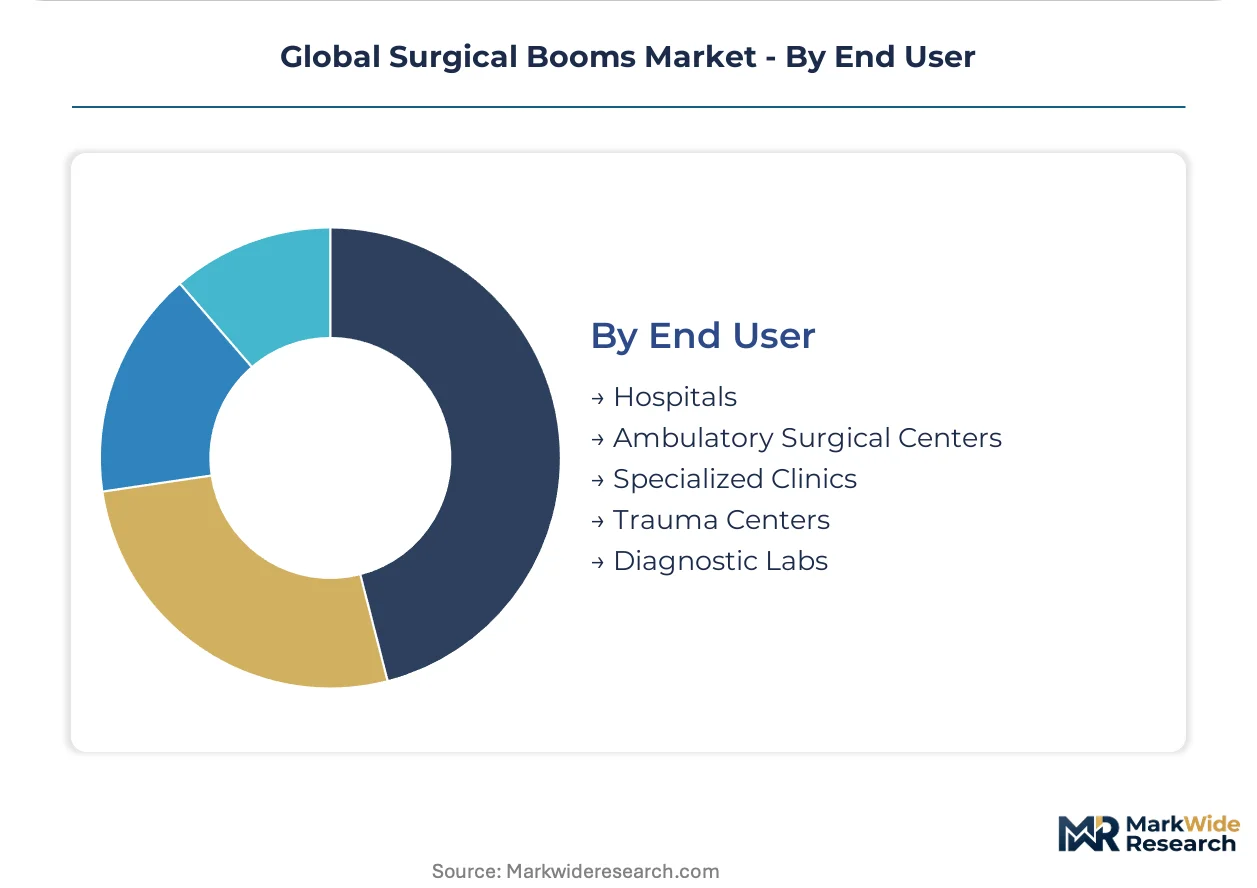
- Hospitals:Centralized capital planning enables integrated procurement of booms with tables, lights, and imaging systems. China's tier-one hospital construction wave concentrates demand for ceiling-mounted configurations.
- Ambulatory Surgical Centers:Freestanding outpatient facilities prioritize cost-efficient ceiling-mounted systems with streamlined service heads. United States ASC volume migration from inpatient settings accelerates this segment.
- Specialized Clinics:Procedure-focused facilities require application-specific boom configurations for ophthalmology, orthopedics, or endoscopy.
- Trauma Centers:Level I and II designation requirements drive specifications for rapid-redeployment mobile systems.
- Diagnostic Labs:Interventional radiology and catheterization labs demand imaging-compatible boom designs with enhanced electromagnetic shielding.
Hospitals dominate absolute unit demand. Ambulatory Surgical Centers are gaining share fastest as site-of-care shifts accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German surgical boom manufacturers export ceiling-mounted configurations to United States health systems modernizing hybrid operating rooms, while Chinese producers supply cost-efficient mobile units to Southeast Asian hospital expansion programs.
United States
Integrated delivery networks consolidate procurement around bundled boom-table-lighting packages for hybrid OR investments. FDA enforcement of 21 CFR electrical safety standards elevates documentation requirements for imported systems. Texas Medical Center in Houston anchors demand for anesthesia-integrated configurations serving high-volume tertiary surgical suites.
Germany
Hospital infrastructure programs specify motorized electric booms with collision-avoidance for new ICU and surgical wing construction. EU Medical Device Regulation mandates clinical evaluation trails that extend vendor qualification timelines. Baden-Württemberg's medical technology corridor clusters precision actuator suppliers serving domestic boom fabricators.
China
Tier-one hospital construction in provincial capitals drives ceiling-mounted boom installation for standardized surgical protocols. NMPA harmonization with IEC 60601-1 third edition filters uncertified manufacturers from public procurement. Yangtze River Delta medical device manufacturing bases scale production of cost-optimized electric positioning systems.
India
Metro hospital expansions in Mumbai and Delhi create procurement pathways for ceiling-mounted configurations as CDSCO regulatory alignment accelerates. Central government health infrastructure schemes fund surgical suite modernization in government medical colleges. Karnataka's medical device parks attract component suppliers for localized boom assembly.
Japan
Aging hospital infrastructure replacement cycles favor automated boom systems with integrated control synchronization. METI medical device quality standards enforce electromagnetic compatibility testing that concentrates demand among established suppliers. Osaka-Kobe industrial corridor maintains specialized manufacturing for heavy-load hydraulic positioning components.
Global Surgical Booms Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers. Hospital capital equipment bundling and ambulatory surgical center standalone purchasing create divergent competitive arenas. Three archetypes dominate: diversified medical technology conglomerates with cross-product bundling power; dedicated surgical infrastructure specialists with installation expertise; and regional cost-optimized fabricators serving price-sensitive procurement channels. M&A activity concentrates among mid-tier specialists seeking geographic coverage, while technology licensing agreements proliferate for motorized positioning and collision-avoidance systems.
Among diversified medical technology conglomerates, Stryker and Drägerwerk occupy positions that exemplify bundling-oriented competitive strategy. SKYTRON sits within the specialist tier alongside dedicated surgical infrastructure providers. The "Others" category aggregates regional fabricators and emerging entrants not yet captured in established competitive rankings.
| Leading Market Players |
|---|
| Hill-Rom Services |
| SKYTRON |
| Stryker |
| Drägerwerk |
| Ondal Medical Systems |
| STERIS |
| Amico Group of Companies |
| Trumpf Medical |
| Getinge |
| Others |
Supply & Pricing Matrix
Yangtze River Delta manufacturing clusters anchor global capacity for motorized positioning systems, translating production scale into tiered pricing power across export markets. Medical-grade stainless steel volatility from Indonesian nickel supply disruptions feeds directly into chassis cost structures, compressing margins for fabricators lacking backward integration into component supply.
Pricing Analysis
Current-generation electric and automated surgical booms command substantial premiums over prior-generation hydraulic and pneumatic systems, while next-generation 5G-enabled predictive maintenance configurations remain in pilot pricing phases. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated systems with full IEC 60601-1 third edition documentation from CE-marked mid-tier offerings and uncertified economy units. Cost compression in the economy tier is intensifying because Chinese manufacturers are scaling electric actuator production for domestic hospital procurement. Ambulatory surgical centers exhibit the highest price sensitivity, prioritizing standalone hardware acquisition over bundled service contracts, whereas United States integrated delivery networks accept premium positioning for standardized multi-facility protocols.
Supply Chain Analysis
Export-control regimes limiting flows of precision electromagnetic interference shielding technologies constrain component access for non-aligned manufacturers, reshaping competitive access to critical inputs. German and Japanese specialty suppliers concentrate production of motorized actuators and certified shielding materials, drawing from medical-grade stainless steel mills in China and Indonesia. Supply chain risk centers on single-source vulnerability for collision-avoidance sensor modules sourced from Osaka-Kobe industrial corridor fabricators. Distribution runs through hospital capital equipment bundling in mature markets and direct procurement by government medical colleges in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as hybrid operating room investments by United States, German, and Chinese health systems accelerate replacement cycles for ceiling-mounted infrastructure.
For Market Incumbents: Entrench bundling relationships with integrated delivery networks by expanding anesthesia-integrated boom configurations that merge gas delivery with patient monitoring infrastructure. Deepen backward integration into electromagnetic shielding component supply to offset single-source vulnerabilities from Japanese specialty manufacturers. Prioritize in-house IEC 60601-1 third edition certification capabilities to filter emerging competitors lacking documented compliance trails. For New Entrants and Emerging Players: Establish a beachhead in India's metro hospital expansion programs by aligning product documentation with CDSCO regulatory harmonization pathways for ceiling-mounted configurations. Target ambulatory surgical centers in the United States with cost-efficient electric positioning systems that unbundle hardware from service contracts. Pursue white-label manufacturing partnerships with Yangtze River Delta fabricators to access scaled actuator production without captive capacity investment. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because mid-tier specialists face disproportionate EU MDR compliance friction that elevates ongoing quality management costs beyond standalone revenue bases. Acquisition targets should display installed base density in specific geographic clusters enabling service revenue unbundling. Watch for inflection signals in 5G-enabled remote servicing contract penetration rates as predictive maintenance algorithms compress traditional break-fix service models.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Expedited clearance for electric positioning systems with collision-avoidance integration reduces vendor qualification timelines for United States health systems. |
| CE Marking Under EU MDR | Clinical evaluation documentation for Class IIa devices elevates barriers for uncertified manufacturers in German hospital procurement. |
| Hospital System Partnership | Bundled boom-table-lighting packages with Texas Medical Center-type integrated delivery networks lock in multi-year replacement cycles. |
| Software Companion Development | Digital twin platforms for pre-installation planning reduce commissioning costs and accelerate hybrid OR project timelines in German construction markets. |
| Reimbursement Strategy | Alignment with CMS outpatient procedure migration patterns positions ASC-focused configurations for volume capture from inpatient settings. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and surgical suite planners. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records from United States integrated delivery networks, and customs trade data for medical-grade stainless steel imports. Bottom-up installation volume estimates by facility type and technology tier were triangulated against top-down capital expenditure flows from health system annual reports.
Calibration anchored volume and value outputs across the projection horizon to documented hybrid OR construction permits, NMPA registration data for Chinese tier-one hospitals, and CDSCO import authorization trends. Segmentation dimensions modeled included product type permanence, motorization technology tier, clinical application intensity, and end-user procurement authority structure. CAGRs were derived from elasticity-adjusted replacement cycle compression and greenfield installation rates specific to anesthesia-integrated and imaging-compatible boom configurations.
Stress conditions across nickel price volatility, IEC 60601-1 third edition enforcement intensity, and EU MDR post-market surveillance cost escalation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions of continued regulatory harmonization in India and sustained hospital infrastructure modernization in China. Material shifts in electromagnetic component export controls or structural ceiling reinforcement cost inflation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Pain Management and Surgical Devices Market
Surgical Instruments
Global Surgical Instruments Market
Surgical Instruments
Uro Gynaecological Surgical Devices Market
Surgical Instruments
Europe General Surgical Devices Market
Surgical Instruments
Disposable Surgical Devices Market
Surgical Instruments
Surgical Drains Market
Surgical Instruments
Needle Holders Market
Surgical Instruments
Laparoscopic Needle Holder Robotic Devices Market
Surgical Instruments
Surgical Sutures Market
Surgical Instruments
Ultrasound Needle Guides Market
Surgical Instruments
Global Surgical Stapler Market
Surgical Instruments
Tonsil and Adenoid Removal Products Market
Surgical Instruments
Americas Suture Needles Market
Surgical Instruments
Ischemic Stroke Surgery Market
Surgical Instruments
Surgical Visualization Market
Surgical Instruments
Huber Needles Market