
 Global Wheelchair Market | 2026-2036
Global Wheelchair Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wheelchair Market Outlook
ISO 7176 technical compliance is rotating supplier eligibility across the powered mobility sector. Permobil AB leverages its Scandinavian manufacturing base to sustain premium positioning in standing wheelchair technology. Ottobock SE & Co. KGaA anchors its portfolio through in-house prosthetics-to-mobility integration. Drive Medical competes aggressively on cost-engineered manual wheelchair lines for institutional buyers.
A wheelchair is a wheeled mobility device with a seating system, frame, and propulsion mechanism, typically constructed from aluminum, titanium, or carbon fiber composites, designed to transport users with impaired ambulatory function. Electric wheelchairs incorporate motor drives, joystick controllers, and programmable seating actuators for users lacking upper-body strength. Manual wheelchairs dominate unit volume across hospitals and rehabilitation centers, while powered seating technology commands superior margins due to actuator complexity and software customization. Sports wheelchairs occupy a specialized niche with geometry-optimized frames for court and track competition.
FDA clearance pathways under 21 CFR 890.3850, ISO 7176 durability standards, and EU MDR Class I classification collectively govern product entry and reimbursement eligibility across major markets. Reimbursement coding precision determines whether Medicare, statutory health insurers, or national health services absorb end-user costs. Stakeholders must monitor evolving reimbursement thresholds for smart-drive power assist units versus full electric base codes.
Market Dynamics
Powered seating actuators and programmable drive controls are redrawing competitive boundaries in wheelchair manufacturing, forcing suppliers to integrate software competencies alongside mechanical frame production.
Growth Catalysts
- EU MDR Class I reclassification:Harmonized technical documentation requirements are accelerating consolidation among European manufacturers seeking notified body certification for powered mobility devices.
- Japan's super-aging demographic profile:METI reimbursement expansions for standing wheelchairs are pulling advanced seating systems into home care settings previously served by basic manual models.
- Lithium-ion battery energy density gains:Improved power-to-weight ratios are extending electric wheelchair range specifications, opening outdoor mobility applications to users with progressive conditions.
Market Restraints
- Titanium tubing supply concentration:Russian and Chinese smelters control roughly two-thirds of aerospace-grade titanium feedstock, exposing frame manufacturers to alloy price volatility and export license uncertainty.
- FDA 510(k) clearance timelines:Average review durations for powered wheelchair predicate devices now exceed fourteen months, compressing product refresh cycles and freezing smaller engineering shops from market entry.
- Walker and rollator substitution:Ambulatory patients with temporary mobility limitations increasingly select lower-cost assistive devices, capping manual wheelchair volume in acute rehabilitation discharge planning.
Strategic Opportunities
- German statutory insurance digitization:Electronic health card pre-authorization for power-assist add-ons is reducing reimbursement friction, creating faster conversion from manual to hybrid propulsion systems.
- India's PLI scheme for medical devices:Production-linked incentives for domestic wheelchair manufacturing are attracting component suppliers to establish assembly operations in Gujarat and Tamil Nadu industrial corridors.
- Smart-drive and smartphone convergence:Bluetooth-enabled power-assist units paired with gait analysis apps are creating subscription-based service models that decouple hardware margins from software recurring revenue.
Industry Challenges
- ISO 7176-19 crash-test engineering talent:Qualified technicians capable of interpreting frontal impact sled data for powered seating systems remain scarce in Eastern European and Southeast Asian manufacturing hubs.
- Legacy hospital fleet amortization schedules:Institutional buyers with five-to-seven-year capital equipment cycles are delaying electric wheelchair refresh programs despite improved battery and actuator specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wheelchair Market |
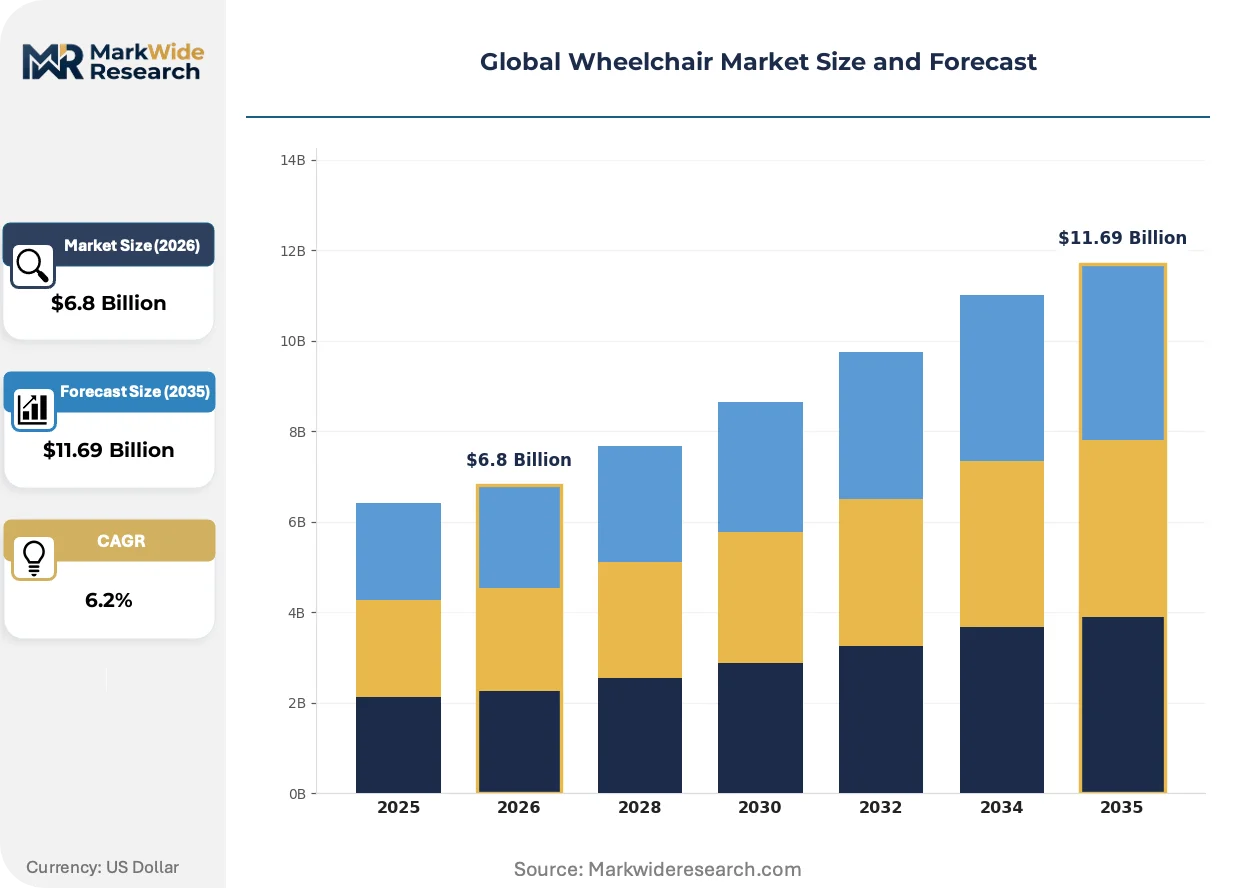
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Wheelchairs, Electric Wheelchairs, Sports Wheelchairs, Pediatric Wheelchairs End User: Hospitals, Rehabilitation Centers, Home Care, Elderly Care Facilities Technology: Powered Seating, Standing Wheelchairs, Lightweight Frames, All-Terrain Models Application: Mobility Assistance, Sports Activities, Medical Transport, Daily Living Activities |
| Companies Covered | Permobil AB, Drive Medical, Invacare Corporation, Karman Healthcare, GF Health Products, Sunrise Medical, Ottobock SE & Co. KGaA, Meghan Medical, Pride Mobility Products Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wheelchair Market Strategic Shifts
Control interfaces and propulsion architectures are diverging across patient acuity levels, with software-defined seating functions displacing mechanical linkages as the primary value determinant in premium segments.
Carbon fiber composite layup automation is fragmenting the traditional aluminum-titanium duopoly in ultralight manual wheelchair frames. German and Japanese racing wheelchair fabricators pioneered automated fiber placement for court sports geometry. Hospital procurement officers now specify carbon fiber for bariatric transport chairs where stiffness-to-weight ratios reduce caregiver strain.
FDA's evolving interpretation of 21 CFR 890.3850 for software-as-a-medical-device is tightening cybersecurity documentation requirements for wheelchair-mounted tablets and voice-control modules. Manufacturers must submit threat modeling and penetration testing protocols alongside traditional biocompatibility data. Powered wheelchair lines with integrated IoT connectivity face the steepest compliance cost escalation.
Hospital group purchasing organizations are consolidating wheelchair specifications across multi-state health systems, compressing supplier diversity from twelve to three approved vendors per category. Academic medical centers in the United States now mandate ISO 7176-8 static load testing documentation for all frame purchases regardless of price tier. This certification-driven consolidation favors vertically integrated manufacturers with in-house metallurgical laboratories over assembly-only competitors.
Global Wheelchair Market Segmentation
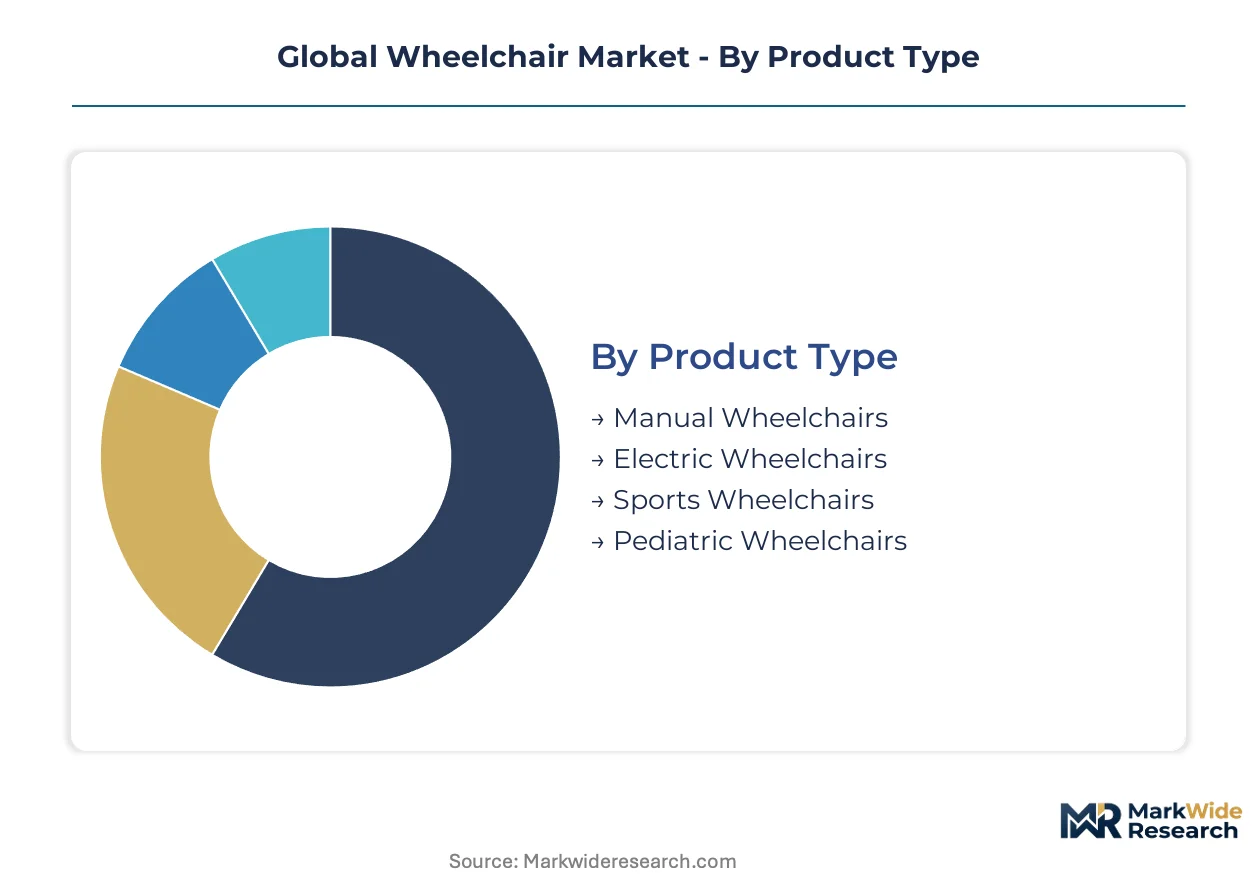
Wheelchair segmentation reveals divergent margin structures across propulsion technologies and care settings. Product type and end-user configuration determine reimbursement coding precision, while technology tier dictates supplier capability requirements.
Product Type:
Manual wheelchairs face the most acute substitution pressure from rollators and walkers in acute discharge planning, while powered alternatives contend with capital budget cycles and maintenance infrastructure gaps.
- Manual Wheelchairs:Aluminum and titanium frames dominate institutional procurement, with carbon fiber penetrating ultralight and bariatric transport segments. Demand concentrates in United States hospital systems and German rehabilitation clinics where ISO 7176-8 static load documentation is now mandatory regardless of price tier.
- Electric Wheelchairs:Motor drives, joystick controllers, and programmable seating actuators serve users lacking upper-body strength. Japan's METI reimbursement expansions are pulling advanced electric models into home care settings previously limited to basic manual alternatives.
- Sports Wheelchairs:Geometry-optimized frames for court and track competition occupy a specialized fabrication niche with premium pricing.
- Pediatric Wheelchairs:Growth-adjustable seating systems accommodate skeletal development, requiring frequent replacement cycles in clinical settings.
Manual wheelchairs anchor the volume base while electric wheelchairs gain share at the steepest rate.
End User:
Procurement authority and reimbursement pathways fragment sharply across institutional versus residential care environments, with capital equipment cycles and insurance pre-authorization creating divergent sales motion requirements.
- Hospitals:Group purchasing organizations consolidate specifications across multi-state health systems, compressing supplier diversity from twelve to three approved vendors per category. United States academic medical centers now mandate ISO 7176-8 documentation for all frame purchases.
- Home Care:Providers are expanding procurement of powered seating systems as lithium-ion battery density gains extend range specifications. German statutory insurance digitization via electronic health card pre-authorization is reducing reimbursement friction for power-assist add-ons.
- Rehabilitation Centers:Functional assessment protocols determine device matching, with seating clinics driving specification complexity.
- Elderly Care Facilities:Japan's super-aging demographic profile is accelerating demand for standing wheelchairs and pressure-relief seating in residential aged care.
Hospitals dominate unit procurement volumes while home care channels show the most rapid expansion trajectory.
Technology:
Software-defined functions are displacing mechanical linkages as the primary value determinant, with actuator complexity and connectivity modules commanding premium positioning.
- Powered Seating:Programmable actuators enable tilt, recline, and elevation functions for pressure management and functional reach. FDA's evolving interpretation of 21 CFR 890.3850 for software-as-a-medical-device is tightening cybersecurity documentation requirements for integrated control systems.
- Standing Wheelchairs:Vertical positioning systems address secondary health complications from prolonged sitting. Japan's METI reimbursement expansions specifically target this category for home care deployment.
- Lightweight Frames:Carbon fiber composite layup automation is fragmenting the traditional aluminum-titanium duopoly in ultralight manual construction.
- All-Terrain Models:Enhanced suspension and traction systems serve outdoor mobility applications for users with progressive conditions.
Powered seating technology captures the highest margin tier while standing wheelchairs climb the fastest in reimbursement-accessible markets.
Application:
Functional use case determines frame geometry, control interface, and durability specifications, with sports and medical transport representing opposite ends of the performance spectrum.
- Mobility Assistance:General ambulatory function replacement spans manual through fully powered configurations. Demand concentrates in Germany, Japan, and the United States where aging demographics and spinal cord injury prevalence drive replacement cycles.
- Daily Living Activities:Seating systems optimized for transfer, reach, and environmental navigation integrate with smart-home controls. Bluetooth-enabled power-assist units paired with gait analysis apps are creating subscription-based service models.
- Sports Activities:Court and track geometries require custom frame fabrication with crash-tested integrity.
- Medical Transport:Bariatric and institutional transport chairs prioritize caregiver strain reduction through stiffness-to-weight optimization.
Mobility assistance absorbs the majority of unit volume while daily living applications show the strongest technology convergence momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput anchors Germany's distribution reach for powered mobility components into Central and Eastern European care networks. Japan's Shinkansen freight corridors expedite just-in-time delivery of lithium-ion battery packs to Osaka-based seating system integrators. India's Dedicated Freight Corridor between Delhi and Mumbai is reducing inland transit times for aluminum frame tubing sourced from Gujarat extrusion plants.
United States
Medicare reimbursement thresholds and Veterans Affairs procurement specifications drive demand for FDA-cleared powered seating systems. The FDA's 21 CFR 890.3850 pathway governs predicate device clearances for joystick-controlled electric bases. Tennessee's manufacturing corridor hosts assembly operations serving hospital group purchasing organizations across the Southeast and Midwest.
Germany
Statutory health insurance digitization via electronic health card pre-authorization is accelerating power-assist add-on conversions. EU MDR Class I reclassification mandates notified body certification for powered mobility devices entering the single market. North Rhine-Westphalia's industrial cluster concentrates frame metallurgy laboratories serving ISO 7176 compliance documentation.
Japan
METI reimbursement expansions for standing wheelchairs are pulling advanced seating systems into residential aged care previously limited to manual models. The PMDA's convergence with MDR technical documentation standards streamlines dual-market registration for domestic manufacturers. Osaka's precision actuator supply chain feeds integration facilities in the Kansai industrial zone.
India
Production-linked incentive schemes for medical devices are attracting component suppliers to establish assembly operations in Gujarat and Tamil Nadu. CDSCO registration requirements for powered wheelchairs are harmonizing with ISO 7176 standards for export-oriented manufacturers. Tamil Nadu's industrial corridor hosts carbon fiber composite layup operations targeting bariatric transport chair specifications.
United Kingdom
NHS England's specialized wheelchair services framework is consolidating procurement specifications across integrated care systems. MHRA post-Brexit recognition of EU MDR certificates maintains market access for continental suppliers. The Midlands manufacturing belt retains aluminum frame fabrication capacity serving institutional buyers.
Global Wheelchair Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and reimbursement navigation capabilities. The supplier base organizes into three tiers: Scandinavian premium seating architects, German prosthetics-to-mobility integrators, and cost-engineered volume fabricators. Strategic moves concentrate on backward integration into titanium tubing supply and software-as-a-medical-device certification capacity.
Within the premium powered seating tier, Permobil AB exemplifies Scandinavian manufacturing concentration for standing wheelchair technology. Ottobock SE & Co. KGaA anchors German engineering integration across prosthetics and mobility portfolios. Drive Medical occupies the cost-optimized institutional procurement segment. These three archetypes represent the competitive vectors reshaping supplier eligibility under tightening ISO 7176 and FDA documentation requirements.
| Leading Market Players |
|---|
| Permobil AB |
| Drive Medical |
| Invacare Corporation |
| Karman Healthcare |
| GF Health Products |
| Sunrise Medical |
| Ottobock SE & Co. KGaA |
| Meghan Medical |
| Pride Mobility Products Corp |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at German and Japanese frame metallurgy laboratories creates scale economies that simultaneously concentrate supply among ISO 7176-certified manufacturers and establish price floors for uncertified competitors. This dynamic compresses margins for aluminum tubing fabricators lacking in-house testing documentation while rewarding vertically integrated seating system integrators with pricing power in powered mobility segments.
Pricing Analysis
Volume-discount tiering structures separate hospital group purchasing organization contracts from individual home care provider orders. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FDA-cleared powered seating commanding substantial premiums over basic manual transport chairs. Cost compression in economy manual wheelchairs is intensifying because institutional buyers consolidate vendor panels from twelve to three approved suppliers. Home care providers exhibit the highest price sensitivity due to reimbursement pre-authorization friction, while academic medical centers prioritize ISO 7176-8 documentation over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate lithium-ion battery pack procurement for electric wheelchair assembly, whereas strategic stockpiling of titanium tubing persists among frame manufacturers exposed to Russian and Chinese smelter concentration. Supply concentrates in Germany, Japan, and the United States for powered seating actuators, with carbon fiber composite layup operations expanding in India and China. Raw material dependencies encompass aerospace-grade titanium feedstock, lithium-ion cells, and automated fiber placement equipment. Single-source vulnerability in Russian titanium smelting exposes frame fabricators to export license uncertainty. Distribution runs through hospital group purchasing organizations and statutory insurance electronic health card pre-authorization channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wheelchair manufacturing is evolving into a service-attach opportunity where software subscription revenue from Bluetooth-enabled power-assist units and gait analysis apps expands faster than hardware margins. Recurring revenue from seating system calibration, remote diagnostics, and predictive maintenance contracts now outpaces unit sales growth in premium powered mobility segments.
For Market Incumbents: Consolidate backward integration into titanium tubing supply and carbon fiber composite layup capacity to defend against alloy price volatility and certification-driven vendor consolidation. Capture ISO 7176-19 crash-test engineering talent through targeted recruitment in Eastern European manufacturing hubs. Channel control through exclusive hospital system partnerships protects pricing power as group purchasing organizations narrow vendor panels.
For New Entrants and Emerging Players: Anchor in India's PLI scheme for medical devices to exploit production-linked incentives and establish assembly operations in Gujarat and Tamil Nadu industrial corridors. Target standing wheelchair segments in Japan's residential aged care market where METI reimbursement expansions create accessible demand previously limited to manual models. Pursue software-as-a-medical-device certification pathways for smartphone-integrated power-assist units.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated seating system architects with captive metallurgical laboratories and software development capabilities over assembly-only competitors. Long-term viability hinges on reimbursement navigation expertise and regulatory certification capacity across FDA, EU MDR, and PMDA jurisdictions. Monitor FDA 510(k) clearance timeline compression as an inflection indicator for smaller engineering shop market entry viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-a-Medical-Device Certification | FDA's evolving 21 CFR 890.3850 interpretation tightens cybersecurity documentation for wheelchair-mounted IoT connectivity modules. |
| Backward Integration into Titanium Supply | Captive aerospace-grade tubing production insulates frame manufacturers from Russian and Chinese smelter export license volatility. |
| Hospital System Partnership Expansion | Exclusive contracts with academic medical centers secure ISO 7176-8 mandatory documentation requirements across multi-state health systems. |
| Smart-Drive Subscription Service Launch | Bluetooth-enabled power-assist units paired with gait analysis apps decouple hardware margins from recurring software revenue streams. |
| Reimbursement Strategy Digitization | German electronic health card pre-authorization reduces friction for power-assist add-on conversions from manual to hybrid propulsion. |
Study Parameters
Cross-validation between primary interviews with powered seating engineers, hospital procurement officers, and rehabilitation clinicians anchors the qualitative findings against secondary validation from FDA 510(k) clearance databases, EU MDR notified body certification records, and METI reimbursement expansion filings. Bottom-up triangulation across component supplier interviews and top-down reconciliation against statutory health insurance expenditure data ensures segmentation integrity across manual, electric, and sports wheelchair categories.
Sensitivity analysis frameworks test demand projections against lithium-ion battery energy density improvement trajectories and ISO 7176 standard revision timelines. Modeled segmentation spans propulsion technology, end-user care setting, and software integration complexity across the analysis window. CAGRs derive from regression analysis of historical procurement volumes weighted by reimbursement policy shift probabilities and demographic aging curves in Germany, Japan, and the United States.
Decision-makers should treat outputs as directional under stable regulatory harmonization assumptions; material deviation in FDA cybersecurity documentation requirements or EU MDR reclassification enforcement would warrant model refresh. Revision becomes warranted when titanium feedstock export licensing crosses disruption thresholds or when standing wheelchair reimbursement codes expand beyond current statutory coverage.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
ECG Sensor Patch Market
Medical Devices
Europe Electroencephalography Devices Market
Medical Devices
3D Medical Imaging Devices Market
Medical Devices
Peripheral Interventions Market
Medical Devices
Spinal Traction Market
Medical Devices
Image-Based Cytometer Market
Medical Devices
Echogenic Catheters Market
Medical Devices
North America Surgical Visualization Products Market
Medical Devices
Interventional Cardiology Devices Market
Medical Devices
Asia-Pacific Refractive Surgery Devices Market
Medical Devices
Global Uterine Manipulation Devices Market
Medical Devices
Intracranial Stents Total Addressable Market
Medical Devices
Buccal Cavity Devices Market
Medical Devices
Germany Ophthalmic Devices Market
Medical Devices
Tubeless Insulin Pump Market
Medical Devices
Gastric Electrical Stimulators Market