
 Global Asthma and Copd Devices Market | 2026-2036
Global Asthma and Copd Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Asthma and Copd Devices Market Foresight
Smart inhaler certification and connected device interoperability standards is unwinding legacy product hierarchies across the respiratory device landscape. AstraZeneca leverages its biologics-digital pairing strategy to sustain leadership in integrated asthma management platforms. Boehringer Ingelheim anchors its position through deep specialization in soft mist inhaler mechanics, while Philips Respironics dominates hospital-to-home nebulizer transitions with its ventilator-adjacent respiratory portfolio.
Asthma and COPD devices comprise metered dose inhalers, dry powder inhalers, nebulizers, soft mist inhalers, and spacer devices engineered to deliver bronchodilators and corticosteroids with particle sizes between one and five micrometers for optimal lower airway deposition. These instruments serve the primary commercial purpose of reducing acute exacerbation frequency and maintaining forced expiratory volume in chronic obstructive and asthmatic patient populations. Metered dose inhalers occupy the largest installed base due to decades of clinical familiarity and compact form factors, though connectivity-enabled technology segments are capturing disproportionate R&D investment as reimbursement codes increasingly reward adherence documentation. Home care patients represent the fastest-growing end user channel as pulmonary rehabilitation programs shift monitoring responsibilities away from ambulatory care centers.
FDA digital health pre-certification pathways and EU MDR Class IIa device requirements are tightening validation standards for connectivity-enabled inhalers across both North American and European markets. Japan's PMDA has accelerated review timelines for combination products incorporating digital monitoring, reshaping competitive access dynamics for foreign manufacturers. China's NMPA alignment with international electromagnetic compatibility standards is opening previously restricted procurement channels for ultrasonic nebulization systems. Stakeholders must monitor evolving cybersecurity mandates for connected respiratory devices as regulators in multiple jurisdictions draft post-market surveillance requirements for cloud-transmitted patient data.
Market Dynamics
Connectivity-enabled inhaler certification is compressing product development timelines while fragmenting competitive hierarchies as reimbursement codes reward adherence documentation over legacy device familiarity.
Growth Catalysts
- MDR Class IIa device requirements:EU regulatory harmonization accelerates cross-border procurement standardization for connected respiratory devices. Manufacturers gain streamlined market access across Germany, France, and Italy.
- Home care patient channel:Pulmonary rehabilitation programs in the United States and Japan are transferring monitoring responsibilities from ambulatory centers to domestic settings. This shift expands addressable device populations beyond hospital discharge cohorts.
- Soft mist inhaler mechanics:Advances in liquid formulation aerosolization improve lower airway deposition rates for corticosteroid delivery. Specialist manufacturers capture premium positioning through differentiated particle engineering.
Market Restraints
- Electronics input cost volatility:MEMS sensors and Bluetooth Low Energy modules face semiconductor foundry allocation constraints. Device margins compress when sensor lead times extend beyond twelve weeks.
- Cloud infrastructure supplier concentration:Patient data transmission dependencies on hyperscale cloud providers in the United States create systemic resilience risks. Cybersecurity incident propagation threatens multi-market device fleets simultaneously.
- FDA digital health pre-certification timeline:Validation pathway complexity extends connected inhaler approval cycles. Smaller manufacturers abandon connectivity roadmaps rather than absorb compliance overhead.
Strategic Opportunities
- India's CDSCO alignment:Medical device rules harmonization with IMDRF standards opens import substitution opportunities for ultrasonic nebulization systems. Domestic manufacturing incentives reduce landed cost disadvantages.
- Ambient sensor convergence:Integration of inhaler monitors with residential air quality detectors and sleep apnea devices creates integrated respiratory health platforms. Technology licensing between device categories accelerates feature parity.
- Subscription reimbursement models:German statutory health insurance pilot programs for digital therapeutics extend to connected inhaler adherence programs. Recurring revenue structures replace transactional device sales.
Industry Challenges
- Cybersecurity certification skill scarcity:FDA pre-market submission requirements for connected device software bill of materials exceed available qualified engineering capacity. Development teams face recruitment bottlenecks for cloud security specialists.
- Legacy hospital nebulizer integration:Ventilator-adjacent respiratory portfolios require interoperability with proprietary electronic health record systems. Data format fragmentation forces redundant connectivity development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Asthma and Copd Devices Market |
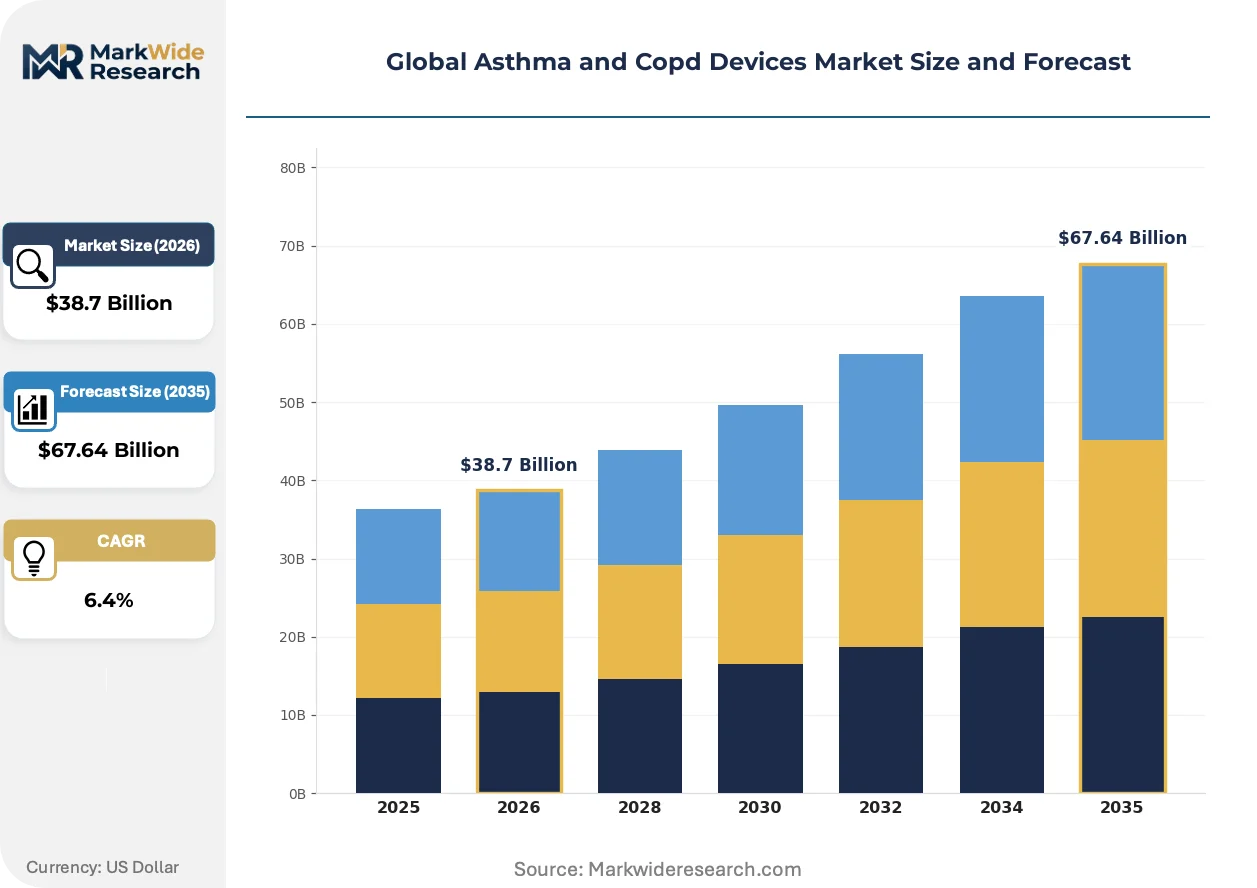
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metered Dose Inhalers, Dry Powder Inhalers, Nebulizers, Soft Mist Inhalers, Spacer Devices Technology: Breath Actuated, Connectivity Enabled, Digital Monitoring, Pressure Meter Based, Ultrasonic Nebulization Application: Chronic Obstructive Lung Disorder, Bronchial Asthma, Allergic Bronchopulmonary, Occupational Lung Disease, Exercise Induced Bronchospasm End User: Pulmonary Clinics, Respiratory Specialists, Home Care Patients, Ambulatory Care Centers, Rehabilitation Facilities |
| Companies Covered | GlaxoSmithKline, AstraZeneca, Boehringer Ingelheim, Philips Respironics, Teva Pharmaceutical Industries, Merck, PARI Medical, Omron, Cipla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Asthma and Copd Devices Market Shifts & Advancements
Sensor-embedded inhaler hardware is compressing form factors while cloud-native software architectures enable real-time adherence analytics that reshape prescriber-pharmacist-patient interaction models.
MEMS-based flow sensors with integrated accelerometers are miniaturizing to dimensions compatible with standard metered dose inhaler canister geometry. Home care patients in Japan and Germany receive these devices through pharmacy dispensing channels that previously stocked only mechanical spacers. The technology is miniaturizing clinical-grade spirometry into daily-use consumer hardware, collapsing the distinction between diagnostic and therapeutic device categories.
EU MDR post-market surveillance requirements for cloud-transmitted patient data are mandating encrypted transmission protocols and audit trail retention periods that exceed prior industry practice. Device manufacturers must revalidate existing connectivity stacks or face notified body withdrawal of CE certificates. Nebulizer systems with integrated mobile applications face the steepest compliance recertification burden due to software lifecycle complexity.
Hospital procurement committees in the United States are unbundling device acquisition from consumables supply contracts that previously locked institutions into single-source relationships. Group purchasing organizations negotiate connectivity platform licenses separately from inhaler hardware, enabling multi-manufacturer formularies. This pattern is most visible in integrated delivery networks across Texas and California where pharmacy benefit managers influence device selection criteria.
Global Asthma and Copd Devices Market Segmentation
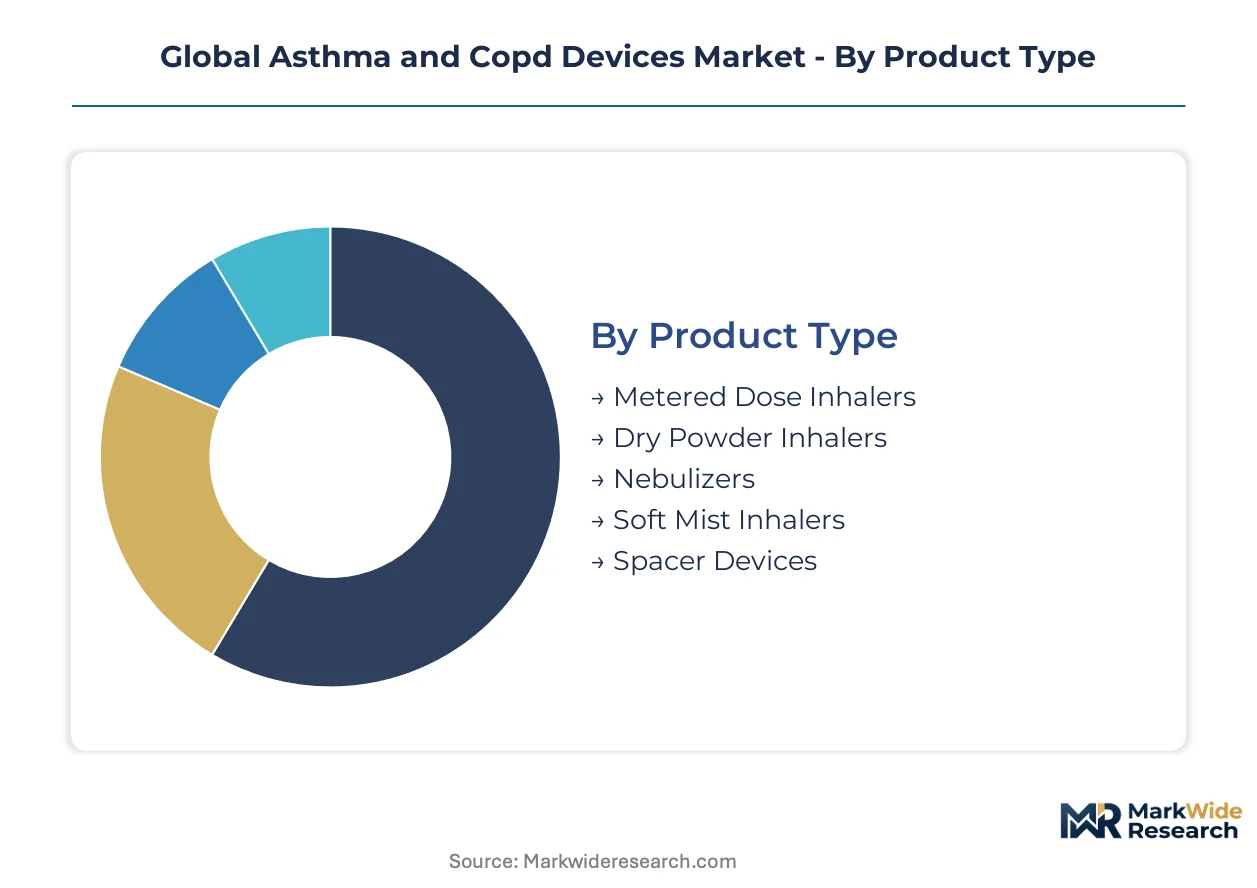
Device segmentation in respiratory care determines reimbursement coding, manufacturing scale economics, and regulatory pathway selection. Category boundaries are blurring as connectivity modules penetrate traditional hardware segments, forcing portfolio reconfiguration across metered dose and soft mist platforms.
Product Type:
Margin pools concentrate in connectivity-ready hardware that captures recurring software revenue alongside device sales, while legacy mechanical formats compete on manufacturing efficiency.
- Metered Dose Inhalers:Pressurized canister systems deliver bronchodilators through chlorofluorocarbon-free propellant formulations with particle sizes calibrated for lower airway deposition. Demand concentrates in the United States where pharmacy benefit managers favor compact form factors for mail-order distribution channels, though reimbursement compression on generic albuterol formulations constrains premium pricing.
- Soft Mist Inhalers:Mechanical spring-energy systems aerosolize liquid formulations without propellants, achieving slower plume velocity that reduces oropharyngeal deposition. Germany's statutory health insurance funds prioritize these devices for corticosteroid delivery in elderly populations with compromised hand-breath coordination, creating protected reimbursement tiers.
- Dry Powder Inhalers:Breath-actuated powder dispersion systems eliminate coordination requirements through patient-generated airflow activation.
- Nebulizers:Compressor-driven and ultrasonic systems convert liquid medications into respirable aerosols for patients requiring high-dose delivery.
- Spacer Devices:Valved holding chambers attach to metered dose inhalers to improve drug delivery efficiency in pediatric and geriatric populations.
Metered dose inhalers hold installed capacity. Soft mist inhalers are rotating up the share rankings.
Technology:
Technology selection dictates regulatory burden and software lifecycle management costs, with connectivity stacks requiring continuous cybersecurity validation.
- Connectivity Enabled:Bluetooth Low Energy modules paired with mobile applications transmit adherence timestamps and inhalation technique metrics to cloud platforms. Japan's PMDA accelerated review timelines for these combination products, reshaping competitive access dynamics for foreign manufacturers seeking premium positioning.
- Digital Monitoring:Embedded sensors track dose counting, timing, and technique without full two-way connectivity, reducing cybersecurity compliance overhead. Home care patients in Germany receive these devices through pharmacy dispensing channels that previously stocked only mechanical spacers, expanding addressable populations.
- Breath Actuated:Mechanical triggers release medication upon patient inhalation, eliminating hand-breath coordination requirements.
- Pressure Meter Based:Manometer-integrated devices provide visual feedback on inspiratory flow rate for technique training.
- Ultrasonic Nebulization:Piezoelectric crystal vibration generates aerosols without compressor noise, enabling bedside use in residential settings.
Digital monitoring holds installed capacity. Connectivity enabled is climbing the fastest.
Application:
Application segmentation aligns with prescriber specialty and reimbursement code specificity, with COPD commanding distinct device formularies from asthma management protocols.
- Chronic Obstructive Lung Disorder:Progressive airflow limitation requires combination long-acting bronchodilator therapy delivered through high-efficiency platforms. Pulmonary rehabilitation programs in the United States are transferring monitoring responsibilities from ambulatory centers to domestic settings, expanding nebulizer and soft mist device deployment.
- Bronchial Asthma:Reversible airway obstruction drives demand for rescue inhalers with rapid onset and maintenance therapy with inhaled corticosteroids. Pediatric specialists in Japan prefer breath-actuated dry powder systems for school-age patients with developing coordination skills.
- Allergic Bronchopulmonary:Fungus-triggered inflammatory conditions require prolonged antifungal nebulization protocols.
- Occupational Lung Disease:Workplace exposure-related conditions demand portable rescue devices for on-site emergency access.
- Exercise Induced Bronchospasm:Activity-triggered bronchoconstriction favors compact metered dose formats for athletic and school environments.
Chronic obstructive lung disorder holds installed capacity. Bronchial asthma is gaining share fastest.
End User:
End user channel selection determines sales force structure, with home care requiring pharmacy partnerships and hospital channels demanding clinical evidence packages.
- Home Care Patients:Domestic self-management populations receive devices through retail pharmacy, durable medical equipment suppliers, and direct-to-patient subscription models. Germany's statutory health insurance pilot programs for digital therapeutics extend to connected inhaler adherence programs, creating recurring revenue structures.
- Pulmonary Clinics:Specialist-directed care settings prescribe advanced delivery platforms with integrated monitoring for severe disease phenotypes. United States integrated delivery networks across Texas and California unbundle device acquisition from consumables supply contracts, enabling multi-manufacturer formularies.
- Respiratory Specialists:Pulmonologist practices drive adoption of novel soft mist and connectivity-enabled platforms through clinical trial participation.
- Ambulatory Care Centers:Outpatient hospital departments manage post-exacerbation transitions with standardized device education protocols.
- Rehabilitation Facilities:Structured pulmonary programs incorporate device technique training into comprehensive care plans.
Pulmonary clinics hold installed capacity. Home care patients are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing clusters concentrate in Germany, the United States, and Japan, where precision engineering capabilities and reimbursement infrastructure sustain premium positioning. Regulatory harmonization across these markets accelerates cross-border procurement standardization for connected respiratory platforms.
United States
Pharmacy benefit managers favor compact metered dose inhalers for mail-order distribution, expanding home care patient channels. FDA digital health pre-certification pathways tighten validation standards for connectivity-enabled devices. Texas and California integrated delivery networks unbundle device acquisition from consumables contracts, enabling multi-manufacturer formularies.
Germany
Statutory health insurance funds prioritize soft mist inhalers for elderly populations with compromised hand-breath coordination. EU MDR Class IIa device requirements streamline cross-border procurement standardization across France and Italy. Bavaria's medical technology corridor anchors production of precision aerosolization systems for export markets.
Japan
PMDA accelerated review timelines for combination products incorporating digital monitoring reshape competitive access for foreign manufacturers. Aging demographics drive demand for connectivity-enabled adherence platforms in pulmonary rehabilitation programs. Tokyo-Osaka industrial clusters specialize in MEMS sensor miniaturization for inhaler integration.
China
NMPA alignment with international electromagnetic compatibility standards opens procurement channels for ultrasonic nebulization systems. Domestic manufacturing incentives under medical device rules harmonization reduce landed cost disadvantages for import substitution. Yangtze River Delta clusters scale production of compressor-driven nebulizers for regional distribution.
India
CDSCO alignment with IMDRF standards creates import substitution opportunities for ultrasonic nebulization systems. Pulmonary disease burden in urban centers expands addressable patient populations beyond hospital discharge cohorts. Maharashtra and Gujarat manufacturing zones develop component supply capabilities for global device assemblers.
Global Asthma and Copd Devices Market Competitive Landscape
Concentration sits with diversified pharmaceutical conglomerates possessing integrated respiratory portfolios. Three to five multinational players command disproportionate share through decades of clinical familiarity and formulary lock-in. Strategic archetypes span biologics-digital pairing specialists, soft mist mechanics engineers, and hospital-to-home transition enablers. Competitive moves center on adherence platform licensing and ventilator-adjacent portfolio expansion.
Within the pharmaceutical-digital integration tier, AstraZeneca and Boehringer Ingelheim exemplify contrasting specialization vectors. AstraZeneca occupies a position emphasizing biologics-digital pairing for integrated asthma management platforms. Boehringer Ingelheim anchors the soft mist inhaler mechanics specialization through liquid formulation aerosolization expertise. Philips Respironics, a subsidiary structure within a broader health technology conglomerate, represents the hospital-to-home nebulizer transition archetype through ventilator-adjacent respiratory portfolio positioning.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| AstraZeneca |
| Boehringer Ingelheim |
| Philips Respironics |
| Teva Pharmaceutical Industries |
| Merck |
| PARI Medical |
| Omron |
| Cipla |
| Others |
Supply & Pricing Matrix
Twelve-week sensor lead times for MEMS and Bluetooth Low Energy modules compress margin buffers for connectivity-enabled inhaler manufacturers, concentrating pricing power with semiconductor foundries serving German and Japanese precision engineering clusters while forcing device makers to absorb cost volatility or surrender market share.
Pricing Analysis
EU MDR Class IIa device requirements dictate the pricing tier structure across European markets, separating CE-marked connectivity platforms from legacy mechanical devices. Three-tier pricing structure across premium connectivity-enabled, standard digital monitoring, and economy mechanical inhalers stratifies reimbursement codes in Germany and Japan. Cost compression in the standard tier intensifies because generic albuterol formulations face pharmacy benefit manager reimbursement compression in the United States. Home care patients exhibit highest price sensitivity due to out-of-pocket exposure, while hospital procurement committees demonstrate lowest sensitivity where adherence documentation drives formulary decisions.
Supply Chain Analysis
Taiwan semiconductor foundry allocation constraints for MEMS sensors create chokepoint vulnerability for inhaler connectivity modules, forcing manufacturers into premium pricing or extended delivery windows. Component sourcing draws from German precision aerosolization systems, Japanese MEMS miniaturization clusters, and Chinese compressor-driven nebulizer manufacturing. Single-source vulnerability concentrates in hyperscale cloud infrastructure for patient data transmission, threatening multi-market device fleet resilience. Distribution runs through pharmacy benefit manager mail-order channels in the United States, statutory health insurance pharmacy networks in Germany, and hospital procurement committees for ventilator-adjacent respiratory portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connectivity-enabled inhaler adoption sits in early-cycle expansion as home care patient channels accelerate beyond hospital discharge cohorts, with digital monitoring technology penetration still below saturation thresholds across major reimbursement markets.
For Market Incumbents: Shield formulary positioning through accelerated FDA digital health pre-certification for combination products, locking in adherence documentation reimbursement codes before connectivity standards commoditize. Deepen backward integration into MEMS sensor supply through captive relationships with Taiwanese foundries, reducing twelve-week lead time exposure that compresses margins for competitors lacking procurement scale.
For New Entrants and Emerging Players: Lead with ultrasonic nebulization systems targeting India's CDSCO-aligned import substitution opportunities, where domestic manufacturing incentives reduce landed cost disadvantages against established multinational portfolios. Capture pulmonary rehabilitation program contracts in Maharashtra and Gujarat urban centers, leveraging component supply zone proximity for logistics cost advantage against distant manufacturing bases.
For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because adherence analytics software creates recurring revenue structures displacing transactional device sales, with German statutory health insurance pilot programs validating subscription reimbursement models. Target acquisition archetypes include soft mist inhaler mechanics specialists with liquid formulation aerosolization IP and cloud-native connectivity stacks with EU MDR cybersecurity certification. Monitor PMDA accelerated review timeline expansion as signal for Japanese market access premium erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Health Pre-Certification | Accelerated approval timelines for connected inhalers reshape competitive access dynamics in United States pharmacy benefit manager networks. |
| EU MDR Class IIa Device Certification | Harmonized validation standards streamline cross-border procurement standardization across German, French, and Italian reimbursement systems. |
| Hospital System Partnership | Integrated delivery network formulary unbundling in Texas and California enables multi-manufacturer connectivity platform licensing. |
| Software Companion Development | Cloud-native adherence analytics applications capture recurring revenue alongside hardware sales in German statutory insurance pilots. |
| Reimbursement Strategy | Adherence documentation coding alignment with CMS and GBA priorities determines pharmacy dispensing channel access for home care patients. |
Research Methodology
The analysis maps metered dose inhalers, soft mist inhalers, nebulizers, and connectivity-enabled platforms, each validated through respiratory specialists, hospital procurement managers, pharmacy benefit directors, and biomedical engineers. Primary interviews with device manufacturers and GPO contracts managers combined with secondary validation against FDA 510(k) filings, EMA MDR submissions, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window, with segmentation modeling across device type, technology tier, application severity, and end-user channel. CAGRs derived from installed base replacement cycles, connectivity penetration curves, and reimbursement code expansion timelines. Forecast inputs incorporated pulmonary rehabilitation program shift rates, MEMS sensor cost trajectories, and cloud infrastructure supplier concentration risks.
Underlying assumptions cover regulatory harmonization continuity, semiconductor foundry allocation normalization, and cybersecurity certification capacity expansion, with deviation risk concentrated in FDA pre-certification timeline delays and EU MDR notified body capacity constraints. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Capnography Devices Market
Medical Devices
Distal Embolic Filters Market
Medical Devices
Craniomaxillofacial Plate and Installation Tools Market
Medical Devices
Implantable Neurostimulators Market
Medical Devices
Global Non Fusion Spinal Devices Market
Medical Devices
Surgical Smart Glasses Market
Medical Devices
Biomedical Warming and Thawing Devices Market
Medical Devices
Neurotech Devices Market
Medical Devices
Cardiac Catheters and Guidewires Market
Medical Devices
Global Contrast Media Injector Market
Medical Devices
X-Ray Positioning Devices Market
Medical Devices
3D Printing in Healthcare Market
Medical Devices
Reusable Laparoscopic Instrument Market
Medical Devices
Nasal Packing Devices Market
Medical Devices
Global Smart Implants Market
Medical Devices
Global Intravenous (IV) Equipment Market