
 Medication Adherence Market | 2026-2036
Medication Adherence Market Size, Share, and Industry Trends Forecast 2026-2036
Medication Adherence Market Analysis
The medication adherence landscape is recalibrating around a sharp split between premium enterprise platforms and commodity reminder tools. Omnicell, Inc. leverages automated dispensing infrastructure to dominate hospital-centric adherence workflows. Cardinal Health anchors its position through distribution scale that reaches retail pharmacies and long-term care facilities nationwide. McKesson Corporation competes by embedding adherence analytics within its existing pharmaceutical supply relationships.
Medication adherence encompasses technologies and services designed to measure, monitor, and improve patient compliance with prescribed pharmaceutical regimens, typically integrating electronic monitoring sensors, software algorithms for behavioral intervention, and data transmission protocols for clinician oversight. The primary commercial purpose centers on reducing avoidable hospitalizations and disease progression costs for payers while improving therapeutic outcomes. Adherence apps currently capture the fastest expansion as smartphone penetration and API connectivity lower deployment barriers, whereas medication management systems command the deepest margin pools due to enterprise licensing structures and EMR integration requirements. Smart pill bottles occupy a maturing niche where hardware commoditization pressures unit economics.
FDA digital health software guidance, CMS remote therapeutic monitoring billing codes, and HIPAA security rule enforcement collectively determine product certification requirements and reimbursement eligibility for adherence solution vendors. The FDA's evolving software-as-medical-device framework shapes R&D investment allocation between diagnostic claims and general wellness positioning. Stakeholders must monitor whether CMS expands RTM coverage beyond the current chronic respiratory and musculoskeletal scope to include broader therapeutic categories.
Market Dynamics
The medication adherence market is reconfiguring around CMS reimbursement codes that now compensate providers for remote therapeutic monitoring, fundamentally altering procurement economics for hospital systems and specialty pharmacies.
Growth Catalysts
- CMS Remote Therapeutic Monitoring Reimbursement:Medicare billing codes for respiratory and musculoskeletal conditions now cover connected adherence devices, creating immediate revenue streams for clinics deploying pill sensors and digital therapeutics.
- Smartphone API Connectivity:Open health data standards enable seamless integration between adherence apps and electronic medical records, reducing deployment friction for health systems seeking behavioral intervention tools.
- Integrated Delivery Network Consolidation:Hospital network mergers in the United States are centralizing pharmacy procurement decisions, favoring enterprise-scale medication management platforms with EMR-native architectures.
Market Restraints
- Hardware Commoditization Pressure:Smart pill bottle manufacturers face margin erosion as Chinese electronics suppliers drive sensor component costs toward commodity levels.
- HIPAA Security Rule Compliance Burden:Encryption and audit requirements for patient data transmission impose ongoing operational costs that disadvantage smaller adherence app developers.
- Behavioral Intervention Efficacy Variability:Algorithm-driven nudge systems demonstrate inconsistent clinical outcomes across patient populations, limiting payer willingness to fund premium-tier solutions.
Strategic Opportunities
- Expansion of RTM Coverage Scope:CMS proposals to extend remote therapeutic monitoring beyond respiratory and musculoskeletal categories would unlock reimbursement for cardiovascular and diabetes adherence programs.
- Convergence of Adherence and Diagnostics:Integration of pharmacokinetic sensors with medication event monitoring is creating real-time therapeutic drug monitoring systems for oncology and immunology.
- Pharmacy Benefit Manager Data Monetization:PBM-owned adherence platforms can repackage de-identified compliance analytics as risk-scoring products for life insurers and reinsurers.
Industry Challenges
- Interoperability Fragmentation:Proprietary data formats between competing EMR vendors force adherence solution providers to maintain multiple integration pipelines, inflating R&D overhead.
- Clinical Validation Timeline Compression:FDA software-as-medical-device pathways demand rigorous evidence generation for behavioral intervention claims, extending time-to-market for algorithm-centric products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medication Adherence Market |
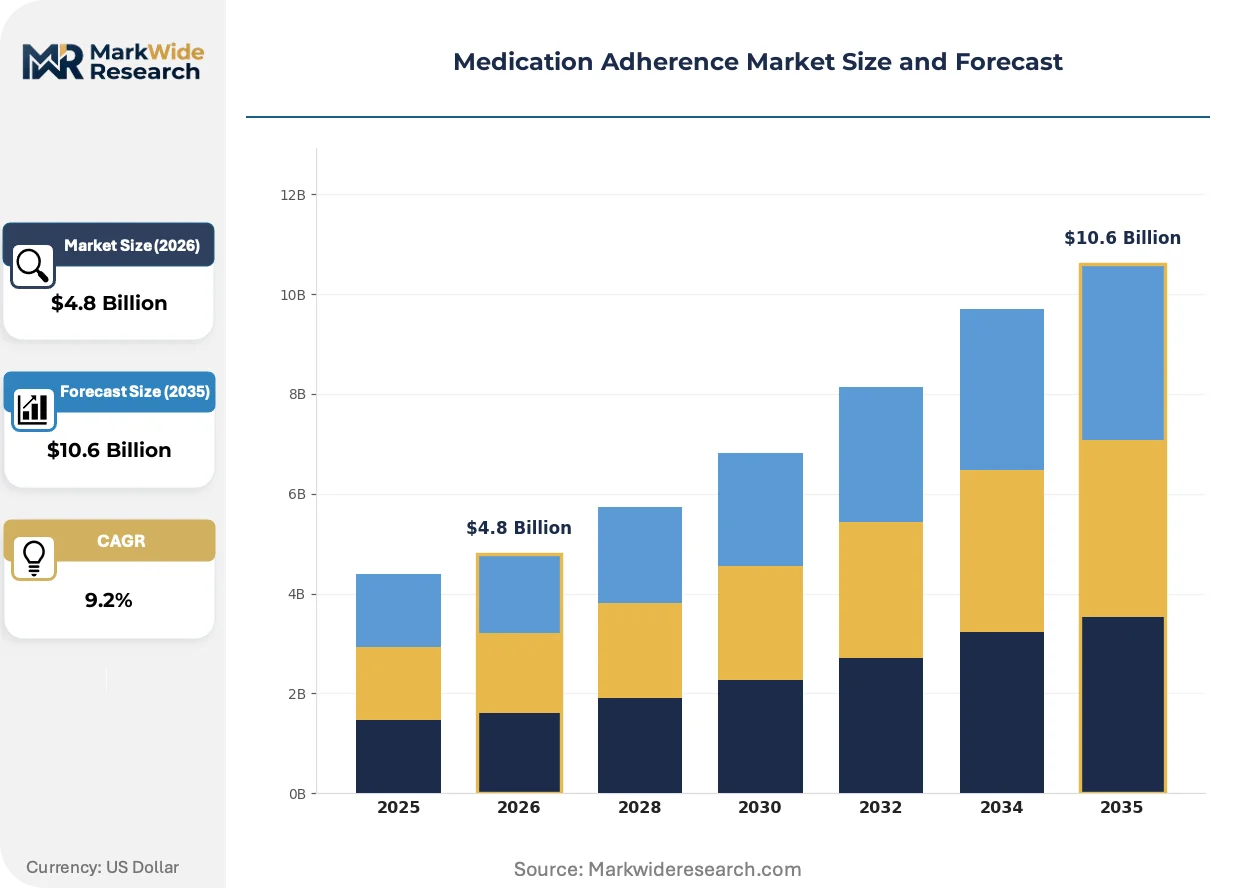
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.6 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Pill Bottles, Adherence Apps, Medication Management Systems, Digital Pillboxes Therapy Area: Diabetes, Cardiovascular, Oncology, Mental Health End User: Patients, Healthcare Providers, Pharmacies, Caregivers Delivery Mode: Mobile, Web-Based, Wearable Devices, SMS Reminders |
| Companies Covered | Omnicell, Inc., Cardinal Health, McKesson Corporation, AdhereTech, DrFirst, Medminder Systems, Inc., Koninklijke Philips N.V., AARDEX Group, Medisafe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medication Adherence Market Emerging Trajectories
Digital health infrastructure is fragmenting adherence solution deployment from centralized hospital IT departments toward distributed care teams and patient-owned devices.
Bluetooth-enabled pill sensors with accelerometer-based ingestion detection are decentralizing medication monitoring from institutional settings into home environments. Skilled nursing facilities and home health agencies are deploying these devices at scale for post-acute care transitions. This shift is decentralizing data ownership toward patients and their designated caregivers, compressing the role of hospital-based pharmacy informatics departments.
FDA's evolving software-as-medical-device guidance is reclassifying behavioral intervention algorithms with diagnostic claims as regulated medical devices. Developers must now navigate premarket notification requirements for adherence apps that predict hospitalization risk. Oncology and rare disease adherence platforms face the steepest compliance burden, with several vendors repositioning products as general wellness tools to avoid regulatory scrutiny.
Specialty pharmacies are unbundling adherence support from drug dispensing, selling compliance coaching as standalone service contracts to payers. This disintermediation threatens traditional pharmacy benefit manager bundled offerings. The model is gaining traction in Medicaid managed care plans seeking to reduce emergency department utilization among high-risk polypharmacy populations.
Medication Adherence Market Segmentation
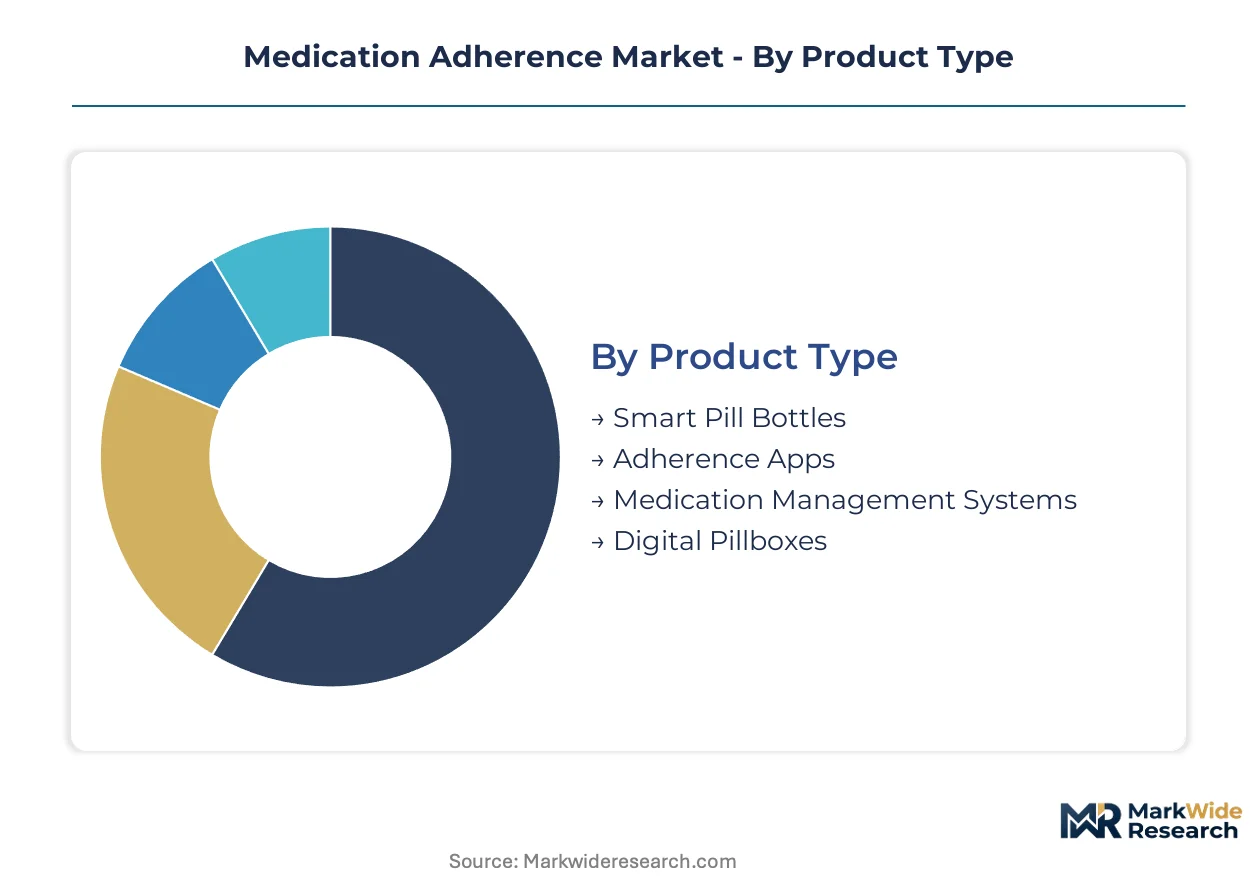
Medication adherence solutions fragment across hardware, software, and service layers that command fundamentally different margin structures and procurement cycles. Understanding these segment boundaries clarifies where enterprise budgets concentrate versus where commoditization pressures dominate.
Product Type:
Supply concentration clusters around platforms with embedded distribution relationships and regulatory clearance depth.
- Smart Pill Bottles:Bluetooth-enabled containers with accelerometer-based ingestion detection and cellular data transmission. Demand concentrates in United States skilled nursing facilities managing post-acute care transitions, though Chinese sensor suppliers are compressing hardware margins toward commodity levels.
- Adherence Apps:Smartphone-native platforms leveraging open health APIs for EMR connectivity and behavioral nudge algorithms. These are expanding most quickly among Medicaid managed care plans seeking to reduce emergency department utilization among high-risk polypharmacy populations.
- Medication Management Systems:Enterprise-scale platforms with native EMR architectures and enterprise licensing structures.
- Digital Pillboxes:Consumer-oriented compartmentalized dispensers with timer-based alerts and basic connectivity.
Today's leader: Medication Management Systems. Tomorrow's challenger: Adherence Apps.
Therapy Area:
Clinical validation requirements and reimbursement eligibility create tiered market access barriers across therapeutic categories.
- Diabetes:Continuous glucose monitor integration with insulin dosing adherence platforms. United States integrated delivery networks are centralizing procurement for these combined monitoring-adherence workflows.
- Cardiovascular:Antihypertensive and anticoagulant regimen monitoring with stroke risk stratification. CMS proposals to extend remote therapeutic monitoring reimbursement beyond respiratory and musculoskeletal categories would unlock immediate demand acceleration here.
- Oncology:Oral oncolytic adherence with therapeutic drug monitoring for narrow therapeutic index agents.
- Mental Health:Psychiatric medication compliance platforms with mood tracking and crisis prediction features.
Cardiovascular commands current enterprise spend. Diabetes shows steepest expansion trajectory if CMS expands RTM coverage scope.
End User:
Purchasing authority and budget ownership determine pricing tolerance and contract complexity across stakeholder types.
- Healthcare Providers:Hospital systems and physician practices seeking CMS-reimbursable remote therapeutic monitoring deployments. Procurement decisions centralize within pharmacy informatics departments at merged integrated delivery networks.
- Pharmacies:Specialty and retail pharmacies unbundling adherence coaching from dispensing operations. This disintermediation threatens traditional pharmacy benefit manager bundled offerings in United States Medicaid managed care plans.
- Patients:Direct-to-consumer purchasers of reminder tools and connected devices.
- Caregivers:Family members and paid home health aides managing medication protocols for dependent populations.
Healthcare Providers anchor current revenue. Pharmacies represent the fastest-growing procurement channel as compliance coaching separates from drug dispensing.
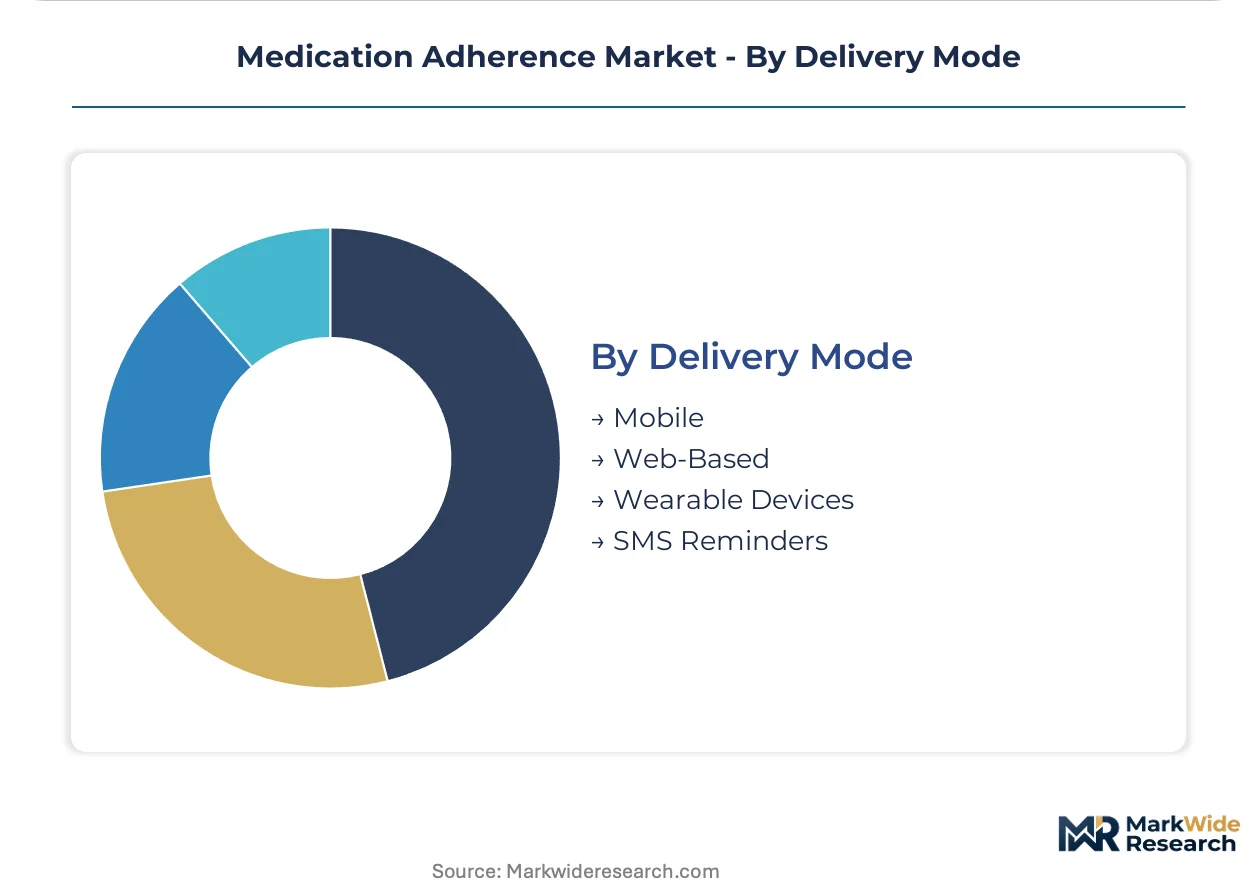
Delivery Mode:
Deployment infrastructure and data transmission protocols segment solutions by technical complexity and HIPAA compliance burden.
- Mobile:Native iOS and Android applications with Bluetooth peripheral pairing and cloud-based analytics dashboards. Encryption and audit requirements for patient data transmission impose operational costs that disadvantage smaller developers.
- Wearable Devices:Smartwatch and patch-based medication event detection with biometric correlation. FDA software-as-medical-device guidance is reclassifying behavioral intervention algorithms with diagnostic claims as regulated medical devices, extending time-to-market for these products.
- Web-Based:Browser-accessible portals for clinician oversight and caregiver coordination.
- SMS Reminders:Text-based alert systems with lowest deployment friction but limited behavioral intervention depth.
Mobile dominates current deployment volume. Wearable Devices face steepest regulatory headwinds but promise richest data streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procurement volumes dwarf Canadian deployment by an order of magnitude, while European hospital networks lag in connected adherence infrastructure adoption.
United States
Integrated delivery networks in Texas and Florida are consolidating pharmacy informatics procurement for enterprise-scale medication management platforms. FDA digital health guidance and CMS remote therapeutic monitoring reimbursement codes are reshaping provider certification requirements and billing eligibility. The Greater Boston cluster anchors specialty pharmacy adherence coaching unbundling from dispensing operations.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia are piloting Bluetooth-enabled pill sensors for post-acute care transitions. EMA medical device regulation and GDPR data transmission requirements impose compliance burdens on adherence app developers. The Berlin-Brandenburg corridor concentrates digital health startups seeking CE marking for behavioral intervention algorithms.
United Kingdom
NHS integrated care systems in London and the Midlands are evaluating medication adherence platforms for polypharmacy populations. MHRA software-as-medical-device guidance influences R&D investment allocation between diagnostic claims and general wellness positioning. The Cambridge-Oxford health tech cluster hosts vendors navigating premarket notification requirements.
Japan
Super-aging municipalities in Kanagawa and Aichi prefectures are deploying smart pill bottles for dependent elderly medication protocols. PMDA pharmaceutical regulation and METI digital health initiatives shape reimbursement pathways for connected adherence devices. The Tokyo-Kanto corridor concentrates hospital system procurement decisions for EMR-native adherence architectures.
India
Corporate hospital chains in Maharashtra and Karnataka are adopting adherence apps for chronic disease management programs. CDSCO medical device rules and the government's digital health mission create certification frameworks for remote therapeutic monitoring solutions. The Hyderabad-Telangana cluster anchors pharmaceutical distribution platforms embedding adherence analytics.
Medication Adherence Market Vendor Landscape
Top-tier vendors anchor hospital-centric automated dispensing infrastructure, while mid-tier specialists compete on behavioral intervention algorithms and API connectivity. The vendor base stratifies across three archetypes: distribution-integrated conglomerates, hardware-automation specialists, and software-native digital health platforms. Consolidation pressures favor enterprise-scale medication management systems with native EMR architectures. Dominant competitive moves include strategic partnerships with integrated delivery networks and portfolio diversification into remote therapeutic monitoring reimbursement workflows.
Within the distribution-integrated tier, McKesson Corporation and Cardinal Health exemplify pharmaceutical supply chain incumbents embedding adherence analytics within existing procurement relationships. Koninklijke Philips N.V. occupies a position among hardware-automation specialists leveraging consumer health device expertise for connected pill sensor deployment. Omnicell, Inc. anchors the hospital-automation archetype through automated dispensing infrastructure that dominates pharmacy informatics procurement at merged United States health systems.
| Leading Market Players |
|---|
| Omnicell, Inc. |
| Cardinal Health |
| McKesson Corporation |
| AdhereTech |
| DrFirst |
| Medminder Systems, Inc. |
| Koninklijke Philips N.V. |
| AARDEX Group |
| Medisafe |
| Others |
Supply Flow & Price Mechanics
United States integrated delivery networks command enterprise licensing negotiations that compress SaaS pricing tiers toward volume-based contract structures. Hospital system consolidation concentrates procurement leverage, forcing adherence platform vendors to unbundle behavioral intervention modules from core medication management systems.
Pricing Analysis
The bundled-versus-unbundled service split separates enterprise medication management platforms from standalone adherence apps. Three-tier pricing structure across premium, standard, and economy levels reflects EMR integration depth and FDA software-as-medical-device certification status. Price differentiation hinges on HIPAA audit trail sophistication and CMS remote therapeutic monitoring billing code eligibility. Cost compression in the smart pill bottle hardware tier intensifies because Chinese sensor suppliers drive component costs toward commodity levels. Medicaid managed care plans exhibit highest price sensitivity, while specialty pharmacies seeking compliance coaching unbundling demonstrate lowest.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific electronics corridors pressures landed costs for Bluetooth-enabled pill sensors and accelerometer components. Manufacturing concentrates in China, South Korea, and Taiwan for MEMS sensors, cellular modems, and lithium battery cells. Raw material dependencies span rare earth elements for magnetometers, medical-grade plastics for pill bottle housings, and semiconductor wafers for processing units. Single-source vulnerability in Bluetooth chipset supply creates exposure to foundry allocation decisions. Distribution runs through pharmaceutical wholesalers and direct-to-hospital contracts for enterprise platforms, with consumer devices flowing through retail pharmacy and e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in medication adherence rests on API standardization reducing integration overhead and specialty pharmacy unbundling creating premium service tiers.
For Market Incumbents: Extend automated dispensing infrastructure into remote therapeutic monitoring reimbursement workflows before pharmacy benefit managers consolidate compliance coaching capabilities. Deepen backward integration into Bluetooth sensor module production to offset Chinese supplier pricing volatility. Anchor hospital system partnerships through native EMR architectures that raise switching costs for rival platforms. For New Entrants and Emerging Players: The gap between premium enterprise licensing and economy reminder apps opens white-space at the mid-market integrated delivery network tier. Target Medicaid managed care plans in Texas and Florida seeking polypharmacy intervention tools with limited IT procurement staff. Pursue white-label partnerships with specialty pharmacies unbundling adherence coaching from dispensing operations. For Investors and Strategic Acquirers: Pharmacy benefit managers are the most active acquirer in this space, seeking data monetization platforms for risk-scoring products. Long-term viability favors vendors with FDA software-as-medical-device clearance depth and CMS reimbursement code alignment. Monitor CMS proposals to extend remote therapeutic monitoring beyond respiratory and musculoskeletal categories as the decisive demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CMS Reimbursement Strategy | Remote therapeutic monitoring code expansion unlocks cardiovascular and diabetes adherence program revenue streams. |
| Hospital System Partnership | Integrated delivery network consolidation in Texas and Florida centralizes procurement for EMR-native architectures. |
| Software Companion Development | FDA software-as-medical-device guidance demands rigorous evidence generation for behavioral intervention claims. |
| CE Marking Pathway | EMA medical device regulation and GDPR compliance burden adherence app developers seeking European market entry. |
| Platform Integration | Open health API connectivity reduces deployment friction for health systems seeking behavioral intervention tools. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining executive interviews with hospital pharmacy informatics directors, specialty pharmacy operations leads, CMS reimbursement policy specialists, and digital health platform CTOs. Secondary validation draws from FDA 510(k) filings, CMS Medicare Physician Fee Schedule updates, hospital procurement databases, and GPO contract repositories. Bottom-up and top-down triangulation cross-checks device shipment data against enterprise licensing disclosures.
Rate-of-change decomposition separates volume growth from pricing trajectory across the analysis window. Segmentation dimensions model product type, therapy area, end user, and delivery mode, with regulatory pathway status as an industry-specific overlay. CAGRs derive from trend extrapolation of CMS reimbursement expansion scenarios and integrated delivery network merger pipelines. Forecast inputs incorporate smartphone penetration curves and EMR vendor API roadmap disclosures.
Caveats apply where CMS remote therapeutic monitoring scope expansion delays or FDA software-as-medical-device reclassification actions could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Immunotherapy Drugs Market
Pharmacology
Aldosterone Receptor Antagonists Market
Pharmacology
Influenza Medication Market
Pharmacology
Angiotensin II Receptor Blockers (Arbs) Market
Pharmacology
Apixaban Market
Pharmacology
Cough Remedies Market
Pharmacology
Hyperkalemia Drugs Market
Pharmacology
Drug Delivery Across the Blood-Brain Barrier Market
Pharmacology
Global Migraine Therapeutics Market
Pharmacology
Anti-Asthma Drugs Market
Pharmacology
Olanzapine API Market
Pharmacology
Semaglutide API Market
Pharmacology
Pegylated Drugs Market
Pharmacology
Clot Busting Drugs Market
Pharmacology
Ketoprofen API Market
Pharmacology
Antihyperlipidemic Drugs Market