
 Propranolol Drug Market | 2026-2036
Propranolol Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Propranolol Drug Market Analytics
The propranolol market is repositioning around a widening split between premium extended-release formulations and commodity immediate-release generics. Sanofi leverages its cardiovascular heritage to sustain brand loyalty among specialist prescribers, while Teva Pharmaceutical Industries Ltd. anchors the generic segment through manufacturing scale and FDA-approved abbreviated new drug applications. Apotex Inc. competes aggressively on price, extending its North American distribution footprint to capture pharmacy benefit manager formulary placements.
Propranolol hydrochloride is a non-selective beta-adrenergic antagonist with a molecular weight of 295.8 g/mol, formulated as racemic mixtures where the S-enantiomer provides the majority of beta-blocking activity; it functions by antagonizing beta-1 and beta-2 receptors to reduce heart rate, myocardial contractility, and vascular resistance. The tablets segment dominates volume due to decades of clinical familiarity and stable reimbursement, while the injectable category occupies the acute care margin pool where hospital formulary premiums apply. Anxiety disorders applications are growing fastest among indications as psychiatrists expand off-label prescribing beyond traditional cardiac and migraine prophylaxis uses.
FDA bioequivalence requirements govern generic substitution and shape manufacturer R&D allocation toward formulation differentiation, while the EPA and OSHA frameworks regulate active pharmaceutical ingredient synthesis waste streams and worker exposure limits at production facilities. The EU's REACH and MDR frameworks constrain excipient sourcing and device-drug combination labeling for European market entrants. Stakeholders must monitor how tightening environmental compliance costs at API manufacturing sites in India and China reshape cost structures for generic producers.
Market Dynamics
The propranolol market is splitting along formulation lines as FDA bioequivalence standards tighten and India's PLI scheme redirects bulk API synthesis toward domestic production, compressing margins for import-dependent generic manufacturers.
Growth Catalysts
- Off-label anxiety prescribing:Psychiatrists in the United States are expanding propranolol's prescriber base beyond cardiology into performance anxiety and generalized anxiety disorder applications.
- India's PLI scheme for APIs:Production-linked incentives for active pharmaceutical ingredients are redirecting bulk synthesis toward domestic Indian manufacturing, reducing import dependency.
- Extended-release formulation premiums:Differentiated delivery technologies command hospital formulary placement and specialist loyalty against commodity immediate-release alternatives.
Market Restraints
- API supply concentration:Bulk propranolol hydrochloride synthesis concentrates in Indian and Chinese chemical parks, exposing formulators to single-source disruption risk.
- EPA and OSHA compliance costs:Waste stream regulations and worker exposure limits at API manufacturing facilities are elevating environmental remediation expenditures.
- Generic substitution pressure:FDA abbreviated new drug application pathways enable rapid bioequivalent entry, eroding brand pricing power in hypertension treatment.
Strategic Opportunities
- Device-drug combinations:European MDR framework convergence with combination product pathways creates labeling clarity for novel delivery systems in migraine prophylaxis.
- Injectable acute care expansion:Hospital formulary premiums for parenteral beta-blockade in perioperative settings offer margin protection against oral generic commoditization.
- REACH-compliant excipient sourcing:EU chemical registration requirements are favoring suppliers with pre-registered polymer and coating material portfolios.
Industry Challenges
- Racemic mixture separation complexity:S-enantiomer purification for targeted beta-1 selectivity requires chromatographic infrastructure that mid-scale API producers lack.
- Formulation stability validation:Extended-release matrix technologies demand accelerated aging studies that compress development timelines for abbreviated new drug applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Propranolol Drug Market |
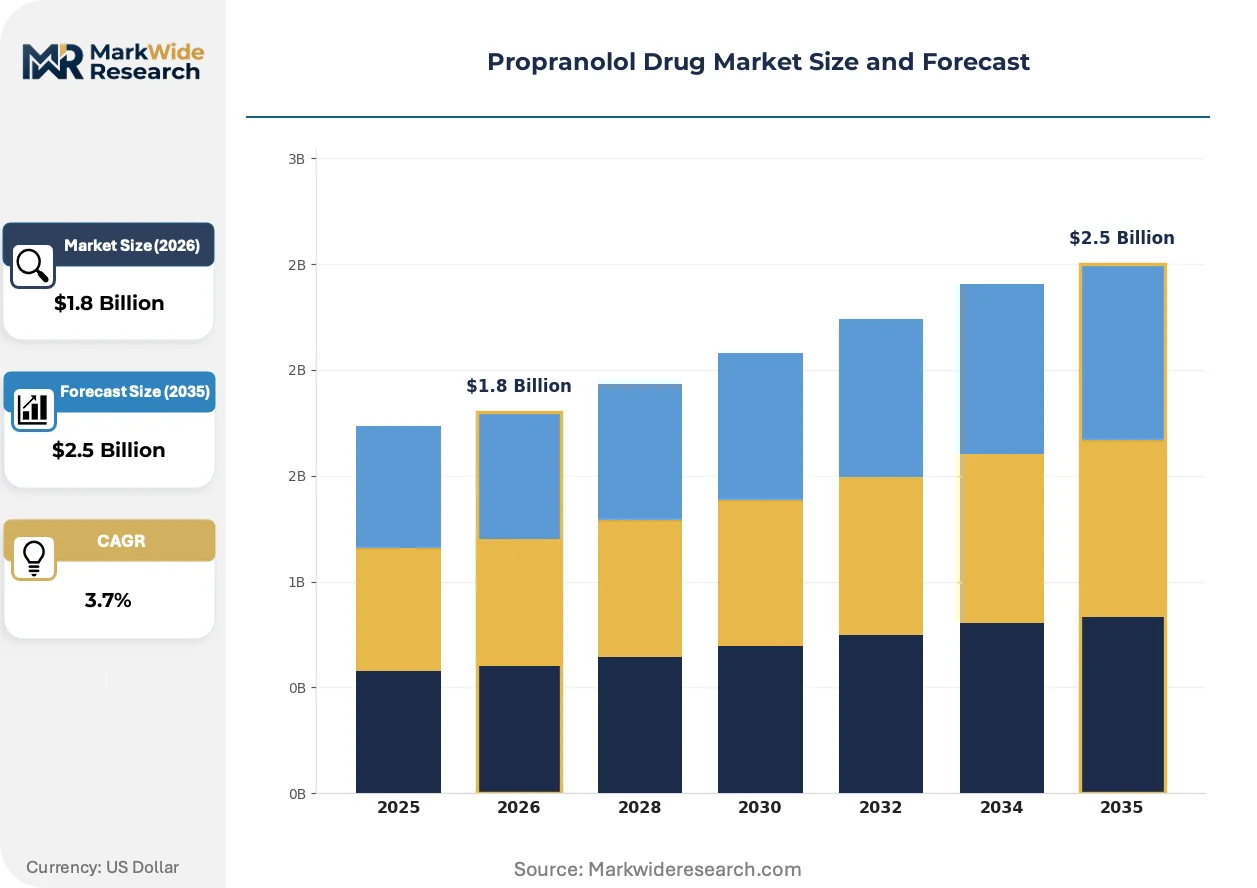
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injectable, Oral Solution Application: Anxiety Disorders, Hypertension, Migraines, Cardiac Arrhythmias End User: Hospitals, Clinics, Homecare, Pharmacies Delivery Mode: Oral, Intravenous, Subcutaneous, Topical |
| Companies Covered | Sanofi, Teva Pharmaceutical Industries Ltd., Apotex Inc., Atnahs Pharma, Viatris, Novartis, AstraZeneca, Lupin Limited, Zydus Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Propranolol Drug Market Evolving Landscape
Formulation science and regulatory chemistry are reshaping competitive differentiation as manufacturers seek escape velocity from immediate-release generic commoditization through delivery technology and indication expansion.
Extended-release matrix technologies are converging with hydrophilic polymer coating systems to enable once-daily dosing profiles that match branded cardiovascular regimens. Cardiology practices in Germany and the United States are adopting these formulations for hypertension maintenance therapy. The technology is compressing reimbursement differentiation between originator and high-barrier generic entrants.
REACH and MDR frameworks in Europe are tightening excipient traceability and device-drug combination labeling requirements for market authorization holders. Manufacturers must now document polymer biocompatibility and leachable profiles for novel coating materials. Injectable presentations and combination delivery systems face the steepest compliance cost escalations, favoring sponsors with established European regulatory affairs capabilities.
Psychiatrists are unbundling performance anxiety prescribing from traditional cardiology referral pathways, creating direct-to-specialist demand channels that bypass primary care gatekeeping. Telehealth platforms in the United States are facilitating this channel disintermediation through asynchronous prescription workflows. Anxiety disorder applications now represent the fastest-expanding prescriber base outside established cardiac and migraine prophylaxis indications.
Propranolol Drug Market Segmentation
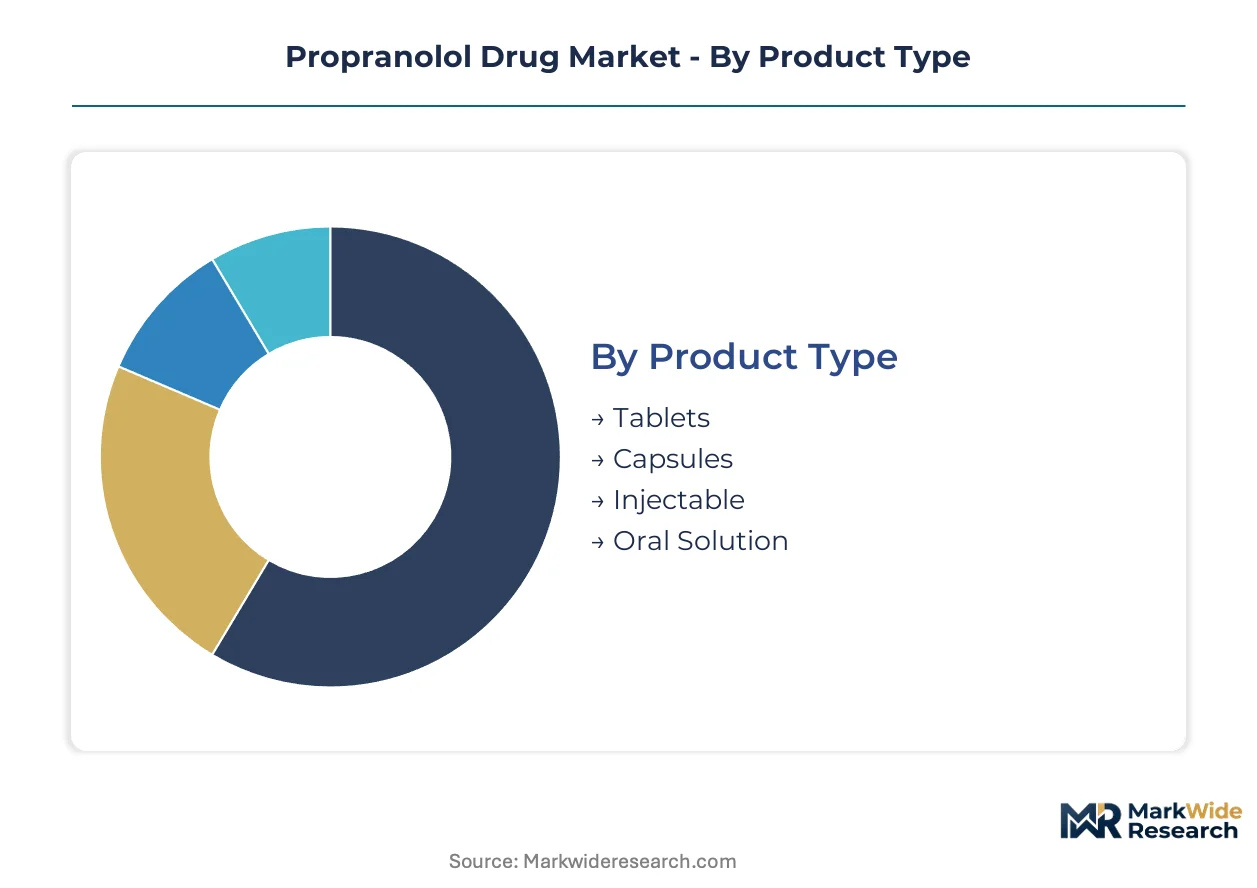
Formulation differentiation and prescriber channel expansion are fragmenting propranolol's commercial landscape into distinct margin pools. Each segmentation dimension reveals divergent growth trajectories between commoditized immediate-release generics and premium delivery technologies.
Product Type:
Replacement cycles favor extended-release platforms over legacy immediate-release formats as formulary committees prioritize adherence economics.
- Tablets:Immediate-release and extended-release matrix formulations dominate outpatient prescribing due to decades of clinical familiarity and stable pharmacy benefit manager reimbursement. Volume concentrates in the United States where off-label anxiety applications bypass cardiology gatekeeping.
- Injectable:Parenteral propranolol hydrochloride commands acute care premiums in perioperative and emergency settings where rapid beta-blockade is critical. Hospital formulary placement in Germany and the United States protects margins against oral generic commoditization.
- Capsules:Gelatin and HPMC shells enable modified-release profiles with polymer coating differentiation.
- Oral Solution:Liquid formulations serve pediatric and geriatric populations with swallowing difficulties.
Volume placements concentrate in tablets; the faster expansion belongs to injectable.
Application:
Cost tier stratification separates premium psychiatric prescribing from commodity cardiovascular maintenance therapy.
- Anxiety Disorders:Performance anxiety and generalized anxiety disorder applications are expanding fastest as psychiatrists unbundle prescribing from traditional cardiology referral pathways. Telehealth platforms in the United States facilitate direct-to-specialist demand channels.
- Hypertension:Beta-blockade for blood pressure control faces intense generic substitution pressure under FDA abbreviated new drug application pathways.
- Migraines:Prophylactic use in episodic migraine management maintains steady neurology clinic volumes.
- Cardiac Arrhythmias:Arrhythmia control applications concentrate in hospital-based electrophysiology practices with specialist loyalty to extended-release brands.
Volume placements concentrate in hypertension; the fastest expansion trajectory belongs to anxiety disorders.
End User:
Customer type determines pricing power across institutional procurement versus retail pharmacy substitution dynamics.
- Hospitals:Acute care settings capture parenteral formulation premiums through group purchasing organization negotiations and perioperative protocol standardization.
- Clinics:Outpatient cardiology and neurology practices anchor extended-release prescribing with specialist formulary influence.
- Homecare:Long-term maintenance therapy for chronic conditions drives mail-order pharmacy volume with 90-day supply economics.
- Pharmacies:Retail channels face the steepest generic substitution pressure with pharmacy benefit manager tiered copay structures favoring lowest-cost bioequivalent options.
Volume placements concentrate in pharmacies; the steepest expansion trajectory belongs to homecare.
Delivery Mode:
Supply concentration in oral formats is displacing investment toward alternative pharmacokinetic profiles.
- Oral:Gastrointestinal absorption of propranolol hydrochloride enables convenient outpatient management with first-pass metabolism determining bioavailability profiles.
- Intravenous:Direct vascular administration achieves rapid therapeutic levels in acute cardiac and perioperative settings where oral intake is contraindicated.
- Subcutaneous:Depot injection technologies for sustained beta-blockade remain experimental with limited commercial availability.
- Topical:Transdermal delivery systems for localized hemangioma treatment in pediatric populations occupy niche dermatology applications.
Volume placements concentrate in oral delivery; the gaining share fastest belongs to intravenous.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad anchors API synthesis for propranolol hydrochloride, with Indian chemical parks supplying bulk intermediates to formulation sites across Germany, the United States, and Japan.
United States
Off-label anxiety prescribing through telehealth platforms is expanding psychiatrist access beyond cardiology gatekeeping. FDA abbreviated new drug application pathways accelerate generic substitution in hypertension therapy. New Jersey and North Carolina host major formulation facilities serving domestic pharmacy benefit manager networks.
Germany
Cardiology practices in Bavaria and Baden-Württemberg adopt extended-release matrix formulations for hypertension maintenance. EU MDR and REACH frameworks constrain excipient sourcing and device-drug combination labeling. Frankfurt-Rhine-Main corridor concentrates regulatory affairs capabilities for European market authorization.
India
CDSCO oversight and PLI scheme incentives redirect bulk API production toward domestic synthesis in Telangana and Gujarat. Hyderabad-Visakhapatnam chemical corridor reduces import dependency for propranolol hydrochloride intermediates. Formulation exporters in Maharashtra leverage cost advantages for North American and European supply contracts.
Japan
PMDA maintains stringent bioequivalence standards for generic beta-blocker substitution in cardiac arrhythmia management. Kansai region formulation specialists serve aging population demand for chronic cardiovascular therapy. Osaka-Tokyo distribution channels prioritize extended-release adherence economics in national health insurance reimbursement.
United Kingdom
NHS formulary committees balance immediate-release generic cost containment against extended-release premium positioning. MHRA post-Brexit regulatory autonomy shapes divergence from EMA centralized procedures. Greater Manchester and Cambridge clusters host pharmacovigilance operations for European market surveillance.
Propranolol Drug Market Competitive Landscape
Capital-heavy API producers compete with asset-light formulation specialists across the propranolol value chain. The market structures around three tiers: originator brands with cardiovascular heritage, scaled generic manufacturers with FDA-approved abbreviated new drug applications, and regional API-to-formulation integrators. Strategic archetypes include patent-era incumbents defending specialist prescriber loyalty, volume-driven generic houses capturing pharmacy benefit manager placements, and backward-integrated Indian producers exploiting PLI scheme cost advantages. Dominant competitive moves center on extended-release formulation differentiation and geographic expansion into anxiety disorder prescribing channels.
Among heritage pharmaceutical houses, Sanofi occupies a position exemplifying brand persistence in cardiology specialist networks. Teva Pharmaceutical Industries Ltd. and Apotex Inc. represent the scaled generic tier, with the former anchoring manufacturing volume and the latter exemplifying aggressive price competition for North American formulary access. These three entities collectively illustrate the market's tripartite segmentation between premium brand positioning, manufacturing scale, and price-driven commodity supply.
| Leading Market Players |
|---|
| Sanofi |
| Teva Pharmaceutical Industries Ltd. |
| Apotex Inc. |
| Atnahs Pharma |
| Viatris |
| Novartis |
| AstraZeneca |
| Lupin Limited |
| Zydus Pharma |
| Others |
Value Network & Pricing Analysis
Backward integration into API synthesis anchors pricing power for Indian producers leveraging PLI scheme incentives, while import-dependent formulators absorb margin compression from single-source exposure. This structural divide separates captive supply advantages from tariff-vulnerable procurement positions.
Pricing Analysis
Value-based pricing anchors on clinical outcome differentiation between extended-release matrix formulations and commodity immediate-release tablets. Three-tier pricing structure across premium extended-release, standard branded generic, and economy bioequivalent tiers reflects FDA certification stratification. Cost compression in the immediate-release segment intensifies because Teva and Apotex compete aggressively for pharmacy benefit manager formulary placement. Hospital procurement committees show least price sensitivity for perioperative injectable presentations, while retail pharmacies face steepest substitution pressure.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and Indian chemical parks supplying bulk propranolol hydrochloride intermediates. Raw material dependencies center on naphthol derivatives, isopropylamine, and specialized solvent recovery systems. Tariff exposure on API imports from Hyderabad-Visakhapatnam corridor feeds into formulation cost structures for North American generic houses. Distribution runs through group purchasing organizations for hospital injectables and pharmacy benefit manager networks for outpatient oral formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The propranolol market is transitioning from racemic mixture commoditization toward enantiomer-selective synthesis and device-drug combination platforms. Extended-release matrix technologies and S-enantiomer purification capabilities are displacing legacy immediate-release manufacturing.
For Market Incumbents: Lock in specialist prescriber loyalty through extended-release formulation differentiation and migraine prophylaxis device-drug combination pipelines. Defend against generic substitution pressure by securing hospital formulary placement for perioperative injectable presentations. Prioritize backward integration into PLI scheme-eligible API synthesis to neutralize import cost volatility. For New Entrants and Emerging Players: Capture telehealth-enabled psychiatry prescribing channels for performance anxiety applications outside traditional cardiology gatekeeping. Target anxiety disorder segments in United States metropolitan markets with asynchronous prescription platform partnerships. Pursue FDA abbreviated new drug application pathways for bioequivalent extended-release matrices to bypass originator formulation patents. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale API-to-formulation integrators with CDSCO-compliant Indian manufacturing assets and European REACH-registered excipient portfolios. Long-term viability hinges on racemic separation infrastructure and MDR-compliant combination product capabilities. Watch FDA bioequivalence guidance revisions as inflection signals for generic substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Matrix Development | Once-daily dosing profiles match branded cardiovascular regimens in German and United States cardiology practices. |
| S-Enantiomer Purification Investment | Chromatographic infrastructure enables targeted beta-1 selectivity beyond commodity racemic mixture supply. |
| PLI Scheme API Manufacturing Scale-Up | Domestic Indian synthesis reduces import dependency for propranolol hydrochloride intermediates under CDSCO oversight. |
| Device-Drug Combination Regulatory Pathway | European MDR convergence creates labeling clarity for novel migraine prophylaxis delivery systems. |
| Telehealth Platform Partnership | Asynchronous prescription workflows expand psychiatrist access for performance anxiety applications beyond cardiology referral. |
Research Methodology
Independent corroboration across regulatory submissions, pharmaceutical trade data, and hospital procurement records underwrites the qualitative findings. Primary interviews with regulatory affairs leads, formulary directors, and API manufacturing executives combined with secondary validation from FDA filings, EMA submissions, and CDSCO manufacturing facility inspections. Bottom-up volume modeling and top-down value reconciliation anchored the market sizing across the analysis window.
Rate-of-change decomposition separated volume growth from pricing dynamics across formulation type, application indication, and regional regulatory cluster. The analytical framework modeled extended-release versus immediate-release substitution patterns, anxiety disorder prescribing expansion, and injectable acute care penetration. CAGRs derived from segment-level growth trajectory blending and cross-reference to historical beta-blocker lifecycle patterns. Industry-specific inputs included FDA abbreviated new drug application approval timelines and PLI scheme capacity addition schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA bioequivalence standard revisions and EPA waste stream compliance cost escalations at API manufacturing sites. Forecasts reflect assumptions about psychiatrist prescribing behavior normalization and European MDR implementation pacing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Attention Deficit Hyperactivity Disorder (ADHD) Therapeutics Market
Pharmacology
Injectable Drugs Market
Pharmacology
ACE Inhibitors Market
Pharmacology
Global Geriatric Medicines Market
Pharmacology
Global Migraine Therapeutics Market
Pharmacology
Clot Busting Drugs Market
Pharmacology
Aldosterone Receptor Antagonists Market
Pharmacology
Hypertension Drug Market
Pharmacology
Antithrombotic Drugs Market
Pharmacology
Global Olanzapine Market
Pharmacology
Huoxiang Zhengqi Drug Market
Pharmacology
Cough Remedies Market
Pharmacology
Global Asthma Therapeutics Market
Pharmacology
Autacoids and Related Drugs Market
Pharmacology
Olanzapine API Market
Pharmacology
Thromboprophylactic Drugs Market