
 Cough Remedies Market | 2026-2036
Cough Remedies Market Size, Share, and Industry Trends Forecast 2026-2036
Cough Remedies Market Outlook
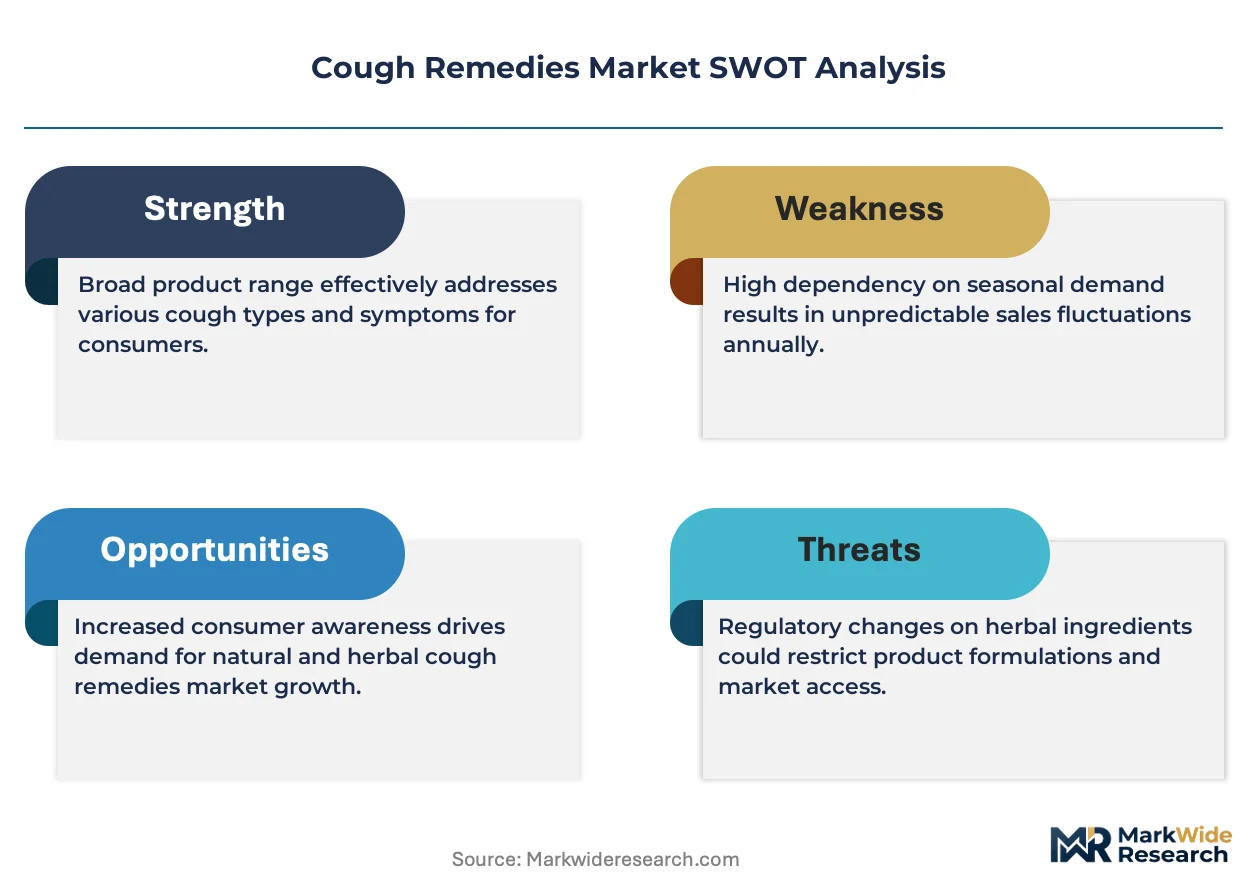
OTC monograph reform is expanding the cost-of-entry calculus for cough remedy manufacturers seeking FDA compliance. Johnson & Johnson leverages its pharmacy channel control to sustain shelf dominance across retail chains. GlaxoSmithKline anchors its position through R&D intensity in pediatric formulations. Reckitt Benckiser Group differentiates via brand strength in the seasonal allergies segment.
Cough remedies comprise pharmacological and non-pharmacological formulations designed to suppress or expectorate respiratory tract irritants, typically containing dextromethorphan, guaifenesin, or herbal actives in liquid, solid, or aerosolized delivery systems. Their primary commercial purpose centers on symptomatic relief of acute and chronic cough across consumer and clinical settings. The OTC medications category dominates volume as households self-treat routine respiratory episodes, while herbal remedies capture premium margin pools among consumers seeking natural alternatives. Pediatric care applications command higher unit economics due to formulation complexity and safety testing requirements, whereas liquid formulations lead delivery mode preferences for children and elderly populations.
The FDA enforces OTC monograph standards that dictate active ingredient concentrations and labeling requirements, directly shaping product development timelines and reformulation costs. EMA's MDR and REACH frameworks in Europe impose additional toxicology and environmental compliance burdens on manufacturers exporting to multiple jurisdictions. WHO guidelines on essential medicines influence national formulary inclusion decisions across emerging markets. Stakeholders must monitor evolving monograph updates and pediatric safety advisories to anticipate reformulation investments and geographic portfolio prioritization.
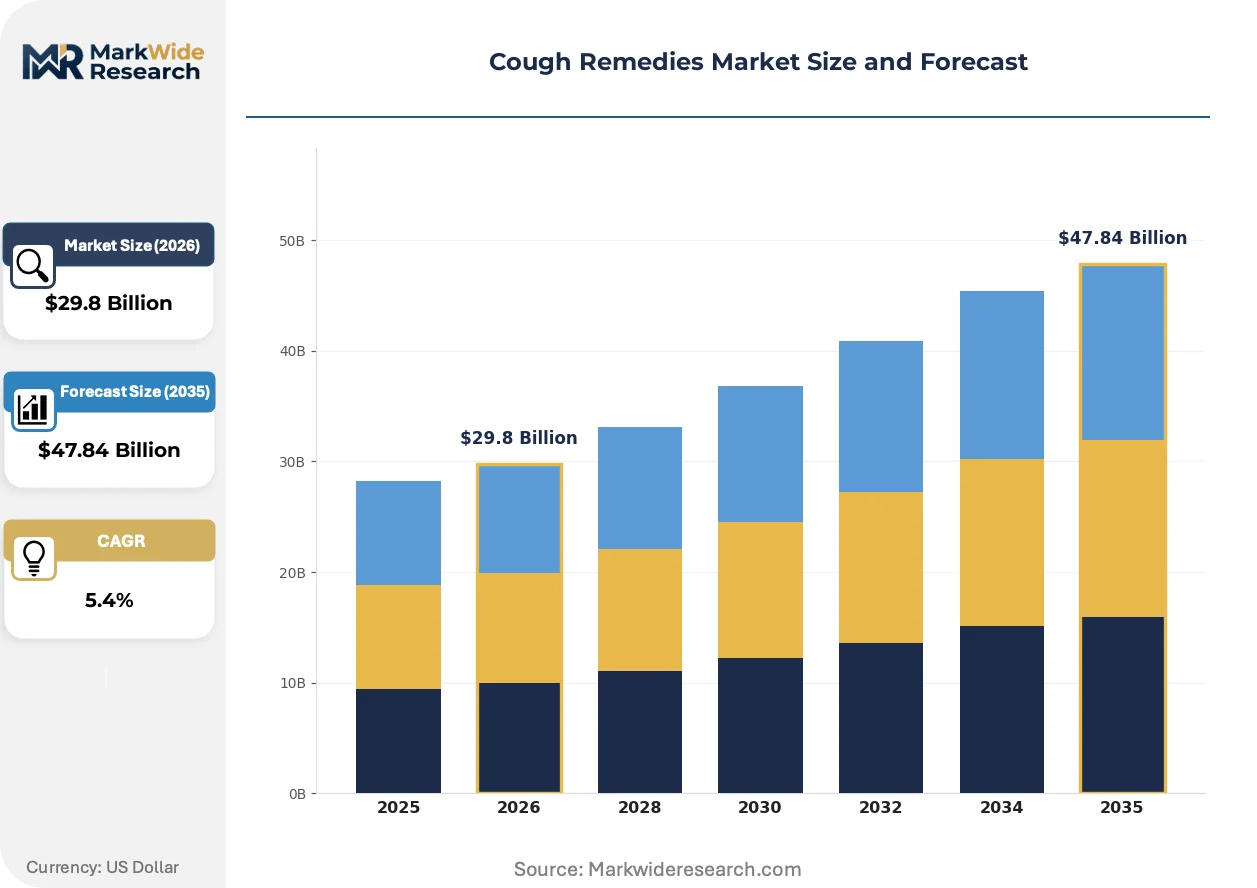
Market Dynamics
The FDA's OTC monograph reform is compressing product development timelines while simultaneously elevating compliance costs for dextromethorphan and guaifenesin formulations across all manufacturer tiers.
Growth Catalysts
- Pediatric formulation complexity:Parents in the United States increasingly favor non-prescription options for children, creating sustained pull for specialized liquid delivery systems with enhanced safety testing.
- REACH environmental frameworks:European manufacturers advancing green chemistry credentials capture premium positioning among environmentally conscious pharmacy chains and institutional buyers.
- Herbal active convergence:Traditional medicine systems in India and China are validating botanical cough suppressants through modern toxicology studies, opening regulatory pathways previously blocked by monograph restrictions.
Market Restraints
- API supply concentration:Dextromethorphan precursor chemicals concentrate among Chinese chemical manufacturers, exposing formulators to input volatility and geopolitical trade friction.
- Monograph reformulation costs:The FDA's tightened active ingredient standards force simultaneous label revisions and stability testing across entire product portfolios.
- Natural remedy substitution:Honey-based and saline nebulization alternatives gain traction among consumers skeptical of synthetic actives, eroding baseline demand for conventional suppressants.
Strategic Opportunities
- Sub-Saharan Africa underpenetration:WHO essential medicines list inclusion creates procurement pathways for basic expectorants in Nigeria, Kenya, and Ghana where pharmacy infrastructure is expanding.
- Elderly polypharmacy formulations:Combination products addressing cough plus cardiovascular or diabetic comorbidities address unmet need in Japan's aging demographic.
- Direct-to-consumer telehealth integration:Pharmacy chains in the United States are building cough remedy subscriptions into virtual care platforms, capturing recurring revenue beyond acute episodes.
Industry Challenges
- Pediatric toxicology expertise scarcity:Formulation scientists capable of designing age-appropriate dosing matrices with abuse-deterrent properties command premium compensation and extended recruitment cycles.
- Cross-jurisdiction label harmonization:Simultaneous compliance with FDA pregnancy category requirements, EMA pediatric investigation plans, and Health Canada bilingual mandates fragments regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cough Remedies Market |
| Market Size in 2026 | $29.8 Billion |
| Market Size in 2035 | $47.84 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OTC Medications, Herbal Remedies, Cough Syrups, Lozenges Application: Non-Prescription, Pediatric Care, Adult Care, Seasonal Allergies Delivery Mode: Liquid Formulations, Tablets, Inhalers, Sprays End User: Households, Pharmacies, Hospitals, Clinicians |
| Companies Covered | Johnson & Johnson, Pfizer, GlaxoSmithKline, Reckitt Benckiser Group, Bayer, Sanofi, Novartis, Procter & Gamble, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cough Remedies Market Strategic Shifts
Delivery system miniaturization and bioavailability engineering are redefining efficacy benchmarks while regulatory digitization accelerates approval pathway fragmentation across major jurisdictions.
Microencapsulation technology for sustained-release dextromethorphan is overtaking immediate-release tablets in pharmacy chain formularies. Pediatric and elderly patient segments are driving adoption due to reduced dosing frequency and improved nighttime symptom control. This shift is compressing margins for commodity liquid manufacturers while rewarding R&D-intensive players with patent-protected delivery platforms.
EMA's Medical Device Regulation (MDR) reclassification is forcing nebulizer-cough remedy combination products through notified body conformity assessments previously exempt under pharmaceutical pathways. Manufacturers must now maintain dual technical files bridging drug and device quality systems. German and French pharmacy distributors are demanding MDR compliance documentation before shelf placement, filtering out smaller exporters.
Subscription-based replenishment models are displacing acute purchase patterns among urban households with chronic respiratory conditions. Pharmacy chains in the United States are bundling cough remedies with seasonal allergy prophylaxis into auto-ship programs. This behavioral shift concentrates volume with retail platforms possessing logistics infrastructure, marginalizing independent drugstores lacking digital fulfillment capabilities.
Cough Remedies Market Segmentation
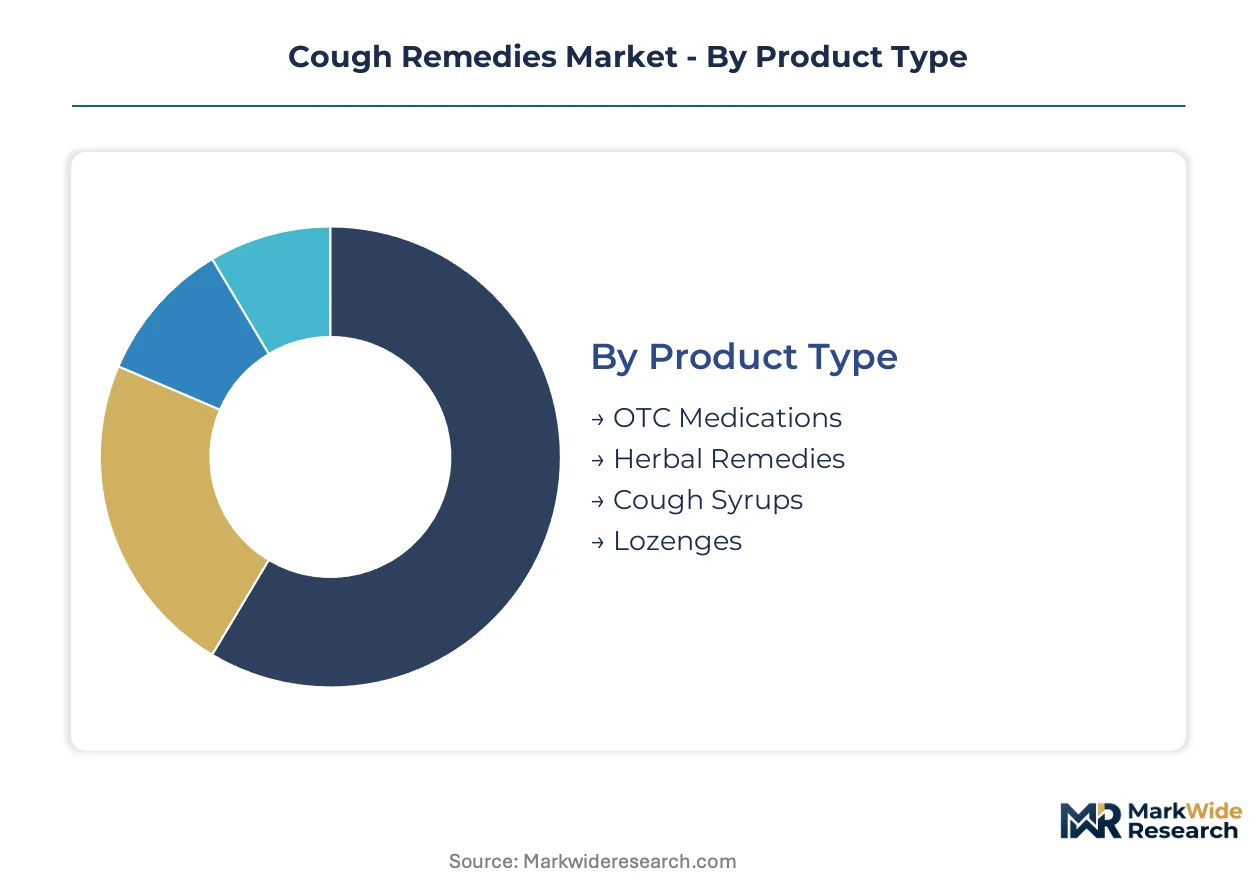
Formulation complexity and regulatory pathway requirements determine margin capture across cough remedy categories. Manufacturers must align R&D investment with the specific compliance burdens and consumer price sensitivity inherent to each segment structure.
Product Type:
Households select product types based on symptom severity, speed of relief required, and trust in active ingredient transparency.
- OTC Medications:Synthetic formulations containing dextromethorphan, guaifenesin, or combination actives dominate pharmacy chain shelf space. FDA monograph compliance costs concentrate volume among established manufacturers with dedicated regulatory affairs teams in the United States.
- Herbal Remedies:Botanical actives including ivy leaf extract, marshmallow root, and thyme extract command premium positioning. REACH environmental credentials and organic certification requirements in Germany and France filter out commodity suppliers lacking green chemistry documentation.
- Cough Syrups:Liquid delivery systems with viscosity-optimized flow characteristics target pediatric and elderly swallowing difficulties. Sugar-free and alcohol-free variants address diabetic and pediatric safety constraints.
- Lozenges:Sustained-release mucoadhesive formulations provide localized demulcent action for throat irritation. Portability drives impulse purchase patterns in convenience retail channels.
OTC Medications leads on scale; Herbal Remedies leads on momentum.
Application:
Patient age and prescription status create divergent formulation requirements and pricing power.
- Non-Prescription:Self-treatment of acute cough episodes drives volume through retail pharmacy and e-commerce channels. Label comprehension requirements limit complexity in multi-symptom combinations.
- Pediatric Care:Age-appropriate dosing matrices with abuse-deterrent properties and palatability engineering command specialized toxicology expertise. FDA pediatric safety advisories trigger reformulation cycles unavailable to smaller manufacturers.
- Adult Care:Polypharmacy considerations in aging populations necessitate interaction screening with cardiovascular and diabetic medications. Unit economics favor larger pack sizes and subscription replenishment models.
- Seasonal Allergies:Antihistamine-cough suppressant combinations address post-nasal drip etiology. Pollen forecasting integration in pharmacy loyalty programs drives pre-season stocking behavior.
Non-Prescription captures the volume base; Pediatric Care captures the margin premium.
Delivery Mode:
Patient adherence and caregiver administration convenience dictate formulation technology selection.
- Liquid Formulations:Suspension and solution technologies with dose-calibrated measuring devices dominate pediatric prescribing. Viscosity modifiers and flavor masking systems require specialized excipient sourcing.
- Tablets:Immediate-release and sustained-release solid dosage forms optimize supply chain efficiency through stability and transport density. Microencapsulation patents differentiate R&D-intensive players from commodity manufacturers.
- Inhalers:Nebulizer-compatible and metered-dose formulations target lower respiratory tract deposition. EMA MDR reclassification forces dual drug-device quality system compliance.
- Sprays:Topical oropharyngeal delivery provides rapid onset for acute symptom relief. Propellant selection faces REACH environmental scrutiny in European markets.
Tablets dominate manufacturing efficiency; Liquid Formulations dominate clinical preference for vulnerable populations.
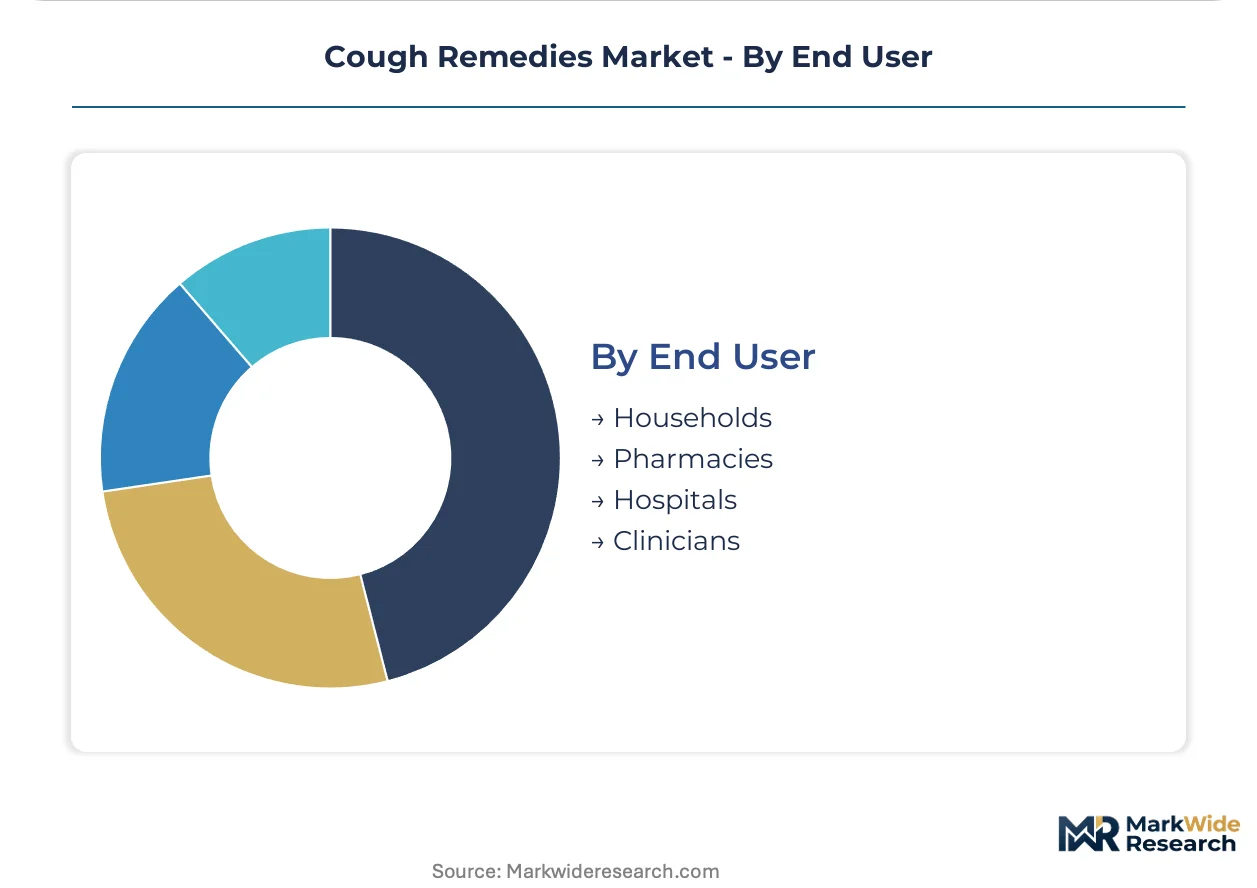
End User:
Purchase authority and reimbursement pathway determine channel strategy and pricing architecture.
- Households:Direct-to-consumer transactions through retail pharmacy, mass merchandisers, and e-commerce platforms. Subscription auto-ship programs capture chronic condition households in the United States.
- Pharmacies:Professional recommendation influence and formulary placement drive brand selection. Chain procurement consolidation concentrates volume with suppliers offering direct-to-warehouse logistics.
- Hospitals:Formulary committee governance and group purchasing organization contracts prioritize unit-dose packaging and interaction databases. Short shelf-life liquid formulations face inventory management constraints.
- Clinicians:Prescription authority for compounded or restricted formulations influences off-label recommendation patterns. Continuing medical education relationships shape brand preference in specialist practices.
Households generate the transaction volume; Hospitals generate the compliance benchmark.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cough remedies industry traces its modern commercial origins to nineteenth-century pharmaceutical manufacturing clusters in Germany and the United States, where standardized extraction of botanical actives first merged with industrial-scale tablet production.
United States
Pharmacy chain consolidation and direct-to-consumer telehealth integration drive procurement concentration toward national distributors with warehouse logistics capabilities. FDA OTC monograph reform mandates simultaneous label revisions across entire portfolios, elevating compliance costs for dextromethorphan formulators. New Jersey-based manufacturing clusters house specialized toxicology laboratories supporting pediatric safety testing requirements.
Germany
Consumer preference for herbal alternatives and green chemistry credentials sustains premium positioning for ivy leaf and thyme extract formulations. EMA MDR reclassification forces nebulizer-cough remedy combinations through notified body conformity assessments previously exempt under pharmaceutical pathways. Bavarian chemical manufacturers advance REACH-compliant excipient sourcing for export markets.
China
Traditional medicine validation through modern toxicology studies opens regulatory pathways for botanical cough suppressants previously blocked by monograph restrictions. NMPA alignment with international stability testing standards accelerates domestic manufacturer export readiness. Yangtze River Delta chemical clusters concentrate dextromethorphan precursor production, exposing formulators to input volatility and trade friction exposure.
India
Household self-treatment culture and expanding pharmacy retail networks drive volume demand for affordable expectorant formulations. CDSCO pediatric safety advisories trigger reformulation cycles that filter out smaller manufacturers lacking dedicated regulatory affairs teams. Gujarat-based API manufacturers supply domestic formulators while building WHO prequalification documentation for African export markets.
Japan
Aging demographic polypharmacy requirements create unmet need for combination products addressing cough plus cardiovascular or diabetic comorbidities. PMDA geriatric formulation guidelines prioritize interaction screening databases and unit-dose packaging for institutional settings. Kansai region pharmaceutical manufacturers specialize in sustained-release delivery platforms for elderly adherence optimization.
Cough Remedies Market Competitive Environment
The competitive structure tilts toward diversified healthcare conglomerates with pharmacy channel control and dedicated pediatric toxicology expertise. Consolidation pressure concentrates volume among established manufacturers maintaining FDA regulatory affairs teams, while smaller herbal specialists capture premium positioning through organic certification. Three archetypes dominate: pharmacy chain-integrated suppliers with direct-to-warehouse logistics, R&D-intensive players with patent-protected delivery platforms, and botanical specialists with REACH environmental credentials. Competitive moves center on M&A for pediatric formulation capabilities and strategic partnerships for telehealth subscription integration.
Within the diversified healthcare conglomerate tier, Johnson & Johnson and GlaxoSmithKline occupy positions reflecting pharmacy channel dominance and R&D intensity in specialized formulations respectively. Reckitt Benckiser Group exemplifies brand-driven positioning in seasonal allergy-cough combination segments. These three entities anchor the competitive landscape through distinct capability configurations rather than overlapping strategic postures.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Pfizer |
| GlaxoSmithKline |
| Reckitt Benckiser Group |
| Bayer |
| Sanofi |
| Novartis |
| Procter & Gamble |
| AstraZeneca |
| Others |
Value Chain & Pricing Dynamics
Pediatric toxicology expertise concentration in New Jersey and Bavaria drives labor-cost differentials that widen pricing-tier spreads between premium pediatric formulations and commodity adult generics. Formulation scientists capable of abuse-deterrent matrix design command compensation premiums that manufacturers pass through to pharmacy chains, while automated liquid-filling operations in Gujarat and the Yangtze River Delta compress economy-tier margins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates patent-protected microencapsulation platforms from FDA-monograph-compliant generics and unbranded liquid commodities. Price differentiation rests on pediatric safety certification tier and pharmacy chain formulary placement rather than raw ingredient cost. Cost compression in the economy tier is intensifying because API precursor volatility from Chinese chemical clusters feeds through to guaifenesin formulators. Household buyers in the non-prescription segment exhibit highest price sensitivity, while hospital procurement committees prioritize interaction database access over unit cost.
Supply Chain Analysis
Direct-to-warehouse channels serving consolidated pharmacy chains handle volume demand for OTC tablet and liquid formulations, while specialty distributors manage temperature-controlled pediatric shipments. API production concentrates in China, India, and Germany, with dextromethorphan precursor chemistry anchored in the Yangtze River Delta and excipient sourcing from Bavarian REACH-compliant manufacturers. Raw material dependencies include dextromethorphan base compounds, guaifenesin crystals, and viscosity-modifying excipients. Single-source vulnerability from concentrated Chinese precursor production exposes formulators to trade friction and input volatility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cough remedies market functions as a regulatory compounder where FDA OTC monograph reform cycles continuously reshape competitive viability and procurement concentration.
For Market Incumbents: Extend pediatric formulation patent portfolios through sustained-release delivery platform investments that abuse-deterrent requirements make defensible. Deepen backward integration into API precursor supply through captive sourcing arrangements in India and China, mitigating the tariff exposure and geopolitical friction threatening guaifenesin and dextromethorphan input stability. For New Entrants and Emerging Players: The mid-tier price-point gap between premium pediatric microencapsulation products and economy liquid generics offers white-space entry for botanical specialists with REACH-compliant ivy leaf and thyme extract formulations. Target Germany and France pharmacy chains where organic certification commands shelf placement, using green chemistry documentation as the primary go-to-market credential. For Investors and Strategic Acquirers: Diversified healthcare conglomerates with pharmacy channel control are the most active acquirers in this space, seeking pediatric toxicology capabilities and telehealth subscription infrastructure. Long-term viability favors targets with dual FDA-EMA regulatory affairs bandwidth and MDR-compliant nebulizer combination platforms. Watch WHO essential medicines list inclusion decisions for Nigeria, Kenya, and Ghana as the inflection signal for African procurement pathway opening.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Formulation Patent Extension | Abuse-deterrent matrix investments lock in pharmacy formulary placement against generic erosion. |
| REACH-Compliant Excipient Sourcing | German green chemistry credentials unlock premium positioning in EMA-regulated pharmacy chains. |
| Telehealth Subscription Integration | Auto-ship bundling with seasonal allergy prophylaxis captures recurring revenue from chronic households. |
| WHO Prequalification Documentation | African essential medicines procurement pathways open for basic expectorants in Nigeria and Ghana. |
| MDR Conformity Assessment Completion | Notified body certification filters out competitors from German nebulizer-cough remedy shelf placement. |
Study Parameters
Direct dialogue with regulatory affairs directors, pharmacy chain procurement managers, pediatric formulation scientists, and hospital formulary committee members grounded qualitative insights in operational reality. Secondary validation drew from FDA OTC monograph filings, EMA MDR submission databases, WHO essential medicines list documentation, and REACH compliance registries. Bottom-up volume modeling across delivery modes and applications triangulated against top-down pharmaceutical market sizing from customs trade records and pharmacy retail audit data.
Segment-level value outputs trace patient age demographics, prescription status, and delivery technology patent life across the projection horizon. The analytical framework modeled formulation complexity tiers, regulatory pathway requirements, and channel concentration patterns. CAGRs derived from pediatric care volume elasticity, API input cost trajectories, and pharmacy chain consolidation rates. Forecast inputs included monograph reform implementation timelines and MDR reclassification compliance deadlines.
Caveats apply where FDA pediatric safety advisory revisions, EMA MDR notified body backlog delays, or Chinese API export restriction shifts could materially shift the outlook. Forecasts reflect documented assumptions regarding pharmacy chain procurement consolidation velocity and telehealth platform adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Aspirin API Market
Pharmacology
Hyperkalemia Drugs Market
Pharmacology
Drug Eruptions Treatment Market
Pharmacology
Angiotensin II Receptor Blockers (Arbs) Market
Pharmacology
Anti-Asthma Drugs Market
Pharmacology
Global Pharmacokinetics Services Market
Pharmacology
Global Asthma Therapeutics Market
Pharmacology
Autacoids and Related Drugs Market
Pharmacology
Medication Adherence Market
Pharmacology
Antihyperlipidemic Drugs Market
Pharmacology
Attention Deficit Hyperactivity Disorder (ADHD) Therapeutics Market
Pharmacology
UK Pharmacovigilance Market
Pharmacology
Global Migraine Therapeutics Market
Pharmacology
Clot Busting Drugs Market
Pharmacology
Global Olanzapine Market
Pharmacology
Semaglutide API Market