
 Drug Delivery Across the Blood-Brain Barrier Market | 2026-2036
Drug Delivery Across the Blood-Brain Barrier Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Delivery Across the Blood-Brain Barrier Market Foresight
Multi-source antibody licensing is realigning how pharmaceutical companies secure blood-brain barrier shuttle technologies. Denali Therapeutics leverages its TV platform to anchor partnered programs across neurodegeneration. Roche Holding AG sustains one of the deepest pipelines in CNS biologics through internal discovery and external collaboration. Gate2Brain competes on receptor-mediated transport specificity with a focus on peptide conjugate architectures.
Drug delivery across the blood-brain barrier encompasses engineered transport systems that exploit endogenous receptor pathways, focused ultrasound, or magnetic nanoparticle guidance to achieve therapeutic concentrations in brain parenchyma that conventional intravenous administration cannot reach. Liposome formulations with surface-modified apolipoprotein E peptides achieve payload transfer across endothelial tight junctions at clinically relevant dosing scales. Nanoparticle systems lead current development investment due to tunable surface chemistry and established manufacturing infrastructure, while conjugate platforms represent the fastest-expanding segment as antibody-shuttle fusions demonstrate proof-of-mechanism in Phase II oncology and neurodegeneration studies. Transcytosis technology dominates partnered deal flow because it preserves blood-brain barrier integrity while enabling repeat dosing.
FDA breakthrough therapy designations and EMA PRIME eligibility for CNS-targeted biologics are compressing regulatory timelines and reshaping clinical trial investment priorities. ISO 10993 biocompatibility standards and FDA guidance on liposomal and nanoparticle drug products govern material qualification and characterization requirements for commercial-scale blood-brain barrier platforms. Stakeholders must monitor how FDA and EMA convergence on complex generic guidance for nanomedicines will alter exclusivity periods and biosimilar entry dynamics for first-generation blood-brain barrier products.
Market Dynamics
Transcytosis platform maturation is compressing clinical development timelines and forcing contract research organizations to reconfigure their service architectures around receptor-mediated transport validation.
Growth Catalysts
- FDA Breakthrough Therapy Designations:Compressed review timelines for Alzheimer's and glioblastoma candidates accelerate capital deployment into blood-brain barrier programs.
- Peptide Conjugate Architectures:Gate2Brain and competing platforms demonstrate receptor specificity gains that expand addressable neurodegenerative indications.
- Massachusetts and California Clusters:Concentrated contract research and biologics manufacturing infrastructure anchors scaled platform development.
Market Restraints
- ISO 10993 Biocompatibility Qualification:Extended material characterization timelines delay first-in-human enrollment for novel nanoparticle formulations.
- Lipid Supply Concentration:Critical liposome precursor sourcing concentrates among limited qualified suppliers, creating input vulnerability.
- Tight Junction Preservation Requirements:Transcytosis platforms face intrinsic payload size constraints that exclude larger biologic modalities.
Strategic Opportunities
- EMA PRIME Eligibility Expansion:European accelerated assessment pathways for CNS-targeted therapies create parallel regulatory arbitrage opportunities.
- Focused Ultrasound Convergence:Integration with magnetic nanoparticle guidance systems opens transient blood-brain barrier disruption protocols for oncology applications.
- Academic Medical Center Partnerships:Direct hospital system relationships bypass traditional pharmaceutical distribution channels for investigator-initiated trials.
Industry Challenges
- Neuropharmacology-Toxicology Hybrid Skill Scarcity:Blood-brain barrier program teams require rare cross-functional expertise in endothelial biology and CNS safety assessment.
- GLP Manufacturing Scale-Up:Nanoparticle batch consistency at commercial volumes demands capital-intensive single-use bioreactor installations.
- Complex Generic Guidance Uncertainty:Pending FDA-EMA convergence on nanomedicine exclusivity definitions complicates portfolio valuation models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Delivery Across the Blood-Brain Barrier Market |
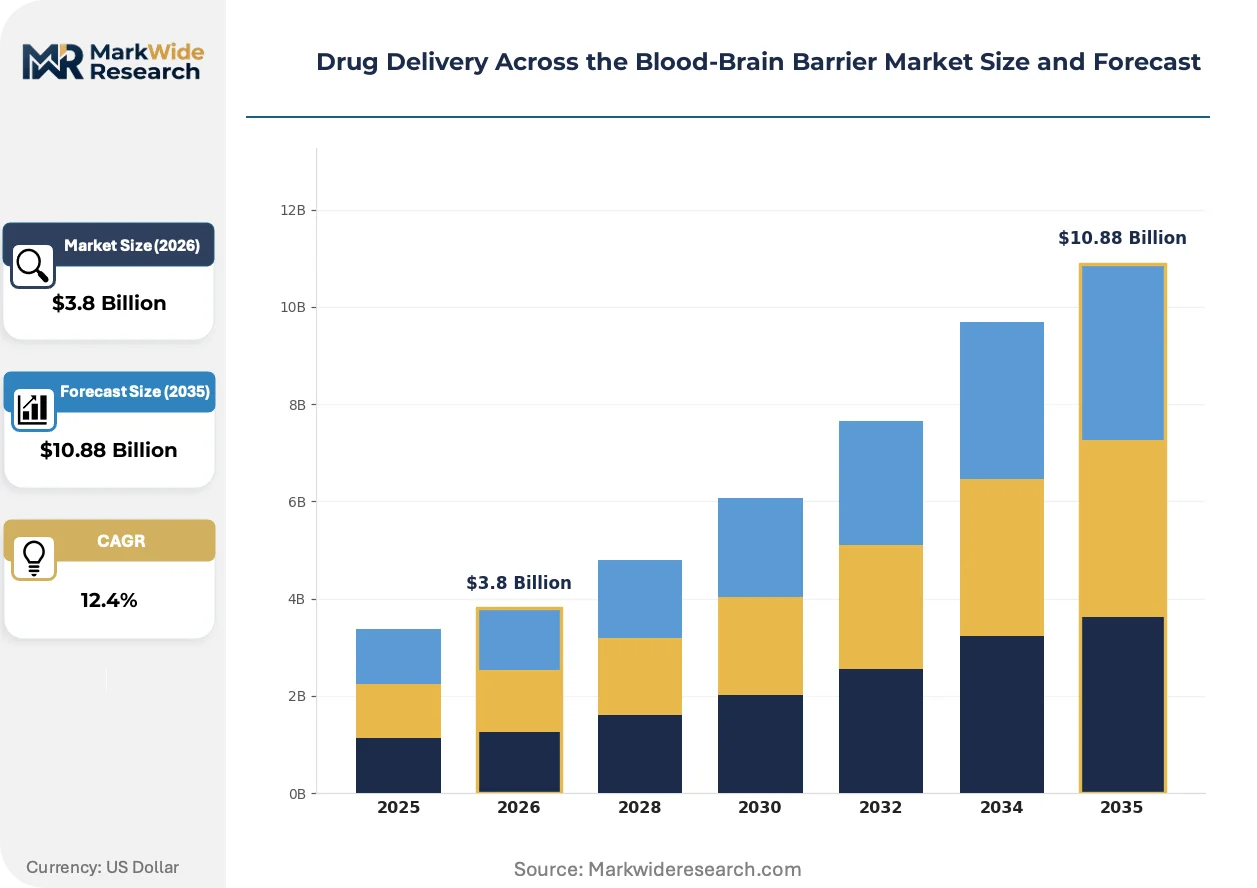
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.88 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanoparticles, Microemulsions, Liposomes, Conjugates Technology: Magnetofection, Ultrasound, Transcytosis, Chemical Penetration End User: Pharmaceutical Companies, Research Institutions, Biotech Firms, Hospitals Application: Neurological Disorders, Cancer Therapy, Pain Management, Vaccine Delivery |
| Companies Covered | ArmaGen, Gate2Brain, Denali Therapeutics, JCR Pharmaceuticals, Roche Holding AG, Bioasis Technologies, Ossianix, ABL Bio, Angiochem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Delivery Across the Blood-Brain Barrier Market Shifts & Advancements
Platform engineering priorities are pivoting from permeability enhancement toward selective receptor targeting that preserves barrier integrity across repeat dosing cycles.
Focused ultrasound-mediated blood-brain barrier opening is electrifying glioblastoma treatment protocols by enabling transient, localized permeability without systemic toxicity. Academic medical centers in the United States and Germany are deploying clinical-grade systems for combination therapy trials. This modality is electrifying partnership structures between device manufacturers and pharmaceutical developers previously siloed across regulatory pathways.
EMA PRIME eligibility criteria for central nervous system biologics are tightening evidentiary standards for blood-brain barrier penetration proof. Sponsors must now submit receptor binding kinetic data prior to accelerated assessment designation. European biotechnology firms are responding by front-loading translational pharmacology investments before regulatory submission.
Hospital procurement committees are consolidating blood-brain barrier therapeutic purchasing through integrated delivery networks rather than individual physician preference. Academic medical centers in California and Massachusetts are negotiating enterprise pricing for transcytosis-enabled candidates across multiple therapeutic areas. This concentration is most visible in neuro-oncology service lines where protocol standardization reduces formulary complexity.
Drug Delivery Across the Blood-Brain Barrier Market Segmentation
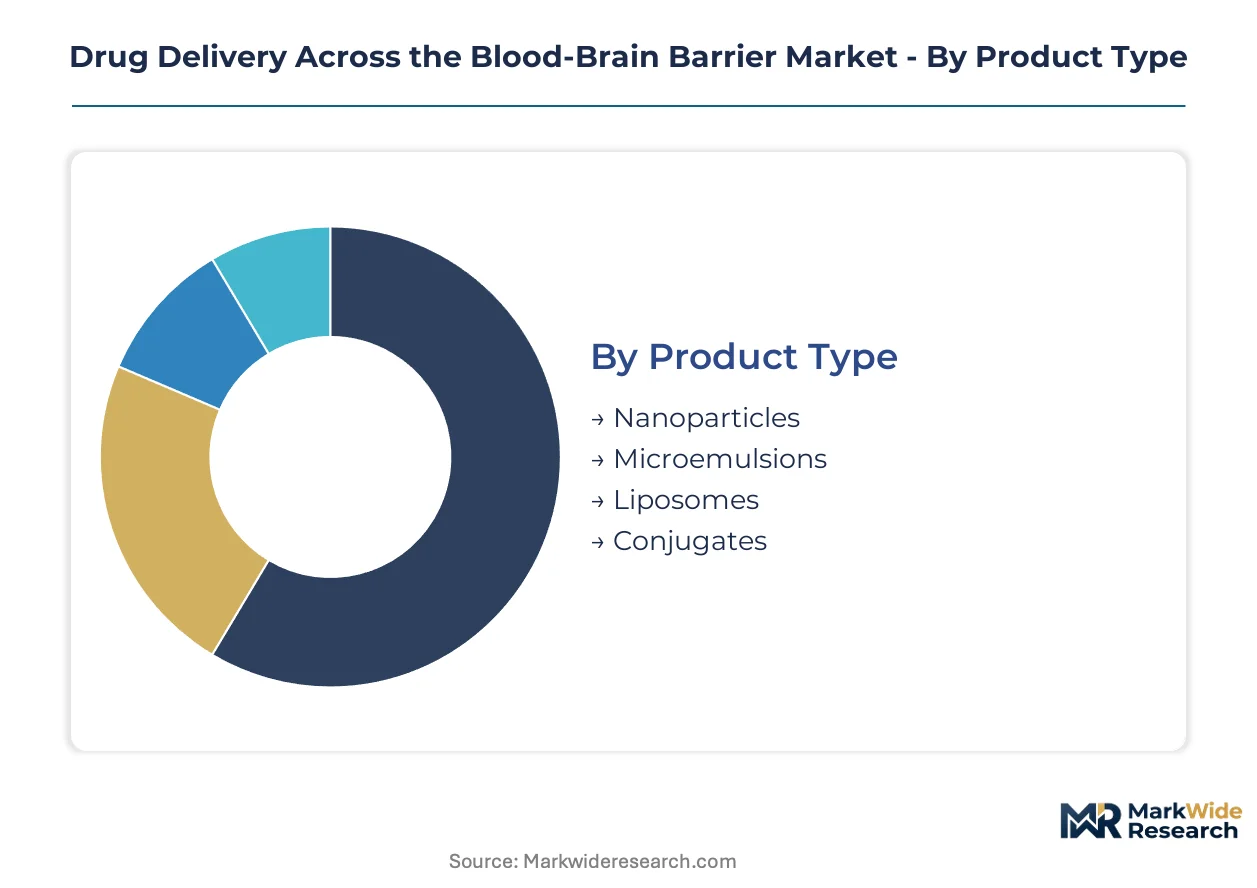
Drug delivery across the blood-brain barrier demands precise matching of platform architecture to disease biology and dosing regimen. Segmentation reveals how transcytosis-enabled modalities command premium positioning against disruption-based alternatives, while end-user concentration in Massachusetts and California biotech clusters reshapes commercial strategy.
Product Type:
Standardized manufacturing protocols dominate nanoparticle and liposome supply, while conjugate platforms require bespoke engineering for each therapeutic payload.
- Nanoparticles:Polymeric or lipid-core structures with tunable surface chemistry enable receptor-targeted brain penetration at scalable production volumes. Demand concentrates in glioblastoma programs where repeat dosing tolerance favors non-disruptive entry mechanisms.
- Conjugates:Antibody-shuttle fusions and peptide conjugates fuse transport moieties to therapeutic cargoes through recombinant or synthetic chemistry. Massachusetts biotech firms anchor development investment as FDA breakthrough designations compress Phase II enrollment timelines for Alzheimer's candidates.
- Liposomes:Phospholipid bilayer vesicles surface-modified with apolipoprotein E peptides achieve endothelial transcytosis.
- Microemulsions:Thermodynamically stable oil-in-water dispersions enhance lipophilic drug solubility.
Leading the category by volume: Nanoparticles. Expanding most quickly: Conjugates.
Technology:
Capital intensity separates device-dependent modalities from biologics-only platforms, with ultrasound systems requiring hospital infrastructure investment that transcytosis avoids.
- Transcytosis:Receptor-mediated vesicular transport preserves tight junction integrity while enabling chronic dosing protocols. Gate2Brain and competing peptide architectures concentrate demand in neurodegeneration pipelines where barrier preservation determines repeat administration feasibility.
- Ultrasound:Focused acoustic energy transiently disrupts endothelial tight junctions for localized drug entry. German and United States academic medical centers deploy clinical-grade systems for glioblastoma combination trials, electrifying device-pharma partnership structures.
- Magnetofection:Magnetic nanoparticle guidance concentrates therapeutic payload at target vasculature.
- Chemical Penetration:Osmotic or alkylglycerol-based disruption achieves temporary barrier permeabilization.
Dominating partnered deal flow: Transcytosis. Steepest expansion trajectory: Ultrasound.
End User:
Procurement authority concentrates in integrated delivery networks for hospitals, while biotech firms retain platform development autonomy through contract research partnerships.
- Biotech Firms:Specialized developers pioneer receptor-targeted shuttle technologies through venture-backed platform maturation. California and Massachusetts clusters anchor scaled manufacturing infrastructure for clinical-grade nanoparticle batches.
- Pharmaceutical Companies:Major sponsors license transcytosis platforms to de-risk CNS pipeline assets, with Roche sustaining one of the deepest internal discovery efforts in blood-brain barrier biologics.
- Research Institutions:Academic medical centers conduct investigator-initiated trials and mechanistic pharmacology studies.
- Hospitals:Neuro-oncology service lines standardize protocols for focused ultrasound-mediated delivery.
Highest platform licensing activity: Biotech Firms. Fastest procurement consolidation: Hospitals.
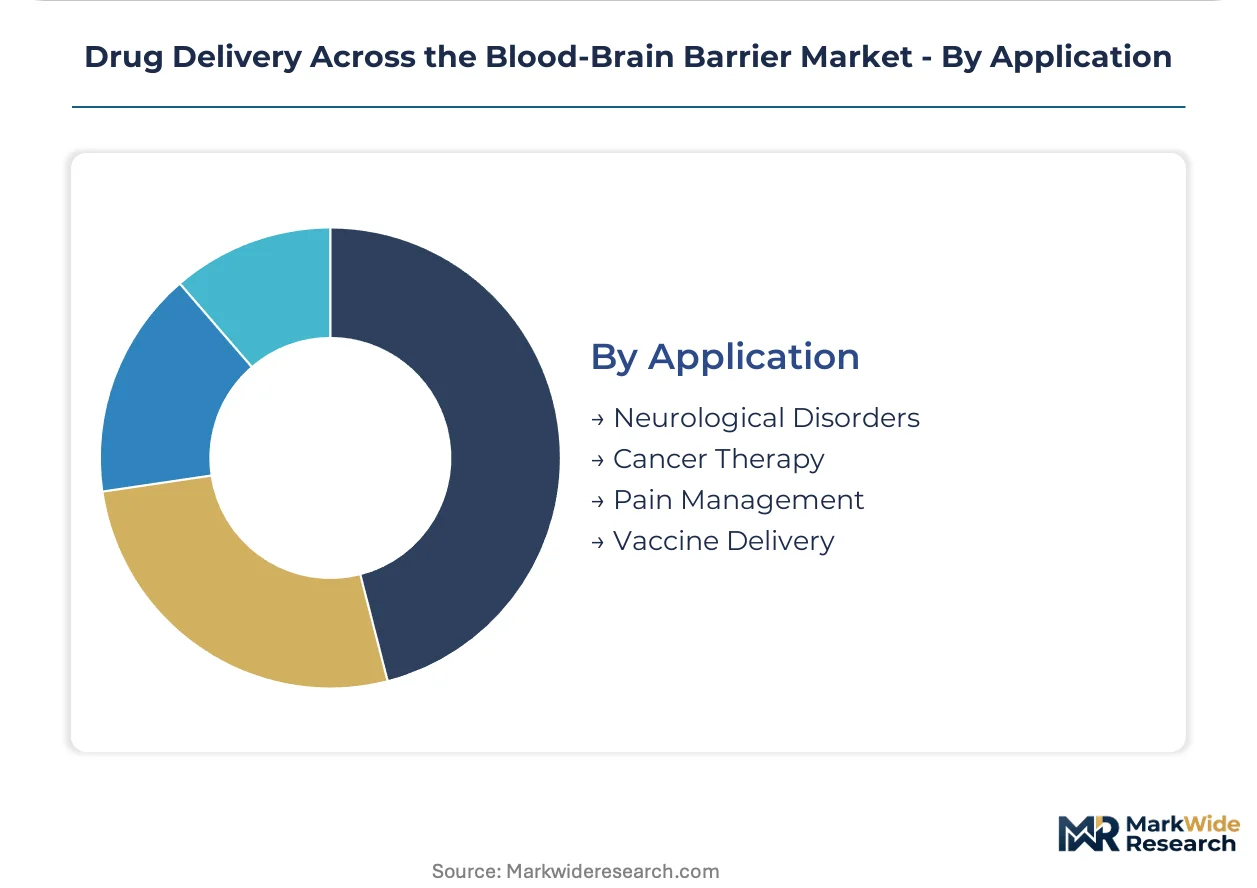
Application:
Regulatory pathway complexity varies by indication, with oncology benefiting from accelerated assessment frameworks that neurological disorders increasingly access.
- Neurological Disorders:Alzheimer's and Parkinson's programs drive chronic dosing platform demand where barrier integrity preservation determines commercial viability. EMA PRIME eligibility tightening evidentiary standards front-loads translational pharmacology investment.
- Cancer Therapy:Glioblastoma multiforme represents the most advanced clinical application, with transient disruption protocols acceptable for terminal indications. FDA breakthrough therapy designations compress review timelines for combination regimens.
- Pain Management:Opioid-sparing CNS delivery targets chronic neuropathic conditions.
- Vaccine Delivery:Neurotropic pathogen immunization requires antigen presentation across endothelial barriers.
Largest addressable patient population: Neurological Disorders. Gaining share fastest: Cancer Therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phospholipid precursor manufacturing concentrates in Germany's chemical corridor, anchoring European liposome supply chains for blood-brain barrier formulations. Venture deployment for transcytosis platforms clusters in coastal United States biotech hubs. Clinical trial density for focused ultrasound protocols peaks in German and United States academic medical centers.
United States
FDA breakthrough therapy designations for Alzheimer's and glioblastoma candidates compress review timelines and accelerate capital deployment into receptor-mediated transport programs. The 21st Century Cures Act provisions expedite regenerative medicine advanced therapy pathways for CNS biologics. Massachusetts and California clusters anchor contract research and biologics manufacturing infrastructure for clinical-grade nanoparticle batches.
Germany
EMA PRIME eligibility criteria tightening evidentiary standards front-load translational pharmacology investments for European sponsors. The German national pharmaceutical regulator enforces ISO 10993 biocompatibility standards with extended material characterization timelines for novel formulations. Heidelberg and Munich academic medical centers deploy clinical-grade focused ultrasound systems for glioblastoma combination trials.
Switzerland
Roche Holding AG sustains one of the deepest internal discovery pipelines in CNS biologics through Basel-based research operations. Swissmedic maintains accelerated assessment pathways for orphan neurological indications that align with EMA centralized procedures. The Basel-Zurich corridor concentrates antibody-shuttle fusion development for neurodegenerative disease candidates.
Japan
PMDA Sakigake designation system compresses regulatory timelines for blood-brain barrier-enabled oncology and neurology therapies. The national pharmaceutical regulator harmonizes nanomedicine guidance with FDA and EMA frameworks to facilitate multinational trial enrollment. Tokyo-Osaka biotech clusters specialize in liposome surface modification technologies for apolipoprotein E peptide conjugation.
United Kingdom
MHRA post-Brexit regulatory autonomy enables tailored accelerated access pathways for CNS-targeted biologics with blood-brain barrier penetration proof. The Innovative Licensing and Access Pathway compresses market entry timelines for medicines addressing unmet neurological needs. London-Cambridge biotech corridor specializes in academic spin-out formation for transcytosis platform ventures.
Drug Delivery Across the Blood-Brain Barrier Market Competitive Landscape
Platform licensing dominates the current landscape as pharmaceutical sponsors seek de-risked CNS pipeline assets through external collaboration. The market structures around three tiers: integrated biopharmaceutical conglomerates with internal discovery capabilities, venture-backed platform specialists with proprietary shuttle technologies, and academic spin-outs transitioning receptor targeting research toward clinical validation. Strategic archetypes include technology licensors monetizing transport moieties through milestone-heavy partnership structures, vertically integrated developers controlling manufacturing from nanoparticle synthesis through fill-finish, and device-pharma hybrids converging focused ultrasound hardware with therapeutic payloads. Technology licensing and strategic partnerships constitute the dominant competitive moves, with capacity expansion in GLP nanoparticle manufacturing trailing as a secondary priority.
Among platform specialists, Denali Therapeutics and Gate2Brain occupy distinct positions within the receptor-mediated transport segment. Denali Therapeutics exemplifies the integrated platform developer archetype through its TV technology anchor across partnered neurodegeneration programs. Gate2Brain represents the peptide conjugate specialization vector with focused receptor specificity claims. Roche Holding AG sits within the conglomerate tier, sustaining internal discovery depth in blood-brain barrier biologics while selectively licensing complementary technologies. These three entities illustrate how competitive positioning fragments across business model rather than therapeutic indication alone.
| Leading Market Players |
|---|
| ArmaGen |
| Gate2Brain |
| Denali Therapeutics |
| JCR Pharmaceuticals |
| Roche Holding AG |
| Bioasis Technologies |
| Ossianix |
| ABL Bio |
| Angiochem |
| Others |
Supply & Pricing Matrix
Venture-backed platform specialists concentrated in Massachusetts and California biotech clusters exercise pricing discipline through milestone-heavy partnership structures that tie revenue to clinical validation rather than unit volume. This financing pattern concentrates supply bargaining power among contract research organizations and lipid precursor suppliers, compressing margins for early-stage developers while rewarding scaled manufacturers with GLP batch consistency.
Pricing Analysis
Platform licensing agreements bundle regulatory consulting and manufacturing technology transfer within upfront fees, unbundling ongoing clinical support and supply security warranties into separate milestone payments. Pricing stratifies across premium, standard, and economy tiers based on receptor specificity validation data and ISO 10993 biocompatibility certification completeness. Cost compression in peptide conjugate architectures is intensifying because EMA PRIME eligibility tightening demands front-loaded translational pharmacology investment. Biotech firms with preclinical proof-of-mechanism data exhibit the least price sensitivity, while academic spin-outs negotiating first partnerships show acute cost consciousness.
Supply Chain Analysis
Dual-sourcing requirements for clinical-grade phospholipids mandate qualification of at least two suppliers for liposome precursor batches, forcing developers to maintain relationships with German chemical corridor manufacturers and Japanese specialty lipid producers simultaneously. Raw material dependencies center on synthetic phospholipids, recombinant protein expression systems, and single-use bioreactor consumables. Single-source vulnerability concentrates in qualified suppliers for apolipoprotein E peptide surface modification reagents. Distribution runs through integrated delivery networks at academic medical centers rather than traditional pharmaceutical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform maturation is compressing development timelines and forcing capital-constrained developers into distressed asset sales, consolidating competitive position around scaled transcytosis capabilities.
For Market Incumbents: Hedge against focused ultrasound disruption by securing device-pharma hybrid partnerships before transient barrier opening protocols achieve regulatory standardization. Prioritize backward integration into lipid precursor manufacturing to reduce supply vulnerability from German and Japanese chemical suppliers. Denali Therapeutics' TV platform licensing model demonstrates how proprietary shuttle technology anchors defensive deal flow across neurodegeneration pipelines. For New Entrants and Emerging Players: Enter via pain management applications where opioid-sparing CNS delivery faces lower regulatory evidentiary bars than Alzheimer's or glioblastoma pathways. Target investigator-initiated trial partnerships at California and Massachusetts academic medical centers to bypass traditional pharmaceutical distribution channels. Gate2Brain's peptide conjugate specialization illustrates how receptor specificity claims differentiate white-space positioning against antibody-shuttle fusion incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor venture-backed platform specialists with validated receptor binding kinetics but stalled Series C financing in the United States coastal biotech corridors. Long-term viability over the coming decade hinges on EMA-FDA regulatory convergence timelines and complex generic guidance clarity for nanomedicine exclusivity definitions. Watch for FDA breakthrough therapy designation density as the inflection signal for platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designations compress enrollment timelines for Alzheimer's candidates. |
| Manufacturing Scale-Up | GLP nanoparticle batch consistency demands capital-intensive single-use bioreactor installations. |
| Licensing Agreement | Milestone-heavy partnership structures monetize transport moieties without clinical execution risk. |
| Clinical Trial Advancement | Heidelberg and Munich academic medical centers deploy focused ultrasound systems for glioblastoma protocols. |
| Pipeline Diversification | Roche sustains internal discovery depth across CNS biologics while selectively licensing complementary technologies. |
Research Methodology
FDA filings, ClinicalTrials.gov records, and EMA submission documents formed the secondary backbone for platform technology assessment and regulatory pathway mapping. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists validated transcytosis platform adoption patterns and pricing dynamics. Bottom-up and top-down triangulation reconciled venture deployment data with contract research organization capacity utilization across Massachusetts and California biotech clusters.
Bottom-up modeling anchored volume projections to individual pipeline stage transitions and partnership announcement flows, while top-down analysis cross-checked aggregate market expansion against CNS therapeutic area investment trends. Segmentation dimensions spanned product type, technology mechanism, end user archetype, and application indication across the projection horizon. CAGRs derived from logistic curve fitting to clinical trial enrollment velocity and regulatory designation density rather than extrapolated historical growth rates. Forecast inputs incorporated ISO 10993 biocompatibility qualification timelines and phospholipid precursor supply concentration metrics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA-EMA divergence on nanomedicine exclusivity definitions or acute lipid supply disruption. Forecasts reflect assumptions regarding EMA PRIME eligibility criteria stability and focused ultrasound device reimbursement pathway clarity. Deviation in regulatory convergence timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Alzheimer Drugs Market
Pharmacology
Propranolol Drug Market
Pharmacology
Clot Busting Drugs Market
Pharmacology
Ibuprofen API Market
Pharmacology
Immunotherapy Drugs Market
Pharmacology
Artemisinin Antimalarial Drugs Market
Pharmacology
Global Olanzapine Market
Pharmacology
Anti Inflammatory Therapeutics Market
Pharmacology
Ketoprofen API Market
Pharmacology
Anti-Hypertensive Drugs Market
Pharmacology
Hydroxychloroquine Drugs Market
Pharmacology
Thromboprophylactic Drugs Market
Pharmacology
Antithrombotic Drugs Market
Pharmacology
Global Migraine Therapeutics Market
Pharmacology
Hyperkalemia Drugs Market
Pharmacology
Medication Adherence Market