
 Antimycotics Market | 2026-2036
Antimycotics Market Size, Share, and Industry Trends Forecast 2026-2036
Antimycotics Market Outlook
Specialized mycology research talent is collapsing across academic medical centers, constraining pipeline innovation for novel antifungal classes. Pfizer Inc. leverages its established manufacturing infrastructure to sustain azole production at scale. Merck & Co., Inc. anchors its position through echinocandin R&D intensity, while Gilead Sciences, Inc. differentiates via lipid-based amphotericin B formulations for severe systemic infections.
Antimycotics comprise pharmaceutical agents that inhibit fungal cell membrane synthesis, cell wall integrity, or nucleic acid metabolism, typically administered at therapeutic concentrations ranging from topical creams to high-dose intravenous infusions for life-threatening invasive disease. Azoles dominate current prescription volumes due to broad-spectrum oral bioavailability, though echinocandins command premium positioning in hospital formularies for azole-resistant Candida bloodstream infections. Intravenous delivery mode captures the highest margin pool among administration routes, driven by intensive care unit utilization and the requirement for therapeutic drug monitoring in critically ill patients.
The FDA's post-market safety requirements for hepatotoxicity monitoring shape azole labeling and prescriber education, while the EMA's antifungal resistance surveillance networks influence European formulary restrictions. Health Canada and the TGA enforce comparable bioequivalence standards for generic polyene approvals, tightening market access for non-innovator manufacturers. Stakeholders must monitor antifungal stewardship mandates from CMS and private payers, as reimbursement policies increasingly tie coverage to documented susceptibility testing rather than empiric prescribing patterns.
Market Dynamics
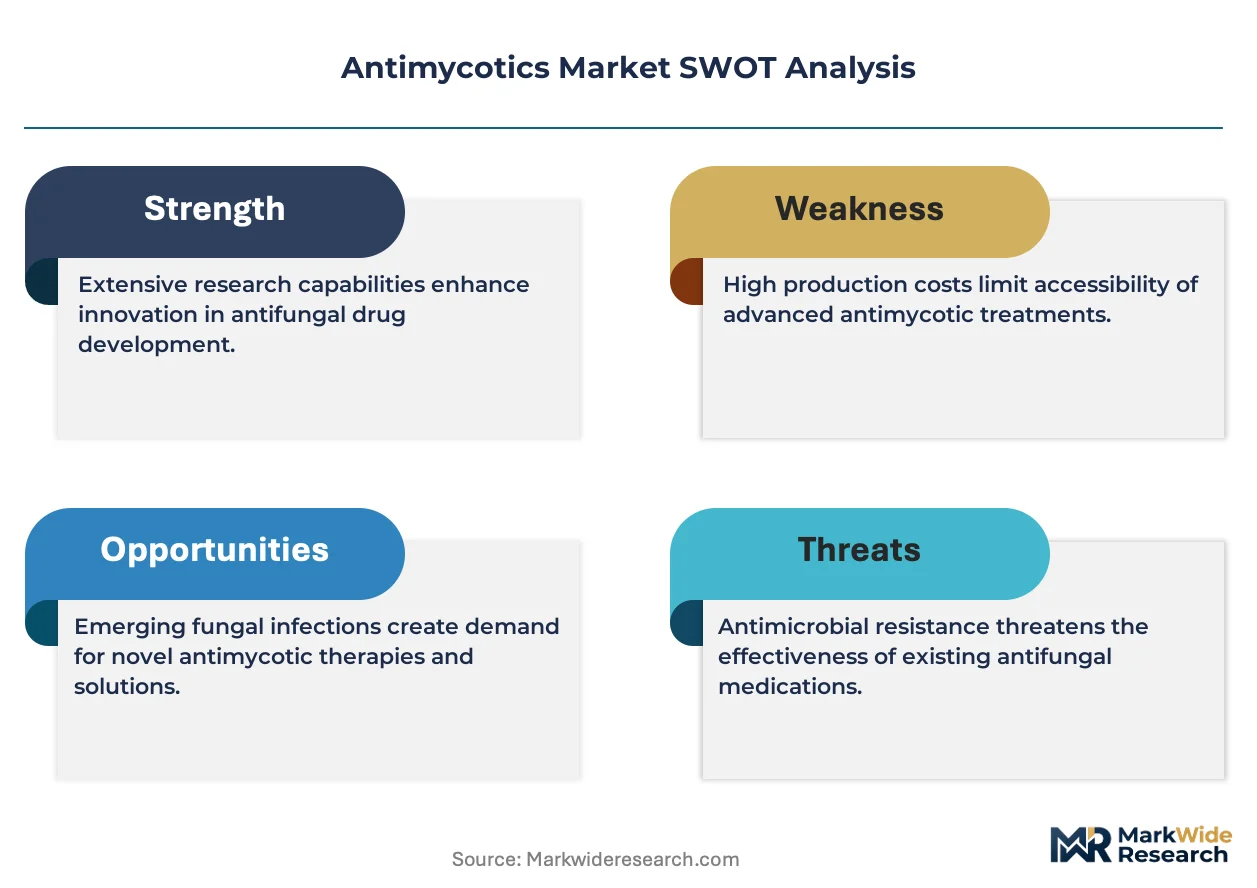
FDA's intensified hepatotoxicity surveillance of azole-class drugs is forcing manufacturers to reallocate R&D budgets toward echinocandin and polyene alternatives, compressing development timelines for novel antifungal classes.
Growth Catalysts
- Hospital formulary expansion:Integrated health systems in the United States are consolidating procurement of intravenous echinocandins for azole-resistant Candida bloodstream infections.
- REACH compliance alignment:European manufacturers accelerating green chemistry adoption for azole synthesis to preempt EMA environmental risk assessments.
- Immunocompromised patient pools:Oncology and transplant centers are expanding systemic antifungal protocols as prophylaxis duration extends.
Market Restraints
- Active pharmaceutical ingredient concentration:Azole precursor manufacturing clusters in China create supply vulnerability amid export license volatility.
- Specialized fermentation capacity:Polyene production requires dedicated bioreactor infrastructure with limited contract manufacturing availability.
- Generic substitution pressure:Fluconazole commoditization erodes branded oral azole margins in outpatient settings.
Strategic Opportunities
- India's CDSCO fast-track pathway:Localized clinical trials for novel echinocandins can accelerate market entry against entrenched azole prescribing.
- Liposomal formulation advances:Nanoparticle drug delivery convergence with amphotericin B reduces nephrotoxicity profiles for ICU applications.
- Specialty pharmacy distribution:Direct-to-provider models for high-cost intravenous therapies bypass traditional wholesale markups.
Industry Challenges
- Medical mycology expertise erosion:Academic medical centers are shuttering fungal pathology training programs, constraining susceptibility testing interpretation.
- Therapeutic drug monitoring infrastructure:Hospital laboratories lack LC-MS/MS capacity for voriconazole and posaconazole level quantification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antimycotics Market |
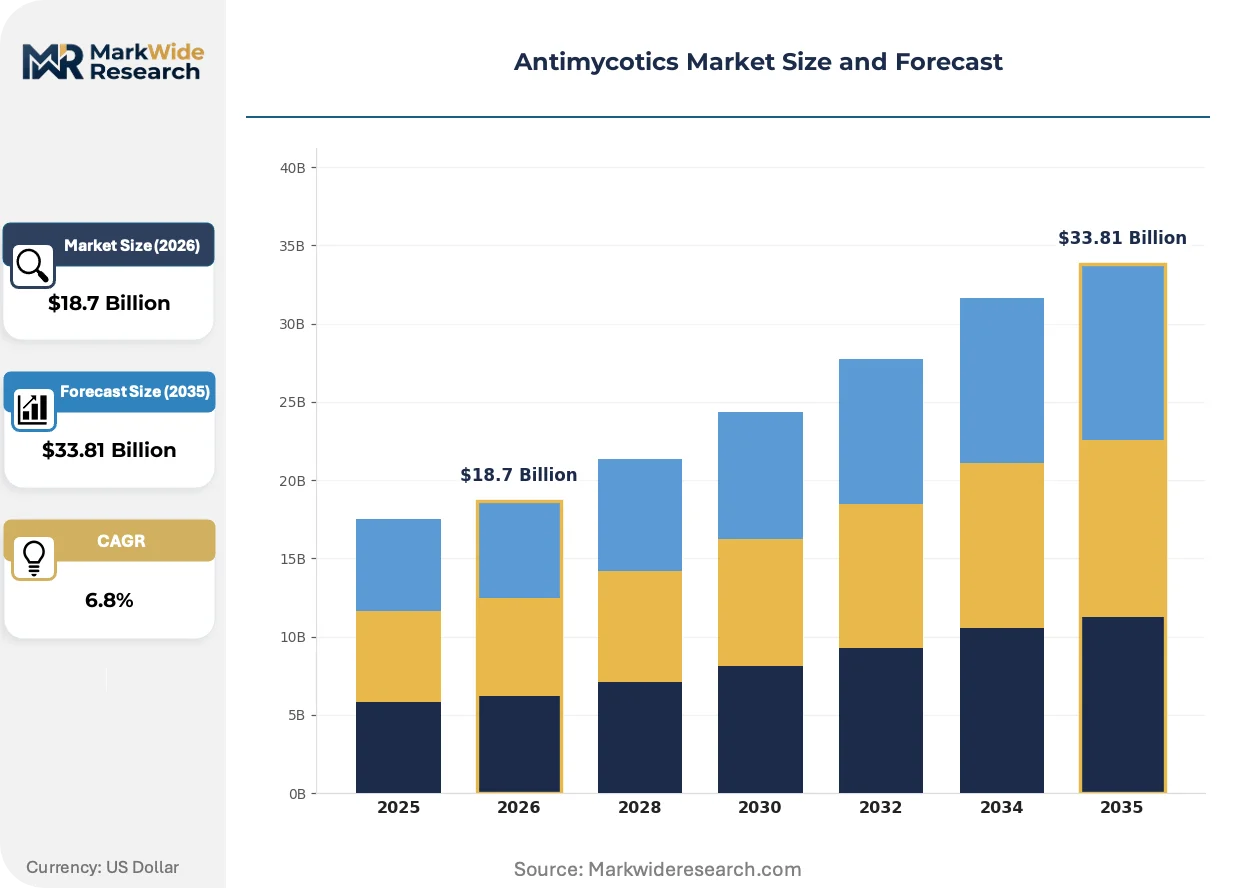
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Azoles, Polyenes, Echinocandins, Allylamines Application: Dermatological Infections, Candidiasis, Aspergillosis, Systemic Fungal Infections Delivery Mode: Topical, Oral, Intravenous, Inhalation End User: Hospitals, Clinics, Homecare, Pharmaceutical Companies |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Astellas Pharma Inc., Novartis AG, GlaxoSmithKline plc, Sanofi, Bayer AG, Gilead Sciences, Inc., Glenmark Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antimycotics Market Strategic Shifts
Novel antifungal development is pivoting toward cell wall-targeting mechanisms as azole resistance surveillance intensifies across hospital networks. Three convergent forces are restructuring competitive positioning.
Oral bioavailability enhancement technologies are miniaturizing particle size distributions for itraconazole and posaconazole formulations, enabling submicron absorption profiles that bypass food-effect variability. Compounding pharmacies in the United States are adopting nanomilling equipment to serve hematology-oncology clinics requiring consistent plasma exposure. This capability is compressing the clinical advantage window of intravenous-only echinocandins for step-down therapy.
EMA's antifungal resistance surveillance networks are mandating susceptibility reporting thresholds that reshape European hospital formulary tiers. Manufacturers must now submit annual resistance trend data for azole and echinocandin classes to maintain marketing authorization. German and French hospital consortia are responding by restricting empiric fluconazole use in favor of documented antifungal stewardship protocols.
Consolidated purchasing agreements between United States integrated delivery networks and group purchasing organizations are displacing individual hospital formulary autonomy. Three-year sole-source contracts for echinocandin classes now predominate in systems exceeding 50 hospitals, extracting price concessions in exchange for volume commitments. This concentration is most visible in the Southeast and Midwest regions where Catholic health system mergers have created dominant procurement entities.
Antimycotics Market Segmentation
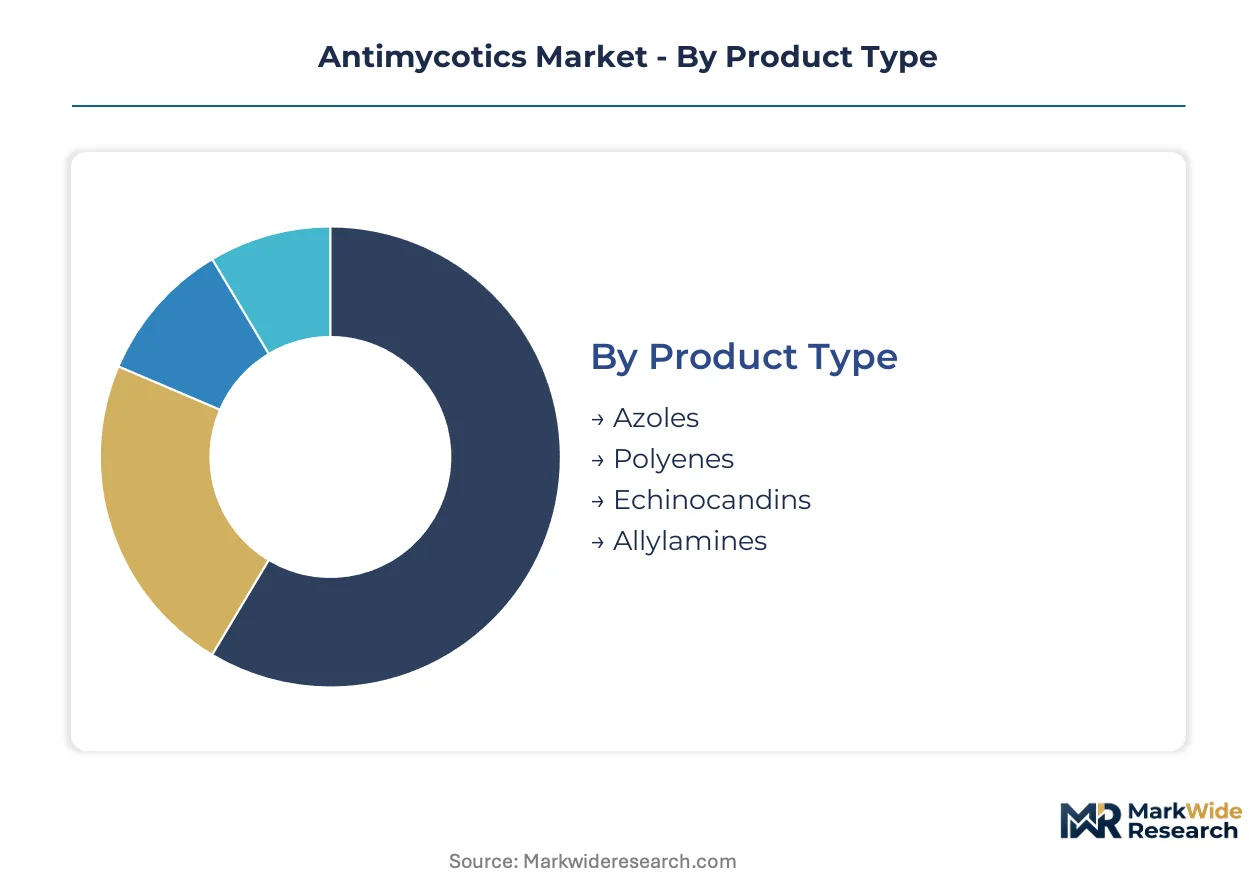
Antimycotics market segmentation reveals distinct channel dynamics where intravenous formulations flow through hospital formularies while oral azoles reach patients via retail pharmacy networks. Each dimension—product chemistry, disease indication, administration route, and care setting—carries unique margin profiles and regulatory touchpoints that shape manufacturer strategy.
Product Type:
Channel distribution varies sharply by molecular class, with hospital procurement dominating high-cost intravenous therapies and outpatient pharmacies handling oral regimens.
- Azoles:Oral bioavailability drives broad prescription volumes through retail channels, though FDA hepatotoxicity surveillance is compressing empiric prescribing in favor of documented susceptibility testing. Fluconazole commoditization has shifted volume toward generic substitution, while voriconazole and posaconazole retain hospital formulary positioning for prophylaxis protocols.
- Echinocandins:Intravenous-only administration anchors these agents in intensive care unit formularies for azole-resistant Candida bloodstream infections. Three-year sole-source contracts between integrated delivery networks and manufacturers are concentrating procurement power in United States health systems exceeding 50 hospitals.
- Polyenes:Amphotericin B formulations require dedicated bioreactor infrastructure with limited contract manufacturing availability, constraining supply expansion.
- Allylamines:Terbinafine dominates dermatological applications through topical and oral routes with established generic competition.
By volume, Azoles leads. By growth pace, Echinocandins is climbing the fastest as resistance surveillance reshapes empiric therapy selection.
Application:
Cost tier stratification separates prophylactic outpatient regimens from high-acuity inpatient interventions requiring therapeutic drug monitoring.
- Systemic Fungal Infections:Invasive aspergillosis and mucormycosis command premium pricing for liposomal amphotericin B and combination echinocandin-azole protocols in hematology-oncology centers. CMS reimbursement policies increasingly tie coverage to documented susceptibility testing rather than empiric prescribing.
- Candidiasis:Bloodstream and invasive candidiasis drive echinocandin utilization in surgical and intensive care units, with step-down to oral fluconazole upon clinical stabilization.
- Aspergillosis:Voriconazole remains first-line for pulmonary forms, though triazole resistance surveillance is expanding isavuconazole and combination therapy adoption.
- Dermatological Infections:Onychomycosis and tinea corporis represent high-volume, low-margin topical and oral terbinafine prescriptions through retail pharmacy channels.
Systemic Fungal Infections generates highest revenue per treated patient. Dermatological Infections expands most quickly in emerging markets with rising diagnostic access.
Delivery Mode:
Margin concentration tracks invasiveness of administration, with intravenous capture in critical care settings offsetting development and manufacturing complexity.
- Intravenous:Echinocandins and liposomal amphotericin B formulations dominate intensive care unit utilization where therapeutic drug monitoring infrastructure supports complex dosing. United States integrated delivery networks extract price concessions through volume-commitment contracts.
- Oral:Azole tablets and capsules serve step-down therapy and outpatient prophylaxis, with nanomilled itraconazole formulations compressing food-effect variability in hematology-oncology clinics.
- Topical:Creams and solutions for superficial dermatophyte infections flow through retail pharmacy with minimal prescriber specialization requirements.
- Inhalation:Limited to niche lipid-based amphotericin B prophylaxis in lung transplant recipients with specialized nebulization protocols.
Intravenous commands highest per-dose revenue. Oral formulations are gaining share fastest as bioavailability enhancement technologies enable step-down therapy.
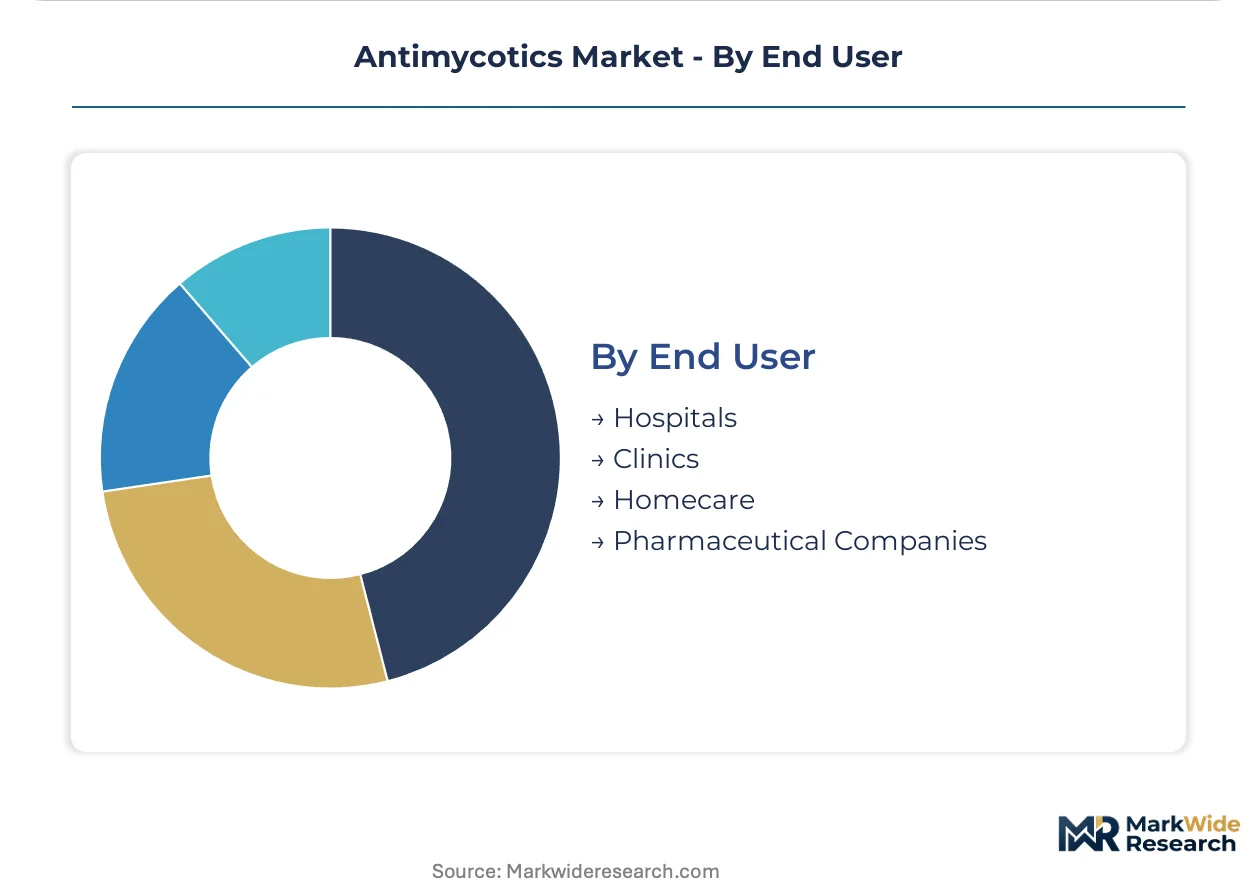
End User:
Customer type determines procurement mechanics, with consolidated purchasing agreements displacing individual hospital autonomy in large health systems.
- Hospitals:Integrated delivery networks and Catholic health system mergers in the United States Southeast and Midwest have created dominant procurement entities negotiating three-year sole-source echinocandin contracts. Antifungal stewardship mandates from CMS and private payers reshape formulary tiers.
- Clinics:Outpatient infusion centers and oncology clinics handle step-down therapy and prophylaxis, with specialty pharmacy distribution bypassing traditional wholesale markups for high-cost intravenous therapies.
- Homecare:Subcutaneous and oral regimens for stable patients reduce hospital length of stay, though reimbursement complexity constrains expansion.
- Pharmaceutical Companies:Active pharmaceutical ingredient sourcing and contract manufacturing relationships concentrate azole precursor supply in Chinese manufacturing clusters.
Hospitals dominate value capture. Specialty pharmacy channels serving Clinics are expanding most quickly as site-of-care migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for intravenous echinocandins concentrates in United States integrated delivery networks, while German hospital consortia extract value through resistance surveillance-driven formulary restrictions. This asymmetry reflects divergent procurement architectures and regulatory enforcement intensity.
United States
Catholic health system mergers across the Southeast and Midwest have created procurement entities exceeding 50 hospitals each, negotiating three-year sole-source echinocandin contracts. CMS antifungal stewardship mandates tie reimbursement coverage to documented susceptibility testing. The Boston-Cambridge corridor retains specialized mycology research capacity despite broader academic program closures.
Germany
Hospital consortia in Bavaria and North Rhine-Westphalia restrict empiric fluconazole use through EMA-mandated resistance reporting thresholds. The country's national pharmaceutical regulator requires annual susceptibility trend submissions for azole marketing authorization maintenance. Frankfurt's pharmaceutical logistics hub channels distribution for Central European hospital networks.
India
Oncology and transplant centers in Maharashtra and Karnataka extend systemic antifungal prophylaxis duration as immunocompromised patient pools expand. CDSCO fast-track pathways for novel echinocandins accelerate market entry against entrenched azole prescribing. Hyderabad's active pharmaceutical ingredient manufacturing clusters concentrate azole precursor supply.
Japan
PMDA post-market surveillance requirements for hepatotoxicity monitoring reshape prescriber education and azole labeling. METI incentives for green chemistry adoption in pharmaceutical manufacturing preempt environmental risk assessments. The Kansai region's fermentation infrastructure supports limited polyene contract manufacturing availability.
Australia
TGA bioequivalence standards for generic polyene approvals tighten market access for non-innovator manufacturers. Therapeutic drug monitoring infrastructure gaps in Queensland and Western Australia constrain voriconazole level quantification capacity. Sydney's academic medical centers maintain fungal pathology training programs amid global expertise erosion.
Antimycotics Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Antimycotics Market. The vendor base organizes around three strategic tiers: established pharmaceutical conglomerates with fermentation infrastructure, specialized biotechnology firms with lipid formulation capabilities, and generic manufacturers competing on azole commoditization. Market structure favors consolidation in intravenous hospital formularies while fragmenting across oral outpatient channels. Dominant competitive moves include strategic partnerships for bioreactor capacity access and portfolio diversification into resistance surveillance services.
Among established pharmaceutical conglomerates, Pfizer Inc. and Merck & Co., Inc. occupy positions reflecting scale-driven manufacturing advantages, while Gilead Sciences, Inc. exemplifies specialization in lipid-based delivery technologies. These three entities represent distinct competitive archetypes: the diversified incumbent with captive supply chains, the R&D-intensive firm anchoring echinocandin development, and the formulation innovator targeting severe systemic infections. Their collective positioning illustrates how manufacturing infrastructure, clinical trial intensity, and delivery technology each create defensible market positions.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Astellas Pharma Inc. |
| Novartis AG |
| GlaxoSmithKline plc |
| Sanofi |
| Bayer AG |
| Gilead Sciences, Inc. |
| Glenmark Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Bioreactor utilization rates exceeding 80 percent in polyene manufacturing anchor cost floors across the antimycotics landscape, concentrating supply leverage among fermentation-capable incumbents while forcing price discipline on oral azole commoditizers. This capacity scarcity simultaneously elevates intravenous echinocandin premiums and compresses generic fluconazole margins through volume-dependent procurement.
Pricing Analysis
The customization-premium spread between standard oral azole tablets and patient-specific compounded formulations reaches three-to-one multiples, with nanomilled itraconazole for hematology-oncology clinics commanding formulation premiums against commodity fluconazole. Price differentiation rests on therapeutic drug monitoring bundling and FDA bioequivalence tier certification, with intravenous echinocandins least price-sensitive due to sole-source contract structures. Cost compression in oral azoles intensifies as integrated delivery networks extract volume concessions, while liposomal amphotericin B retains pricing power through nephrotoxicity profile advantages in ICU settings.
Supply Chain Analysis
Inventory lead times for azole precursors stretch 12-16 weeks from Chinese manufacturing clusters, constraining just-in-time procurement for European and North American formulators. Active pharmaceutical ingredient supply concentrates in India and China for azole synthesis, with fermentation-derived polyene production anchored in Japan and limited European sites. Raw material dependencies span triazole intermediates, soybean phospholipids for liposomal formulations, and specialized resin chromatography media. Single-source vulnerability pervades echinocandin fermentation capacity, while distribution runs through consolidated hospital procurement entities and specialty pharmacy direct-to-provider channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antimycotics sector functions as a service-attach opportunity where antifungal stewardship consulting and therapeutic drug monitoring infrastructure deployment outpace molecule sales growth, creating recurring revenue layers beyond drug procurement.
For Market Incumbents: Shield formulary positioning through captive bioreactor capacity expansion in Japan and Germany, insulating against contract manufacturing scarcity. Anchor echinocandin supply security via backward integration into fermentation infrastructure, while deploying resistance surveillance data services to entrench hospital system relationships against generic azole substitution.
For New Entrants and Emerging Players: Therapeutic drug monitoring platform gaps in Australian and Indian hospital laboratories offer white-space entry, with LC-MS/MS service provision more penetrable than molecule development. Target outpatient oncology clinics in Maharashtra and Karnataka with step-down therapy management protocols, leveraging CDSCO fast-track familiarity against entrenched azole prescribing.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors lipid formulation specialists with platform extensibility beyond amphotericin B into next-generation polyenes. Long-term viability hinges on manufacturing infrastructure ownership rather than pure R&D pipelines, with bioreactor capacity utilization rates serving as the critical inflection signal for supply-constrained echinocandin classes.
| Strategic Initiative | Industry Significance |
|---|---|
| Bioreactor Capacity Expansion | Fermentation infrastructure ownership secures echinocandin supply continuity against contract manufacturing bottlenecks. |
| Antifungal Stewardship Partnership | Hospital system consulting contracts embed manufacturers within CMS-mandated susceptibility testing workflows. |
| Liposomal Formulation Advancement | Nanoparticle delivery technology reduces nephrotoxicity profiles for ICU amphotericin B utilization. |
| Specialty Pharmacy Distribution | Direct-to-provider models bypass wholesale markups for high-cost intravenous therapies. |
| Resistance Surveillance Data Service | Annual susceptibility trend submissions satisfy EMA marketing authorization maintenance requirements. |
Study Parameters
Desk research of FDA hepatotoxicity surveillance databases, EMA antifungal resistance network reports, and hospital formulary procurement records preceded structured interviews with infectious disease pharmacists, hospital procurement directors, and CDSCO regulatory leads. Primary fieldwork with compounding pharmacy operators and therapeutic drug monitoring laboratory managers combined with secondary validation through ClinicalTrials.gov entries and CMS reimbursement policy filings. Bottom-up patient-volume modeling and top-down pharmaceutical revenue triangulation anchored segmentation outputs.
Variance decomposition across molecular class, administration route, and care setting dimensions structured the analytical framework over the projection horizon. CAGRs derived from hospital admission trend extrapolation, immunocompromised population growth curves, and resistance surveillance pattern modeling. Forecast inputs incorporated bioreactor capacity utilization assumptions, generic substitution elasticity parameters, and stewardship mandate compliance cost trajectories.
Forecasts assume regulatory continuity in FDA post-market surveillance and EMA environmental risk assessment regimes; material policy shifts would require re-modeling. Outputs reflect assumptions of stable azole precursor export licensing from Chinese manufacturing clusters and sustained Catholic health system merger momentum in the United States Southeast. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Huoxiang Zhengqi Drug Market
Pharmacology
Aldosterone Receptor Antagonists Market
Pharmacology
Global Asthma Therapeutics Market
Pharmacology
Antihyperlipidemic Drugs Market
Pharmacology
Immunotherapy Drugs Market
Pharmacology
Alexipharmic Drugs Market
Pharmacology
Global Geriatric Medicines Market
Pharmacology
Antithrombotic Drugs Market
Pharmacology
Influenza Medication Market
Pharmacology
ACE Inhibitors Market
Pharmacology
Clot Busting Drugs Market
Pharmacology
Hyperkalemia Drugs Market
Pharmacology
Global Pharmacokinetics Services Market
Pharmacology
Aspirin API Market
Pharmacology
Alzheimer Drugs Market
Pharmacology
Anti-Hypertensive Drugs Market