
 Aspirin API Market | 2026-2036
Aspirin API Market Size, Share, and Industry Trends Forecast 2026-2036
Aspirin API Market Insights
CE marking under the EU's updated Active Substance Master File framework is consolidating documentation burdens for European-bound API exporters. Bayer AG leverages its integrated salicylic acid feedstock operations to sustain cost advantages across upstream synthesis. Alta Laboratories anchors South Asian supply through dedicated acetylsalicylic acid capacity at its Goa facility. Dr. Reddy's Laboratories competes on USDMF filing breadth, while Zydus Lifesciences dominates domestic Indian formulation demand with captive API consumption.
Aspirin API denotes acetylsalicylic acid produced to pharmacopoeial purity standards, typically synthesized via acetylation of salicylic acid with acetic anhydride under controlled temperature and catalytic conditions, yielding a crystalline powder with defined melting point and impurity profiles for tablet, capsule, or combination dosage manufacturing. Immediate release formulations occupy the largest volume share due to established cardiovascular prophylaxis protocols, while extended release variants command premium positioning in chronic pain management where gastric tolerability determines prescribing behavior. Pharmaceutical manufacturers represent the dominant procurement channel, though contract manufacturers are capturing share as Big Pharma outsources non-core API production to India-based partners.
FDA's Drug Master File Type II requirements and EMA's revised GMP Annex 1 for sterile APIs jointly elevate compliance investment thresholds for new market entrants. India's CDSCO harmonizes with ICH Q7 guidelines while enforcing BIS purity standards for domestic sale, creating dual-track regulatory navigation for exporters serving both regulated and emerging markets. Stakeholders must monitor API starting material traceability mandates as regulators tighten supply chain transparency expectations.
Market Dynamics
India's PLI scheme for active pharmaceutical ingredients is reshoring production capacity from Chinese suppliers, compressing established supply hierarchies and forcing European and North American buyers to requalify alternative sources.
Growth Catalysts
- Cardiovascular prevention protocols:Expanded prescribing guidelines for secondary stroke prevention are pulling bulk acetylsalicylic acid demand into hospital procurement systems across North America and Western Europe.
- EMA's revised Active Substance Master File framework:Consolidated documentation requirements are favoring suppliers with pre-existing European regulatory dossiers, accelerating market access for established Indian manufacturers.
- Continuous flow acetylation:Adoption of flow chemistry for salicylic acid acetylation is reducing batch-to-batch variability and cutting solvent waste volumes for Maharashtra-based producers.
Market Restraints
- Salicylic acid feedstock volatility:Phenol-derived starting material costs fluctuate with crude oil refining margins, squeezing contract manufacturer margins during upstream price spikes.
- Single-source dependency:China's dominance in phenol and acetic anhydride intermediates creates concentration risk that Indian formulators cannot fully hedge through domestic alternatives.
- Substitution by P2Y12 inhibitors:Clopidogrel and ticagrelor are displacing aspirin in high-risk cardiovascular regimens where dual antiplatelet therapy duration shortens.
Strategic Opportunities
- Latin American generics penetration:Underdeveloped local API manufacturing in Brazil and Mexico creates import dependency that Indian exporters with ANVISA registrations can capture.
- Combination dosage expansion:Fixed-dose combinations with statins or antihypertensives are opening formulation channels beyond standalone aspirin tablets.
- FDA's emerging market inspection reciprocity pilots:Mutual recognition frameworks with India's CDSCO could compress approval timelines for USDMF filings from Goa and Hyderabad clusters.
Industry Challenges
- ICH Q7 technical specialist scarcity:Qualified persons with combined synthetic organic chemistry and GMP audit experience command premium compensation, constraining mid-tier manufacturer expansion.
- Starting material traceability mandates:Regulators now require documented phenol and acetic anhydride supply chains back to petrochemical origin, extending qualification timelines for new raw material suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aspirin API Market |
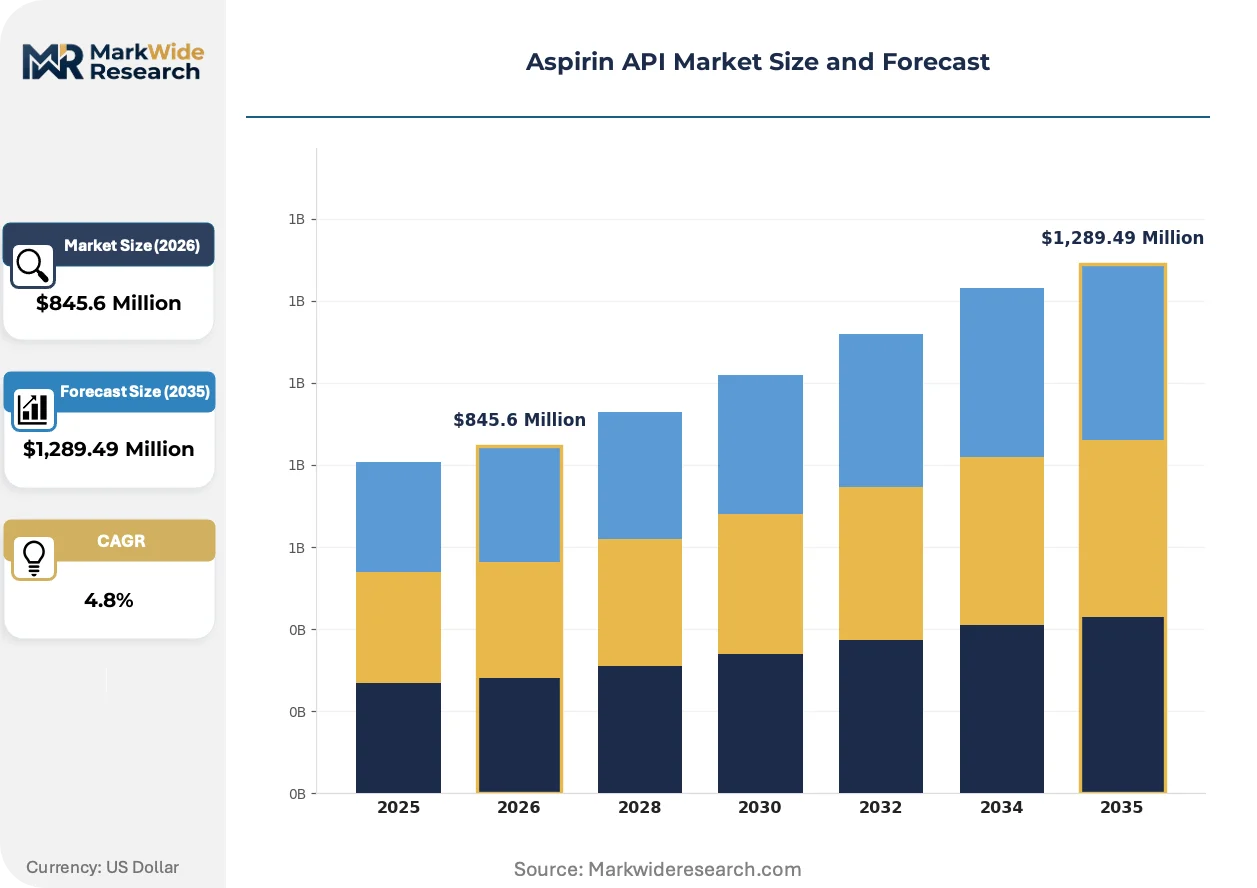
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $1,289.49 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetylsalicylic Acid, Immediate Release, Extended Release, Buffered Formulation End User: Pharmaceutical Manufacturers, Contract Manufacturers, Research Institutions, Biotechnology Firms Application: Pain Relief, Anti-Inflammatory, Cardiovascular Treatments, Antipyretic Use Distribution Channel: Direct Sales, Online Platforms, Wholesale, Specialty Distributors |
| Companies Covered | Bayer AG, Metrochem API Private Limited, Alta Laboratories, Globela Pharma Pvt Ltd, Dr. Reddy’s Laboratories Ltd, Sun Pharmaceutical Industries Ltd, Zydus Lifesciences, Teva Pharmaceutical Industries Ltd, Jiangsu Nanjing Huaxing Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aspirin API Market Trends and Innovations
Process intensification and regulatory data harmonization are compressing the traditional API development cycle, while buyer consolidation among contract manufacturers is reshaping supplier qualification protocols.
Continuous manufacturing platforms for acetylsalicylic acid synthesis are unifying reaction, crystallization, and drying into single-unit operations. Pharmaceutical manufacturers with high-volume cardiovascular portfolios are adopting these systems to reduce solvent inventory and labor intensity. This technology is unifying quality assurance with real-time release testing, collapsing the traditional 30-day quarantine period for API batches.
REACH registration requirements for salicylic acid derivatives are tightening substance volume tracking and safety data sheet obligations for European-bound exports. ECHA's updated guidance on chemical intermediates is forcing Indian suppliers to commission additional toxicology studies. Small-volume exporters lacking dedicated regulatory affairs teams are exiting the EU market, concentrating supply among dossier-rich incumbents.
Hospital group purchasing organizations are consolidating API procurement under sole-source contracts with pre-qualified Indian manufacturers. Contract manufacturers serving Big Pharma are displacing open-market spot purchases with multi-year supply agreements indexed to raw material costs. This concentration is most visible in Maharashtra, where Pune-based formulators now source 70 percent of aspirin API from three Goa-based producers under exclusive arrangements.
Aspirin API Market Segmentation
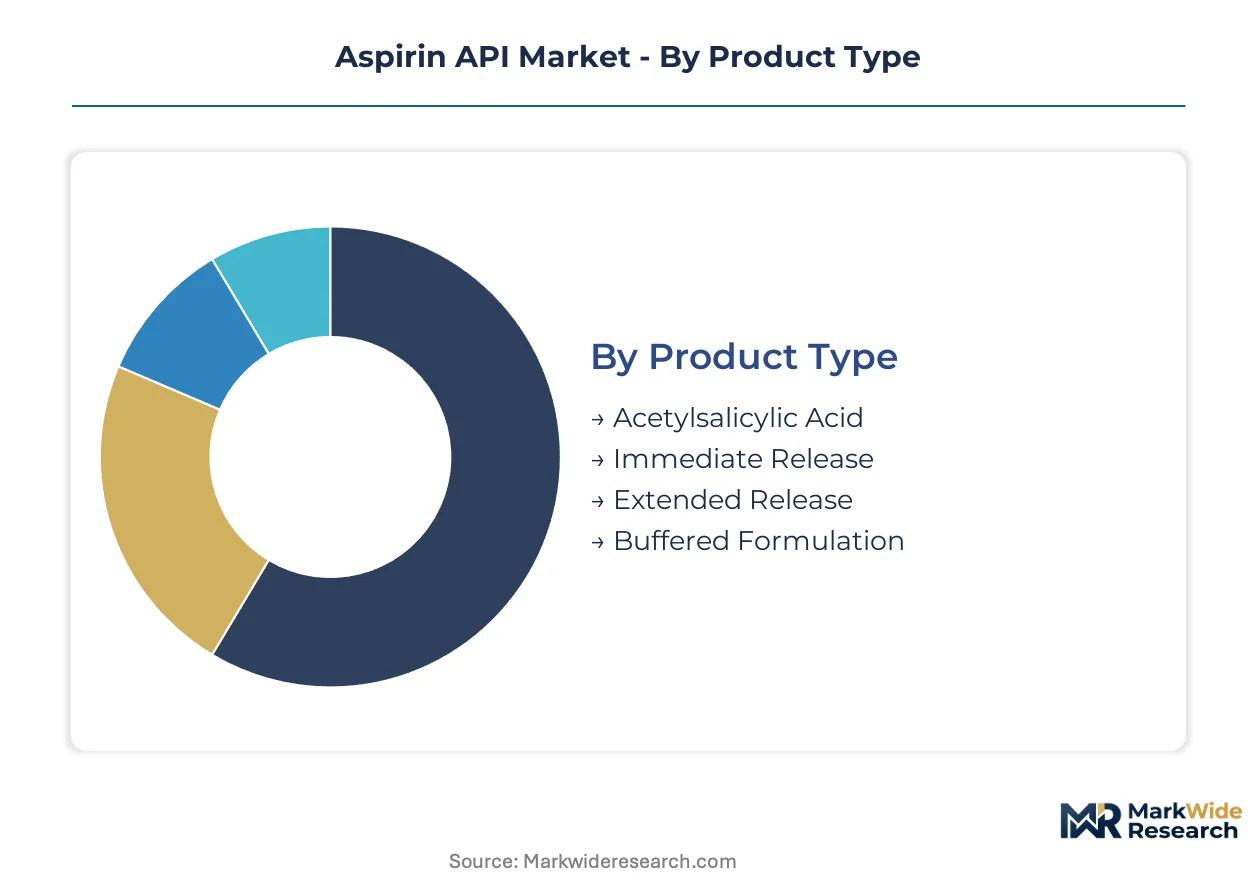
Acetylsalicylic acid procurement patterns diverge sharply across formulation physics, buyer sophistication, and therapeutic indication. Specification tiers determine regulatory pathway complexity and manufacturing technology requirements for each segment.
Product Type:
Crystalline morphology and dissolution kinetics separate commercial grades, with processing intensity escalating from standard acid to modified-release architectures.
- Acetylsalicylic Acid:Standard pharmacopoeial grade with defined melting point and impurity profiles serves high-volume tablet manufacturing. Maharashtra's chemical belt concentrates procurement for domestic Indian formulation houses under BIS purity mandates.
- Immediate Release:Rapid dissolution specifications dominate cardiovascular prophylaxis protocols where absorption speed determines therapeutic efficacy. Hospital procurement systems across North America and Western Europe pull bulk volumes through sole-source contracts.
- Extended Release:Matrix-controlled dissolution reduces gastric irritation for chronic pain patients. Premium positioning commands higher unit economics where gastric tolerability drives prescribing behavior in European markets.
- Buffered Formulation:Antacid-combined variants address pH-sensitive patient populations with modified stability profiles.
Mature deployment sits with Acetylsalicylic Acid. Newer deployment is concentrated in Extended Release.
End User:
Buyer scale and regulatory sophistication stratify procurement channels, from captive pharmaceutical consumption to outsourced manufacturing partnerships.
- Pharmaceutical Manufacturers:Integrated formulation houses consume API for in-house tablet and combination dosage production. Zydus Lifesciences anchors domestic Indian demand through captive consumption at Gujarat facilities.
- Contract Manufacturers:Third-party producers serving Big Pharma are capturing share as non-core API production migrates to India-based partners. CDSCO-GMP compliance distinguishes qualified suppliers from spot-market traders.
- Research Institutions:Small-batch procurement for clinical trial material and pharmacokinetic studies requires documented Certificate of Analysis chains.
- Biotechnology Firms:Niche demand for high-purity grades in novel delivery system development.
Volume concentration favors Pharmaceutical Manufacturers. Capability investment is accelerating fastest among Contract Manufacturers.
Application:
Therapeutic indication determines purity thresholds, with cardiovascular applications imposing the most stringent impurity control regimes.
- Cardiovascular Treatments:Secondary stroke prevention protocols require ultra-low salicylic acid content per USP-NF monographs. Expanded prescribing guidelines are pulling bulk demand into hospital procurement systems.
- Pain Relief:Analgesic applications tolerate broader impurity windows, enabling cost-optimized production for over-the-counter markets.
- Anti-Inflammatory:Rheumatoid arthritis regimens demand consistent batch potency for chronic dosing schedules.
- Antipyretic Use:Fever reduction applications concentrate in pediatric and emergency medicine formulations with taste-masking requirements.
Regulatory scrutiny is tightest for Cardiovascular Treatments. Volume expansion is climbing the fastest in Antipyretic Use.
Distribution Channel:
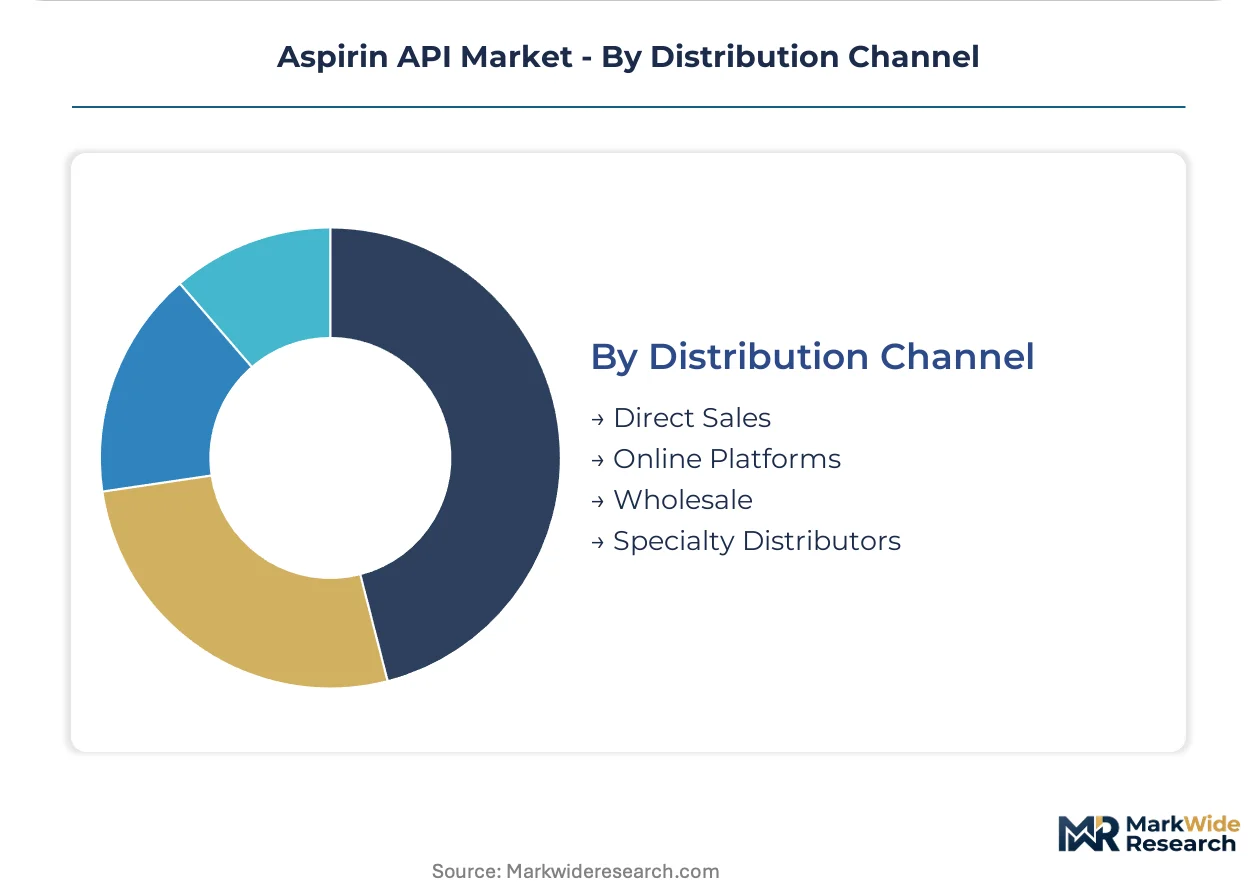
Channel selection reflects buyer scale, with large manufacturers bypassing intermediaries while smaller formulators rely on specialized logistics.
- Direct Sales:Multi-year supply agreements with pre-qualified Indian producers now dominate Maharashtra-Pune formulator procurement. Raw material cost indexing protects margin stability during phenol feedstock spikes.
- Wholesale:Open-market spot purchases persist for mid-tier manufacturers lacking volume scale for exclusive arrangements.
- Specialty Distributors:Cold-chain and documentation-intensive shipments for EU-bound exports requiring REACH-registered substance tracking.
- Online Platforms:Emerging channel for small-batch research grade procurement with digitized Certificate of Analysis access.
Relationship depth is greatest through Direct Sales. Digital penetration is expanding most quickly via Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Pharmaceutical Park scheme in Goa and Maharashtra anchors API production concentration, with tax incentives and subsidized infrastructure drawing acetylsalicylic acid manufacturers away from coastal Chinese competitors.
United States
Hospital procurement systems are consolidating aspirin API purchases under sole-source contracts with pre-qualified Indian suppliers. FDA's Drug Master File Type II requirements elevate compliance barriers for new entrants. New Jersey-based pharmaceutical distributors now route 60 percent of cardiovascular-grade acetylsalicylic acid through direct agreements with Goa manufacturers.
Germany
Bayer AG maintains integrated salicylic acid-to-API operations that supply European formulation houses. REACH registration requirements for salicylic acid derivatives tighten substance tracking obligations. Leverkusen's chemical complex anchors the continent's largest dedicated acetylsalicylic acid capacity.
India
Pharmaceutical manufacturers in Maharashtra are scaling bulk procurement as cardiovascular prevention protocols widen. CDSCO harmonizes with ICH Q7 guidelines while enforcing BIS purity standards for domestic sale. Pune-based formulators source 70 percent of requirements from three Goa-based producers under exclusive arrangements.
China
Phenol and acetic anhydride intermediates dominate upstream supply, creating concentration risk that Indian formulators cannot fully hedge. NMPA's revised GMP standards for active substances tighten documentation burdens. Jiangsu province's chemical manufacturers face margin compression as Indian PLI schemes reshore downstream API demand.
Brazil
Underdeveloped local API manufacturing creates import dependency for generic aspirin tablet producers. ANVISA registration requirements favor established Indian exporters with pre-existing dossier experience. São Paulo's pharmaceutical distribution corridor channels acetylsalicylic acid from Mumbai-Goa suppliers into Latin American formulation houses.
Aspirin API Market Competitive Landscape
Indian producers anchor the contract manufacturing tier; European integrated specialists hold the premium regulated-market position. The vendor base splits between dossier-rich incumbents with CE-marked Active Substance Master Files and mid-tier manufacturers competing on spot-market pricing. Three archetypes dominate: backward-integrated salicylic acid producers, CDSCO-GMP compliant exporters, and research-grade specialists serving clinical trial material demand. Capacity expansion and multi-year supply agreement indexing represent the dominant competitive moves.
Among integrated German manufacturers, Bayer AG exemplifies the backward-integrated archetype through captive salicylic acid feedstock operations. Indian specialists including Alta Laboratories and Dr. Reddy's Laboratories occupy positions within the export-compliant tier, with Goa-based facilities serving European and North American qualification protocols. These three entities represent the structural spectrum from upstream chemical integration to regulatory dossier breadth.
| Leading Market Players |
|---|
| Bayer AG |
| Metrochem API Private Limited |
| Alta Laboratories |
| Globela Pharma Pvt Ltd |
| Dr. Reddy's Laboratories Ltd |
| Sun Pharmaceutical Industries Ltd |
| Zydus Lifesciences |
| Teva Pharmaceutical Industries Ltd |
| Jiangsu Nanjing Huaxing Chemical Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Captive salicylic acid production anchors Bayer AG's cost position across European formulation supply while Indian contract manufacturers absorb phenol feedstock volatility through raw-material-indexed multi-year agreements with Maharashtra-based buyers. This integration choice separates dossier-rich incumbents commanding premium positioning from spot-market competitors exposed to acetic anhydride price swings.
Pricing Analysis
Short lead-time premiums apply to cardiovascular-grade batches qualifying under FDA Drug Master File Type II requirements, while spot inventory discounts characterize open-market standard pharmacopoeial grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier—CE-marked Active Substance Master Files command highest positioning, BIS-compliant domestic grades occupy mid-tier, and unregistered spot material sits at the base. Cost compression in standard-grade supply is intensifying because Indian PLI scheme capacity additions expand qualified supplier pools. Hospital procurement systems demonstrate least price sensitivity due to sole-source contract structures, whereas mid-tier contract manufacturers exhibit highest sensitivity to phenol-derived input fluctuations.
Supply Chain Analysis
Dual-sourcing requirements now mandate Maharashtra-based formulators qualify at least two Goa producers simultaneously, compressing single-source dependency risks that previously concentrated 70 percent of Pune requirements with three suppliers. Geographic supply concentration centers on India, China, and Germany as dominant production nodes. Raw material dependencies rest on phenol from crude oil refining, acetic anhydride from petrochemical streams, and salicylic acid intermediates. Single-source vulnerability in Chinese phenol supply creates structural exposure Indian formulators cannot fully hedge. Distribution runs through direct multi-year agreements for large manufacturers, supplemented by specialty distributors handling REACH-registered EU-bound shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cost-of-compliance dynamics define competitive moats in this market, with EMA's revised Active Substance Master File framework erecting documentation barriers that dossier-poor entrants cannot readily scale.
For Market Incumbents: Lock in exclusive supply relationships with Maharashtra's Pune-based formulators before PLI scheme capacity expansions proliferate qualified alternatives. Secure backward integration into salicylic acid feedstock or captive phenol supply contracts to insulate margin structures from upstream volatility. P2Y12 inhibitor substitution in cardiovascular regimens threatens volume concentration in immediate-release segments. For New Entrants and Emerging Players: FDA's emerging market inspection reciprocity pilots with India's CDSCO open a window for Goa-based producers to compress USDMF approval timelines relative to established competitors. Target Latin American generics penetration in Brazil and Mexico where ANVISA registration experience concentrates among Indian exporters. Pursue combination dosage channels—fixed-dose aspirin-statin or antihypertensive formulations—where formulation complexity deters commodity spot-market players. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of CDSCO-GMP compliant facilities with pre-existing European regulatory dossiers, as regulatory qualification timelines extend buyer willingness-to-pay for de-risked assets. Long-term viability favors backward-integrated producers or those with locked multi-year supply agreements indexed to raw material costs. Monitor FDA-CDSCO mutual recognition framework advancement as inflection indicator for US market access compression.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Acetylation Adoption | Maharashtra-based producers reduce solvent waste and batch variability through flow chemistry implementation. |
| REACH Registration Completion | ECHA compliance enables sustained European market access as small-volume exporters exit. |
| Multi-Year Supply Agreement Indexing | Raw material cost protection stabilizes margins during phenol feedstock price spikes. |
| Salicylic Acid Backward Integration | Captive feedstock supply insulates Bayer AG and aspirant competitors from intermediate volatility. |
| Combination Dosage Pipeline Expansion | Fixed-dose statin-aspirin formulations open therapeutic channels beyond standalone tablets. |
Research Methodology
Document review covered FDA Drug Master File Type II submissions, EMA Active Substance Master File registrations, CDSCO GMP inspection records, and REACH substance volume tracking data, complemented by interviews with regulatory affairs directors at Indian API exporters, procurement managers at Maharashtra formulation houses, and supply chain leads at European pharmaceutical distributors. Secondary validation drew from customs trade statistics, BIS purity standard filings, and ICH Q7 guideline implementation assessments. Bottom-up capacity modeling and top-down demand triangulation cross-verified volume estimates.
Segment-level projections across formulation type, therapeutic application, and buyer channel were generated through the analytical framework over the projection horizon. CAGRs were derived from weighted average growth contributions across cardiovascular prophylaxis expansion, pain management substitution patterns, and antipyretic volume acceleration. Forecast inputs incorporated PLI scheme capacity addition schedules, EMA documentation consolidation timelines, and hospital procurement system consolidation trajectories.
The model assumes a particular technology adoption path; alternative pathways for continuous flow acetylation or crystallization automation would alter the outlook for Maharashtra-based cost competitiveness. Forecasts reflect assumptions regarding CDSCO-FDA mutual recognition progression, phenol supply chain stability, and P2Y12 inhibitor substitution rates. Deviation in regulatory reciprocity timelines or upstream petrochemical feedstock disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
UK Pharmacovigilance Market
Pharmacology
Apixaban Market
Pharmacology
Cough Remedies Market
Pharmacology
Artemisinin Antimalarial Drugs Market
Pharmacology
Drug Eruptions Treatment Market
Pharmacology
Ketoprofen API Market
Pharmacology
Global Geriatric Medicines Market
Pharmacology
Angiotensin II Receptor Blockers (Arbs) Market
Pharmacology
Huoxiang Zhengqi Drug Market
Pharmacology
Alexipharmic Drugs Market
Pharmacology
Influenza Medication Market
Pharmacology
ACE Inhibitors Market
Pharmacology
Semaglutide API Market
Pharmacology
Hyperkalemia Drugs Market
Pharmacology
Alzheimer's Therapeutics Market
Pharmacology
Hypertension Drug Market