
 Aldosterone Receptor Antagonists Market | 2026-2036
Aldosterone Receptor Antagonists Market Size, Share, and Industry Trends Forecast 2026-2036
Aldosterone Receptor Antagonists Market Outlook
The manufacturing scale gap between large pharmaceutical conglomerates and mid-size generics producers is bifurcating competitive dynamics in aldosterone receptor antagonists. Bayer leverages its integrated active pharmaceutical ingredient operations to sustain cost advantages across European distribution networks. Pfizer Inc competes through specialized cardiovascular therapeutic franchises that anchor its hospital formulary presence. Novartis differentiates via deep clinical trial infrastructure that supports regulatory submissions for mineralocorticoid receptor modulators.
Aldosterone receptor antagonists are steroidal compounds that competitively inhibit mineralocorticoid receptors in renal distal tubules and vascular smooth muscle, with eplerenone exhibiting greater receptor selectivity than spironolactone to reduce gynecomastia risk in heart failure patients. These agents functionally suppress sodium reabsorption and myocardial fibrosis, serving as cornerstone therapies in guideline-directed medical therapy for reduced ejection fraction heart failure. Spironolactone occupies the mature volume position in hypertension and edema management where generic pricing pressures compress margins, while eplerenone captures premium positioning in post-myocardial infarction heart failure with elevated cardiovascular risk profiles. Oral delivery dominates prescribing patterns across hospitals and retail pharmacies, though intravenous formulations are gaining traction in acute decompensated heart failure settings where rapid hemodynamic stabilization is required.
FDA cardiovascular and renal drug advisory committees shape trial design requirements for new mineralocorticoid receptor antagonists, while EMA's Committee for Medicinal Products for Human Use enforces centralized cardiovascular safety assessments across European marketing authorizations. The EU MDR intensifies post-market surveillance obligations for implantable and drug-device combination products that may incorporate sustained-release aldosterone antagonist formulations. Stakeholders must monitor evolving pharmacovigilance mandates and health technology assessment criteria that determine reimbursement access for next-generation selective mineralocorticoid receptor modulators.
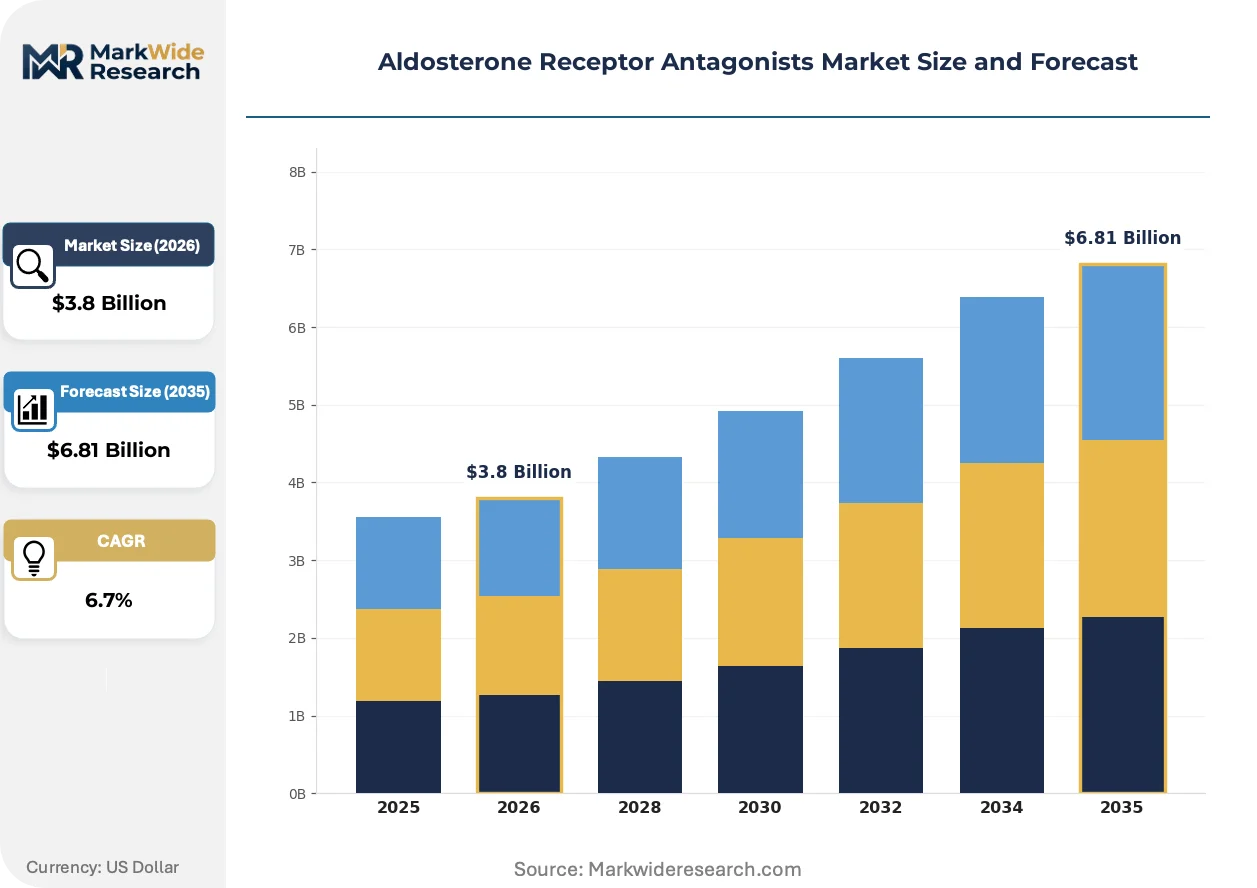
Market Dynamics
Cardiology departments in hospital systems are expanding prescription volumes for heart failure protocols, tightening formulary control over mineralocorticoid receptor antagonists and compressing margins for non-selective agents.
Growth Catalysts
- EMA cardiovascular safety assessments:Centralized marketing authorization requirements across European member states are standardizing evidence thresholds, accelerating regulatory clarity for new entrants.
- Chronic kidney disease management programs:Dedicated care pathways in the United States, Germany, and Japan are institutionalizing aldosterone antagonist use in nephrology protocols.
- Intravenous formulation development:Acute decompensated heart failure settings are driving demand for rapid hemodynamic stabilization options beyond oral delivery.
Market Restraints
- Spironolactone generic pricing:Mature volume positioning in hypertension and edema management compresses margins, limiting R&D reinvestment capacity for established producers.
- FDA evidence requirements:Tightening trial design mandates for new mineralocorticoid receptor blockers extend development timelines and inflate clinical infrastructure costs.
- Eplerenone selectivity premium:Higher manufacturing complexity for receptor-specific compounds constrains supply elasticity relative to non-selective alternatives.
Strategic Opportunities
- Post-myocardial infarction protocols:Elevated cardiovascular risk profiles in acute coronary syndrome survivors represent underpenetrated positioning for selective receptor modulators.
- Drug-device combination products:EU MDR post-market surveillance obligations for sustained-release formulations create first-mover advantages for integrated delivery systems.
- Health technology assessment criteria:Evolving reimbursement access pathways for next-generation selective agents reward deep clinical trial infrastructure investments.
Industry Challenges
- Pharmacovigilance mandates:FDA cardiovascular and renal drug advisory committee oversight requires continuous safety monitoring infrastructure that strains mid-size generics producers.
- Active pharmaceutical ingredient scale:Manufacturing capacity gaps between integrated conglomerates and external suppliers create supply assurance risks during volume surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aldosterone Receptor Antagonists Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eplerenone, Spironolactone, Canrenone, Others Therapy Area: Hypertension, Heart Failure, Chronic Kidney Disease, Edema End User: Hospitals, Clinics, Homecare Settings, Retail Pharmacies Delivery Mode: Oral, Injectable, Intravenous, Sublingual |
| Companies Covered | Merck & Co, Bayer, Pfizer Inc, Novartis, GlaxoSmithKline, Johnson & Johnson, Sanofi, Boehringer Ingelheim, Otsuka Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aldosterone Receptor Antagonists Market Strategic Shifts
Receptor selectivity engineering and delivery modality diversification are fragmenting competitive positioning across acute and chronic care settings. Formulation innovation is reshaping hospital formulary negotiations.
Next-generation non-steroidal mineralocorticoid receptor antagonists are displacing legacy steroidal compounds in heart failure with preserved ejection fraction trials. Cardiology research consortia in the United States and Japan are accelerating patient recruitment for these agents. The shift is compressing addressable market assumptions for established spironolactone and eplerenone franchises.
EU MDR intensifies post-market surveillance obligations for implantable and drug-device combination products incorporating sustained-release aldosterone antagonist formulations. Manufacturers must establish centralized safety databases across European distribution networks. Cardiovascular therapeutic franchises with existing pharmacovigilance infrastructure capture compliance cost advantages.
Hospital procurement committees are consolidating mineralocorticoid receptor antagonist purchasing through therapeutic class contracts rather than molecule-specific negotiations. Integrated delivery networks in the United States are unbundling acute and chronic care prescribing rights. This concentration shifts pricing leverage toward formulary managers and away from individual physician preference.
Aldosterone Receptor Antagonists Market Segmentation
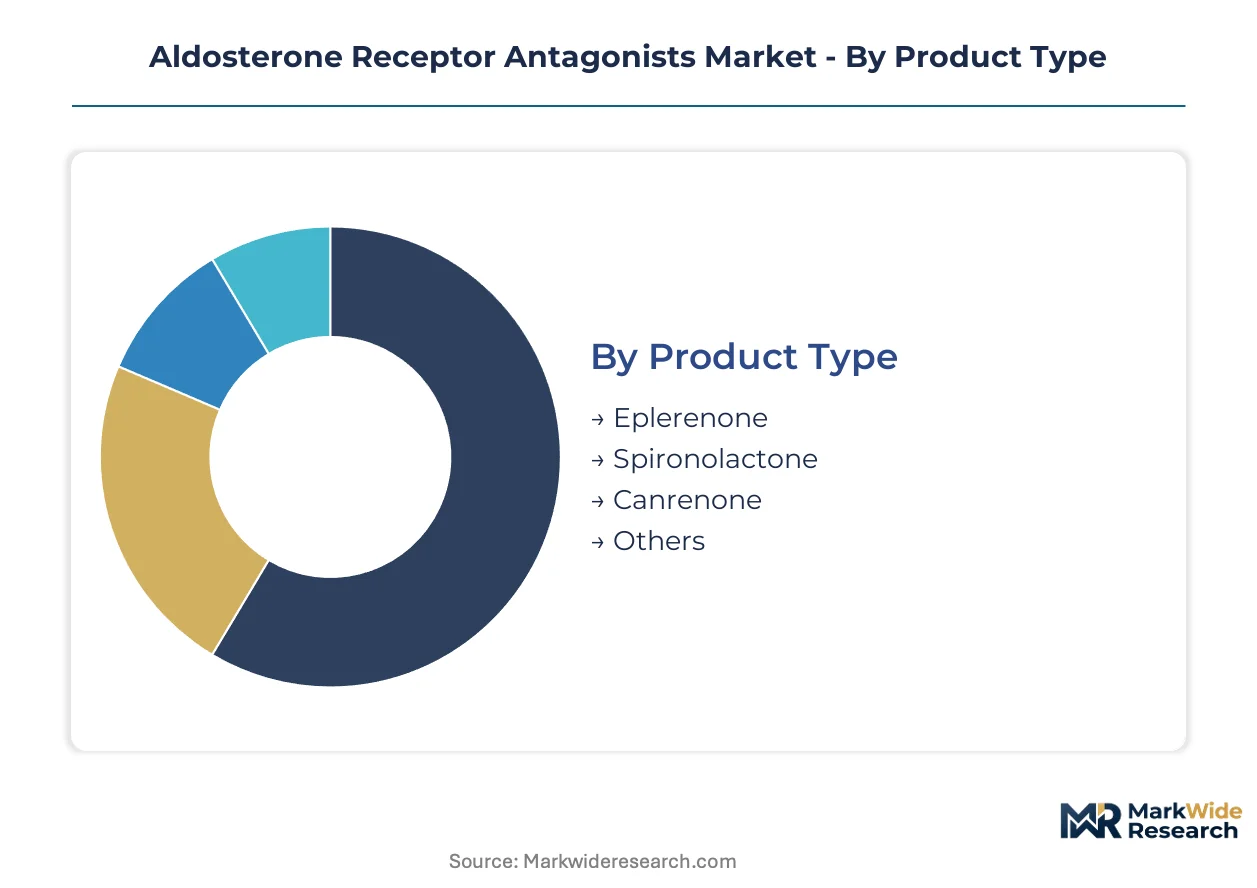
Segmentation in aldosterone receptor antagonists reveals how receptor selectivity, clinical setting, and delivery urgency fragment prescribing patterns across cardiology and nephrology protocols. Understanding these divides exposes where next-generation non-steroidal agents threaten incumbent positions.
Product Type:
Substitution pressure from next-generation non-steroidal mineralocorticoid receptor antagonists weighs most heavily on legacy steroidal compounds, particularly where gynecomastia risk and endocrine side effects drive formulary reassessment.
- Eplerenone:A 9,11-epoxy-derivative of spironolactone with 500-fold greater selectivity for mineralocorticoid over androgen and progesterone receptors. Demand concentrates in post-myocardial infarction heart failure protocols across US hospital systems, where FDA cardiovascular guidelines reward reduced endocrine liability with preferred formulary tier placement.
- Spironolactone:The prototypical 17-spirolactone steroidal compound with potent but non-selective mineralocorticoid antagonism. Volume leadership in hypertension and edema management persists in Germany and Japan, though generic pricing compression in retail pharmacy channels constrains manufacturer margins.
- Canrenone:The active metabolite of spironolactone with equivalent pharmacological activity but modified pharmacokinetics. Prescribing remains concentrated in select European markets where national formularies retain historical reimbursement preferences.
- Others:Emerging non-steroidal scaffolds including finerenone and esaxerenone currently in Phase III and marketed positions in Japan. Development pipelines target heart failure with preserved ejection fraction where steroidal agents demonstrate limited efficacy.
Spironolactone retains volume leadership; non-steroidal alternatives in development hold the steepest expansion curve.
Therapy Area:
Cost tier stratification separates acute intervention protocols from chronic maintenance regimens, with reimbursement intensity varying sharply across hospital-based versus outpatient care pathways.
- Heart Failure:Reduced ejection fraction protocols in US academic medical centers anchor guideline-directed medical therapy demand. EMA centralized assessments for new mineralocorticoid receptor modulators prioritize cardiovascular mortality endpoints in this indication.
- Chronic Kidney Disease:Dedicated management programs in Japan and Germany are institutionalizing aldosterone antagonist use in diabetic nephropathy protocols. PMDA and EMA have both approved finerenone for this indication, accelerating segment expansion.
- Hypertension:Resistant hypertension represents a residual indication where spironolactone's low cost sustains positioning against renin-angiotensin alternatives. Retail pharmacy dispensing dominates this volume-heavy, margin-thin segment.
- Edema:Cirrhosis and nephrotic syndrome applications persist in hospital formulary maintenance, though diuretic combination therapies increasingly displace standalone mineralocorticoid blockade.
Heart failure commands premium pricing tiers; chronic kidney disease applications are climbing the fastest as regulatory approvals accumulate.
End User:
Customer type fragmentation reflects divergent procurement authority, with integrated delivery networks consolidating purchasing power while homecare channels fragment decision-making.
- Hospitals:Cardiology departments in US health systems exercise therapeutic class contracting authority over mineralocorticoid receptor antagonists. Formulary committees prioritize intravenous formulation availability for acute decompensated heart failure.
- Clinics:Outpatient cardiology and nephrology practices in Germany manage chronic therapy initiation and titration. EMA pharmacovigilance mandates for mineralocorticoid receptor modulators concentrate adverse event reporting through these settings.
- Homecare Settings:Post-discharge heart failure management programs in Japan leverage remote monitoring to sustain adherence. Reimbursement pathways for home infusion of investigational intravenous formulations remain underdeveloped.
- Retail Pharmacies:Generic spironolactone dispensing dominates volume in this channel, with pharmacy benefit managers applying maximum allowable cost constraints across US commercial and Medicare Part D plans.
Hospitals retain volume leadership; homecare settings hold the steepest expansion curve as remote patient monitoring infrastructure matures.
Delivery Mode:
Application urgency creates a maturity gradient, with acute care modalities attracting development investment while established oral formats face commoditization.
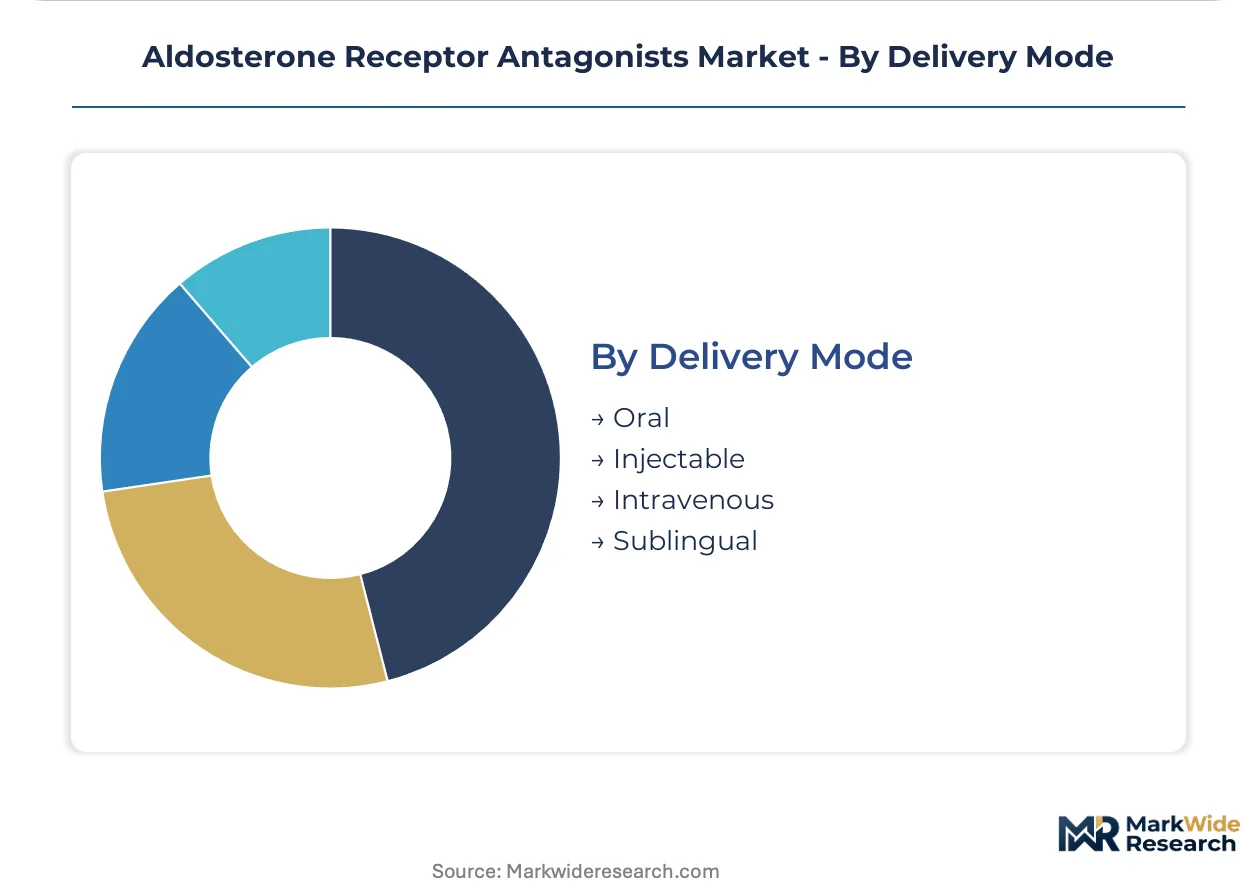
- Oral:Tablet and suspension formulations dominate maintenance therapy across all therapy areas. Manufacturing scale advantages for immediate-release oral dosage forms sustain cost competitiveness against novel delivery alternatives.
- Intravenous:Acute decompensated heart failure settings in US hospitals drive demand for rapid hemodynamic stabilization. Development programs target bioequivalent exposure profiles to enable seamless oral-to-intravenous transitions.
- Injectable:Subcutaneous depot formulations in early development aim to address adherence gaps in chronic kidney disease. PMDA has granted Sakigake designation to one Japanese-developed sustained-release injectable candidate.
- Sublingual:Rapid-onset formulations for hypertensive emergency applications remain preclinical, with absorption variability challenges constraining clinical translation.
Oral delivery retains volume leadership; intravenous formulations hold the steepest expansion curve as acute heart failure protocols evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Generic spironolactone pricing compresses margins in German and Japanese retail channels, while US hospital systems absorb premium eplerenone costs through therapeutic class contracts. Demand elasticity diverges sharply between acute care settings and chronic maintenance populations.
United States
Academic medical centers in Boston and Houston anchor guideline-directed medical therapy adoption for reduced ejection fraction heart failure. FDA cardiovascular and renal drug advisory committees enforce tightening trial design requirements for new mineralocorticoid receptor blockers. Integrated delivery networks across the Southeast consolidate purchasing authority through therapeutic class contracts rather than molecule-specific negotiations.
Germany
Chronic kidney disease management programs in Bavaria and North Rhine-Westphalia institutionalize aldosterone antagonist use in diabetic nephropathy protocols. EMA centralized marketing authorization requirements standardize evidence thresholds across member states. Outpatient cardiology practices in Berlin manage chronic therapy titration under intensified pharmacovigilance mandates.
Japan
PMDA approvals for finerenone in diabetic kidney disease accelerate nephrology protocol expansion in Tokyo and Osaka metropolitan areas. The country's national pharmaceutical regulator grants Sakigake designation to sustained-release injectable candidates. Remote patient monitoring infrastructure in Kansai sustains post-discharge heart failure adherence programs.
United Kingdom
NHS England formulary committees prioritize cost-effectiveness assessments for mineralocorticoid receptor modulators in heart failure pathways. NICE technology appraisals determine reimbursement access for next-generation selective agents. Clinical trial infrastructure in London and Cambridge supports cardiovascular mortality endpoint studies for emerging non-steroidal scaffolds.
France
Hospital procurement centralization in Île-de-France compresses margins for non-selective agents through volume-based tendering. ANSM pharmacovigilance oversight concentrates adverse event reporting through outpatient cardiology settings. Research consortia in Lyon accelerate patient recruitment for heart failure with preserved ejection fraction trials.
Aldosterone Receptor Antagonists Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the aldosterone receptor antagonists landscape. Integrated pharmaceutical conglomerates with captive active pharmaceutical ingredient operations sustain cost advantages in high-volume oral generics. Mid-size specialists with deep clinical trial infrastructure capture premium positioning for receptor-selective compounds. Competitive dynamics center on formulary control negotiations and regulatory submission speed rather than manufacturing scale alone. Strategic moves concentrate on therapeutic class contracting authority and pharmacovigilance infrastructure investments.
Among integrated conglomerates, Bayer and Pfizer Inc exemplify divergent competitive positioning. Bayer leverages in-house production of steroidal compounds to defend margin position in European distribution networks. Pfizer Inc anchors hospital formulary presence through specialized cardiovascular therapeutic franchises. Novartis occupies a distinct tier through clinical trial infrastructure that supports regulatory submissions for mineralocorticoid receptor modulators. These three entities represent the dominant archetypes: cost-integrated manufacturers, formulary-anchored franchises, and trial-capability specialists.
| Leading Market Players |
|---|
| Merck & Co |
| Bayer |
| Pfizer Inc |
| Novartis |
| GlaxoSmithKline |
| Johnson & Johnson |
| Sanofi |
| Boehringer Ingelheim |
| Otsuka Pharmaceutical |
| Others |
Value Chain & Pricing Dynamics
Ninety-day API inventory buffers at European formulation plants concentrate pricing leverage among integrated manufacturers with captive steroidal compound production. This lead-time band separates cost-integrated conglomerates from mid-size generics producers exposed to spot market potassium canrenoate volatility. Hospital procurement committees exploit this asymmetry through therapeutic class contracting that compresses margins for non-selective agents.
Pricing Analysis
After-sales pharmacovigilance service contracts drive lifetime value for mineralocorticoid receptor modulators facing intensified FDA adverse event reporting mandates. Three-tier pricing structure across premium, standard, and economy levels separates eplerenone's receptor-selective positioning from spironolactone's generic commoditization. Cost compression in the oral maintenance tier stems from pharmacy benefit manager maximum allowable cost constraints. Retail pharmacy channels exhibit highest price sensitivity; academic medical centers absorb premium positioning for reduced endocrine liability.
Supply Chain Analysis
Strait of Hormuz transit vulnerability for Indian-imported bulk steroidal intermediates constrains European formulation capacity during volume surges. Active pharmaceutical ingredient production concentrates in India, China, and Italy for synthetic steroidal scaffolds. Manufacturing rests on hecogenin-derived sapogenin feedstocks, potassium salt precursors, and specialized epoxidation catalysts. Single-source vulnerability for 9,11-epoxy-derivative intermediates elevates supply assurance risk. Distribution runs through hospital procurement centralization in Germany and integrated delivery network formularies in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as chronic kidney disease management programs institutionalize aldosterone antagonist protocols ahead of heart failure with preserved ejection fraction regulatory approvals. Finerenone's PMDA endorsement in diabetic nephropathy signals penetration tailwinds across nephrology care pathways.
For Market Incumbents: Fortify pharmacovigilance infrastructure investments to capture compliance cost advantages under EU MDR post-market surveillance obligations. Deepen backward integration into steroidal API operations to defend margin position against Indian and Chinese bulk intermediate suppliers. Non-steroidal mineralocorticoid receptor antagonist displacement in heart failure with preserved ejection fraction trials threatens established eplerenone franchises. For New Entrants and Emerging Players: Anchor in post-myocardial infarction protocols across US Southeast integrated delivery networks where therapeutic class contracting creates white-space for selective receptor modulators. Target chronic kidney disease applications in Japan's metropolitan nephrology clinics as finerenone reimbursement pathways mature. Pursue hospital formulary access through intravenous formulation partnerships with acute decompensated heart failure service lines. For Investors and Strategic Acquirers: Carve-out targets emerge from large pharmaceutical conglomerates divesting mature cardiovascular therapeutic franchises to refocus on oncology and immunology pipelines. Five-to-ten year viability hinges on clinical trial infrastructure depth supporting next-generation non-steroidal submissions. Watch FDA cardiovascular and renal drug advisory committee trial design mandates as inflection indicators for development timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Deep trial infrastructure accelerates regulatory submissions for mineralocorticoid receptor modulators under EMA centralized assessments. |
| Regulatory Approval Pathway | PMDA Sakigake designation for sustained-release injectables compresses development timelines for Japanese nephrology protocols. |
| Backward Integration | In-house steroidal API production defends margin position against potassium canrenoate spot market volatility in European distribution. |
| Hospital System Partnership | Therapeutic class contracting authority with US academic medical centers anchors formulary presence for acute decompensated heart failure. |
| Reimbursement Strategy | NICE technology appraisals determine access for next-generation selective agents in NHS England heart failure pathways. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up prescription volume modeling and top-down therapeutic class expenditure analysis were triangulated to constrain estimate variance.
Across the analysis window, segmentation dimensions included receptor selectivity tier, therapy area, end-user channel, and delivery modality. CAGRs were derived from patient population epidemiology, protocol penetration assumptions, and pricing trajectory modeling. Forecast inputs incorporated PMDA approval timelines for diabetic kidney disease indications and EU MDR surveillance cost inflation.
Decision-makers should treat outputs as directional under stable regulatory evidence thresholds; material deviation in FDA trial design mandates or EMA centralized assessment timelines would warrant model refresh. Practitioners should keep alternative scenarios live as non-steroidal mineralocorticoid receptor antagonist clinical readouts in heart failure with preserved ejection fraction evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Drug Repurposing Market
Pharmacology
Semaglutide API Market
Pharmacology
Intranasal Drug and Vaccine Delivery Market
Pharmacology
Antitussive Drugs Market
Pharmacology
Hydroxychloroquine Drugs Market
Pharmacology
Global Geriatric Medicines Market
Pharmacology
Cough Remedies Market
Pharmacology
Anti Inflammatory Therapeutics Market
Pharmacology
Prescription Narcotic Cough Preparations and Expectorants Market
Pharmacology
Attention Deficit Hyperactivity Disorder (ADHD) Therapeutics Market
Pharmacology
Drug Eruptions Treatment Market
Pharmacology
Antithrombotic Drugs Market
Pharmacology
Immunotherapy Drugs Market
Pharmacology
Medication Adherence Market
Pharmacology
Aspirin API Market
Pharmacology
Injectable Drugs Market