
 Antihyperlipidemic Drugs Market | 2026-2036
Antihyperlipidemic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Antihyperlipidemic Drugs Market Intelligence
RNA-targeted therapeutics is tilting antihyperlipidemic development toward gene-silencing platforms that reduce LDL-C through mechanisms beyond traditional enzyme inhibition. Amgen leverages its established biologics infrastructure to sustain manufacturing scale for injectable lipid-lowering therapies. Pfizer anchors its position through oral small-molecule programs that compete across primary care prescribing channels. Sanofi differentiates via partnership networks that extend reach into hospital-based lipid clinics.
Antihyperlipidemic drugs comprise pharmacological agents that modulate lipid metabolism through HMG-CoA reductase inhibition, PPAR-alpha activation, bile acid binding, or PCSK9 pathway blockade, formulated as tablets, prefilled syringes, or intravenous infusions with specified dissolution profiles and bioavailability parameters. Their primary purpose is the reduction of atherogenic lipoproteins to prevent myocardial infarction, stroke, and peripheral arterial disease in at-risk populations. The statin segment retains dominant volume share in oral prescribing despite generic saturation, while PCSK9 inhibitors capture concentrated value pools in injectable formats for familial hypercholesterolemia and statin-intolerant patients. Homecare administration routes are gaining structural traction as self-injection devices and sublingual formulations reduce clinic dependency for chronic lipid management.
The FDA's Risk Evaluation and Mitigation Strategy requirements for novel antihyperlipidemic agents shape clinical trial endpoints and post-market surveillance obligations, while the EMA's pharmacovigilance framework for cardiovascular drugs influences labeling decisions across European markets. REACH compliance in Europe governs active pharmaceutical ingredient sourcing and environmental discharge standards for manufacturing facilities. China's NMPA streamlined review pathways for innovative cardiovascular therapies accelerate market entry timelines for multinational sponsors. Stakeholders must monitor evolving payer evidence requirements for LDL-C outcome trials as health technology assessment bodies tighten reimbursement criteria for premium-priced biologic therapies.
Market Dynamics
The antihyperlipidemic drugs market pivots on FDA accelerated approval pathways for breakthrough cardiovascular therapies, which compress development timelines and reshape competitive positioning between injectable biologics and oral small-molecule programs.
Growth Catalysts
- Specialty clinic expansion:Cardiovascular treatment centers in the United States drive concentrated uptake of PCSK9 inhibitors for familial hypercholesterolemia patients.
- REACH compliance frameworks:European environmental discharge standards for active pharmaceutical ingredient manufacturing elevate barriers for new entrants while securing incumbent supply positions.
- RNA-targeted platforms:Gene-silencing therapeutics reduce LDL-C through mechanisms beyond traditional enzyme inhibition, opening new prescription categories.
Market Restraints
- Generic statin saturation:Volume-dominant oral HMG-CoA reductase inhibitors face pricing compression that limits revenue expansion in primary care channels.
- Biologic manufacturing concentration:Injectable lipid-lowering therapies depend on limited biologics infrastructure, creating supply vulnerability for prefilled syringe formats.
- Reimbursement evidence thresholds:Health technology assessment bodies in Germany and France tighten LDL-C outcome trial requirements for premium-priced therapies.
Strategic Opportunities
- Homecare administration routes:Self-injection devices and sublingual formulations reduce clinic dependency for chronic lipid management.
- China's NMPA streamlined pathways:Accelerated review timelines for innovative cardiovascular therapies compress market entry for multinational sponsors.
- Statin-intolerant patient pools:Underpenetrated segments in Japan and South Korea present concentrated demand for non-statin lipid-lowering alternatives.
Industry Challenges
- Post-market surveillance obligations:FDA Risk Evaluation and Mitigation Strategy requirements demand extended pharmacovigilance infrastructure that strains mid-cap sponsors.
- Cross-platform formulation expertise:Developers must simultaneously master tablet dissolution profiles for oral programs and bioavailability parameters for intravenous infusion formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antihyperlipidemic Drugs Market |
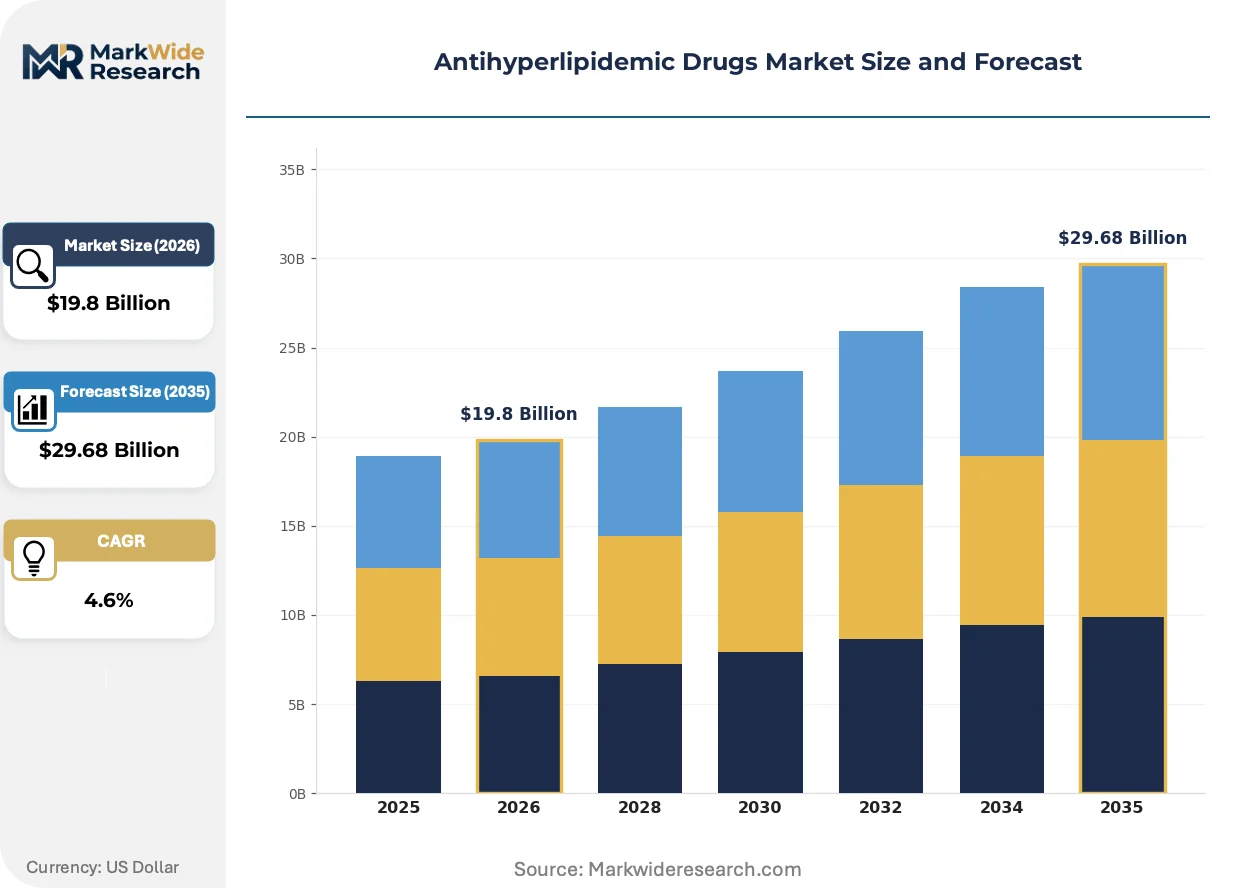
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $29.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Statins, Fibrates, Bile Acid Sequestrants, PCSK9 Inhibitors Administration Route: Oral, Injectable, Intravenous, Sublingual End User: Hospitals, Clinics, Pharmacies, Homecare Target Population: Adults, Elderly, Pediatric, Patients with Diabetes |
| Companies Covered | Amgen, Novartis, Pfizer, AbbVie, Bristol-Myers Squibb, AstraZeneca, Merck & Co., Daiichi Sankyo, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antihyperlipidemic Drugs Market Strategic Shifts & Innovations
RNA-targeted therapeutics are compressing traditional small-molecule development cycles while regulatory frameworks accelerate cardiovascular drug review timelines. Three forces are actively restructuring competitive positioning.
Small-interfering RNA platforms targeting PCSK9 expression are migrating from hospital infusion centers to prefilled syringe formats suitable for quarterly home administration. Specialty lipid clinics in the United States and Germany are adopting these injectable regimens at pace, compressing the addressable market for daily oral therapies among high-risk cardiovascular patients.
EMA pharmacovigilance frameworks for cardiovascular drugs are tightening labeling requirements across European markets. Manufacturers must now incorporate real-world evidence into post-authorization safety protocols, affecting how PCSK9 inhibitors and emerging CETP inhibitors position against statin combinations in formulary negotiations.
Hospital-based procurement committees are consolidating purchasing authority for biologic lipid-lowering therapies. Integrated delivery networks in the United States are replacing individual physician prescribing autonomy with centralized pharmacy and therapeutics committee decisions, compressing brand access for newer entrants without established hospital contracts.
Antihyperlipidemic Drugs Market Segmentation
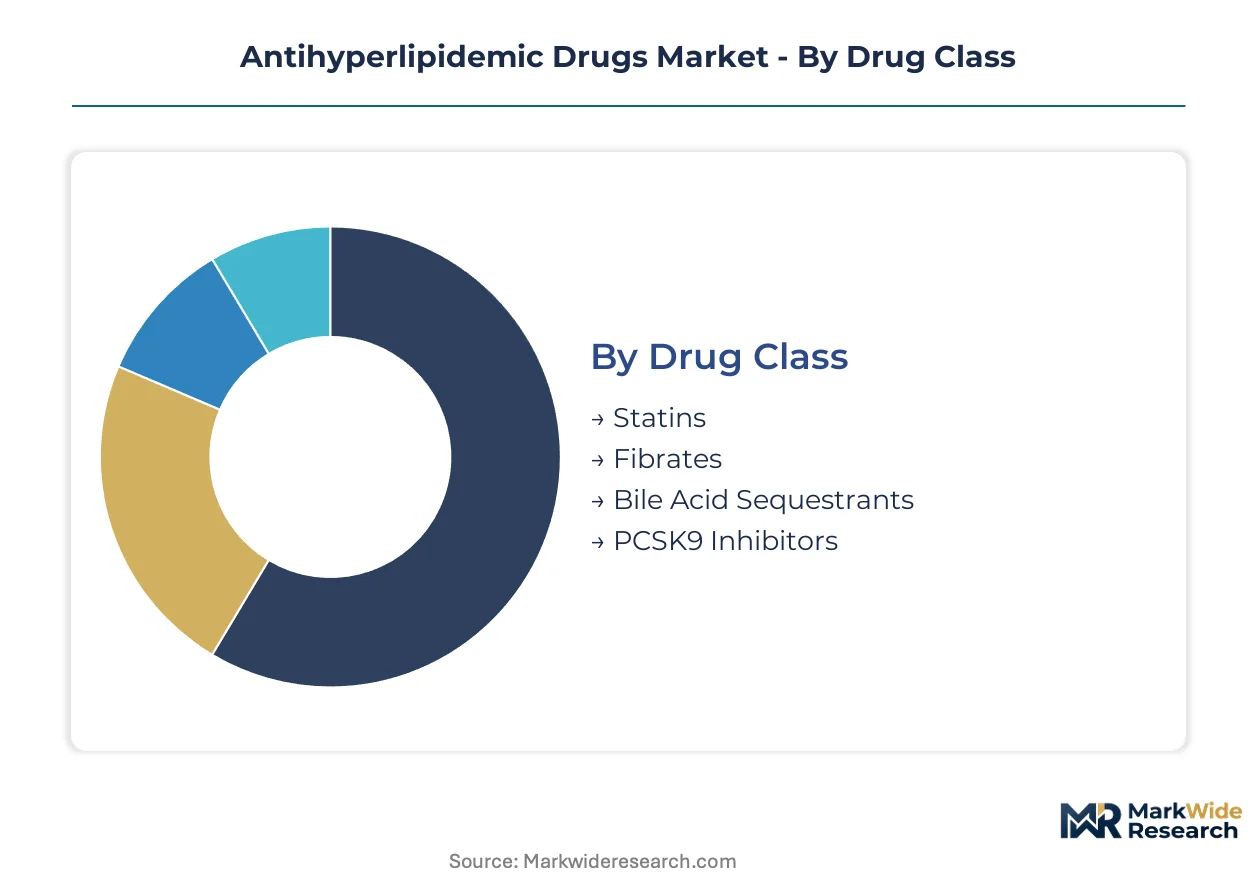
Antihyperlipidemic drugs segment across four distinct dimensions that shape prescribing patterns and commercial access. Drug class determines reimbursement tier and manufacturing complexity, while administration route dictates distribution channel and patient compliance economics.
Drug Class:
Use cases span from mass-market cardiovascular prevention to ultra-rare familial hypercholesterolemia, with cost tiers separating primary care prescribing from specialty biologics.
- Statins:HMG-CoA reductase inhibitors formulated as tablets with established dissolution profiles dominate primary care prescribing for secondary cardiovascular prevention. Demand concentrates in United States Medicare Part D formularies where generic atorvastatin and rosuvastatin face pricing compression that limits branded revenue expansion.
- PCSK9 Inhibitors:Monoclonal antibodies and RNA-targeted biologics delivered via prefilled syringe formats require cold-chain distribution and specialty pharmacy networks. United States cardiovascular treatment centers drive concentrated uptake for familial hypercholesterolemia patients with LDL-C thresholds above guideline-directed statin targets.
- Fibrates:PPAR-alpha agonists targeting elevated triglycerides in metabolic syndrome populations.
- Bile Acid Sequestrants:Resin-based oral formulations binding intestinal cholesterol for patients with statin intolerance.
The dominant share belongs to Statins, while PCSK9 Inhibitors is closing the gap fastest.
Administration Route:
Route selection determines patient autonomy, with self-administration formats gaining structural traction against facility-dependent infusion models.
- Oral:Tablet and capsule formulations with specified bioavailability parameters enable daily patient-managed therapy without clinic dependency. Primary care channels in Germany and France prioritize oral prescribing for population-scale cardiovascular risk reduction.
- Injectable:Prefilled syringe and autoinjector devices for biologic therapies shift administration from hospital infusion centers to quarterly home-based regimens. United States specialty lipid clinics adopt these formats to reduce nursing overhead while improving adherence metrics.
- Intravenous:Hospital-based infusion protocols for acute lipid management and investigational RNA therapeutics.
- Sublingual:Rapid-dissolve formulations emerging for statin-intolerant patients requiring non-oral absorption pathways.
Oral administration retains volume leadership, though Injectable formats are expanding most quickly through homecare adoption.
End User:
Site-of-care economics separate centralized purchasing authority from decentralized retail dispensing.
- Hospitals:Integrated delivery networks in the United States consolidate purchasing authority through pharmacy and therapeutics committees that gate biologic access. EMA pharmacovigilance frameworks require real-world evidence integration into hospital formulary decisions.
- Homecare:Self-injection devices and mail-order specialty pharmacies reduce clinic dependency for chronic lipid management. Japan's aging population drives demand for home-based administration among elderly patients with mobility constraints.
- Clinics:Outpatient cardiovascular treatment centers managing high-risk familial hypercholesterolemia cohorts.
- Pharmacies:Retail dispensing networks for generic statin maintenance therapy.
Hospitals command premium biologic volumes, while Homecare is gaining share fastest through device-enabled self-administration.
Target Population:
Risk stratification separates population-scale prevention from concentrated therapy for comorbid conditions.
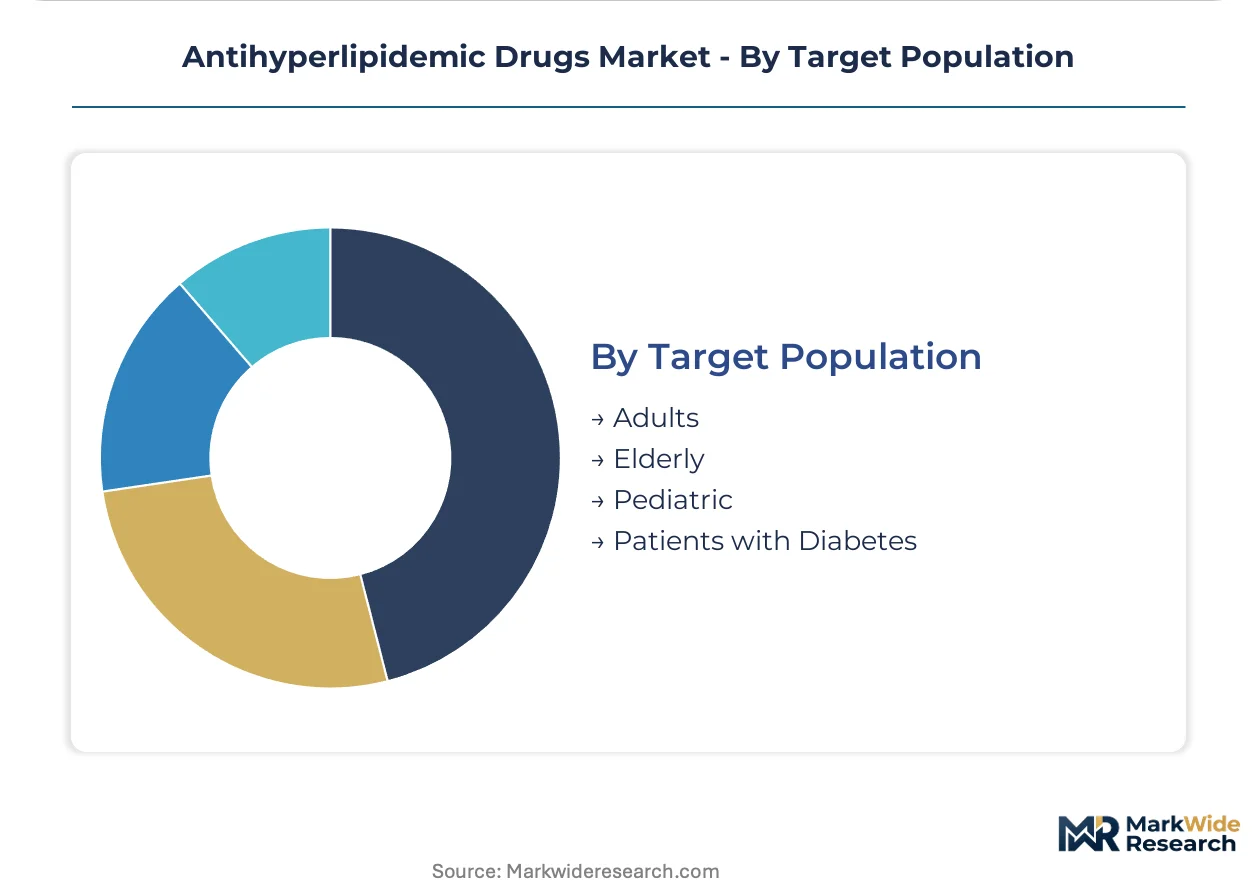
- Adults:Working-age cardiovascular risk reduction drives volume demand across oral statin prescribing. China's NMPA streamlined pathways accelerate market entry for therapies targeting this demographic.
- Patients with Diabetes:Dyslipidemia comorbidity creates concentrated demand for combination therapies addressing both glucose and lipid metabolism. United States endocrinology practices prioritize this segment for PCSK9 inhibitor access.
- Elderly:Polypharmacy management challenges in aged populations with multiple cardiovascular risk factors.
- Pediatric:Rare familial hypercholesterolemia cases requiring specialized dosing protocols.
Adults represent the largest addressable base, while Patients with Diabetes is climbing the fastest through integrated cardiometabolic care models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty cardiovascular treatment centers concentrate purchasing authority for PCSK9 inhibitors in the United States, while Germany's hospital formulary committees gate biologic access through centralized procurement. China's NMPA streamlined review pathways and Japan's aging demographics reshape regional competitive timelines for novel lipid-lowering therapies.
United States
Medicare Part D formularies drive volume demand for generic statins while cardiovascular treatment centers in Boston and Cleveland concentrate PCSK9 inhibitor uptake for familial hypercholesterolemia patients. FDA accelerated approval pathways compress development timelines for RNA-targeted therapeutics. Integrated delivery networks in Texas and California consolidate pharmacy and therapeutics committee authority over biologic access.
Germany
Hospital-based lipid clinics in Munich and Heidelberg adopt quarterly injectable regimens for high-risk cardiovascular patients. EMA pharmacovigilance frameworks tighten labeling requirements for PCSK9 inhibitors in formulary negotiations. REACH compliance standards for active pharmaceutical ingredient manufacturing elevate environmental discharge barriers for new market entrants.
China
NMPA streamlined review pathways accelerate market entry timelines for multinational sponsors targeting working-age cardiovascular risk reduction. Shanghai and Beijing specialty hospitals pilot homecare administration devices for biologic lipid-lowering therapies. The country's dual carbon goals influence manufacturing facility siting decisions for imported active pharmaceutical ingredients.
Japan
Aging demographics in Tokyo and Osaka drive demand for self-injection devices among elderly patients with mobility constraints. PMDA review standards prioritize real-world evidence integration for statin-intolerant patient populations. Kansai region medical centers concentrate adoption of sublingual formulations for non-oral absorption pathways.
Switzerland
Swissmedic regulatory frameworks attract cardiovascular drug development headquarters for European market access strategy. Basel and Zurich hospital networks coordinate centralized purchasing for premium-priced biologic therapies. The country's pharmaceutical manufacturing cluster supports contract production of prefilled syringe formats for RNA-targeted platforms.
Antihyperlipidemic Drugs Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented prescribing environments. The United States market consolidates around integrated delivery networks and specialty pharmacy networks that gate biologic access, while European markets fragment across national reimbursement authorities. Three archetypes dominate: established biologics manufacturers with cold-chain infrastructure, oral small-molecule developers with primary care reach, and RNA-platform specialists with gene-silencing intellectual property. Competitive moves concentrate on strategic partnerships with hospital systems and portfolio diversification into homecare administration formats.
Within the biologics infrastructure tier, Amgen and Novartis occupy positions anchored by manufacturing scale for injectable lipid-lowering therapies. Pfizer exemplifies the oral small-molecule archetype through primary care channel presence. Sanofi sits within the partnership-network tier, extending reach into hospital-based lipid clinics through collaborative arrangements.
| Leading Market Players |
|---|
| Amgen |
| Novartis |
| Pfizer |
| AbbVie |
| Bristol-Myers Squibb |
| AstraZeneca |
| Merck & Co. |
| Daiichi Sankyo |
| Sanofi |
| Others |
Cost & Logistics Intelligence
Active pharmaceutical ingredient manufacturing in China and India anchors cost structures for antihyperlipidemic drugs, concentrating margin capture with sponsors who secured long-term offtake contracts before REACH compliance elevated European environmental discharge standards. This upstream concentration funnels pricing power toward incumbents with established biologics infrastructure, while generic statin manufacturers absorb compression through volume-scale efficiencies.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient suppliers index to raw material baskets and energy benchmarks, stabilizing input costs for statin tablet manufacturers while exposing PCSK9 inhibitor sponsors to biologics fermentation yield volatility. Three-tier pricing structure across premium biologics, standard branded small-molecules, and economy generics separates reimbursement tiers in United States Medicare formularies. Cost compression in oral statin segments intensifies because of generic atorvastatin and rosuvastatin saturation, while injectable biologics retain pricing resilience through indication-specific access protocols. Primary care prescribing channels exhibit highest price sensitivity, whereas specialty lipid clinics demonstrate lowest sensitivity due to outcome-based contracting with integrated delivery networks.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for antihyperlipidemic drug sponsors, prompting dual-sourcing strategies for HMG-CoA reductase inhibitor intermediates. Manufacturing concentrates in China for fermentation-derived statins, India for synthetic API intermediates, and Switzerland for biologics fill-finish operations. Cold-chain distribution draws from specialized logistics networks for monoclonal antibody therapies, while oral formulations rest on conventional pharmaceutical wholesaler infrastructure. Single-source vulnerability in biologics manufacturing creates supply interruption exposure for PCSK9 inhibitor prefilled syringe formats. Distribution runs through specialty pharmacy networks for injectable therapies and retail chains for oral maintenance regimens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation in the United States and hospital formulary centralization in Germany, fragmenting individual physician autonomy and compressing brand access for newer market entrants.
For Market Incumbents: Insulate manufacturing positions through backward integration into active pharmaceutical ingredient production, particularly for RNA-targeted platform inputs where fermentation capacity scarcity threatens supply security. Secure hospital system partnerships with pharmacy and therapeutics committees before centralized procurement authority hardens, as integrated delivery networks in Texas and California already gate biologic access through restricted formularies. For New Entrants and Emerging Players: Build out sublingual formulation capabilities targeting statin-intolerant patient pools in Japan and South Korea, where regulatory pathways for non-oral absorption mechanisms remain underpenetrated. Prioritize homecare administration device development to bypass hospital-based procurement consolidation, leveraging Japan's aging demographics and mobility-constrained elderly populations as the most penetrable entry segment. For Investors and Strategic Acquirers: Capital is best deployed toward RNA-platform specialists with gene-silencing intellectual property and established prefilled syringe manufacturing partnerships, as these archetypes command premium valuations through mechanism differentiation beyond traditional enzyme inhibition. Long-term viability hinges on sponsors who navigate tightening FDA Risk Evaluation and Mitigation Strategy requirements without drowning in pharmacovigilance infrastructure costs. The signal to watch is NMPA approval velocity for multinational sponsors in China, where accelerated review timelines for cardiovascular therapies indicate regulatory receptivity that could compress competitive entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| RNA Platform Manufacturing Scale-Up | Gene-silencing therapies require fermentation capacity expansion to meet quarterly injection demand from United States specialty clinics. |
| Hospital System Partnership Development | Pharmacy and therapeutics committee relationships in integrated delivery networks determine biologic access for familial hypercholesterolemia patients. |
| Homecare Administration Device Launch | Self-injection formats reduce clinic dependency and improve adherence metrics among Japan's elderly cardiovascular populations. |
| REACH Compliance Certification | European environmental discharge standards for API manufacturing elevate barriers for new entrants while securing incumbent supply positions. |
| Statin-Intolerant Patient Access Strategy | Non-statin lipid-lowering alternatives address underpenetrated segments in Japan and South Korea with concentrated demand. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, formulary directors at United States integrated delivery networks, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submission databases, ClinicalTrials.gov protocol registries, and Medicare Part D formulary databases. Bottom-up patient population modeling and top-down pharmaceutical market sizing were triangulated to reconcile volume estimates across oral and injectable administration routes.
Calibration against historical approval timelines and reimbursement decision patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include drug class, administration route, end-user site of care, and target population risk stratification. CAGRs were derived from epidemiological trend analysis, pricing trajectory assumptions, and penetration curve modeling for RNA-targeted therapeutics versus established small-molecule alternatives. Forecast inputs incorporated NMPA review velocity, EMA pharmacovigilance framework evolution, and specialty clinic expansion rates in United States cardiovascular treatment centers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese API manufacturers or breakthrough gene-editing therapies from platform biotechs would shift outcomes beyond modeled ranges. Regulatory timeline acceleration in China or reimbursement restriction tightening in Germany represent specific revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Huoxiang Zhengqi Drug Market
Pharmacology
Hydroxychloroquine Drugs Market
Pharmacology
Aspirin API Market
Pharmacology
Global Geriatric Medicines Market
Pharmacology
Ketoprofen API Market
Pharmacology
Antitussive Drugs Market
Pharmacology
Injectable Drugs Market
Pharmacology
Drug Eruptions Treatment Market
Pharmacology
Aldosterone Receptor Antagonists Market
Pharmacology
Prescription Narcotic Cough Preparations and Expectorants Market
Pharmacology
Antimycotics Market
Pharmacology
ACE Inhibitors Market
Pharmacology
Global Artemisinin Combination Therapy Market
Pharmacology
Alexipharmic Drugs Market
Pharmacology
Thromboprophylactic Drugs Market
Pharmacology
Attention Deficit Hyperactivity Disorder (ADHD) Therapeutics Market