
 Influenza Medication Market | 2026-2036
Influenza Medication Market Size, Share, and Industry Trends Forecast 2026-2036
Influenza Medication Market Intelligence
Profitability from traditional symptomatic treatments is narrowing as focus shifts toward novel antiviral therapies. Roche leverages its diagnostic capabilities to support its antiviral drug portfolio. GlaxoSmithKline sustains a strong market presence through its extensive vaccine and pharmaceutical offerings. Shionogi & Co., Ltd. specializes in the development of innovative antiviral compounds targeting specific viral replication mechanisms.
Influenza medication encompasses a class of pharmaceutical products designed to prevent or treat infections caused by influenza viruses. These therapies include neuraminidase inhibitors, which function by blocking viral release from host cells, and vaccines that stimulate targeted antibody production. Antiviral drugs, primarily through oral administration, constitute a mature and large market segment. Conversely, vaccines delivered via injection and innovative nasal spray formats represent the fastest-growing segment, propelled by governmental immunization programs.
The market operates under stringent oversight from bodies like the U.S. FDA, the European Medicines Agency (EMA), and Japan's PMDA. These regulators enforce rigorous clinical trial protocols that establish the safety and efficacy of new influenza medications. Successfully navigating the development pipeline to address antigenic drift in influenza strains remains a critical strategic challenge for all manufacturers.
Market Dynamics
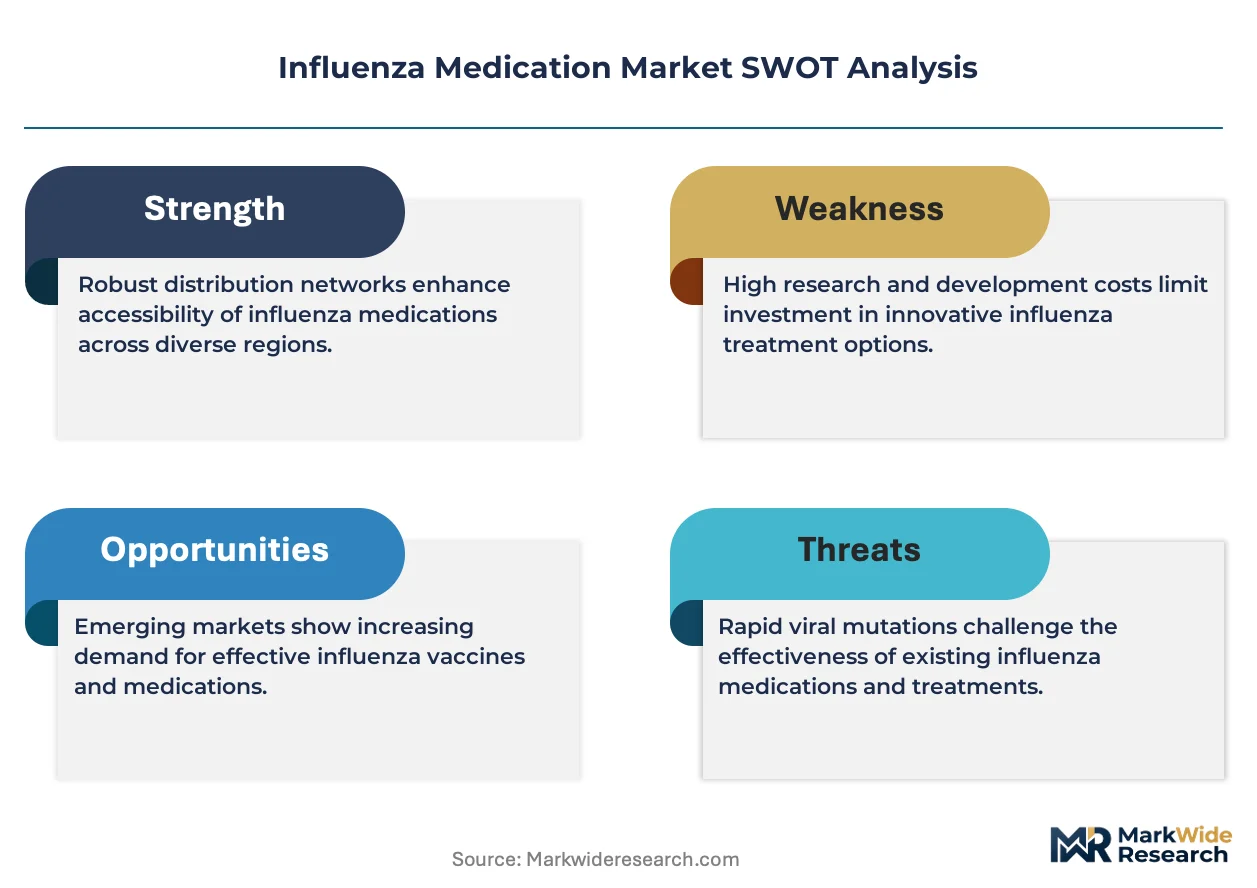
The market's structure is defined by the constant pressure of influenza's antigenic drift. This biological reality compels continuous innovation in vaccine platforms and antiviral therapies, shifting investment away from static treatments toward adaptive and rapid-response development cycles.
Growth Catalysts
- Governmental Immunization Programs:National public health initiatives in countries like Japan expand vaccine coverage, stimulating demand for influenza medications among high-risk groups.
- Cell-Based Vaccine Manufacturing:This platform accelerates production timelines and enables a closer match to circulating strains, improving vaccine efficacy and supply responsiveness.
- Long-Term Care Demand:A focus on preventative care within nursing homes creates a concentrated demand channel for vaccines and prophylactic antiviral drugs.
Market Restraints
- Antigenic Drift:Rapid viral mutation can cause a mismatch between the vaccine and circulating strains, reducing seasonal efficacy and public confidence.
- Stringent Regulatory Hurdles:Lengthy and costly clinical trials mandated by the FDA and EMA create significant barriers to entry for new market participants.
- High R&D Investment:Developing novel antiviral compounds requires substantial capital with a high risk of failure during late-stage clinical trials.
Strategic Opportunities
- Universal Vaccine Development:Research into a universal vaccine providing broad, long-lasting protection against multiple strains represents a transformative commercial opportunity.
- mRNA Platform Integration:Applying mRNA technology to influenza could dramatically shorten vaccine development timelines in response to emerging viral threats.
- Emerging Market Expansion:Expanding access to modern vaccines and antivirals in large, middle-income countries presents a significant growth opportunity for manufacturers.
Industry Challenges
- Cold Chain Logistics:Maintaining the integrity of temperature-sensitive vaccines, particularly newer formulations, during distribution in regions with inconsistent infrastructure remains a significant operational hurdle.
- Global Regulatory Harmonization:Manufacturers face complexity in navigating disparate clinical trial data requirements and approval processes across different national regulatory agencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Influenza Medication Market |
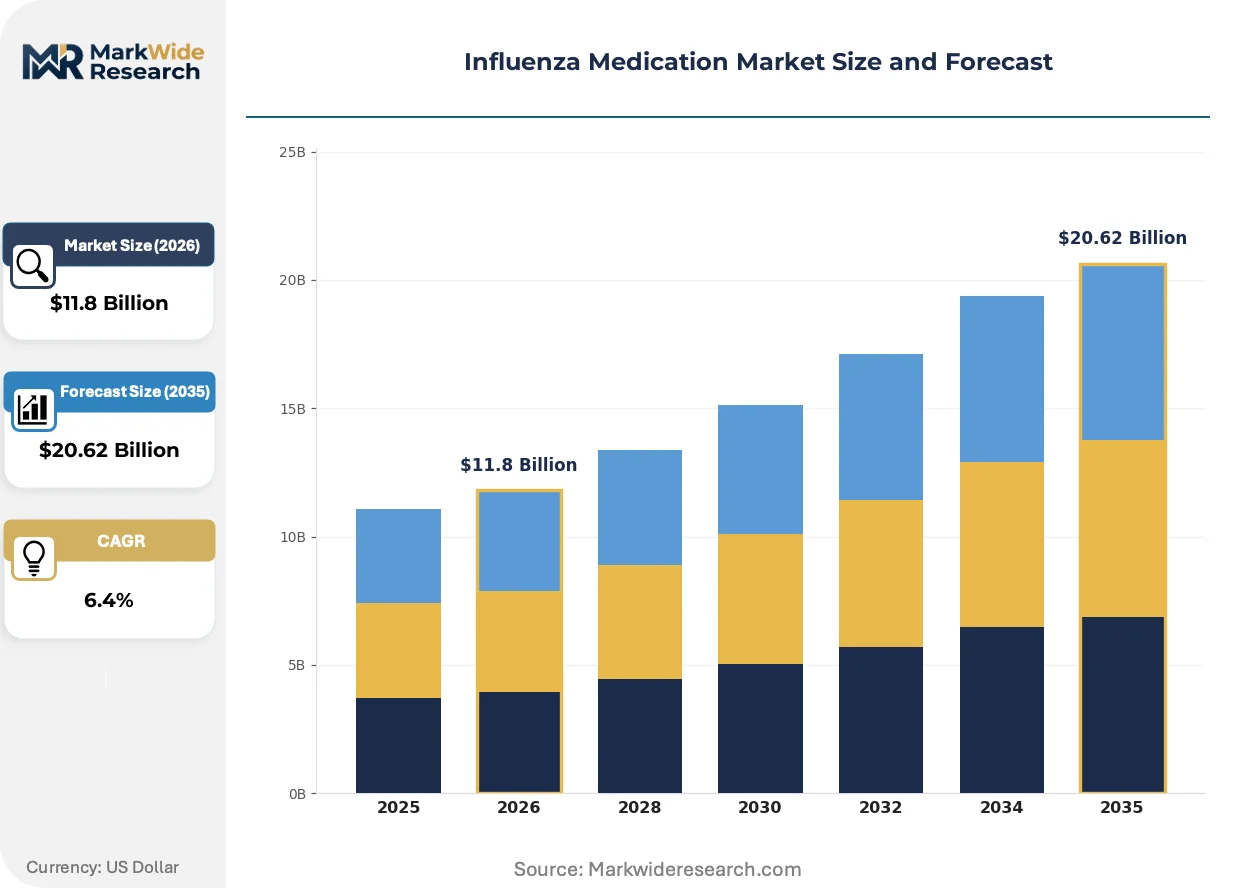
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiviral Drugs, Vaccines, Symptomatic Treatment, Herbal Remedies Therapy Area: Influenza A, Influenza B, Seasonal Flu, Pandemic Flu End User: Hospitals, Clinics, Diagnostic Labs, Long-Term Care Facilities Delivery Mode: Oral Administration, Inhalation, Injection, Nasal Spray |
| Companies Covered | GlaxoSmithKline plc, Roche, Seqirus, Shionogi & Co., Ltd., Sanofi, BioCryst Pharmaceuticals, Inc., AstraZeneca plc, Genentech, Inc., Daiichi Sankyo Company, Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Influenza Medication Market Strategic Shifts & Innovations
The competitive landscape is shifting from symptomatic treatment toward proactive prevention and targeted viral inhibition. This evolution is driven by deeper virological understanding and the industrialization of next-generation platforms, fundamentally changing how influenza is managed.
Computational biology and AI models are now used to predict influenza virus evolution and identify conserved epitopes for vaccine design. Pharmaceutical research organizations are rapidly adopting these predictive tools to inform their R&D pipelines. This approach is digitizing the traditionally slow, empirical process of antigen selection, accelerating development to better match future circulating strains.
Regulatory bodies like the U.S. FDA and the European Medicines Agency are offering accelerated review pathways for pandemic-preparedness therapeutics. This policy framework shortens time-to-market for novel antivirals and universal vaccine candidates that show significant clinical advantages. The innovative vaccine segment is most affected, as developers prioritize assets that qualify for these fast-track designations.
A significant behavioral shift involves large healthcare systems and corporate wellness programs procuring influenza medications through population-level health contracts. This model moves away from individual prescription fulfillment toward bulk purchasing of vaccines and prophylactic antivirals. The trend is most visible in nations with integrated public health systems, such as the United Kingdom.
Influenza Medication Market Segmentation
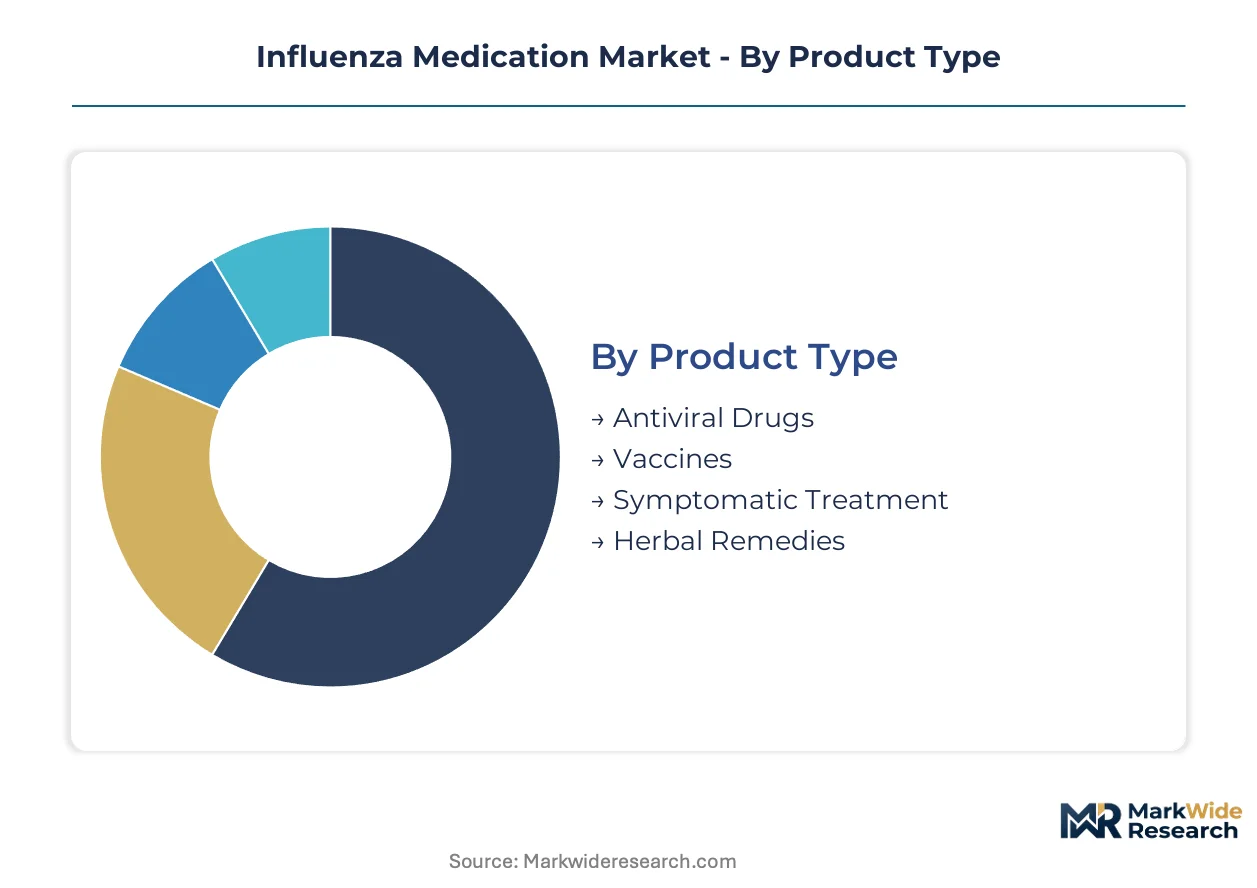
The influenza medication market exhibits diverse segmentation, reflecting the varied approaches to prevention and treatment across different patient populations and disease severities. Understanding these segments helps manufacturers tailor product development, distribution strategies, and regulatory submissions effectively. This granular view highlights where specific pharmaceutical interventions generate the most impact within public health systems.
Product Type:
The intensity of after-sales service varies significantly across different influenza medication product types, from routine vaccine administration to complex antiviral treatment regimens. Technical specifications and regulatory oversight shape the entire product lifecycle for these pharmaceutical offerings.
- Antiviral Drugs:These pharmaceutical compounds directly target viral replication mechanisms, such as neuraminidase inhibitors which block viral release from host cells. Demand concentrates in acute care settings and for high-risk individuals, driven by their efficacy in reducing disease severity when administered early.
- Vaccines:Vaccines stimulate the immune system to produce targeted antibodies, providing prophylactic protection against influenza viruses. Governmental immunization programs and long-term care facilities drive substantial demand, especially in countries with robust public health infrastructure like Japan.
- Symptomatic Treatment:This category includes over-the-counter and prescription medications designed to alleviate influenza symptoms like fever, cough, and congestion. Consumers primarily seek these treatments for comfort and temporary relief, often as a first line of self-care.
- Herbal Remedies:Natural compounds and traditional medicines fall into this segment, used as complementary or alternative therapies for influenza symptoms. Patient preference for natural solutions influences demand in various cultural contexts.
By volume, Antiviral Drugs maintain a substantial market share. By growth pace, innovative Vaccine formats are ahead.
Therapy Area:
The application of influenza medications spans distinct viral strains and epidemiological patterns, dictating the specific therapeutic or prophylactic response required. Each therapy area presents unique challenges for drug development and public health management.
- Seasonal Flu:This segment addresses the annually recurring influenza outbreaks, characterized by predictable viral strains requiring updated vaccines each year. Public health campaigns in countries like Germany encourage widespread vaccination to mitigate community spread.
- Pandemic Flu:Novel influenza strains with the potential for global spread and severe illness define this therapy area, demanding rapid development of new vaccines and antiviral stockpiles. Regulatory bodies like the U.S. FDA offer accelerated review pathways for these critical interventions.
- Influenza A:Medications specifically targeting Influenza A viruses, which are responsible for most severe outbreaks and pandemics, fall into this category. These therapies focus on the most prevalent and pathogenic influenza type.
- Influenza B:This segment includes treatments and vaccines effective against Influenza B viruses, which typically cause milder but still significant seasonal epidemics. Specific diagnostics identify these strains to guide appropriate treatment.
The clinical focus remains heavily on Seasonal Flu prevention. The public health impact of Pandemic Flu drives significant research and development investment.
End User:
The type of end user significantly influences procurement patterns and the scale of influenza medication deployment. Each setting requires tailored solutions for prevention, diagnosis, and treatment.
- Hospitals:These facilities manage severe influenza cases requiring hospitalization and administer antiviral treatments to high-risk patients. Large-scale procurement contracts secure essential medications for inpatient care and emergency departments.
- Long-Term Care Facilities:Vulnerable elderly populations reside in these facilities, creating a concentrated demand for prophylactic antivirals and annual vaccination programs. Population-level health contracts often facilitate bulk purchasing for residents and staff.
- Clinics:Outpatient clinics serve as primary points of contact for routine vaccinations and initial diagnosis and treatment of uncomplicated influenza. These settings focus on accessible care and community-level prevention.
- Diagnostic Labs:These laboratories perform influenza testing to confirm infections, identify viral strains, and inform treatment decisions. They support surveillance efforts crucial for public health monitoring.
Hospitals represent a critical point of care for severe cases. Long-Term Care Facilities drive significant demand for preventative measures.
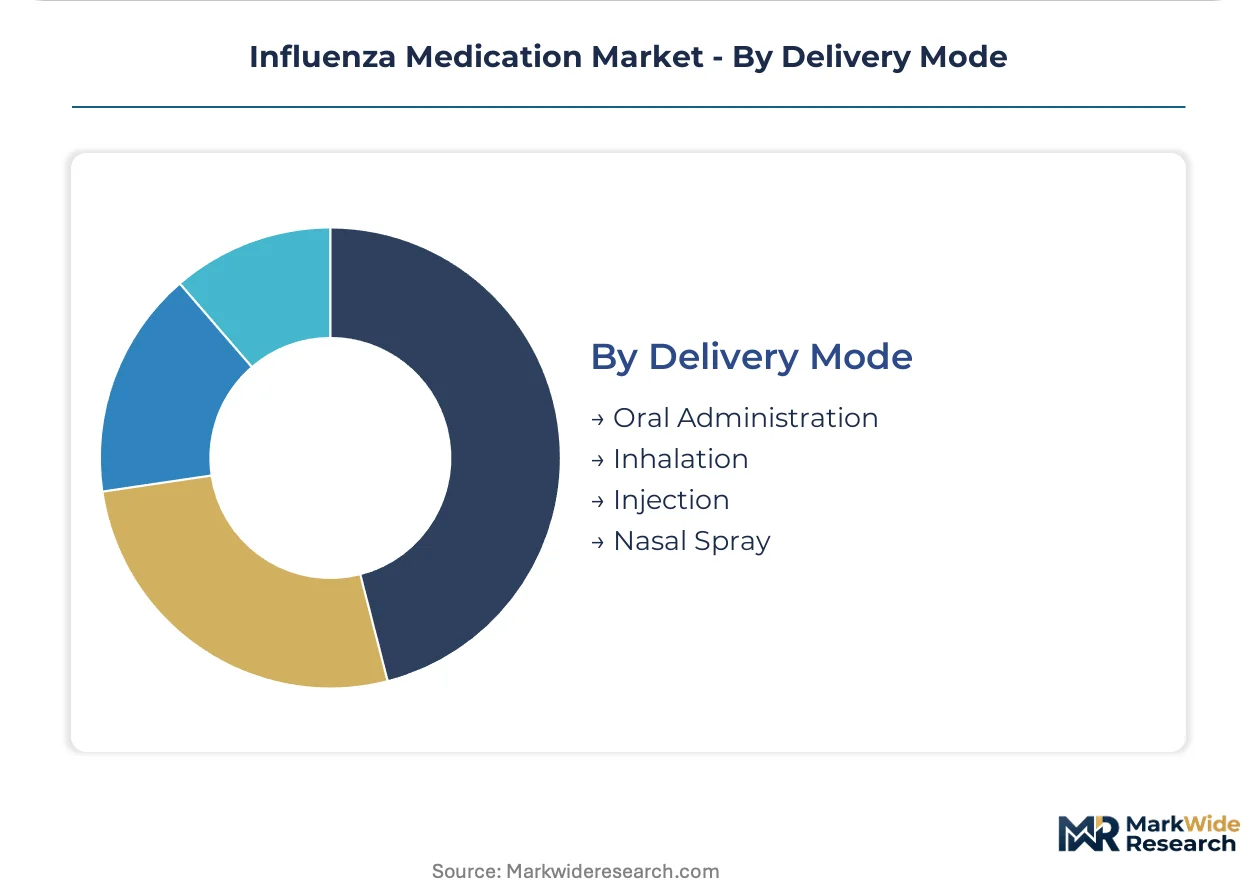
Delivery Mode:
The route of administration for influenza medications impacts patient convenience, efficacy, and logistical considerations. Innovation in delivery modes seeks to improve accessibility and compliance.
- Injection:This traditional delivery method for vaccines involves administering the medication directly into the muscle or under the skin. Governmental immunization programs widely utilize injectable vaccines due to their established efficacy and ease of mass administration.
- Nasal Spray:This non-invasive delivery method offers an alternative to injections, particularly appealing for pediatric populations and those with needle phobia. Innovative nasal spray formulations represent a fast-growing segment, propelled by convenience and targeted mucosal immunity.
- Oral Administration:Antiviral drugs are primarily delivered through oral tablets or liquids, offering patient convenience for at-home treatment. This mode supports early intervention outside of clinical settings.
- Inhalation:Medications delivered via inhalation target the respiratory tract directly, providing localized treatment for influenza symptoms or viral inhibition. This method offers a focused approach for certain antiviral therapies.
Oral Administration offers significant patient ease of use. Nasal Spray delivery is expanding most quickly due to its non-invasive nature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for influenza medication varies significantly across geographies, reflecting distinct public health priorities and healthcare system structures. While some nations prioritize widespread preventative vaccination, others focus on rapid antiviral deployment for acute cases.
United States
Demand for advanced antiviral therapies and innovative vaccine formats is strong within the United States. The U.S. FDA rigorously oversees clinical trials for new influenza medications, ensuring safety and efficacy. Biotech hubs like Boston and San Francisco drive significant research and development for novel vaccine platforms.
Germany
Widespread public health campaigns stimulate vaccine coverage among high-risk groups across Germany. The European Medicines Agency (EMA) ensures the safety and efficacy of influenza treatments within the European Union. Pharmaceutical clusters in Bavaria and North Rhine-Westphalia focus on advanced manufacturing capabilities.
Japan
Governmental immunization programs expand vaccine access, particularly for the elderly population in Japan. The PMDA enforces strict regulatory standards for new drug approvals and post-market surveillance. Research institutions in Tokyo and Osaka contribute to cell-based vaccine development and adoption.
United Kingdom
Population-level health contracts for influenza medications are common in the United Kingdom's integrated public health system. The National Health Service (NHS) procures bulk vaccines and prophylactic antivirals for widespread distribution. Biopharmaceutical centers in Cambridge and Oxford advance mRNA vaccine research and development.
China
Expanding access to modern vaccines and antivirals presents a significant growth opportunity for manufacturers in China. The NMPA streamlines approval processes for essential medicines to meet public health needs. Pharmaceutical manufacturing zones in Shanghai and Jiangsu are increasing production capacities for influenza treatments.
Influenza Medication Market Key Industry Players
Capability concentration sits with one tier, primarily specialized biotech firms and research institutions; scale advantage sits with another, dominated by large, diversified pharmaceutical companies. The market structure is tiered, featuring major global pharmaceutical companies, specialized antiviral developers, and innovative vaccine manufacturers. Strategic partnerships between smaller innovators and larger players are common, alongside substantial R&D investment in next-generation therapies.
At the scale-driven end, GlaxoSmithKline plc and Roche exemplify diversified pharmaceutical giants with extensive portfolios spanning vaccines and antiviral drugs. Shionogi & Co., Ltd. represents a specialized archetype, focusing on innovative antiviral compounds that target specific viral replication mechanisms. These firms anchor the market through both established product lines and significant investments in novel therapeutic approaches.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Roche |
| Seqirus |
| Shionogi & Co., Ltd. |
| Sanofi |
| BioCryst Pharmaceuticals, Inc. |
| AstraZeneca plc |
| Genentech, Inc. |
| Daiichi Sankyo Company, Limited |
| Others |
Cost & Logistics Intelligence
Regulatory chokepoints for advanced influenza medications determine both the premium pricing for novel therapies and the highly specialized supply chain for their production and distribution. Stringent oversight creates significant entry barriers and cost structures.
Pricing Analysis
Long-term offtake contracts dominate the pricing model for influenza medications, particularly for vaccines procured by public health authorities. Price differentiation stems from clinical efficacy, regulatory approval status from agencies like the U.S. FDA, and the volume scale of procurement. Pricing pressure stems from governmental immunization programs seeking bulk discounts for widespread vaccine coverage. Public health systems exhibit high price sensitivity for seasonal vaccines, while specialized antivirals command premium pricing for high-risk individuals.
Supply Chain Analysis
Restricted-technology controls on advanced biomanufacturing equipment limit the flows of specialized production capabilities, concentrating influenza medication supply chains. Supply concentration centers in countries with robust pharmaceutical manufacturing like the USA, Germany, and Japan, with China contributing significantly to API production. Raw material dependencies include specific viral strains for vaccine production and specialized cell culture media. Single-source vulnerability for novel vaccine platforms represents a structural risk, while cold chain logistics define the downstream distribution model to hospitals and clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The influenza medication market represents a substitution defense, as incumbents must navigate the threat of next-generation vaccine technologies. mRNA platforms and universal vaccine candidates could significantly displace established product lines.
For Market Incumbents: Insulate existing market share by accelerating investment in next-generation vaccine platforms, particularly mRNA technology. Strategic partnerships with specialized biotech firms can mitigate the threat from emerging universal vaccine candidates. Expanding cell-based manufacturing capacity in regions like Germany and the USA reinforces supply reliability and efficacy. Securing long-term governmental immunization program contracts further defends against competitive shifts.
For New Entrants and Emerging Players: Build out differentiated product portfolios by targeting innovative vaccine delivery methods, such as advanced nasal spray formulations. White-space opportunities exist in developing novel antiviral compounds against specific viral replication mechanisms. Emerging markets, particularly China, offer significant penetration potential for modern vaccines and antivirals. A go-to-market strategy focusing on accelerated regulatory pathways for pandemic preparedness therapeutics can unlock rapid approvals.
For Investors and Strategic Acquirers: Accelerated review pathways from regulatory bodies like the U.S. FDA reshape the acquisition landscape for novel influenza medications. The market demonstrates sustained long-term viability over a 5-10 year window due to continuous antigenic drift and population growth. Acquisition targets should focus on specialized biotech firms possessing proprietary mRNA technology or universal vaccine intellectual property. Successful Phase 3 clinical trials for universal vaccine candidates represent a critical inflection signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in mRNA Vaccine R&D | This accelerates vaccine development timelines, allowing manufacturers to respond rapidly to emerging viral threats. |
| Expand Cell-Based Manufacturing | This improves production speed and efficacy, ensuring a closer match to circulating influenza strains. |
| Pursue Accelerated Regulatory Pathways | This shortens time-to-market for novel antivirals and universal vaccine candidates with significant clinical advantages. |
| Form Strategic Biotech Partnerships | Collaborations with specialized firms enhance R&D capabilities for innovative antiviral compounds and next-generation vaccines. |
| Strengthen Cold Chain Logistics | This maintains the integrity of temperature-sensitive vaccines during distribution, especially in regions with inconsistent infrastructure. |
Research Approach
Findings reconcile primary fieldwork against secondary review of U.S. FDA filings, EMA submissions, and ClinicalTrials.gov data. Primary interviews engaged drug development executives, regulatory affairs leads, hospital procurement managers, and public health officials. This approach ensured comprehensive insights into market dynamics and technological advancements. Bottom-up market sizing was triangulated with top-down validation from industry reports.
Forecast inputs considered include product type, therapy area, end user, delivery mode, and regional regulatory cluster across the analysis window. The analytical framework integrated historical performance data with projected growth drivers to derive compound annual growth rates. Key industry-specific inputs like antigenic drift patterns and governmental immunization program expansion influenced projections. This comprehensive modeling approach ensured robust volume and value outputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large pharmaceutical companies or innovative biotech firms would shift outcomes. Material shifts in rapid viral mutation or geopolitical dynamics affecting supply chains would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
UK Pharmacovigilance Market
Pharmacology
Immunotherapy Drugs Market
Pharmacology
Anti Inflammatory Therapeutics Market
Pharmacology
Antihyperlipidemic Drugs Market
Pharmacology
Aldosterone Receptor Antagonists Market
Pharmacology
Olanzapine API Market
Pharmacology
Hepatitis C Drug Market
Pharmacology
Apixaban Market
Pharmacology
Huoxiang Zhengqi Drug Market
Pharmacology
Global Pharmacokinetics Services Market
Pharmacology
Artemisinin Antimalarial Drugs Market
Pharmacology
Aspirin API Market
Pharmacology
Intranasal Drug and Vaccine Delivery Market
Pharmacology
Anti-Obesity Therapeutics Market
Pharmacology
Pegylated Drugs Market
Pharmacology
Angiotensin II Receptor Blockers (Arbs) Market