
 US Ketamine Clinics Market | 2026-2036
US Ketamine Clinics Market Size, Share, and Industry Trends Forecast 2026-2036
US Ketamine Clinics Market Insights
DEA Schedule III registration is reorganizing competitive access in the US Ketamine Clinics Market. Mindbloom leverages telehealth protocols to extend reach beyond traditional infusion centers. Klarity Clinic specializes in intravenous administration protocols that anchor premium service positioning. Field Trip Health navigates state-level licensing variance to sustain multi-clinic operations.
US ketamine clinics deliver sub-anesthetic doses of ketamine hydrochloride via intravenous infusion, intranasal spray, or oral routes to modulate glutamate NMDA receptor activity for rapid antidepressant effect. The primary commercial purpose centers on treating major depressive disorder, post-traumatic stress disorder, and chronic pain syndromes refractory to conventional pharmacotherapy. Intravenous therapy commands the highest margin pool due to supervised medical infrastructure requirements, while intranasal administration represents the fastest-expanding segment driven by lower per-session overhead and broader prescriber accessibility. Private clinics dominate operational volume, though hospital-based clinics capture complex patient referrals requiring integrated psychiatric monitoring.
FDA oversight of compounded ketamine products, DEA Schedule III controlled substance protocols, and state medical board practice guidelines collectively determine clinic licensing burden and treatment protocol legitimacy. These frameworks elevate compliance costs for new entrants while protecting incumbent operators with established regulatory infrastructure. Stakeholders must monitor evolving FDA guidance on esketamine versus generic ketamine coverage determinations and state Medicaid expansion decisions that will reshape patient addressable populations.
Market Dynamics
DEA Schedule III registration requirements are reorganizing competitive access in the US Ketamine Clinics Market, elevating compliance costs for new entrants while protecting incumbent operators with established regulatory infrastructure. FDA oversight of compounded ketamine products and evolving state medical board practice guidelines are reshaping clinic operating requirements across metropolitan corridors.
Growth Catalysts
- Treatment-resistant depression protocols:Mental health providers are expanding service lines for patients refractory to conventional pharmacotherapy, creating demand concentration in Texas, Florida, and California metropolitan areas.
- Telehealth integration frameworks:Remote patient monitoring technologies enable clinic operators to extend reach beyond traditional infusion centers, reducing geographic access barriers for maintenance dosing protocols.
- Medicaid expansion decisions:State-level coverage determinations for esketamine versus generic ketamine are reshaping patient addressable populations in jurisdictions with expanded behavioral health benefits.
Market Restraints
- Compounded ketamine supply chain concentration:FDA oversight of 503A and 503B compounding pharmacies limits sourcing flexibility, creating dependency on a narrow supplier base for clinic inventory.
- Schedule III controlled substance protocols:DEA registration requirements impose substantial compliance overhead, including storage security mandates and inventory tracking systems that elevate fixed costs for new market entrants.
- Psychiatric specialty workforce scarcity:Supervised medical infrastructure requirements for intravenous therapy strain availability of qualified anesthesiologists and psychiatric nurses in secondary metropolitan markets.
Strategic Opportunities
- Intranasal administration expansion:Lower per-session overhead and broader prescriber accessibility position intranasal delivery as the fastest-expanding segment for clinic network scaling.
- Hospital-based clinic partnerships:Complex patient referrals requiring integrated psychiatric monitoring create white space for joint ventures between private operators and academic medical centers.
- Chronic pain syndrome protocols:Fibromyalgia and neuropathic pain applications represent underpenetrated indications beyond major depressive disorder and post-traumatic stress disorder.
Industry Challenges
- State licensing variance navigation:Multi-clinic operators face operational complexity from inconsistent medical board guidelines across jurisdictions regarding supervision ratios and facility standards.
- Reimbursement pathway uncertainty:Prior authorization requirements and coverage gap management between commercial payers and Medicare create revenue cycle friction for clinic administrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Ketamine Clinics Market |
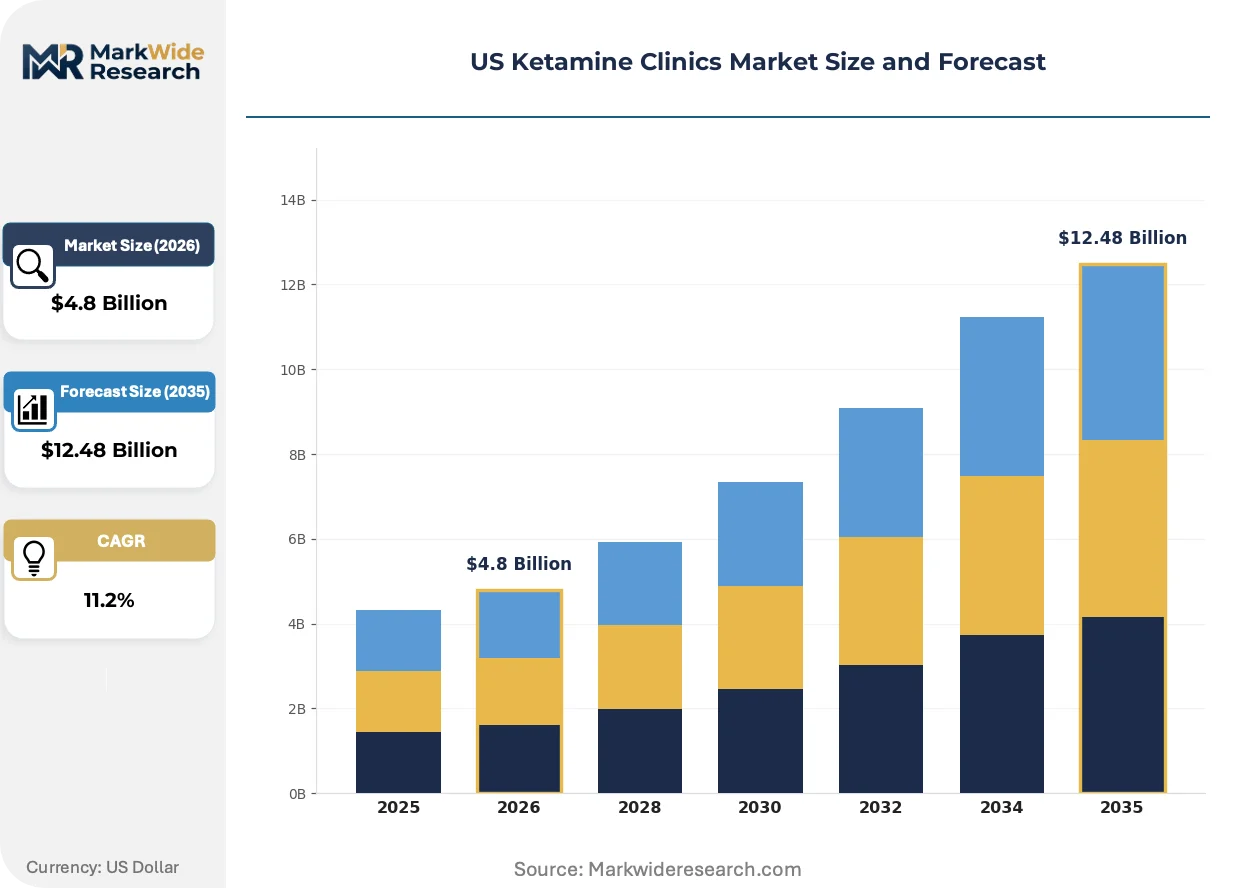
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Intravenous Therapy, Intranasal Therapy, Oral Administration, Sublingual Administration Patient Type: Chronic Pain Patients, Depression Patients, PTSD Patients, Anxiety Patients Clinic Type: Private Clinics, Hospital-Based Clinics, Mobile Clinics, Outpatient Centers Payment Model: Out-of-Pocket Payments, Insurance-covered Services, Subscription Model, Package Deals |
| Companies Covered | Better U, Innerwell, Ketamine Clinics Los Angeles, Klarisana Health, Klarity Clinic, Mindbloom, Nue Life Health, NY Ketamine Infusions, Field Trip Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Ketamine Clinics Market Trends and Innovations
Digital health infrastructure is actively reshaping how ketamine clinics deliver and monitor treatment, with remote patient engagement tools and data capture platforms reorganizing the traditional infusion-center model. Technology convergence, regulatory clarification, and shifting patient expectations are driving three distinct market developments.
Remote physiological monitoring systems are fragmenting the traditional clinic visit structure by enabling asynchronous patient data collection between sessions. Outpatient mental health networks are adopting wearable biosensors and mobile symptom tracking applications to maintain therapeutic continuity. This technology is fragmenting revenue concentration away from high-margin supervised infusion sessions toward distributed care models with lower per-touch economics.
FDA guidance development on compounded versus manufactured ketamine products is clarifying the boundary between legitimate clinical practice and unregulated distribution channels. The agency's enforcement posture against non-compliant telehealth prescribers is compressing gray-market supply routes. Hospital-based clinics in California, Texas, and Florida are responding by strengthening pharmacy partnerships and documentation protocols to demonstrate treatment necessity.
Patient acquisition patterns are rotating toward direct-to-consumer channels as stigma reduction and media coverage elevate treatment awareness. Traditional psychiatric referral networks are losing primacy to online search and social media discovery for initial clinic contact. This behavioral shift concentrates demand in metropolitan markets with established digital marketing sophistication and compresses patient lifetime value for operators dependent on physician referrals.
US Ketamine Clinics Market Segmentation
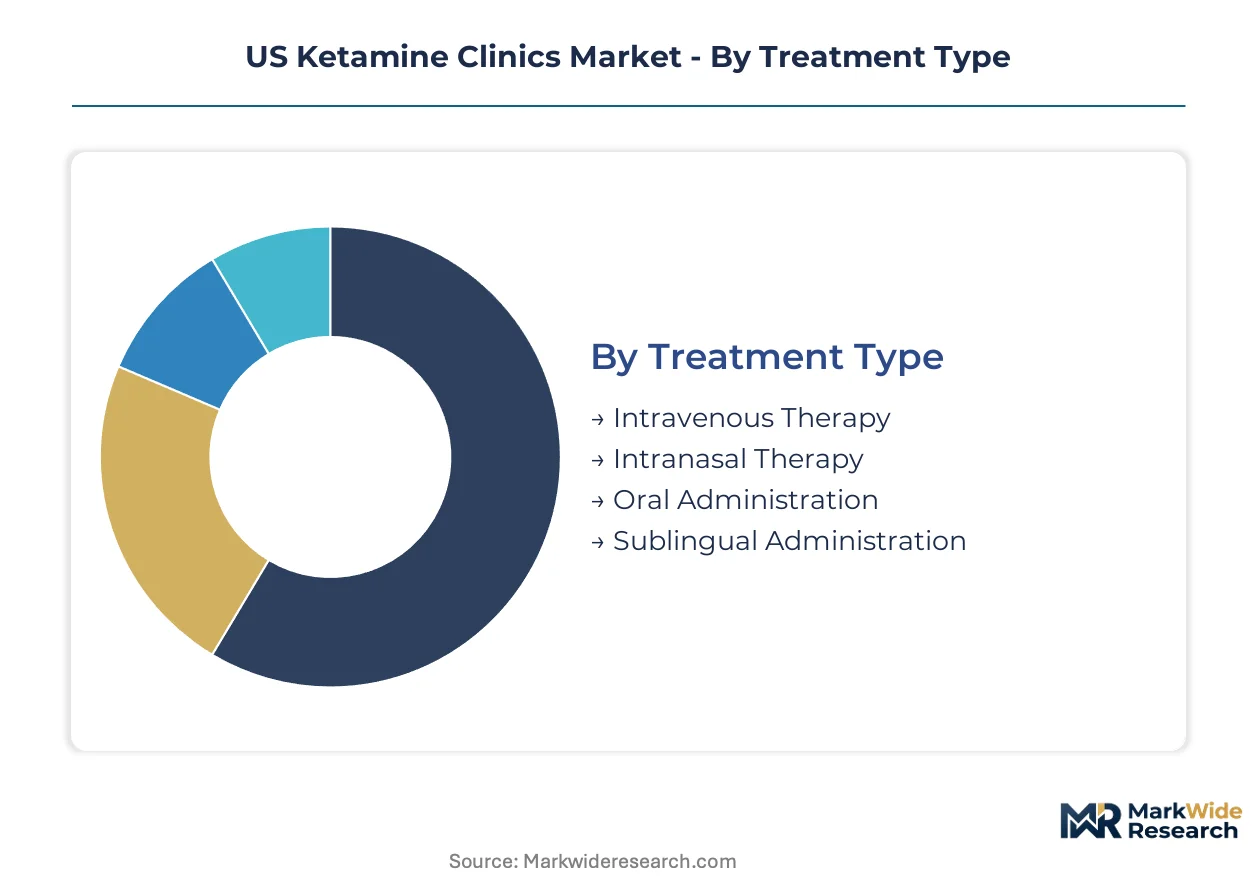
Segmentation in the US Ketamine Clinics Market reveals how regulatory requirements, reimbursement pathways, and patient acuity stratify operational economics across service delivery models. Clinic operators align infrastructure investments with specific patient populations and payment structures to defend margin positions.
Treatment Type:
Substitution pressure from oral and sublingual alternatives is intensifying competitive dynamics for high-overhead intravenous protocols, reshaping capital allocation across delivery modalities.
- Intravenous Therapy:Supervised infusion of ketamine hydrochloride via IV drip requires anesthesiologist or psychiatric nurse presence, dedicated monitoring equipment, and DEA-compliant storage infrastructure. Demand concentrates in Texas, Florida, and California metropolitan corridors where treatment-resistant depression patient density justifies fixed cost absorption. FDA oversight of compounding sources elevates supply chain complexity for clinic operators.
- Intranasal Therapy:Esketamine nasal spray administration under REMS-certified prescriber supervision enables lower per-session overhead and broader geographic reach through telehealth-integrated protocols. Demand is climbing fastest in Medicaid expansion states where coverage determinations favor FDA-approved formulations over compounded alternatives.
- Oral Administration:Compounded ketamine tablets or troches prescribed for at-home use face intensifying FDA enforcement against non-compliant telehealth distribution channels.
- Sublingual Administration:Dissolvable formulations bypass first-pass metabolism while retaining lower infrastructure requirements than intravenous delivery.
Intravenous therapy retains volume leadership; intranasal administration holds the steepest expansion curve.
Patient Type:
Cost tier stratification separates complex chronic pain populations requiring multi-session protocols from single-indication mental health patients with shorter treatment durations.
- Chronic Pain Patients:Fibromyalgia and neuropathic pain indications demand extended treatment courses with higher session frequency, anchoring revenue stability for established infusion centers. Patient concentration in Sun Belt states with aging demographics and workers compensation claim volume supports specialized clinic positioning.
- Depression Patients:Treatment-resistant major depressive disorder represents the primary commercial addressable population, with FDA esketamine approval creating reimbursement pathway clarity that generic ketamine lacks. Texas and Florida Medicaid expansion decisions are reshaping patient access economics.
- PTSD Patients:Veterans Affairs referral networks and trauma-focused psychiatric practices drive geographic demand concentration near military installations and urban VA medical centers.
- Anxiety Patients:Generalized anxiety and panic disorder applications remain underpenetrated relative to depression protocols, with limited payer coverage constraining commercial development.
Depression patients command the largest addressable base; chronic pain patients generate the highest per-patient lifetime value.
Clinic Type:
Margin structure varies dramatically across facility types, with hospital-based operations capturing complex referrals while private clinics optimize for throughput and marketing efficiency.
- Private Clinics:Independent operators dominate transaction volume through direct-to-consumer acquisition channels and streamlined scheduling infrastructure. California, Texas, and Florida host the densest private clinic networks, with digital marketing sophistication determining patient capture rates.
- Hospital-Based Clinics:Academic medical center affiliations enable integrated psychiatric monitoring and complex case management, capturing referrals beyond standalone operator capabilities. DEA Schedule III registration requirements align with existing hospital pharmacy infrastructure.
- Mobile Clinics:Transportable infusion units extend reach into underserved secondary markets, though regulatory variance across state medical board jurisdictions constrains multi-state scaling.
- Outpatient Centers:Ambulatory surgery center partnerships leverage existing anesthesia staffing and emergency response protocols for higher-acuity patient populations.
Private clinics retain volume leadership; hospital-based clinics hold the steepest expansion curve among institutional partnerships.
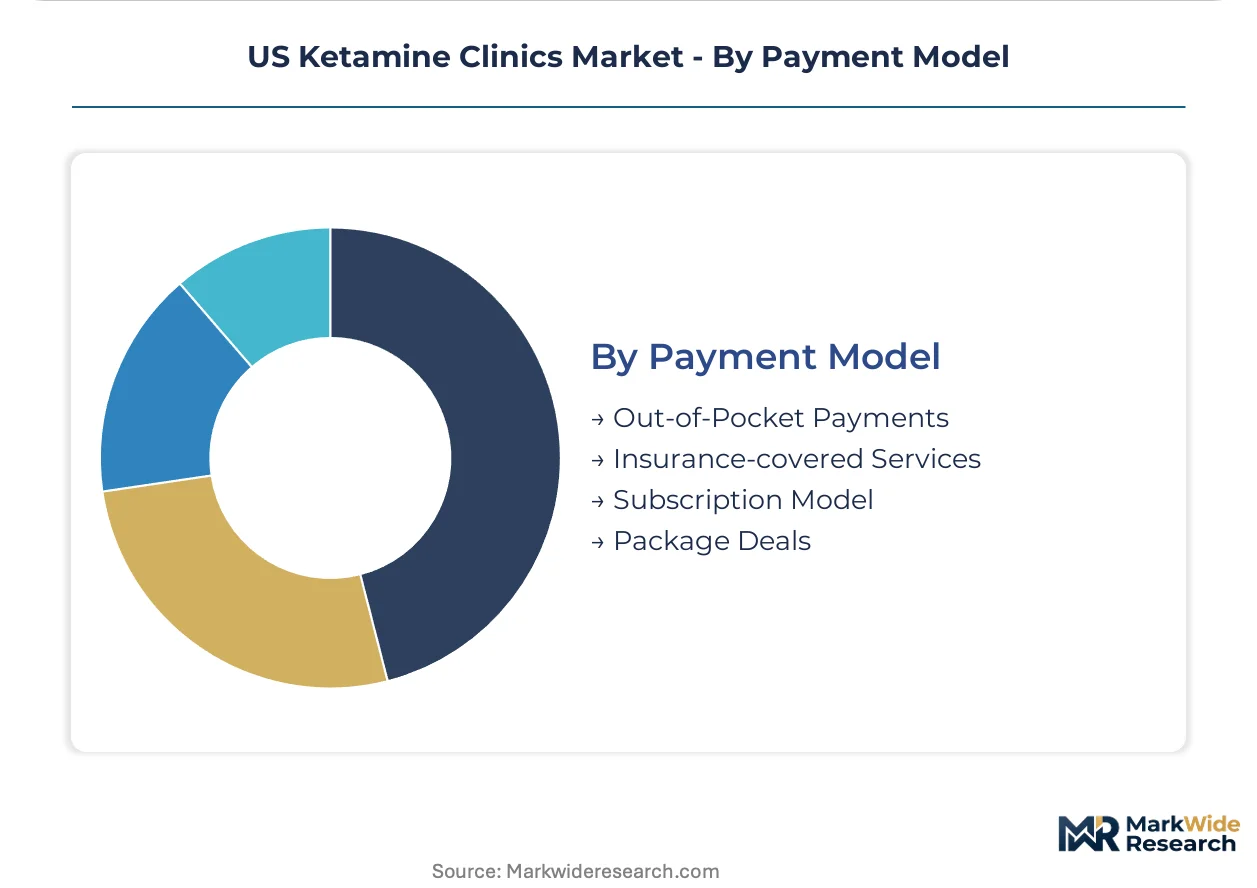
Payment Model:
Customer type stratification separates cash-pay wellness-oriented patients from coverage-dependent populations, with subscription structures emerging to smooth revenue cyclicality.
- Out-of-Pocket Payments:Direct patient financing dominates the generic ketamine segment where FDA-approved esketamine coverage gaps persist. Affluent metropolitan markets in California and Florida sustain premium pricing for concierge-style service delivery.
- Insurance-covered Services:Prior authorization requirements and formulary positioning for esketamine create revenue cycle friction, with Medicare Advantage plans showing variable coverage generosity across states.
- Subscription Model:Monthly membership structures bundle maintenance dosing protocols with remote monitoring, reducing per-session revenue concentration.
- Package Deals:Prepaid multi-session pricing addresses patient acquisition cost recovery while locking in treatment adherence.
Out-of-pocket payments retain volume leadership; subscription models hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Treatment-resistant depression patient density concentrates in metropolitan corridors where regulatory clarity intersects with affluent self-pay populations. Texas, Florida, and California anchor clinic network expansion due to favorable state medical board frameworks and veterans affairs referral volume.
California
Los Angeles and San Francisco metropolitan areas host the densest private clinic networks, with direct-to-consumer acquisition channels dominating patient intake. FDA oversight of compounded ketamine products has prompted hospital-based operators to strengthen pharmacy partnerships and documentation protocols. San Diego anchors specialized PTSD protocols serving military installations along the Southern California corridor.
Texas
Houston and Dallas-Fort Worth corridors concentrate chronic pain patient volume tied to workers compensation claim density and aging demographics. State Medicaid expansion decisions remain pending, constraining coverage-dependent patient access to esketamine formulations. Austin emerges as a telehealth-integrated clinic hub leveraging remote patient monitoring for maintenance dosing protocols.
Florida
Miami and Tampa metropolitan areas sustain premium cash-pay service delivery for concierge-style ketamine therapy. DEA Schedule III registration requirements align with existing pain management clinic infrastructure across the Gulf Coast. Orlando captures veterans affairs referral networks from central Florida military installations.
New York
Greater New York metropolitan corridor faces psychiatric specialty workforce scarcity that strains supervised medical infrastructure requirements. State medical board supervision ratio guidelines elevate compliance costs for intravenous therapy operators. Buffalo and Rochester clinics target cross-border Canadian patients seeking lower-cost alternatives.
US Ketamine Clinics Market Competitive Landscape
Player mix skews toward specialized mental health operators and telehealth-integrated platforms rather than hospital-based systems. Market structure fragments across independent private clinics, venture-backed digital health platforms, and academic medical center partnerships. Strategic archetypes include infusion-center specialists optimizing for per-session margins, remote-first platforms capturing maintenance dosing volume, and hybrid operators balancing supervised protocols with distributed care models. Dominant competitive moves center on geographic network scaling through de novo clinic openings and strategic partnerships with compounding pharmacies to secure supply chain access.
Within the telehealth-integrated tier, Mindbloom and Nue Life Health exemplify remote-first archetypes extending reach beyond traditional infusion centers. Klarity Clinic represents the infusion-specialist model with intravenous administration protocols anchoring premium service positioning. Field Trip Health occupies a position navigating state-level licensing variance to sustain multi-clinic operations across metropolitan corridors.
| Leading Market Players |
|---|
| Better U |
| Innerwell |
| Ketamine Clinics Los Angeles |
| Klarisana Health |
| Klarity Clinic |
| Mindbloom |
| Nue Life Health |
| NY Ketamine Infusions |
| Field Trip Health |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at DEA-registered 503B compounding pharmacies shapes both supply availability and minimum viable pricing for clinic operators across Texas, Florida, and California corridors. Scale concentration among sterile compounders with Schedule III storage infrastructure elevates price floors for intravenous protocols while compressing margins for smaller independent clinics lacking volume leverage.
Pricing Analysis
Cost-plus contracts with quarterly API indexation dominate generic ketamine sourcing agreements between clinic networks and compounding pharmacies. Three-tier pricing structure across concierge IV infusion, standard intranasal administration, and economy oral troche tiers separates premium supervised medical infrastructure from lower-overhead telehealth protocols. Cost compression in the oral segment is intensifying because FDA enforcement against non-compliant telehealth prescribers is restricting gray-market supply channels. Cash-pay depression patients in affluent metropolitan markets show lowest price sensitivity, while Medicaid-dependent populations in non-expansion states face highest access barriers due to prior authorization friction.
Supply Chain Analysis
Inventory lead times for sterile ketamine hydrochloride API stretch 8-12 weeks for 503B compounders lacking backward integration into active pharmaceutical ingredient manufacturing. Domestic supply draws from registered domestic compounders and limited import channels from India and selected European Union member states with FDA mutual recognition agreements. Single-source vulnerability concentrates at the API level where three manufacturers control bulk ketamine salt production for North American pharmaceutical use. Distribution runs through cold-chain logistics partners to DEA-registered clinic pharmacies with dual-lock storage and perpetual inventory tracking mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where DEA Schedule III registration requirements create substantial regulatory entrenchment protecting incumbent operators from rapid competitive displacement.
For Market Incumbents: Fortify supply chain positioning through exclusive compounding pharmacy partnerships that lock in API allocation priority during shortage periods. Expand capacity in Houston and Dallas-Fort Worth corridors where chronic pain patient density supports fixed cost absorption. Vertical integration into remote patient monitoring technology addresses emerging telehealth-integrated competitors threatening maintenance dosing revenue streams. For New Entrants and Emerging Players: Maintenance dosing protocol gaps in secondary metropolitan markets offer white-space entry points where established operators under-serve patients beyond initial induction series. Chronic pain syndromes including fibromyalgia and neuropathic pain represent the most penetrable indication expansion with limited specialized competition. Direct-to-consumer digital acquisition channels bypass entrenched psychiatric referral networks that incumbent clinics depend upon for patient intake. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid operators blending supervised infusion infrastructure with remote monitoring capabilities that capture both acute and maintenance revenue pools. Long-term viability hinges on Medicaid expansion trajectory and FDA esketamine coverage determinations that reshape addressable population economics. Watch state medical board supervision ratio guideline harmonization as inflection indicator for multi-clinic scaling feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Certification Expansion | Esketamine nasal spray administration under FDA REMS protocols enables broader prescriber access beyond anesthesiologist-dependent IV models. |
| Telehealth Platform Integration | Remote patient monitoring partnerships with wearable biosensor vendors fragment revenue toward distributed maintenance dosing protocols. |
| Hospital System Partnership | Academic medical center affiliations capture complex psychiatric referrals requiring integrated monitoring beyond standalone clinic capabilities. |
| Compounding Pharmacy Acquisition | Captive 503B infrastructure secures supply chain priority during API allocation constraints and elevates documentation compliance. |
| Chronic Pain Protocol Development | Fibromyalgia and neuropathic pain indications extend patient lifetime value through extended multi-session treatment courses. |
Research Methodology
Initial hypotheses were tested against primary input from ketamine clinic medical directors, DEA compliance officers, compounding pharmacy operations managers, and psychiatric nurse anesthetists and refined through secondary validation against FDA 483 inspection records, state medical board disciplinary databases, CMS Medicare claims extracts, and DEA controlled substance tracking system disclosures. Bottom-up clinic capacity modeling triangulated against top-down patient population epidemiology estimates derived from National Institute of Mental Health treatment-resistant depression prevalence studies.
Variance decomposition across treatment modality, patient acuity tier, clinic facility type, and state regulatory cluster shaped the analytical framework throughout the projection horizon. CAGRs were derived from segment-level patient volume trajectories and per-session revenue assumptions indexed to Medicaid coverage expansion scenarios and commercial payer prior authorization trend data. Modeled inputs incorporated DEA registration approval timelines, REMS certification penetration curves, and telehealth regulatory stability assumptions.
Forecasts assume regulatory continuity in DEA Schedule III controlled substance protocols and FDA compounded drug enforcement postures; material policy shifts including ketamine rescheduling or compounding pharmacy restriction would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Addiction Treatment
Opioid Use Disorder Treatment Market
Addiction Treatment
Drug Free Depression Treatment Market
Addiction Treatment
Opioid Withdrawal Treatment Market
Addiction Treatment
Opioid Use Disorder (OUD) Market
Addiction Treatment
Global Addiction Treatment Market
Addiction Treatment
Opioid Induced Constipation Treatment Market
Addiction Treatment
Cocaine Intoxication Treatment Market
Addiction Treatment
Methadone Market
Addiction Treatment
Smokeless Tobacco Treatment Market
Addiction Treatment
Nicotine De-Addiction Products Market
Addiction Treatment
US Mental Health and Addiction Treatment Centers Market
Addiction Treatment
Global Substance Use Disorder Treatment Market
Addiction Treatment
Substance Abuse Treatment Market
Addiction Treatment
Alcohol Use Disorder Treatment Market