
 Ibuprofen API Market | 2026-2036
Ibuprofen API Market Size, Share, and Industry Trends Forecast 2026-2036
Ibuprofen API Market Outlook
Contract manufacturing services is repositioning how ibuprofen API value gets captured, shifting margin from pure molecule sales to integrated formulation partnerships. IOL Chemicals and Pharmaceuticals Limited leverages backward integration into key starting materials to sustain cost leadership across bulk orders. Granules India Limited anchors its competitiveness through FDA-inspected facilities that supply regulated markets. BASF competes on pharmaceutical-grade purity standards and specialized impurity control capabilities.
Ibuprofen API denotes the active pharmaceutical ingredient of 2-(4-isobutylphenyl)propionic acid, a non-steroidal anti-inflammatory drug synthesized primarily through the Boots process or Hoechst-Celanese route with molecular formula C13H18O2. Pharmaceutical manufacturers represent the dominant end-user segment, where direct sales channels concentrate margin pools through long-term supply agreements with integrated formulation houses. Tablet formulations within the solid dosage category lead volume consumption, while powder forms serve compounding pharmacies and regional generics producers seeking flexibility in final dosage design.
ICH Q3D elemental impurity guidelines and FDA current Good Manufacturing Practice inspections shape supplier qualification barriers, particularly for facilities serving US and European markets. India's CDSCO and China's NMPA enforce parallel but distinct registration pathways that fragment market access requirements. Stakeholders must monitor evolving pharmacopeial monograph revisions and bioequivalence study demands for complex generic ibuprofen formulations.
Market Dynamics
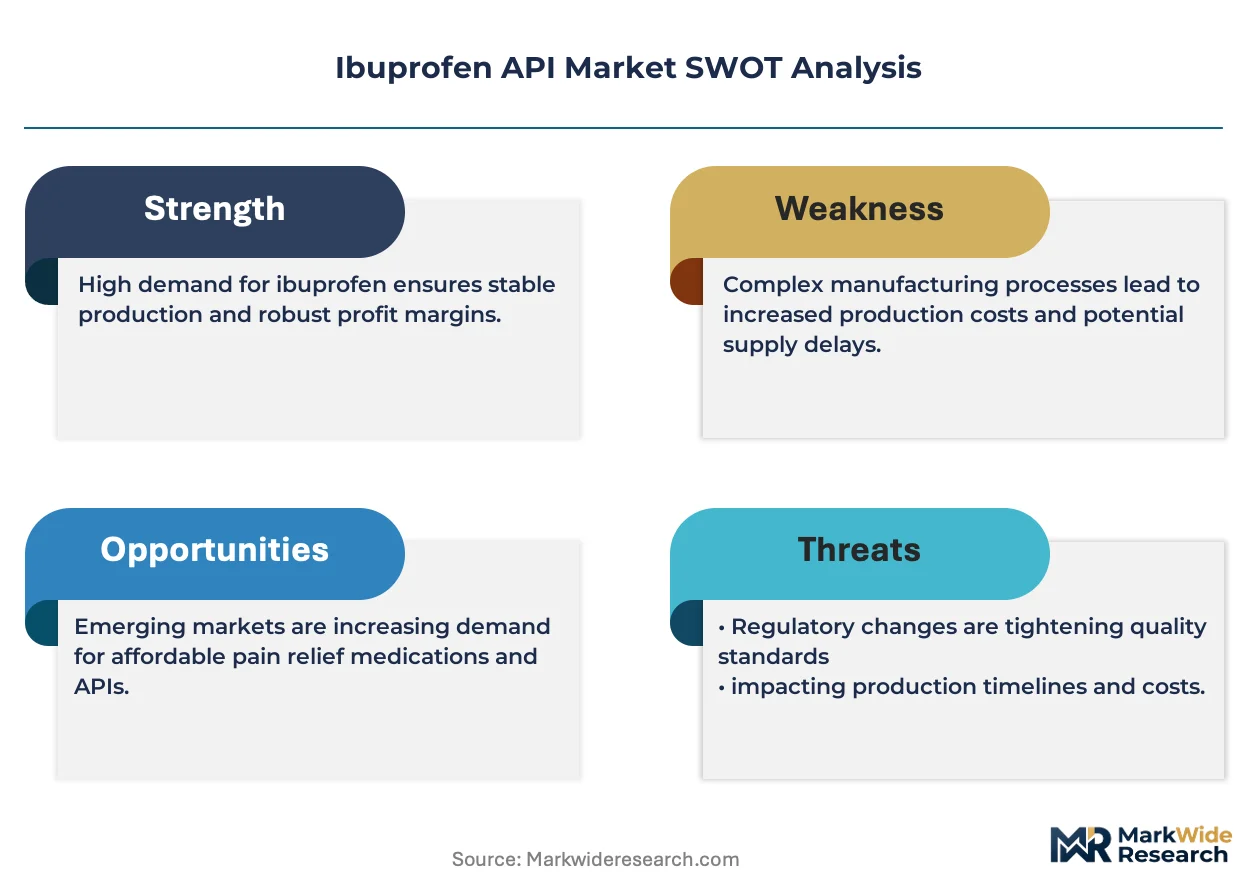
ICH Q3D elemental impurity guidelines are forcing API manufacturers to rebuild quality infrastructure around metal detection and control, compressing supplier margins while elevating qualification barriers for contract manufacturers serving regulated markets.
Growth Catalysts
- OTC analgesic volume expansion:Retail pharmacy chains in the United States and Germany are expanding private-label ibuprofen tablet offerings, pulling bulk API orders through direct sourcing agreements with integrated formulation houses.
- REACH compliance harmonization:European chemical registration pathways are consolidating impurity documentation standards, reducing redundant testing costs for API exporters targeting EMA-regulated markets.
- Continuous manufacturing adoption:Pharmaceutical-grade powder processing is replacing batch synthesis in select facilities, compressing cycle times for high-volume oral solid dosage production.
Market Restraints
- Starting material cost volatility:Isobutylbenzene and acetic anhydride price swings compress margin predictability for Boots process operators dependent on petrochemical feedstock chains.
- Indian supply concentration:Bulk API production clusters in Hyderabad and Vadodara create geographic risk exposure for buyers lacking qualified secondary sources under FDA inspection protocols.
- Genotoxic impurity thresholds:ICH M7 guideline limits on nitrosamine and alkyl sulfonate residues require costly analytical method upgrades and extended stability validation timelines.
Strategic Opportunities
- Brazilian generics acceleration:ANVISA simplified registration pathways for essential medicines are opening volume opportunities for FDA-inspected Indian suppliers with established South American distribution.
- Specialty impurity profiling services:Contract laboratories offering ICP-MS elemental analysis and forced degradation studies are capturing margin pools adjacent to commodity API sales.
- Hospital formulary consolidation:Integrated delivery networks in the United States are centralizing procurement around single-source injectable and oral solid contracts, favoring suppliers with end-to-end documentation capabilities.
Industry Challenges
- Analytical chemist scarcity:Qualified personnel capable of ICH Q2(R1) method validation and Q3D risk assessment are concentrated among top-tier contract research organizations, inflating salary benchmarks for mid-cap API houses.
- Legacy facility retrofit costs:Containment upgrades for OSHA-compliant handling of potent compounds and EPA-permitted solvent recovery systems demand capital deployment that strains privately held manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ibuprofen API Market |
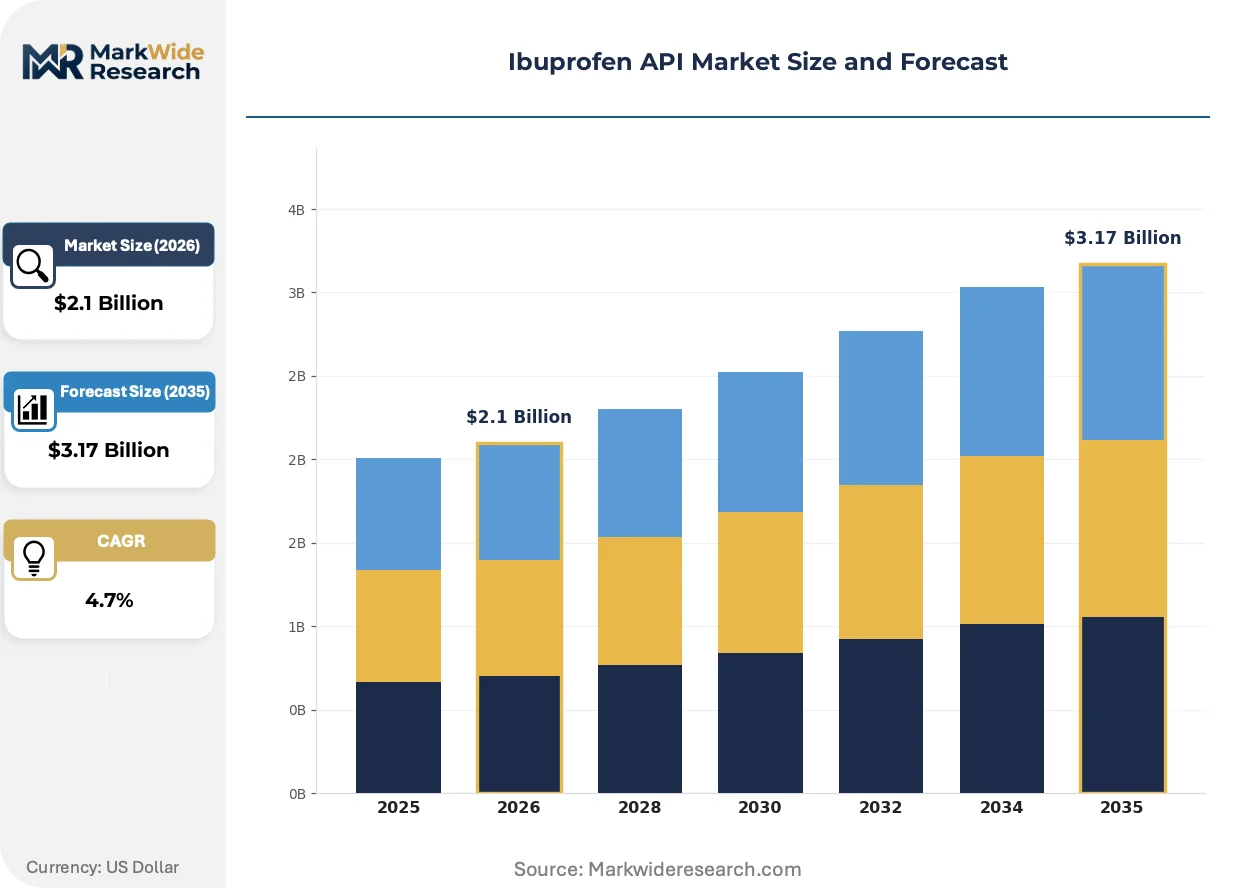
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.17 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Tablets, Capsules, Powder End User: Pharmaceutical Manufacturers, Contract Research Organizations, Hospitals, Retail Pharmacies Formulation: Liquid, Solid, Semi-Solid, Gel Distribution Channel: Direct Sales, Wholesalers, Online Pharmacies, Distributors |
| Companies Covered | SI Group, Granules India Limited, IOL Chemicals and Pharmaceuticals Limited, Teva API, Rochem International Inc., BASF, Hubei Biocause Pharmaceutical, Xinhua Pharmaceutical, Solara Active Pharma Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ibuprofen API Market Strategic Shifts
Process analytical technology and real-time release testing are compressing quality verification timelines, while regulatory convergence around elemental impurity standards is homogenizing supplier qualification protocols across major markets.
Continuous flow chemistry is absorbing batch inefficiencies in ibuprofen synthesis, enabling tighter temperature control and reduced solvent volumes. Mid-cap API manufacturers in India are piloting these systems for high-volume orders destined for North American retail chains. The technology is absorbing capital that would otherwise fund geographic expansion, concentrating investment among established players with existing regulatory dossiers.
REACH authorization requirements for critical solvents are forcing reformulation of purification steps in European-bound production. Manufacturers serving EMA markets are substituting dichloromethane-dependent crystallization with aqueous-based alternatives, extending development timelines by 12-18 months for process changes requiring regulatory filing. German and Swiss formulation houses are responding by pre-qualifying suppliers with verified green-chemistry pathways.
Hospital procurement groups are consolidating annual API contracts around outcome metrics including batch consistency and documentation turnaround time. Group purchasing organizations in the United States are displacing spot-market purchasing with multi-year agreements that bundle analytical services and regulatory support. This concentration is most visible in the southeastern United States, where integrated delivery networks have reduced qualified supplier pools to three-to-four API houses per therapeutic category.
Ibuprofen API Market Segmentation
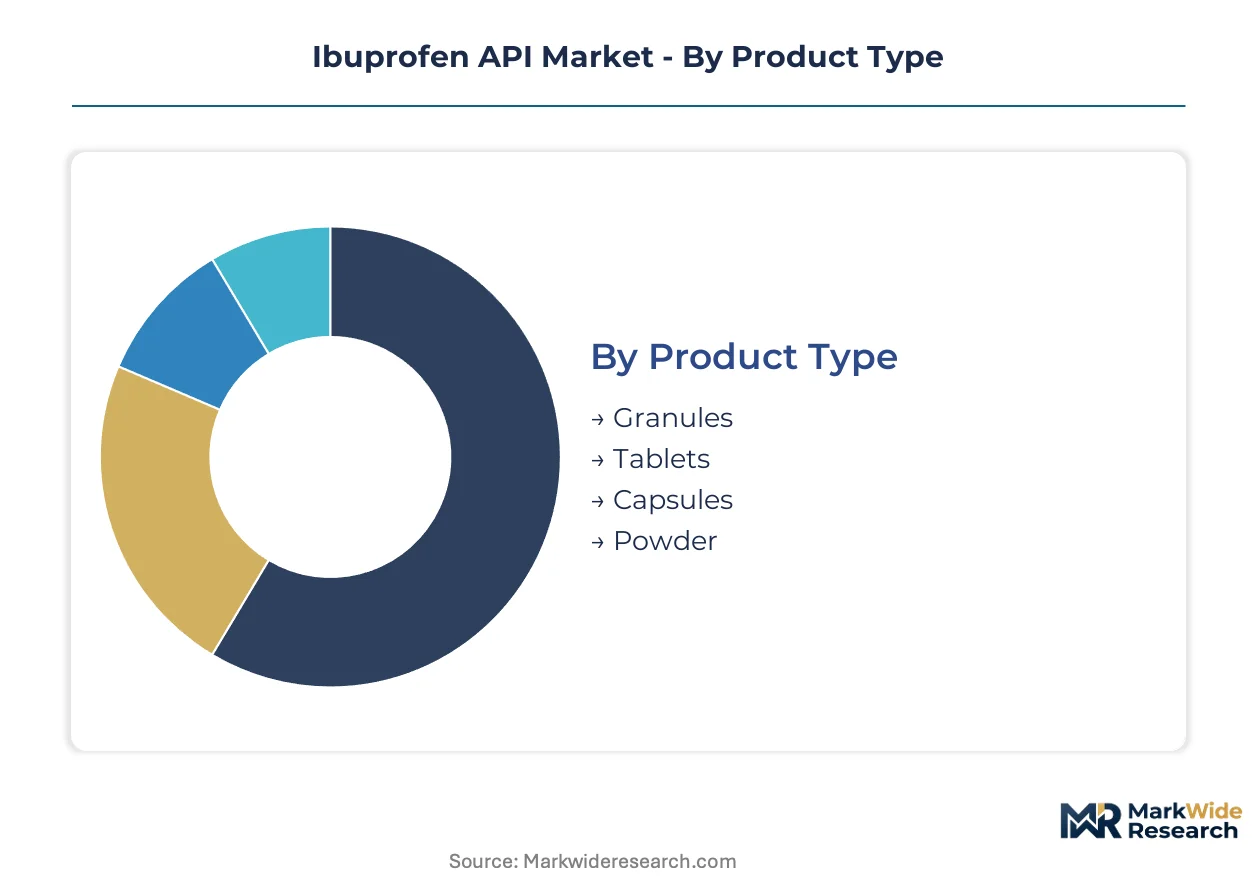
Ibuprofen API demand fragments across formulation technologies and procurement channels that reshape supplier qualification requirements. Pharmaceutical buyers select API grades based on finished dosage specifications, regulatory filing pathways, and manufacturing equipment compatibility.
Product Type:
Form selection drives equipment investment cycles and stability validation timelines for API buyers planning production line upgrades.
- Granules:Intermediate processed material with defined particle size distribution enables direct compression tableting without additional milling steps. North American contract manufacturers favor granules for high-speed rotary press operations serving retail pharmacy private-label programs.
- Tablets:Compressed solid dosage forms containing ibuprofen API with excipient matrices dominate volume consumption through automated packaging lines. German and United States retail chains pull tablet-grade API through long-term supply agreements with integrated formulation houses seeking batch-to-batch dissolution profile consistency.
- Capsules:Gelatin or HPMC shells encapsulating ibuprofen powder or granules serve markets requiring taste masking and modified release profiles.
- Powder:Unprocessed crystalline API with specified particle morphology serves compounding pharmacies and regional generics producers seeking formulation flexibility.
Tablets sit at the top of the volume ranking, with granules climbing the fastest as continuous manufacturing adoption accelerates.
End User:
Procurement sophistication varies sharply across buyer categories, with regulatory documentation requirements determining supplier eligibility tiers.
- Pharmaceutical Manufacturers:Integrated formulation houses with FDA-inspected facilities purchase API under master service agreements specifying ICH Q3D elemental impurity limits and forced degradation data packages. Direct sales channels concentrate margin pools through multi-year contracts with United States and European buyers.
- Contract Research Organizations:CROs engaged in bioequivalence studies for complex generic ibuprofen formulations require reference-standard API with comprehensive impurity profiling and stability data.
- Hospitals:Integrated delivery networks in the United States centralize procurement around single-source contracts bundling API, analytical services, and regulatory support.
- Retail Pharmacies:Private-label program operators source through qualified distributors rather than direct API relationships, pushing quality accountability upstream.
Pharmaceutical manufacturers command the largest procurement volumes, with contract research organizations expanding most quickly as complex generic filings multiply.
Formulation:
Physical state determines solubility enhancement requirements, packaging configurations, and shelf-life validation protocols for API specification.
- Liquid:Suspension or solution formulations requiring micronized API with controlled particle size for pediatric and geriatric dosing applications.
- Solid:Tablets, capsules, and granules dominate commercial volumes through mechanical stability and dose precision advantages in high-speed packaging operations.
- Semi-Solid:Cream and ointment bases incorporating ibuprofen for topical anti-inflammatory applications serve dermatology and sports medicine segments.
- Gel:Hydrogel matrices enabling transdermal absorption require specialized API dissolution characteristics and permeation enhancer compatibility.
Solid formulations anchor procurement volumes, with gel applications gaining share fastest in topical pain management segments.
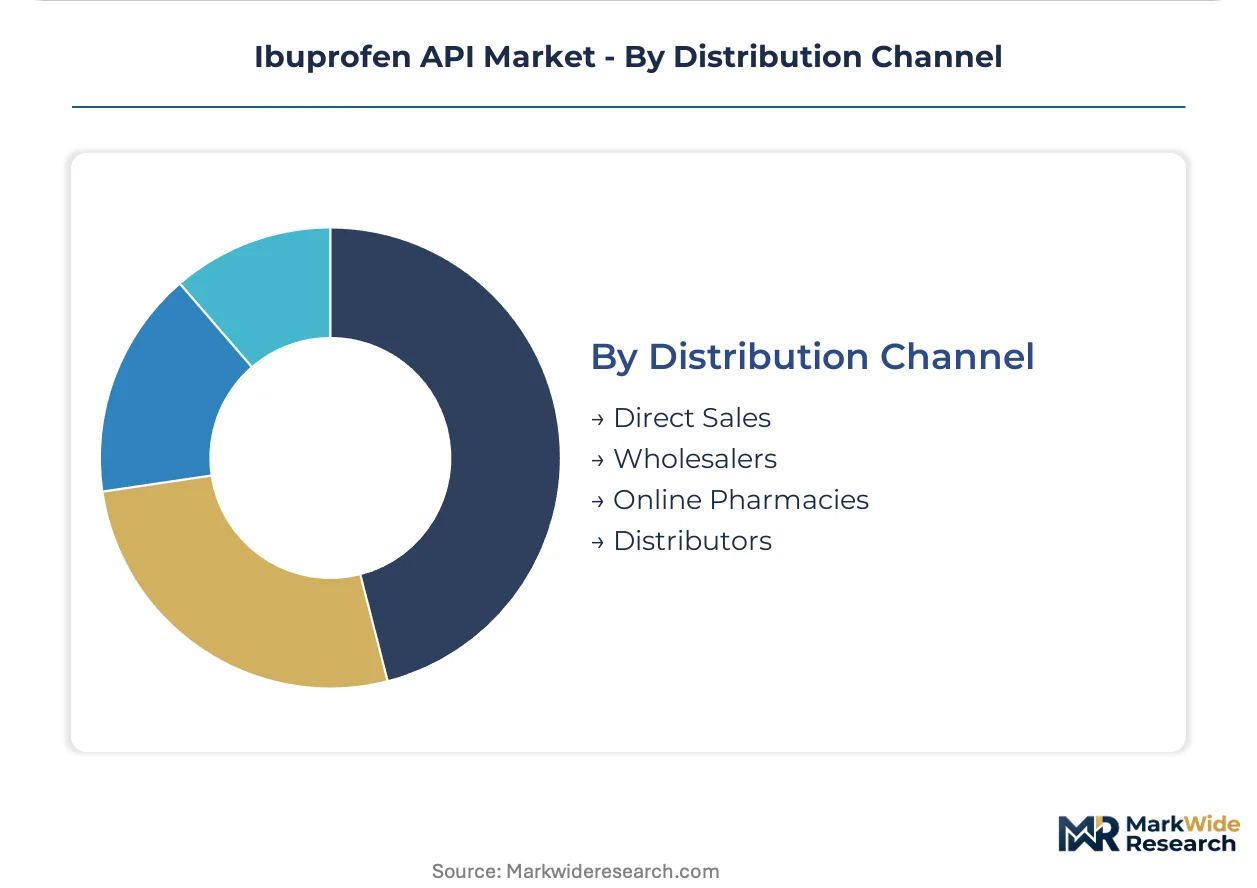
Distribution Channel:
Channel structure determines documentation custody, batch traceability, and quality agreement enforcement mechanisms for API transactions.
- Direct Sales:Long-term supply agreements between API manufacturers and integrated formulation houses eliminate intermediary margins while locking in volume commitments and regulatory dossier co-development. Indian suppliers with FDA-inspected facilities leverage direct relationships with United States and German buyers.
- Wholesalers:Regional inventory aggregation serves mid-cap generics producers lacking qualified supplier qualification capabilities or minimum order scale for direct manufacturer relationships.
- Online Pharmacies:Digital procurement platforms fragment order sizes and compress documentation exchange timelines, creating quality verification challenges for buyers.
- Distributors:Authorized representatives with established regulatory filing support and local warehousing serve emerging market manufacturers navigating CDSCO or NMPA registration pathways.
Direct sales channels capture the largest transaction values, with online pharmacies expanding most quickly as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands bulk synthesis capacity while India dominates FDA-inspected formulation supply, creating a bifurcated sourcing geography for ibuprofen API procurement.
United States
Hospital formulary consolidation and private-label retail expansion drive API demand through direct sourcing agreements. FDA inspection protocols and ICH Q3D compliance requirements elevate qualification barriers for foreign suppliers. New Jersey and North Carolina host formulation clusters where integrated delivery networks centralize procurement around documented batch consistency.
Germany
EMA-regulated buyers prioritize REACH-compliant green-chemistry pathways over traditional solvent-dependent synthesis. German retail pharmacy chains pull tablet-grade API through long-term supply agreements demanding forced degradation data packages. The Rhine-Ruhr and Bavarian chemical corridors concentrate formulation houses pre-qualifying suppliers with verified impurity control capabilities.
India
Hyderabad and Vadodara production clusters supply bulk API under CDSCO oversight while maintaining parallel FDA inspection readiness for export markets. PLI scheme incentives support backward integration into key starting materials. Domestic formulation houses increasingly serve African and Latin American markets through simplified registration pathways.
China
NMPA registration requirements and dual carbon goals reshape synthesis economics for export-oriented manufacturers. Shandong and Jiangsu provinces concentrate Boots process operators facing petrochemical feedstock volatility. State-backed consolidation is absorbing smaller facilities unable to fund elemental impurity detection infrastructure.
Brazil
ANVISA simplified registration pathways for essential medicines accelerate generic ibuprofen volume uptake. São Paulo and Rio de Janeiro formulation clusters source API through established South American distribution networks. Local procurement is shifting from spot-market purchasing toward multi-year agreements with Indian suppliers holding FDA inspection credentials.
Ibuprofen API Market Competitive Environment
Top-tier vendors anchor regulated-market supply, while mid-cap specialists compete on cost leadership for emerging market volume. The vendor base stratifies across three tiers: integrated chemical conglomerates with pharmaceutical-grade purity capabilities, Indian and Chinese bulk manufacturers with backward integration into starting materials, and regional distributors serving spot-market demand. Strategic differentiation concentrates on ICH Q3D compliance infrastructure, continuous manufacturing adoption, and green-chemistry pathway verification.
Among Indian API houses, Granules India Limited and IOL Chemicals and Pharmaceuticals Limited occupy positions exemplifying the backward-integrated cost leadership archetype. BASF represents the pharmaceutical-grade purity standard segment serving EMA-regulated European markets. Solara Active Pharma Sciences and Teva API sit within the contract manufacturing tier where integrated formulation partnerships displace pure molecule sales.
| Leading Market Players |
|---|
| SI Group |
| Granules India Limited |
| IOL Chemicals and Pharmaceuticals Limited |
| Teva API |
| Rochem International Inc. |
| BASF |
| Hubei Biocause Pharmaceutical |
| Xinhua Pharmaceutical |
| Solara Active Pharma Sciences |
| Others |
Value Chain & Pricing Dynamics
ICH Q3D elemental impurity mandates are forcing API buyers to consolidate procurement around suppliers with verified metal detection infrastructure, compressing margin pools for mid-tier manufacturers while elevating price premiums for FDA-inspected facilities with documented forced degradation capabilities.
Pricing Analysis
Capacity additions in Shandong and Jiangsu provinces are reshaping price floors for standard-grade ibuprofen API entering emerging markets. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and feedstock-tier levels separates EMA-compliant suppliers with ICP-MS capabilities from CDSCO-registered houses serving domestic Indian formulations. Cost compression in the technical-grade tier is intensifying because NMPA environmental inspections are absorbing capital that would otherwise fund quality upgrades. Hospital procurement groups in the United States exhibit the lowest price sensitivity, prioritizing batch consistency documentation over per-kilogram savings.
Supply Chain Analysis
India's PLI scheme domestic-content requirements are reshaping sourcing patterns for key starting materials, compelling formulators to pre-qualify backward-integrated suppliers with captive isobutylbenzene production. Manufacturing gravity centers on India, China, and Germany, with Boots process operators drawing from petrochemical feedstock chains anchored in Shandong province. Supply chain risk concentrates in single-source vulnerability for FDA-inspected granule processing, where Hyderabad and Vadodara clusters dominate qualified capacity. Distribution runs through direct sales agreements between API manufacturers and integrated formulation houses, displacing spot-market intermediaries for regulated-market volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ibuprofen API market reads as a late-cycle quality story, with hospital formulary consolidation and ICH Q3D compliance elevating procurement criteria toward documented impurity control capabilities over pure cost optimization.
For Market Incumbents: Lock in multi-year supply agreements with United States integrated delivery networks before REACH authorization requirements force additional solvent substitution investments. Prioritize ICP-MS elemental analysis infrastructure to defend margin position against emerging Indian suppliers with backward integration into isobutylbenzene. Channel control through direct sales relationships remains the critical lever for sustaining premium pricing in EMA-regulated markets. For New Entrants and Emerging Players: Digital procurement platforms serving mid-cap Brazilian generics producers represent the most penetrable white-space target, as ANVISA simplified registration pathways reduce documentation barriers for first-time suppliers. Compounding pharmacy distribution in North American secondary markets offers formulation flexibility demand that bypasses direct competition with integrated formulation houses. A specialized impurity profiling service model—bundling ICH Q3D risk assessment with API supply—provides the strongest go-to-market angle against commodity incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with Indian mid-cap API houses with existing FDA inspection credentials and unexploited backward integration potential into acetic anhydride derivatives. Long-term viability over the projection horizon hinges on regulatory dossier depth rather than pure volume scale, favoring acquisition targets with documented EMA submission history. The signal to watch is NMPA consolidation policy absorbing sub-scale Chinese facilities, which would tighten qualified supplier pools and elevate pricing power for surviving players with environmental compliance infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Key Starting Materials | IOL Chemicals' captive isobutylbenzene production insulates margin predictability from petrochemical volatility. |
| ICH Q3D Compliance Infrastructure Investment | Granules India's ICP-MS capabilities unlock EMA-regulated hospital procurement contracts with documented elemental impurity control. |
| Continuous Manufacturing Adoption | Mid-cap Indian facilities piloting flow chemistry compress cycle times for high-volume North American retail chain orders. |
| Green-Chemistry Pathway Verification | German formulation houses pre-qualify suppliers with aqueous-based crystallization replacing dichloromethane-dependent purification steps. |
| Direct Sales Channel Consolidation | Integrated delivery networks in the southeastern United States centralize procurement around three-to-four qualified API houses per therapeutic category. |
Study Parameters
Multiple input streams — regulatory filing databases, customs trade records, and pharmaceutical procurement contracts — were reconciled through structured primary interviews with API manufacturing executives, regulatory affairs directors at formulation houses, hospital GPO contract managers, and CDSCO registration specialists. Secondary validation drew from FDA inspection classification databases, EMA submission portals, Indian PLI scheme disbursement records, and NMPA environmental compliance disclosures. Bottom-up volume estimates from individual facility capacities were cross-referenced against top-down demand projections from dosage form production data.
Historical capacity utilization trends were cross-referenced against panel input from procurement directors at United States integrated delivery networks and German retail pharmacy chains to anchor growth assumptions across the analysis window. Segmentation modeling incorporated formulation technology, end-user procurement sophistication, regulatory compliance tier, and regional inspection protocol cluster. CAGR derivation rested on reconciling patent expiry timelines for branded ibuprofen formulations with bioequivalence study filing patterns for complex generic entrants.
The model assumes a particular technology adoption path for continuous flow chemistry; alternative pathways for batch synthesis retention would alter the outlook if capital constraints delay facility retrofits beyond current planning horizons. Forecasts reflect assumptions around REACH solvent authorization timelines and NMPA dual carbon enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Aspirin API Market
Pharmacology
Pegylated Drugs Market
Pharmacology
Thromboprophylactic Drugs Market
Pharmacology
Artemisinin Antimalarial Drugs Market
Pharmacology
Clot Busting Drugs Market
Pharmacology
Autacoids and Related Drugs Market
Pharmacology
Aldosterone Receptor Antagonists Market
Pharmacology
Drug Repurposing Market
Pharmacology
Anti-Hypertensive Drugs Market
Pharmacology
Antithrombotic Drugs Market
Pharmacology
Global Pharmacokinetics Services Market
Pharmacology
Prescription Narcotic Cough Preparations and Expectorants Market
Pharmacology
Alzheimer's Therapeutics Market
Pharmacology
Anti-Obesity Therapeutics Market
Pharmacology
Global Asthma Therapeutics Market
Pharmacology
Antitussive Drugs Market