
 Apixaban Market | 2026-2036
Apixaban Market Size, Share, and Industry Trends Forecast 2026-2036
Apixaban Market Analysis
The FDA's abbreviated new drug application pathway is restructuring cost-of-entry calculus for generic apixaban entrants. Bristol-Myers Squibb Company anchors the branded segment through extensive patent estate litigation and manufacturing scale. Pfizer Inc. leverages its co-development heritage to sustain hospital formulary presence. Sun Pharmaceutical Industries Ltd. competes on cost positioning in emerging markets.
Apixaban is a direct factor Xa inhibitor anticoagulant synthesized through multi-step organic chemistry involving pyrazole and naphthalene core structures, formulated primarily as film-coated tablets for oral bioavailability. It prevents thrombin generation and clot formation without routine INR monitoring, displacing warfarin in atrial fibrillation stroke prevention and post-orthopedic surgery prophylaxis. Tablet formulations dominate volume due to outpatient convenience and established dosing regimens, while the atrial fibrillation therapy area captures the deepest margin pools as chronic lifetime therapy. Hospital end users anchor procurement volume through centralized pharmacy committees, though homecare channels are gaining share as self-administration protocols expand.
The FDA oversees bioequivalence standards for generic entrants, while the EMA enforces pharmacovigilance reporting across European markets; both frameworks elevate manufacturing quality compliance as a non-negotiable market access condition. The WHO prequalification program shapes purchasing decisions for institutional buyers in lower-income health systems. Stakeholders must monitor ANDA litigation outcomes and biosimilar naming policy shifts to calibrate portfolio timing.
Market Dynamics
Generic entry through the FDA's abbreviated new drug application pathway is compressing branded pricing power while expanding patient access to factor Xa inhibitor therapy. Patent litigation outcomes between originators and first-to-file challengers now determine market structure more than clinical differentiation.
Growth Catalysts
- Medicare reimbursement alignment:Outpatient oral anticoagulant coverage under Medicare Part D reduces patient out-of-pocket exposure versus parenteral alternatives, accelerating formulary conversion from warfarin in United States health systems.
- Stroke prevention protocols:Updated cardiology society guidelines elevating direct oral anticoagulants to first-line status for non-valvular atrial fibrillation are driving protocol revisions across hospital pharmacy committees.
- Orthopedic surgery expansion:Rising joint replacement volumes in aging populations generate sustained demand for post-operative thromboprophylaxis, with apixaban tablets displacing injectable low-molecular-weight heparin in enhanced recovery pathways.
Market Restraints
- Active pharmaceutical ingredient concentration:Pyrazole derivative manufacturing concentrates among a limited base of specialized chemical suppliers, creating vulnerability to single-source disruption or quality enforcement actions.
- Patent estate thickness:Layered formulation and crystalline polymorph patents extend effective market exclusivity periods, delaying generic substitution even after core composition-of-matter expiration.
- Bleeding risk liability:Lack of approved reversal agents relative to warfarin's vitamin K antidote generates malpractice exposure and residual clinician hesitation in high-fall-risk patient populations.
Strategic Opportunities
- Homecare channel expansion:Self-administration protocols for extended prophylaxis are shifting dispensing from hospital outpatient pharmacies to specialty mail-order distributors, capturing margin through direct patient engagement.
- Emerging market access:WHO prequalification procurement programs in lower-income health systems favor cost-competitive tablet formulations, opening volume opportunities for manufacturers with demonstrated bioequivalence.
- Combination therapy positioning:Antiplatelet co-therapy regimens for post-acute coronary syndrome populations present expansion potential beyond standalone atrial fibrillation indications.
Industry Challenges
- Bioequivalence study complexity:Demonstrating pharmacokinetic equivalence for highly variable drugs demands larger subject populations and extended analytical validation timelines, compressing generic development economics.
- Pharmacovigilance infrastructure:Post-market bleeding event reporting obligations under EMA and FDA frameworks require specialized safety database capabilities that strain mid-tier manufacturer resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apixaban Market |
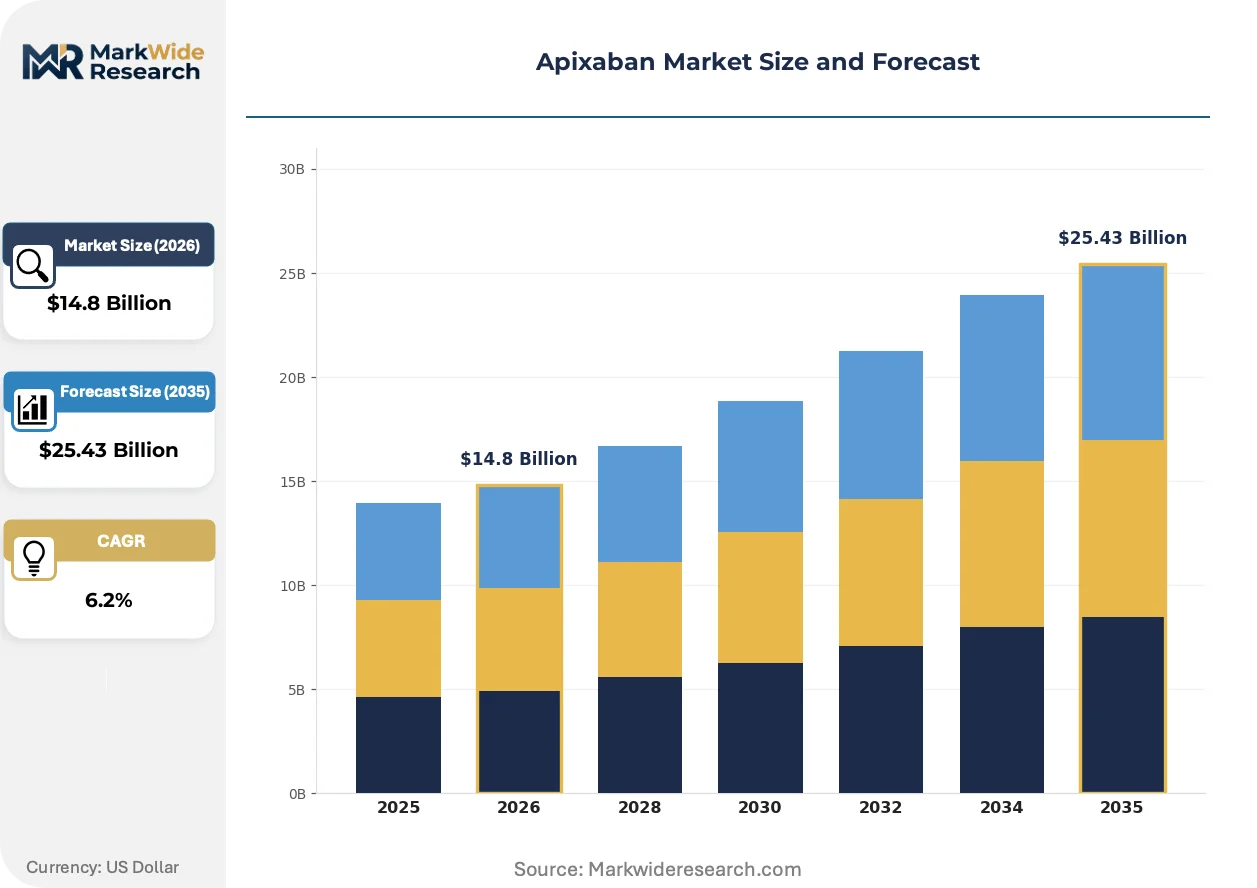
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injectable, IV Administration, Oral Solution Therapy Area: Atrial Fibrillation, Venous Thromboembolism, Coronary Artery Disease, Post-Surgery End User: Hospitals, Outpatient Clinics, Homecare, Pharmacies Distribution Channel: Direct Sales, Wholesalers, Online Pharmacies, Retail Pharmacies |
| Companies Covered | Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., Bristol-Myers Squibb Company, Dr. Reddy’s Laboratories Ltd., Aurobindo Pharma Limited, Pfizer Inc., Sandoz Group AG, Daiichi Sankyo Company Limited, Viatris Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apixaban Market Emerging Trajectories
Digital health integration and manufacturing process intensification are reshaping how anticoagulant therapy is delivered and produced. These developments compress traditional competitive advantages while opening new value capture mechanisms.
Continuous manufacturing technology is integrating into active pharmaceutical ingredient synthesis, replacing batch-wise pyrazole cyclization with flow chemistry platforms that reduce solvent waste and improve yield consistency. Contract development and manufacturing organizations in Ireland and Singapore are deploying these systems to secure quality certifications that accelerate regulatory approvals. The structural consequence is a compression of cost curves for generic entrants while raising compliance barriers for traditional batch manufacturers.
The FDA's Risk Evaluation and Mitigation Strategy requirements for direct oral anticoagulants are tightening prescriber education and patient counseling obligations beyond standard labeling. These mandates elevate documentation burdens for hospital outpatient departments and retail pharmacy chains, driving investment in integrated electronic health record decision support tools. Small independent practices face disproportionate compliance costs, accelerating consolidation into health system employment models.
Hospital pharmacy committees are consolidating formularies around preferred direct oral anticoagulant agents through exclusive contracting with integrated delivery networks. This concentration displaces traditional physician-directed prescribing autonomy with centralized therapeutic class reviews and automated substitution protocols. The United States exhibits the most pronounced shift, with three-quarters of major health systems now maintaining single-agent preferred status for factor Xa inhibitors.
Apixaban Market Segmentation
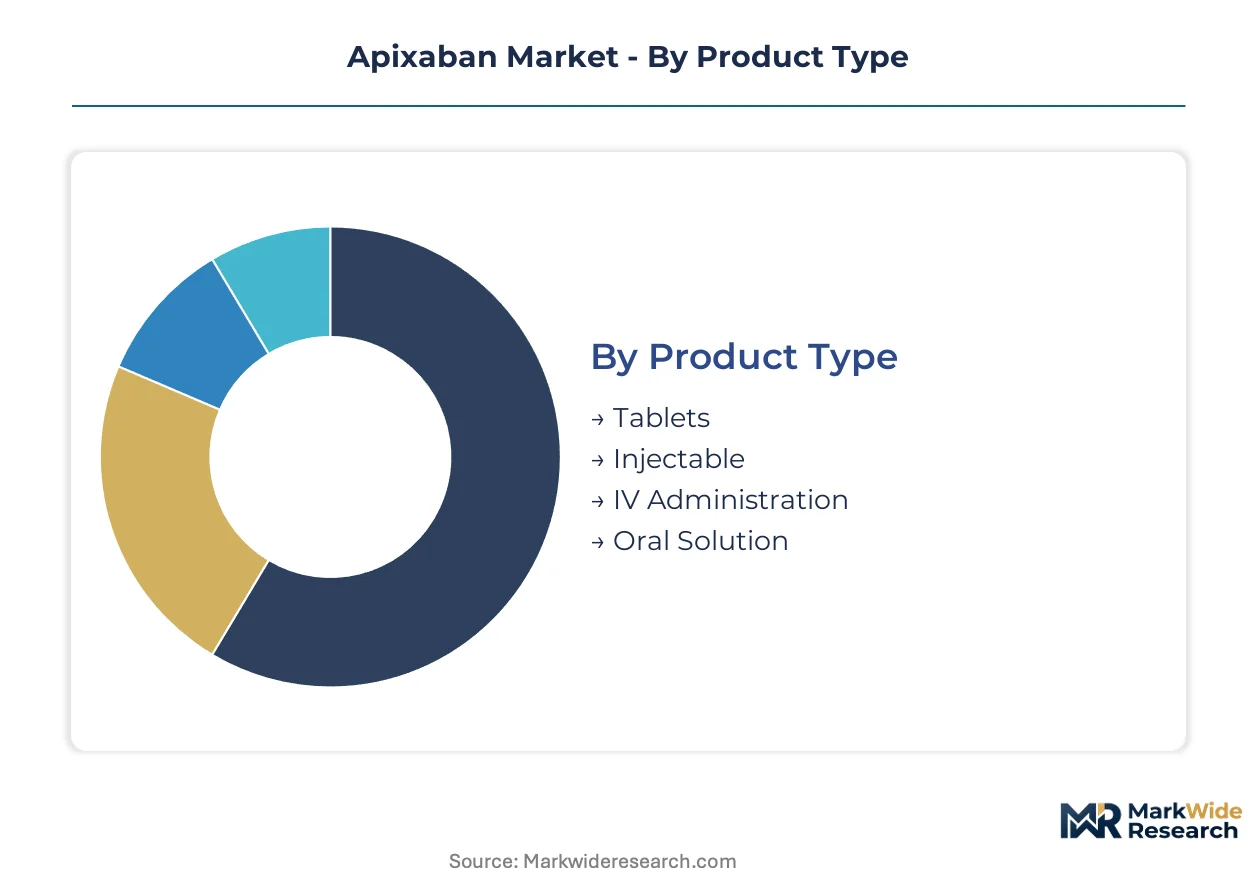
Apixaban market segmentation reveals divergent margin structures across formulation types and care settings. Tablet formulations dominate outpatient volume while hospital procurement concentrates on injectable alternatives for perioperative protocols.
Product Type:
Volume concentrates in oral solid dosage forms, yet premium pricing attaches to parenteral alternatives where bioavailability engineering demands specialized manufacturing.
- Tablets:Film-coated 2.5mg and 5mg strengths constitute the standard of care for chronic anticoagulation. Hospital outpatient pharmacies in the United States process the majority of dispenses, driven by Medicare Part D reimbursement alignment and self-administration protocols.
- Injectable:Subcutaneous formulations command premium positioning for perioperative bridging and nil-per-os patient populations. Orthopedic surgery departments in Germany and France anchor European demand through enhanced recovery after surgery pathways.
- IV Administration:Intravenous presentations serve critical care units where immediate anticoagulation reversal capability is prioritized over oral convenience.
- Oral Solution:Liquid formulations address dysphagia populations and pediatric off-label use, though regulatory labeling restricts commercial promotion.
Today's leader: Tablets. Tomorrow's challenger: Injectable.
Therapy Area:
Application concentration follows guideline evolution, with cardiology society recommendations determining formulary placement across health systems.
- Atrial Fibrillation:Non-valvular atrial fibrillation stroke prevention generates lifetime therapy demand with the deepest margin pools. United States cardiology practices drive volume through CHA2DS2-VASc score implementation and direct oral anticoagulant-first protocols.
- Venous Thromboembolism:Deep vein thrombosis and pulmonary embolism treatment represents the indication with steepest expansion trajectory as extended prophylaxis protocols displace warfarin.
- Coronary Artery Disease:Post-acute coronary syndrome antiplatelet co-therapy presents emerging positioning opportunity beyond standalone anticoagulation.
- Post-Surgery:Joint replacement thromboprophylaxis generates procedure-tied demand with standardized 35-day dosing regimens in orthopedic surgery.
Primary revenue attaches to chronic indications; acute care applications deliver volume volatility tied to surgical scheduling.
End User:
Procurement authority is shifting from physician-directed prescribing toward centralized pharmacy committee control.
- Hospitals:Inpatient pharmacy committees anchor procurement volume through therapeutic class reviews and automated substitution protocols.
- Outpatient Clinics:Hospital-affiliated ambulatory settings process the majority of initial prescriptions following cardiology consultation.
- Homecare:Specialty infusion and mail-order distributors are gaining share as extended prophylaxis protocols shift dispensing beyond hospital walls.
- Pharmacies:Retail chains face margin compression from formulary exclusion and preferred network restrictions.
Institutional buyers consolidate purchasing power; direct-to-patient channels seek engagement bypass.
Distribution Channel:
Channel configuration reflects reimbursement mechanics and inventory carrying cost tradeoffs across the supply chain.
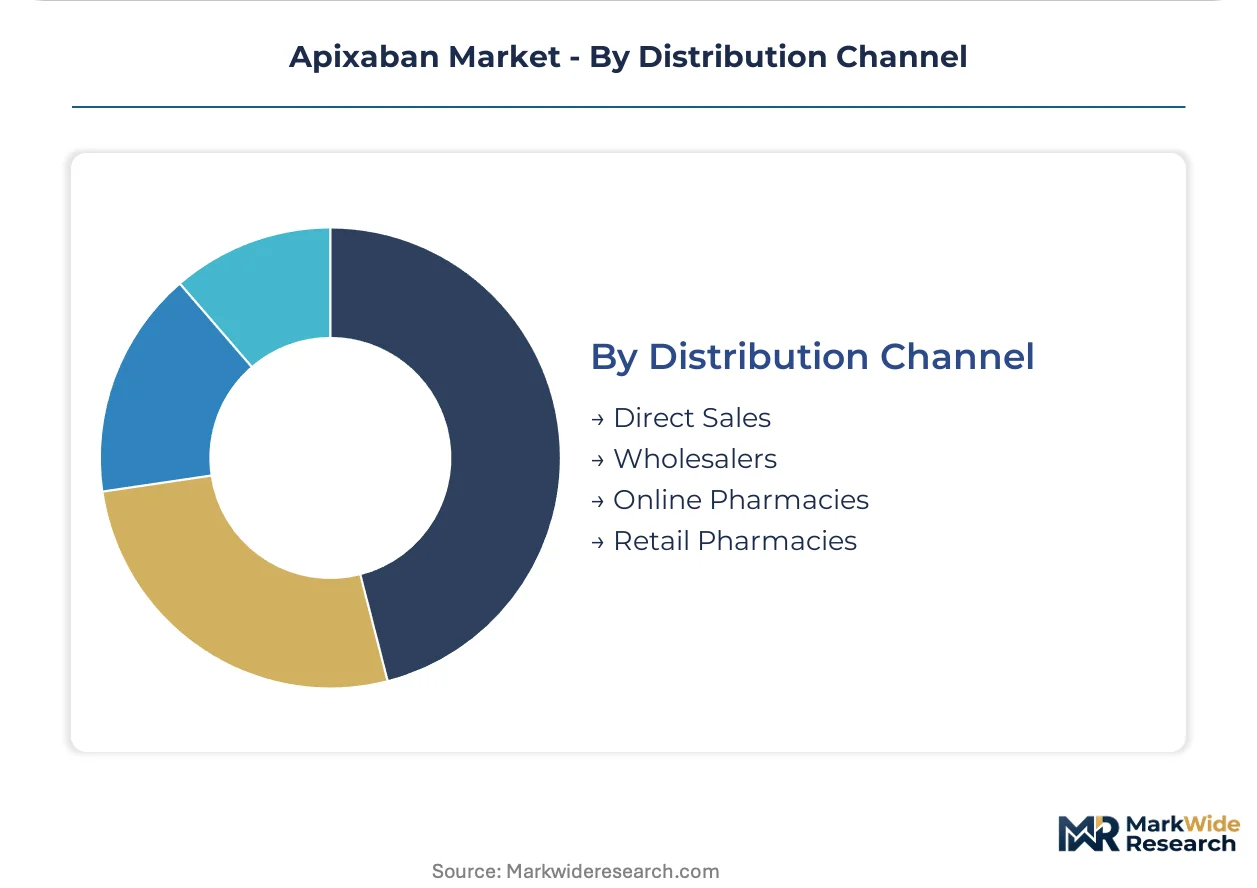
- Direct Sales:Manufacturer-to-health-system contracting dominates United States integrated delivery network procurement, capturing volume through exclusive therapeutic class agreements.
- Wholesalers:Three-tier distribution retains relevance for independent pharmacy and smaller hospital systems lacking direct negotiating scale.
- Online Pharmacies:Digital dispensers face REMS documentation burdens that elevate compliance costs relative to traditional channels.
- Retail Pharmacies:Community pharmacy chains process Medicare Part D beneficiary fills, though preferred network restrictions limit participation.
Consolidated health systems favor direct contracting; fragmented buyers depend on wholesale intermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiology specialist density in the United States anchors global prescription volume, while generic manufacturing talent clusters in India and contract research organizations concentrate in Switzerland and Singapore.
United States
Medicare Part D reimbursement mechanics and integrated delivery network formulary consolidation drive outpatient oral anticoagulant dispensing. The FDA's ANDA pathway and REMS requirements shape competitive entry timelines and prescriber education obligations. The Philadelphia-Camden corridor hosts Bristol-Myers Squibb's manufacturing and litigation operations, while Pfizer maintains headquarters influence in New York.
Germany
Orthopedic surgery volume through enhanced recovery after surgery protocols generates perioperative thromboprophylaxis demand. The EMA's pharmacovigilance framework and Germany's Federal Institute for Drugs and Medical Devices enforce post-market bleeding event reporting standards. The Rhine-Main region around Frankfurt anchors hospital pharmacy committee procurement for Central European distribution.
India
Cost-competitive active pharmaceutical ingredient synthesis and generic formulation manufacturing supply export markets. The CDSCO's bioequivalence study requirements and WHO prequalification programs determine institutional buyer access for lower-income health systems. Hyderabad and Ahmedabad clusters host Sun Pharmaceutical Industries Ltd. and Dr. Reddy's Laboratories Ltd. operations serving emerging market procurement.
Switzerland
Contract development and manufacturing organizations leverage continuous flow chemistry platforms for pyrazole derivative synthesis. Swissmedic's quality certification standards and proximity to EMA headquarters accelerate regulatory approval timelines for European market entry. Basel and Zurich regions concentrate pharmaceutical manufacturing engineering talent for factor Xa inhibitor production.
Japan
Aging demographics and atrial fibrillation prevalence expand chronic anticoagulation therapy pools. The PMDA's stringent bioequivalence standards and pharmacovigilance infrastructure elevate compliance costs for generic entrants. The Kanto region around Tokyo anchors hospital formulary decision-making and cardiology specialist practice patterns.
Apixaban Market Vendor Landscape
The competitive structure tilts toward originator-defended patent estates and first-to-file generic challengers. Branded manufacturers deploy layered formulation patents and crystalline polymorph protections to extend exclusivity, while generic entrants concentrate ANDA litigation resources on core composition-of-matter expiration timing. Two strategic archetypes dominate: vertically integrated pharmaceutical conglomerates with manufacturing scale and specialized generic houses with cost-positioned emerging market focus. Competitive moves center on patent litigation outcomes and exclusive health system contracting.
Within the originator tier, Bristol-Myers Squibb Company and Pfizer Inc. exemplify co-development heritage and hospital formulary anchoring. Among generic-specialist manufacturers, Sun Pharmaceutical Industries Ltd. and Dr. Reddy's Laboratories Ltd. occupy positions shaped by Indian API synthesis cost advantages and WHO prequalification procurement access. Teva Pharmaceutical Industries Ltd. represents the diversified generic conglomerate archetype spanning multiple therapeutic classes.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Bristol-Myers Squibb Company |
| Dr. Reddy's Laboratories Ltd. |
| Aurobindo Pharma Limited |
| Pfizer Inc. |
| Sandoz Group AG |
| Daiichi Sankyo Company Limited |
| Viatris Inc. |
| Others |
Supply Flow & Price Mechanics
Co-development heritage between vertically integrated pharmaceutical conglomerates and specialized generic houses shapes supply behavior and pricing discipline across the apixaban value chain, with patent litigation timelines and manufacturing scale determining margin capture rather than clinical differentiation alone.
Pricing Analysis
Unbundled bioequivalence study services and bundled ANDA litigation support packages split procurement patterns between originator-defended branded segments and first-to-file generic challengers. The dominant pricing structure runs contract-based long-term offtake agreements for hospital formulary placement, with price differentiation driven by FDA bioequivalence certification tier and manufacturing scale. Pricing pressure stems from generic entry through abbreviated new drug application pathways, compressing branded premium capture. Hospital pharmacy committees exhibit highest price sensitivity through centralized therapeutic class reviews, while specialty mail-order distributors accept moderate premiums for direct patient engagement capabilities.
Supply Chain Analysis
Regional distribution centers in Ireland and Singapore deploy continuous flow chemistry platforms for pyrazole derivative synthesis, feeding hub-and-spoke patterns into European and Asian hospital networks. Active pharmaceutical ingredient manufacturing concentrates in India, Switzerland, and the United States, with pyrazole cyclization and naphthalene core structures drawing from specialized chemical suppliers. Single-source vulnerability pervades crystalline polymorph production, where layered formulation patents extend exclusivity periods. Distribution runs through manufacturer-to-health-system direct contracting for integrated delivery networks, with wholesale intermediation serving fragmented independent pharmacy buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the apixaban market rests on continuous manufacturing technology adoption reducing solvent waste and yield inconsistency, alongside premium-tier positioning for perioperative injectable formulations in orthopedic surgery pathways.
For Market Incumbents: Deepen backward integration into pyrazole derivative synthesis to secure API supply against single-source disruption threats from specialized chemical suppliers. Layer crystalline polymorph patent protections atop formulation patents to extend effective exclusivity periods beyond core composition-of-matter expiration. Prioritize exclusive contracting with integrated delivery networks to anchor hospital formulary placement against generic substitution protocols. For New Entrants and Emerging Players: Specialty mail-order distributors offer the most penetrable channel partner type for bypassing consolidated health system procurement and capturing direct patient engagement margins. Target WHO prequalification procurement programs in lower-income health systems where cost-competitive tablet formulations face limited originator competition. Pursue emerging market access through demonstrated bioequivalence and institutional buyer relationships rather than direct-to-physician promotion. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier generic manufacturers with underdeveloped pharmacovigilance infrastructure but established CDSCO bioequivalence capabilities and Indian API synthesis cost positions. Long-term viability over the analysis window favors contract development and manufacturing organizations with continuous flow chemistry platforms and Swissmedic quality certifications. Watch ANDA litigation outcome timing as the critical inflection indicator for generic entry economics and branded pricing power compression.| Strategic Initiative | Industry Significance |
|---|---|
| Patent Estate Layering | Extends market exclusivity through crystalline polymorph and formulation patents beyond core composition expiration. |
| Continuous Manufacturing Scale-Up | Reduces solvent waste and improves yield consistency for pyrazole derivative synthesis in Ireland and Singapore facilities. |
| Integrated Delivery Network Contracting | Captures volume through exclusive therapeutic class agreements with consolidated United States health systems. |
| WHO Prequalification Pursuit | Opens institutional procurement access in lower-income health systems for cost-competitive tablet manufacturers. |
| Pharmacovigilance Infrastructure Investment | Addresses EMA and FDA post-market bleeding event reporting obligations that strain mid-tier manufacturer resources. |
Methodological Framework
Direct dialogue with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists grounded qualitative insights in operational reality. Secondary validation drew from FDA ANDA filings, EMA pharmacovigilance submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up prescription volume modeling and top-down therapeutic class revenue triangulation converged on segment-level estimates across the analysis window.
Output projections span product type, therapy area, end user, and distribution channel dimensions over the projection horizon. CAGRs derive from regression-based trend extrapolation calibrated to Medicare reimbursement policy shifts and cardiology guideline evolution. Modeled inputs include orthopedic surgery volume trajectories, generic entry timing scenarios, and integrated delivery network formulary consolidation patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to patent litigation resolutions, regulatory enforcement actions on API suppliers, and reversal agent development timelines. Outputs reflect documented assumptions around guideline adoption rates and reimbursement mechanics. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Antihyperlipidemic Drugs Market
Pharmacology
Hydroxychloroquine Drugs Market
Pharmacology
Anti-Hypertensive Drugs Market
Pharmacology
Global Asthma Therapeutics Market
Pharmacology
Influenza Medication Market
Pharmacology
ACE Inhibitors Market
Pharmacology
Medication Adherence Market
Pharmacology
Global Olanzapine Market
Pharmacology
Global Artemisinin Combination Therapy Market
Pharmacology
Prescription Narcotic Cough Preparations and Expectorants Market
Pharmacology
Antitussive Drugs Market
Pharmacology
Huoxiang Zhengqi Drug Market
Pharmacology
Semaglutide API Market
Pharmacology
Antimycotics Market
Pharmacology
Global Migraine Therapeutics Market
Pharmacology
Hyperkalemia Drugs Market