
 Autacoids and Related Drugs Market | 2026-2036
Autacoids and Related Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Autacoids and Related Drugs Market Outlook
The EU Green Deal's pharmaceutical sustainability criteria is hardening procurement standards across European hospital networks. Sanofi leverages its integrated biologics manufacturing to secure long-term supply contracts for prostaglandin-derived therapies. Pfizer anchors its position through captive fermentation capacity for complex autacoid synthesis. Eli Lilly and Company differentiates via sustained-release formulation technology for serotonin modulators in pain management.
Autacoids and related drugs comprise endogenous signaling molecules—histamines, prostaglandins, serotonin, and bradykinin—and their synthetic analogs, manufactured through recombinant DNA fermentation or multi-step organic synthesis with purity thresholds exceeding 99.5% for injectable grades. These compounds modulate vascular tone, inflammation, and neurotransmission across allergy, pain, and cardiovascular indications. Prostaglandins command the largest revenue pool due to their entrenched role in labor induction and glaucoma therapy, while intranasal delivery modes are gaining fastest as patient preference shifts toward non-invasive administration in allergy treatment. Injectable formats retain margin concentration in hospital settings where bioavailability requirements are most stringent.
FDA accelerated approval pathways and EMA adaptive licensing frameworks are compressing development timelines for autacoid-based biologics, while the EPA monitors active pharmaceutical ingredient discharge from fermentation facilities. The EU MDR imposes strengthened clinical evidence requirements on Class III autacoid delivery devices, reshaping regulatory investment thresholds. Stakeholders must monitor evolving pharmacovigilance obligations as real-world evidence mandates expand across FDA and EMA jurisdictions.
Market Dynamics
FDA accelerated approval pathways and EMA adaptive licensing frameworks are compressing development timelines for autacoid-based biologics, while fermentation capacity constraints concentrate supply among integrated manufacturers. This regulatory velocity is reshaping competitive positioning across prostaglandin and serotonin modulator segments.
Growth Catalysts
- Accelerated FDA Pathways:The FDA's breakthrough therapy designation for inflammatory disease treatments reduces Phase III duration for biologic autacoids. Hospital systems expand formularies in response.
- EU Green Deal Procurement Mandates:Pharmaceutical sustainability criteria harden procurement standards across European hospital networks, favoring manufacturers with verified fermentation discharge controls.
- Intransasal Delivery Technology:Non-invasive administration modes gain traction in allergy treatment as patient preference shifts away from injectable formats in ambulatory settings.
Market Restraints
- Fermentation Input Volatility:Recombinant DNA production depends on pharmaceutical-grade yeast extract and defined media components subject to agricultural supply fluctuations.
- Purity Threshold Escalation:Injectable-grade autacoids require 99.5% purity minimums, constraining batch yields and amplifying quality control expenditure across multi-step organic synthesis.
- EPA Discharge Scrutiny:Active pharmaceutical ingredient runoff from biologics facilities faces intensified environmental monitoring, elevating compliance overhead for fermentation-based production.
Strategic Opportunities
- Specialty Pharmacy Network Expansion:United States distribution channels for prostaglandin analogs concentrate in accredited specialty pharmacies, creating consolidation opportunities for logistics-integrated manufacturers.
- Sustained-Release Formulation Gaps:Pain management applications for serotonin modulators remain underdeveloped versus immediate-release alternatives, presenting formulation technology differentiation potential.
- EU MDR Device Convergence:Class III autacoid delivery devices face strengthened clinical evidence requirements, favoring sponsors with integrated drug-device development capabilities.
Industry Challenges
- Pharmacovigilance Workforce Scarcity:Real-world evidence mandates from FDA and EMA expand post-market surveillance obligations, straining qualified safety data analyst availability.
- Legacy System Integration Friction:Hospital electronic health record systems require costly adaptation to capture autacoid therapy response data for regulatory submission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autacoids and Related Drugs Market |
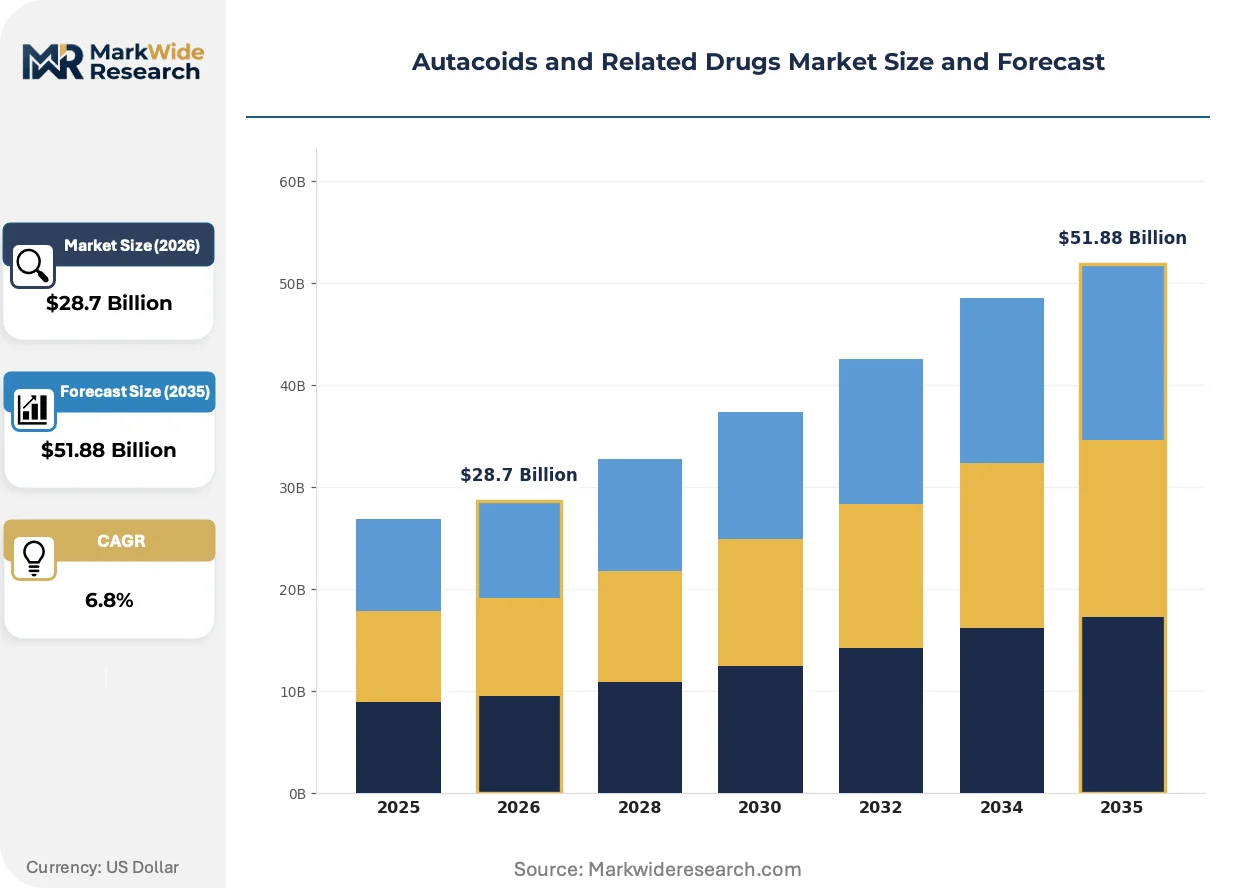
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Histamines, Prostaglandins, Serotonin, Bradykinin Therapy Area: Allergy, Pain Management, Gastrointestinal Disorders, Cardiovascular Diseases Delivery Mode: Injectable, Oral Tablets, Topical, Intranasal End User: Hospitals, Clinics, Home Healthcare, Pharmacies |
| Companies Covered | Sanofi, Merck & Co., Pfizer, Eli Lilly and Company, GlaxoSmithKline, Novartis, AstraZeneca, Teva Pharmaceutical Industries, Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autacoids and Related Drugs Market Strategic Shifts
Continuous manufacturing platforms and single-use bioreactor systems are displacing batch fermentation in autacoid production, while regulatory data science capabilities compress submission preparation cycles. These shifts favor capital-rich incumbents with integrated quality infrastructure.
Continuous processing technology for prostaglandin synthesis is absorbing quality variability that plagues traditional batch fermentation. Contract development and manufacturing organizations in the United States and Germany adopt these platforms at accelerating pace to secure long-term hospital supply contracts. The technology is absorbing margin pressure from purity threshold escalation by reducing in-process testing overhead.
The EU MDR's strengthened clinical evidence requirements for Class III delivery devices is forcing device sponsors to integrate drug development teams earlier in program timelines. This regulatory friction elevates investment thresholds for market entry while compressing development windows for compliant submissions. Glaucoma therapy segments with established prostaglandin delivery devices face the steepest adaptation costs.
Patient-administered intranasal formats for allergy indications are displacing clinic-based injectable administration in United States ambulatory settings. Specialty pharmacy networks capture this volume shift through direct-to-patient distribution models that bypass traditional hospital outpatient channels. Allergy immunotherapy practices in California and Texas exhibit the most pronounced format migration.
Autacoids and Related Drugs Market Segmentation
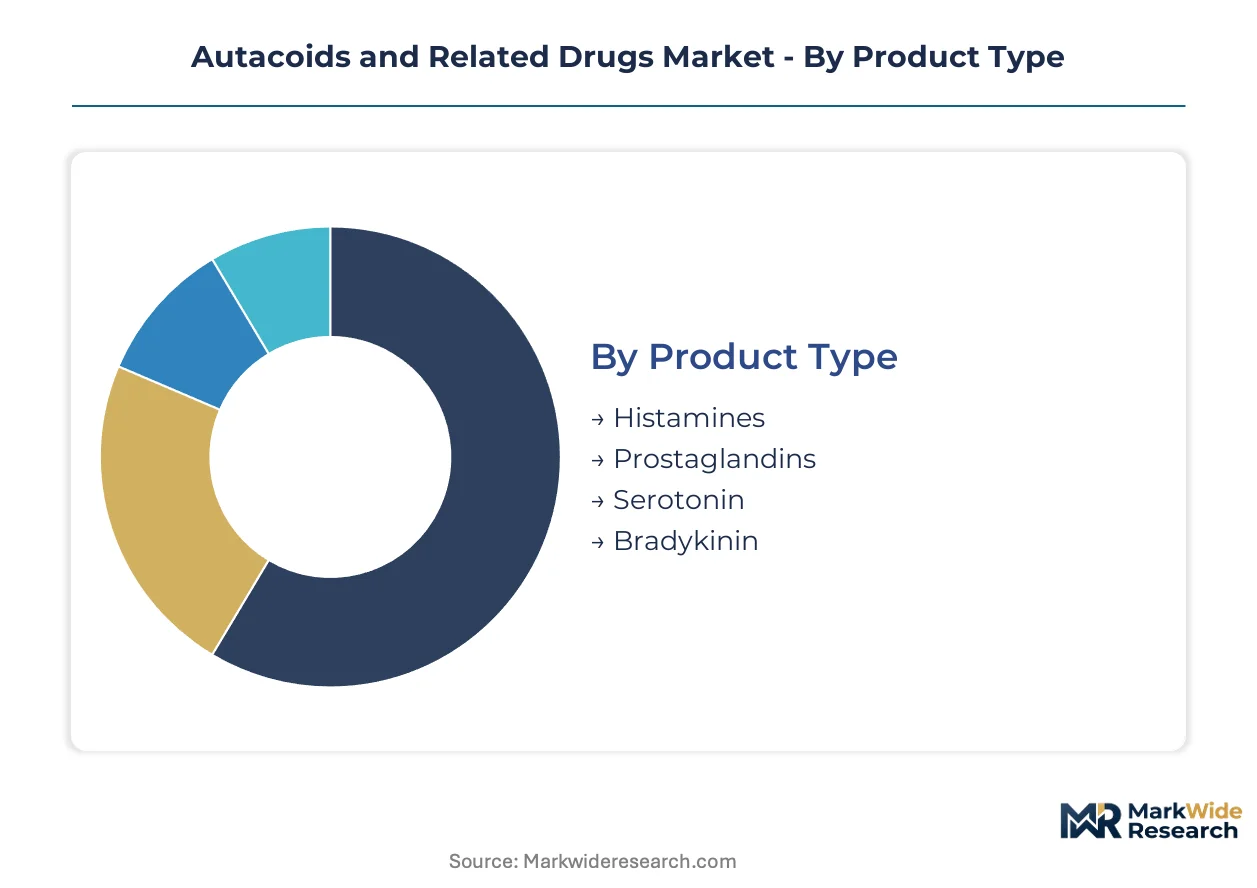
Autacoid therapeutics fragment across four distinct classification axes that reshape procurement patterns and manufacturing investment. Product chemistry determines fermentation complexity and regulatory pathway, while delivery mode governs margin structure and distribution channel selection. Therapy area concentration drives hospital formulary prioritization across acute versus chronic care settings.
Product Type:
Buyers differentiate autacoid classes by synthesis complexity, stability profile, and therapeutic index breadth.
- Prostaglandins:Complex 20-carbon fatty acid derivatives requiring multi-step organic synthesis or recombinant fermentation with stringent stereochemical control. Labor induction and glaucoma applications in the United States sustain the largest revenue pool, though EPA discharge scrutiny elevates compliance overhead for fermentation-based manufacturers.
- Serotonin:Indoleamine signaling molecules and receptor modulators manufactured through chemical synthesis with high purity thresholds for CNS penetration. Pain management formulations in United States specialty pharmacy networks concentrate demand, with sustained-release technology gaps presenting formulation differentiation opportunities.
- Histamines:Biogenic amine antagonists and analogs for allergy and gastric acid modulation.
- Bradykinin:Inflammatory peptide mediators and receptor-targeted therapies for cardiovascular and pain indications.
Prostaglandins lead volumes today; serotonin is gaining share fastest.
Therapy Area:
Application concentration determines reimbursement coding, clinical evidence requirements, and prescriber specialty targeting.
- Allergy:Histamine-targeted therapeutics and mast cell stabilizers for seasonal and perennial allergic conditions. United States ambulatory settings exhibit pronounced format migration toward patient-administered intranasal delivery, bypassing traditional hospital outpatient channels through specialty pharmacy direct-to-patient models.
- Pain Management:Serotonin modulators and prostaglandin inhibitors for acute and chronic nociceptive conditions. Injectable formats retain margin concentration in United States hospital settings where bioavailability requirements are most stringent, while oral alternatives face generic erosion.
- Gastrointestinal Disorders:Histamine receptor antagonists and prostaglandin analogs for acid-related disease and mucosal protection.
- Cardiovascular Diseases:Bradykinin pathway modulators and prostaglandin derivatives for vascular tone regulation.
Pain management commands the steepest pricing; allergy applications are expanding most quickly.
Delivery Mode:
Administration route dictates manufacturing scale economics, cold chain requirements, and patient compliance architecture.
- Injectable:Parenteral formulations requiring 99.5% purity minimums and sterile manufacturing infrastructure. United States hospital systems anchor demand for prostaglandin analogs in labor and delivery units, with batch yield constraints amplifying quality control expenditure.
- Intranasal:Non-invasive mucosal delivery systems for rapid systemic absorption of small-molecule autacoids. United States allergy immunotherapy practices in California and Texas drive fastest adoption as patient preference shifts away from clinic-based administration.
- Oral Tablets:Enteric-coated and immediate-release solid dosages for chronic maintenance therapy.
- Topical:Dermal and ophthalmic formulations for localized effect with minimized systemic exposure.
Injectable formats dominate revenue concentration; intranasal delivery is climbing the fastest.
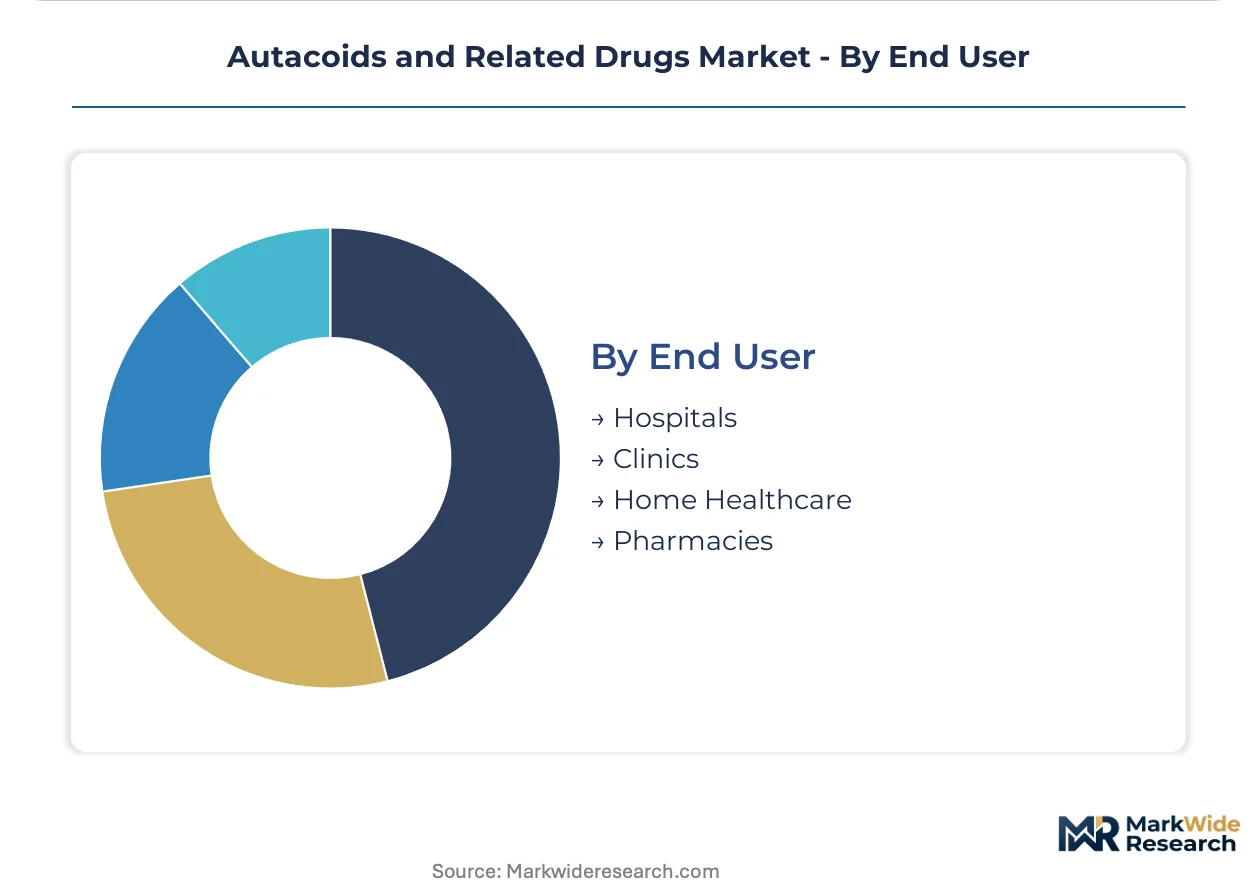
End User:
Purchasing authority and reimbursement mechanics fragment across institutional and retail channels.
- Hospitals:Integrated delivery networks with centralized pharmacy and therapeutics committees controlling formulary access. United States health systems expand biologic autacoid formularies in response to FDA accelerated approval pathways, concentrating procurement among manufacturers with verified fermentation discharge controls.
- Specialty Pharmacies:Accredited distribution channels for high-cost biologics and limited distribution drugs. United States networks capture volume shift from hospital outpatient settings through direct-to-patient models for prostaglandin analogs and serotonin receptor modulators.
- Clinics:Ambulatory care sites for administered therapies and procedure-linked drug delivery.
- Home Healthcare:Patient-directed administration settings for chronic maintenance regimens.
Hospitals anchor procurement volume today; specialty pharmacies are capturing share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The autacoids industry traces its modern commercial roots to Swiss and German pharmaceutical houses that pioneered prostaglandin synthesis in the 1960s, with fermentation-based production later scaling in United States biotech corridors.
United States
Hospital systems in Texas and California are expanding biologic autacoid formularies for labor induction and allergy management. The FDA's breakthrough therapy designation compresses Phase III timelines for inflammatory disease treatments. Specialty pharmacy networks in the Southeast and Midwest capture distribution volume through direct-to-patient models for prostaglandin analogs.
Germany
Integrated manufacturers in North Rhine-Westphalia leverage continuous processing platforms to secure long-term hospital supply contracts. The EU Green Deal's pharmaceutical sustainability criteria harden procurement standards across Bavarian and Baden-Württemberg hospital networks. Contract development organizations in the Frankfurt-Rhine-Main cluster adopt single-use bioreactor systems at accelerating pace.
Switzerland
Basel-area pharmaceutical conglomerates anchor European prostaglandin production through captive fermentation capacity. Swissmedic's adaptive licensing frameworks align with EMA pathways to accelerate market entry for serotonin receptor modulators. The Lake Geneva region concentrates formulation technology development for sustained-release autacoid delivery.
Japan
PMDA's streamlined review pathways for orphan autacoid indications attract development investment from Tokyo and Osaka-based sponsors. The Kanto region's hospital networks prioritize intranasal delivery formats for allergy immunotherapy as patient preference shifts away from injectable administration. Chubu-area manufacturers specialize in high-purity bradykinin pathway modulators for cardiovascular applications.
India
Hyderabad and Mumbai pharmaceutical corridors scale contract fermentation capacity for prostaglandin intermediates serving export markets. CDSCO's strengthened good manufacturing practice inspections elevate quality thresholds for injectable-grade autacoid exports. The Delhi-NCR cluster concentrates regulatory affairs capabilities supporting ANDA filings for histamine antagonist generics.
Autacoids and Related Drugs Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the autacoids value chain. Integrated pharmaceutical conglomerates with captive fermentation infrastructure command supply security premiums from hospital procurement committees. The competitive terrain separates into three archetypes: diversified biologics majors, fermentation-specialized contractors, and formulation technology boutiques. Capacity expansion and strategic partnerships constitute the dominant competitive moves as manufacturers respond to FDA accelerated approval velocity.
Among diversified biologics majors, Sanofi and Pfizer exemplify the integrated manufacturing archetype through their control over fermentation supply chains. Eli Lilly and Company occupies a position within the formulation differentiation tier, particularly for sustained-release serotonin modulator development. These three anchors represent distinct strategic postures: supply security through vertical manufacturing control versus technology-led product differentiation.
| Leading Market Players |
|---|
| Sanofi |
| Merck & Co. |
| Pfizer |
| Eli Lilly and Company |
| GlaxoSmithKline |
| Novartis |
| AstraZeneca |
| Teva Pharmaceutical Industries |
| Bristol-Myers Squibb |
| Others |
Value Chain & Pricing Dynamics
Hospital formulary expansion for biologic autacoids across United States and German networks is compressing procurement cycles and forcing manufacturers to absorb purity threshold escalation costs while defending margin position through captive fermentation infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates injectable-grade prostaglandins with 99.5% purity minimums from standard oral formulations and economy-tier generics. Price differentiation rests on FDA certification tier and fermentation discharge compliance status under EPA scrutiny. Cost compression in the economy tier is intensifying because Indian contract manufacturers scale histamine antagonist production. Hospital systems exhibit lowest price sensitivity due to bioavailability requirements, while ambulatory allergy clinics show highest sensitivity driving intranasal format migration.
Supply Chain Analysis
FDA and EMA certification gating for sterile injectable manufacturing concentrates supply among United States, German, and Swiss facilities with verified quality infrastructure. Production draws from pharmaceutical-grade yeast extract, defined fermentation media, and single-use bioreactor systems. Single-source vulnerability persists for stereochemically controlled prostaglandin intermediates. Distribution runs through accredited specialty pharmacy networks that bypass traditional hospital outpatient channels for direct-to-patient delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autacoids market functions as a stable compounder anchored by chronic disease maintenance requirements and the irreversibility of biologic formulary adoption in major hospital systems.
For Market Incumbents: Deploy continuous processing platform upgrades to absorb batch yield variability and defend against contract manufacturing organization price aggression. Lock in long-term supply agreements with Bavarian and Baden-Württemberg hospital networks before EU Green Deal procurement mandates fully harden. Expand captive fermentation capacity in North Rhine-Westphalia to secure prostaglandin derivative supply security premiums. For New Entrants and Emerging Players: Begin with sustained-release serotonin modulator formulation gaps in United States pain management, where immediate-release alternatives face generic erosion and patient compliance architecture remains underdeveloped. Target California and Texas allergy immunotherapy practices for intranasal delivery adoption. Pursue FDA breakthrough therapy designation to compress Phase III timelines versus standard inflammatory disease pathways. For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation-specialized contractors possessing verified EPA discharge controls and EMA adaptive licensing track records. The five-to-ten year viability window favors sponsors with integrated drug-device development capabilities for EU MDR Class III compliance. Watch for FDA real-world evidence mandate expansion as the inflection signal for pharmacovigilance infrastructure valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Scale-Up | Absorbs quality variability in prostaglandin synthesis while reducing in-process testing overhead for hospital supply contracts. |
| EU MDR Device Convergence Investment | Integrates drug development teams with delivery device engineering to meet strengthened clinical evidence requirements for Class III submissions. |
| Specialty Pharmacy Network Integration | Captures volume shift from hospital outpatient settings through direct-to-patient distribution models for prostaglandin analogs. |
| Sustained-Release Formulation R&D | Addresses technology gaps in serotonin modulator pain management applications versus immediate-release alternatives. |
| Fermentation Discharge Compliance Certification | Secures procurement preference under EU Green Deal pharmaceutical sustainability criteria across European hospital networks. |
Study Parameters
Multiple input streams — regulatory filing analysis, hospital procurement database review, and manufacturing capacity surveys — were reconciled through structured primary interviews with drug development executives, formulary directors, regulatory affairs leads, and specialty pharmacy network managers. Secondary validation incorporated FDA accelerated approval pathway documentation, EMA adaptive licensing framework updates, ClinicalTrials.gov entry analysis, and EPA discharge monitoring reports. Bottom-up segment sizing and top-down market reconciliation were cross-checked for consistency.
Historical volume trajectories were cross-referenced against expert panel inputs to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product chemistry class, delivery mode, therapy area concentration, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized adoption curves. Forecast inputs incorporated fermentation capacity utilization rates and specialty pharmacy network expansion trajectories specific to prostaglandin and serotonin modulator distribution.
Several conditions sit outside the modeled scope, including unforeseen FDA approval pathway reversals, raw material agricultural supply disruptions, and radical delivery technology displacement. Forecasts reflect assumptions about regulatory velocity and hospital formulary stickiness. A model refresh is warranted upon material change in EPA enforcement posture for active pharmaceutical ingredient discharge or EMA pharmacovigilance mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Cough Remedies Market
Pharmacology
Apixaban Market
Pharmacology
Immunotherapy Drugs Market
Pharmacology
Global Olanzapine Market
Pharmacology
Huoxiang Zhengqi Drug Market
Pharmacology
Attention Deficit Hyperactivity Disorder (ADHD) Therapeutics Market
Pharmacology
Global Artemisinin Combination Therapy Market
Pharmacology
UK Pharmacovigilance Market
Pharmacology
Hypertension Drug Market
Pharmacology
Hepatitis C Drug Market
Pharmacology
Hydroxychloroquine Drugs Market
Pharmacology
Semaglutide API Market
Pharmacology
Aldosterone Receptor Antagonists Market
Pharmacology
Thromboprophylactic Drugs Market
Pharmacology
Medication Adherence Market
Pharmacology
Anti-Hypertensive Drugs Market