
 Alexipharmic Drugs Market | 2026-2036
Alexipharmic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Alexipharmic Drugs Market Analysis
Emergency medicine is broadening its share of alexipharmic procurement as hospitals expand toxicology response capabilities. Pfizer Inc anchors North American distribution networks through its established hospital supply contracts. Fresenius SE & Co. KGaA leverages its infusion therapy infrastructure to dominate intravenous antidote delivery. Teva Pharmaceutical Industries Ltd competes aggressively in the generic naloxone segment, sustaining price pressure across emergency departments.
Alexipharmic drugs are pharmaceutical agents formulated to counteract poisons, toxins, or drug overdoses through mechanisms including adsorption, chemical neutralization, receptor antagonism, or chelation, with specifications varying by molecular target and route of administration; their primary purpose is to restore physiological homeostasis following acute toxic exposure in clinical and pre-hospital settings. Tablets and capsules occupy the largest volume share due to outpatient dispensing convenience and activated charcoal's established oral administration protocol. Intravenous delivery commands premium positioning because hospital-based anaphylaxis and opioid reversal require rapid systemic bioavailability that oral routes cannot achieve. Oncology therapy applications represent the fastest-growing segment as cancer treatment-related toxicity management drives demand for specialized antidotes and supportive care agents.
FDA approval pathways for antidote formulations mandate rigorous efficacy demonstrations against specific toxin classes, while EMA's orphan drug incentives accelerate development for rare poisoning indications. The EU's MDR framework imposes stringent clinical evidence requirements on device-drug combination products such as auto-injector naloxone systems. Poison control centers in Germany, France, and Italy coordinate national stockpiling protocols that shape manufacturer tender specifications. Stakeholders must monitor evolving regulatory harmonization between FDA and EMA antidote designation programs to optimize development pipelines and market access strategies.
Market Dynamics
Emergency medicine departments are expanding toxicology response capabilities as opioid overdose caseloads and industrial poisoning incidents reshape hospital procurement priorities. This structural shift concentrates demand in institutional channels, compressing formulary decision cycles and favoring suppliers with integrated distribution networks.
Growth Catalysts
- Poison Control Integration:United States hospital networks are consolidating antidote procurement through poison control center partnerships, driving bulk purchasing of activated charcoal and chelation therapies.
- REACH and CLP Frameworks:European chemical safety regulations mandate industrial poisoning response readiness, accelerating formulary standardization across German, French, and Italian emergency departments.
- Auto-Injector Platforms:Device-drug combination products for pre-hospital naloxone administration are expanding access beyond clinical settings into community emergency response.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient production for chelation therapies concentrates in Asian manufacturing clusters, exposing formularies to single-source vulnerability.
- Oral Bioavailability Limitations:Activated charcoal efficacy degrades with delayed administration, restricting its utility in time-critical opioid reversal scenarios where intravenous routes dominate.
- Orphan Drug Economics:EMA incentives for rare poisoning indications create portfolio allocation tension, diverting R&D resources from high-volume emergency antidotes toward low-incidence toxin classes.
Strategic Opportunities
- Oncology Supportive Care:Cancer treatment-related toxicity management represents an emerging application segment, with specialized antidotes addressing chemotherapy-induced organ damage.
- Community Paramedicine Expansion:Pre-hospital administration protocols in rural United States jurisdictions are creating distribution channel innovation through mobile health unit deployment.
- EU MDR Harmonization:Convergence of device-drug combination product standards across European member states is streamlining cross-border tender participation for integrated delivery systems.
Industry Challenges
- Toxicology Specialist Shortage:Emergency medicine residency programs report insufficient clinical toxicology training, limiting protocol standardization across hospital networks.
- Cold Chain Infrastructure:Intravenous antidote stability requirements demand capital-intensive storage and transport systems, particularly for temperature-sensitive biologic neutralizing agents.
- Formulary Integration Complexity:Legacy hospital information systems require substantial reconfiguration to accommodate real-time antidote inventory tracking mandated by Joint Commission accreditation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alexipharmic Drugs Market |
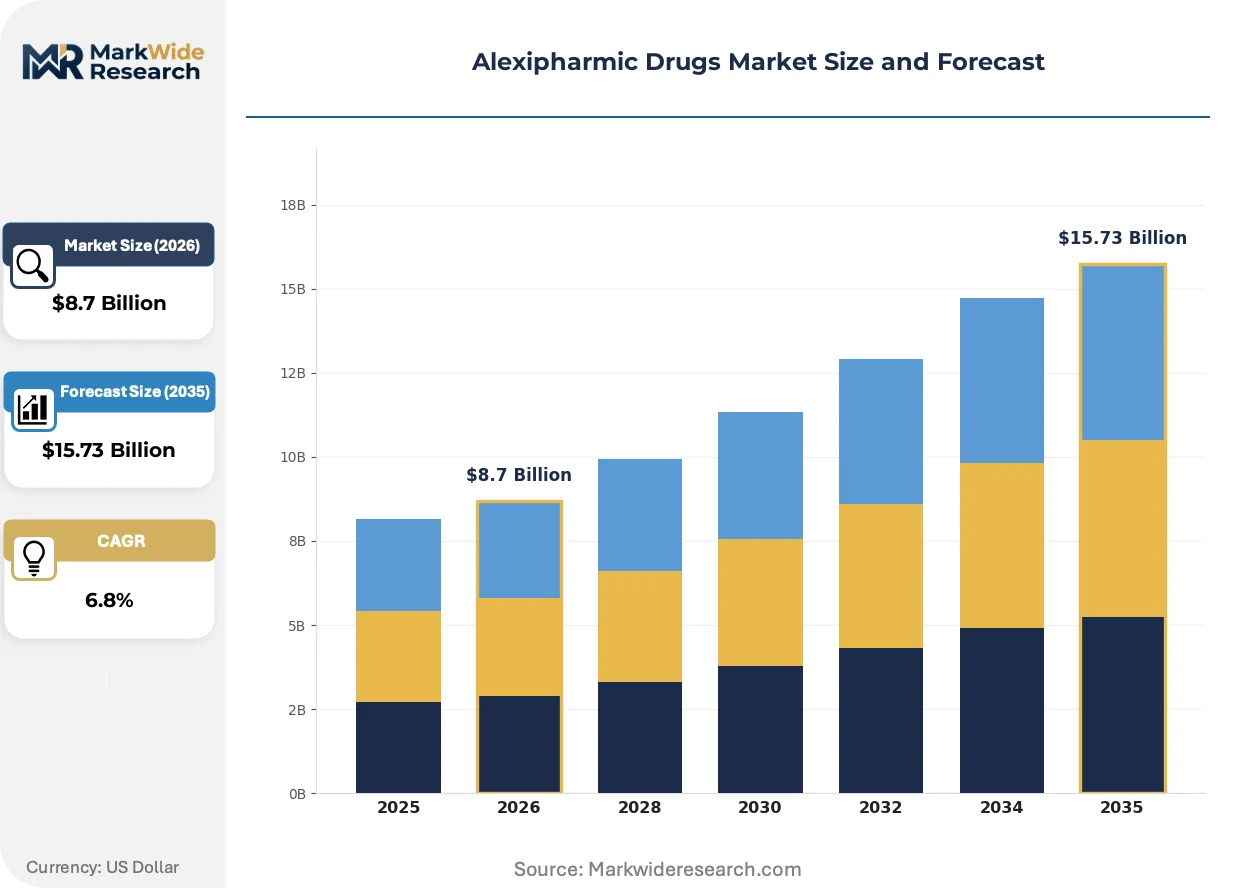
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injections, Syrups Delivery Mode: Oral, Intravenous, Subcutaneous, Transdermal Therapy Area: Immunology, Oncology, Neurology, Infectious Diseases End User: Hospitals, Pharmacies, Research Laboratories, Patients |
| Companies Covered | Pfizer Inc, Bausch Health Companies Inc, Fresenius SE & Co. KGaA, Mylan N.V., Ethypharm S.A., AstraZeneca, Bristol-Myers Squibb Company, Teva Pharmaceutical Industries Ltd, Emergent BioSolutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alexipharmic Drugs Market Emerging Trajectories
Formulation science and delivery mechanisms are converging to compress administration timelines and expand the therapeutic window for acute toxic exposures. These developments are restructuring competitive advantage around bioavailability engineering and point-of-care deployment capabilities.
Lyophilized antidote formulations are consolidating shelf-stable alternatives to liquid preparations, enabling stockpiling flexibility for emergency departments and poison control centers. Hospital networks in the United States are adopting these platforms to reduce waste from expired inventory. This consolidation is compressing supplier margins on traditional liquid presentations while rewarding manufacturers with freeze-drying expertise.
EMA's Medical Device Regulation framework is reclassifying auto-injector naloxone systems as higher-risk device-drug combinations, demanding expanded clinical evidence packages for market authorization. Manufacturers are responding by front-loading pharmacovigilance investments to preempt regulatory scrutiny. European emergency medical services represent the most affected segment, facing procurement delays as notified body capacity constrains certification timelines.
Hospital consortium purchasing is displacing individual institutional procurement for high-volume antidotes, concentrating negotiating leverage among integrated delivery networks. Group purchasing organizations are extracting price concessions in exchange for sole-source or dual-source commitments. This behavioral shift is most visible in the United States, where health system consolidation has created regional procurement monopolies that override traditional distributor relationships.
Alexipharmic Drugs Market Segmentation
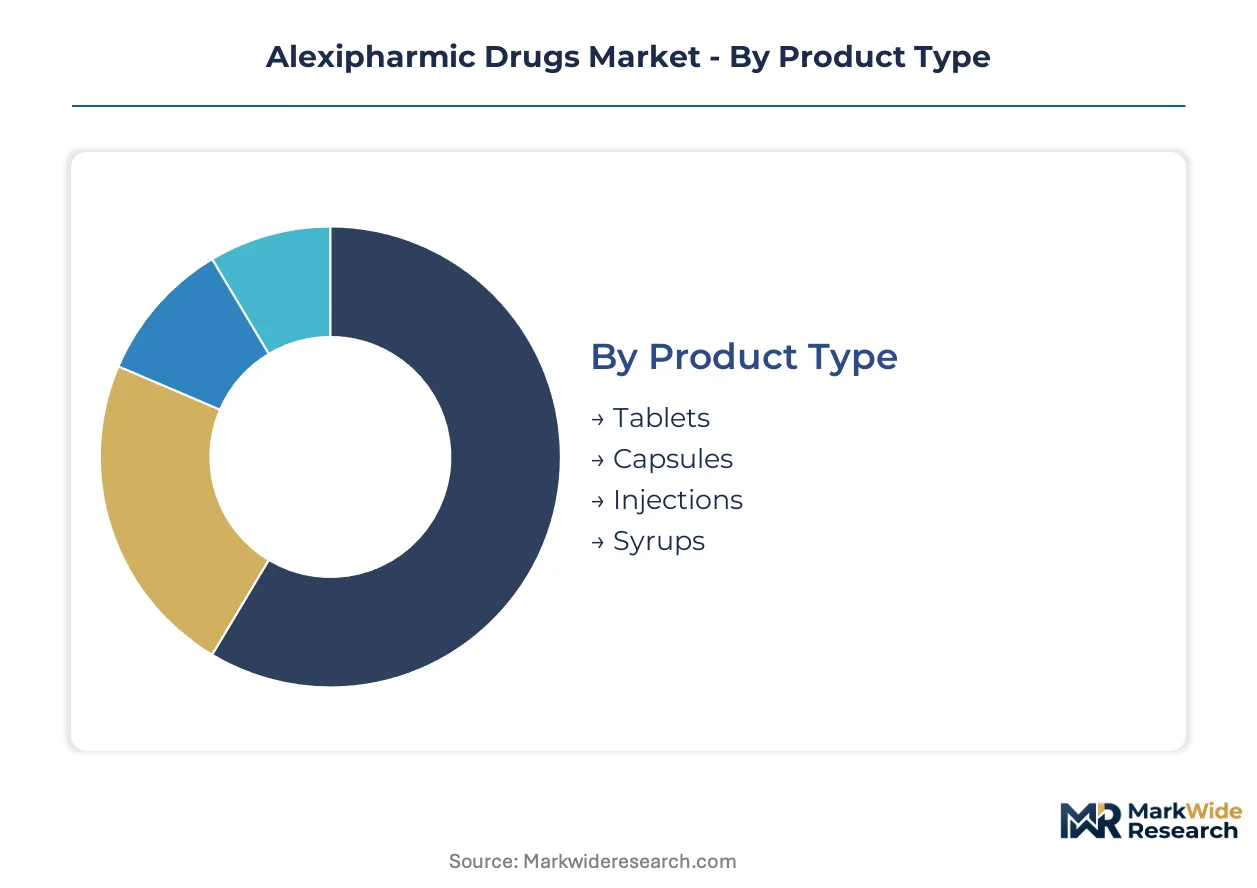
Alexipharmic procurement patterns diverge sharply across formulation types and care settings. Hospital formularies prioritize rapid systemic delivery for emergency toxicology, while outpatient channels favor portable oral presentations for pre-hospital intervention.
Product Type:
Hospital procurement committees weight stability profiles and administration speed against shelf-life economics when selecting formulations for formulary inclusion.
- Tablets:Compressed activated charcoal and oral chelation agents dominate outpatient dispensing through poison control center partnerships. United States emergency departments stock these for stable patients with non-critical ingestions where gastric decontamination remains viable.
- Injections:Lyophilized and liquid parenteral antidotes command premium positioning in institutional procurement due to rapid bioavailability requirements for opioid reversal and anaphylaxis management. Cold chain infrastructure investments concentrate around these formulations.
- Capsules:Encapsulated adsorbents and neutralizing agents serve pre-hospital and ambulatory settings where precise dosing and portability outweigh speed of onset.
- Syrups:Liquid oral presentations address pediatric poisoning protocols and patients with compromised swallowing function, particularly in community pharmacy dispensing.
Volume sits with tablets due to outpatient scale; growth tilts toward injections as hospital toxicology capabilities expand.
Delivery Mode:
Route selection hinges on time-to-treatment windows and toxin pharmacokinetics, with institutional protocols stratifying access by severity classification.
- Oral:Gastric adsorption and enteral chelation depend on administration within narrow post-ingestion windows. Poison control centers in Germany and France coordinate stockpiling protocols for these presentations.
- Intravenous:Direct vascular delivery achieves therapeutic concentrations for receptor antagonists and biologic neutralizing agents. FDA mandates for emergency department readiness accelerate procurement of IV naloxone and anti-venom preparations.
- Subcutaneous:Depot formulations and auto-injector platforms extend antidote access into community paramedicine and bystander response scenarios.
- Transdermal:Patch-based delivery systems for sustained chelation and toxin absorption remain developmental, with EMA Medical Device Regulation frameworks shaping evidence requirements.
Procurement concentrates in intravenous channels; subcutaneous auto-injector formats are climbing the fastest as pre-hospital protocols proliferate.
Therapy Area:
Toxicology service line expansion and oncology supportive care investments are reallocating R&D and commercial resources across therapeutic domains.
- Oncology:Chemotherapy-induced toxicity management drives demand for specialized antidotes addressing organ damage, with hospital networks integrating these into cancer center formularies.
- Neurology:Neurotoxicity reversal agents target opioid overdose, organophosphate poisoning, and iatrogenic sedation complications. United States emergency medicine departments prioritize these for stroke and trauma co-management.
- Immunology:Anaphylaxis and cytokine storm interventions require rapid-acting biologic neutralizers, with EMA orphan drug incentives accelerating development for rare hypersensitivity indications.
- Infectious Diseases:Antimicrobial toxicity antidotes address aminoglycoside nephrotoxicity and antifungal hepatotoxicity in immunocompromised patient populations.
Neurology applications anchor current volume; oncology supportive care represents the steepest expansion trajectory as cancer treatment protocols intensify.
End User:
Channel economics and regulatory accreditation standards differentiate procurement behavior across institutional and direct-to-patient access points.
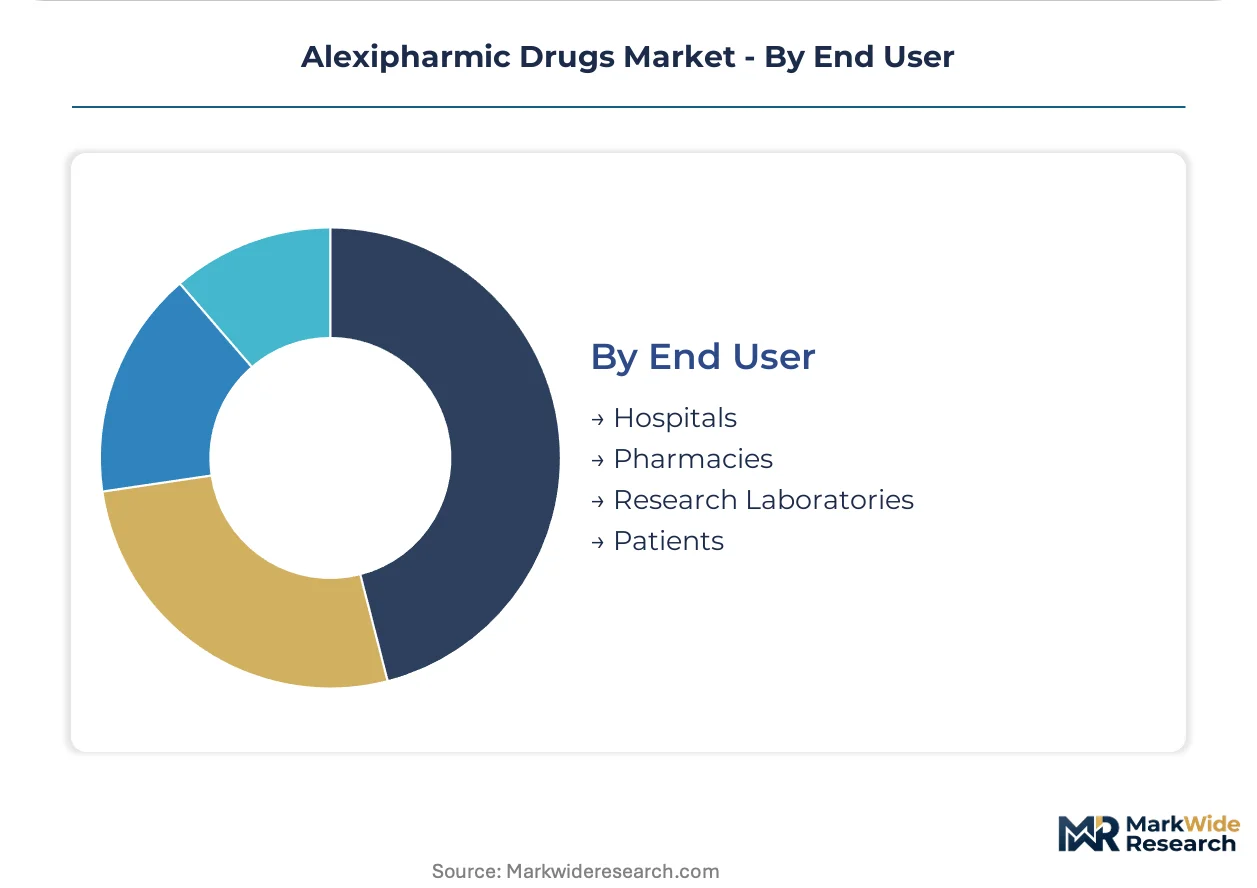
- Hospitals:Integrated delivery networks consolidate antidote purchasing through group purchasing organizations, extracting price concessions for high-volume activated charcoal, naloxone, and chelation therapies.
- Pharmacies:Community and outpatient pharmacy channels dispense oral formulations for pre-hospital intervention, with auto-injector naloxone expanding into retail distribution in select United States jurisdictions.
- Research Laboratories:Academic medical centers and contract research organizations procure specialized antidotes for toxicology studies and clinical trial rescue protocols.
- Patients:Direct dispensing to high-risk individuals—particularly those with known opioid use disorder—creates emerging demand for take-home reversal agents.
Hospital systems capture procurement volume; patient-directed dispensing is gaining share fastest as community overdose prevention programs scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in pharmaceutical manufacturing clusters across multiple continents concentrate alexipharmic production capacity. FDA and EMA regulatory harmonization efforts accelerate cross-border formulary standardization for emergency antidotes.
United States
Poison control center integration with hospital networks drives bulk procurement of activated charcoal and naloxone. FDA mandates for emergency department readiness accelerate stockpiling protocols. The Baltimore-Washington corridor anchors federal antidote reserve management and strategic national stockpile distribution.
Germany
Industrial chemical safety regulations under REACH and CLP frameworks mandate poisoning response readiness across manufacturing regions. EMA orphan drug incentives accelerate development for rare toxin antidotes. The Rhine-Ruhr industrial cluster concentrates chelation therapy demand from heavy metal exposure incidents.
France
Hospital consortium purchasing consolidates antidote procurement through regional health agencies. ANSM coordinates national toxicology response standards with poison control centers. The Lyon-Grenoble pharmaceutical belt specializes in lyophilized antidote formulation manufacturing.
Japan
PMDA fast-track designations for emergency-use antidotes compress regulatory review timelines. METI industrial safety directives require corporate poisoning response preparedness. The Kansai region around Osaka hosts specialized manufacturers of biologic neutralizing agents for venom and toxin exposure.
India
CDSCO streamlined approval pathways for essential emergency medicines expand domestic antidote manufacturing capacity. The country's pharmaceutical export zones supply API for chelation therapies to European and North American formularies. Hyderabad and Ahmedabad clusters specialize in generic naloxone and activated charcoal production.
Alexipharmic Drugs Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with hospital procurement committees favoring established supply relationships for high-risk emergency medicines. The vendor base concentrates around three tiers: integrated pharmaceutical conglomerates with hospital distribution networks, mid-scale generic manufacturers competing on price, and niche developers of orphan antidote indications. Strategic moves center on formulary integration partnerships and lyophilization capacity expansion to capture shelf-stable formulation demand.
Within the integrated pharmaceutical tier, Pfizer Inc and Fresenius SE & Co. KGaA exemplify divergent positioning archetypes. Pfizer anchors North American hospital supply contracts through its established institutional distribution infrastructure. Fresenius leverages its infusion therapy and parenteral manufacturing expertise to dominate intravenous antidote delivery channels. Teva Pharmaceutical Industries Ltd occupies the generic-specialist position, sustaining price competition in the naloxone segment through high-volume production economics.
| Leading Market Players |
|---|
| Pfizer Inc |
| Bausch Health Companies Inc |
| Fresenius SE & Co. KGaA |
| Mylan N.V. |
| Ethypharm S.A. |
| AstraZeneca |
| Bristol-Myers Squibb Company |
| Teva Pharmaceutical Industries Ltd |
| Emergent BioSolutions |
| Others |
Supply Flow & Price Mechanics
Lyophilized formulation premiums against liquid commodity presentations bifurcate procurement economics, with freeze-dried antidotes commanding hospital formulary preference for shelf stability while standard liquid naloxone faces spot-market discounting; this tier divergence concentrates manufacturing investment in Germany and France while pushing price-sensitive generic procurement toward Indian API suppliers.
Pricing Analysis
Short lead-time premiums for cold-chain IV antidotes sustain margin protection for Fresenius and Pfizer hospital contracts, while spot inventory of oral activated charcoal trades at commodity discounts. Three-tier pricing structure across premium freeze-dried, standard liquid parenteral, and economy generic oral tiers reflects EMA certification grades and FDA emergency-use designation status. Cost compression in the generic naloxone segment is intensifying because Teva's high-volume production economics force competitor margin sacrifice. Group purchasing organizations exhibit highest price sensitivity, whereas poison control center bulk contracts show lowest sensitivity due to regulatory stockpiling mandates.
Supply Chain Analysis
Temperature-controlled freight costs for biologic neutralizing agents absorb 15-20% of landed hospital prices, particularly for Kansai-region Japanese manufacturers serving European emergency medical services. API production for chelation therapies concentrates in India and China, with Hyderabad and Ahmedabad clusters supplying European and North American formularies. Supply chain vulnerability rests on single-source dependence for snake anti-venom plasma collection in Costa Rica and Australia. Distribution runs through hospital group purchasing organizations in the United States and regional health agency tenders in France and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EMA Medical Device Regulation certification creates a barrier-to-entry moat, forcing non-compliant auto-injector manufacturers into protracted notified body queues while accredited players capture formulary lock-in.
For Market Incumbents: Anchor hospital supply contracts through lyophilization capacity expansion in the Lyon-Grenoble pharmaceutical belt, defending against Fresenius's intravenous dominance by acquiring freeze-drying expertise in France. Consolidate position against Teva's generic naloxone price pressure through exclusive poison control center partnerships that bundle activated charcoal with premium antidote portfolios.
For New Entrants and Emerging Players: The mid-tier price-point gap between Pfizer's premium hospital contracts and Indian generic exports offers white-space entry for European mid-scale manufacturers with EMA orphan drug incentives. Target oncology supportive care antidotes for chemotherapy-induced toxicity as the most penetrable segment, leveraging fast-track PMDA designations in Japan for regulatory credibility. Pursue community paramedicine distribution through mobile health unit deployment in rural United States jurisdictions as the primary go-to-market angle.
For Investors and Strategic Acquirers: Exit pathways concentrate in Big Pharma bolt-on acquisitions of orphan antidote developers with EMA designation portfolios, particularly those addressing rare industrial toxin exposures. Long-term viability favors platform companies with device-drug combination capabilities spanning auto-injector and IV delivery modes. Watch FDA-EMA regulatory harmonization progress on antidote designation programs as the critical inflection signal for portfolio reallocation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilization Capacity Expansion | Freeze-drying expertise in France's Lyon-Grenoble belt captures hospital shelf-stability demand. |
| EMA Orphan Drug Designation | Rare poisoning indication incentives accelerate development timelines for specialized antidote portfolios. |
| Poison Control Center Partnership | United States bulk procurement consolidation rewards integrated distribution network investments. |
| Auto-Injector Regulatory Pathway | MDR compliance for device-drug combinations unlocks European emergency medical services procurement. |
| Oncology Supportive Care Pipeline | Chemotherapy toxicity antidotes address fastest-expanding hospital formulary segment. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital formulary directors, poison control center procurement managers, emergency medicine toxicologists, and pharmaceutical regulatory affairs leads. FDA 510(k) submissions, EMA marketing authorization applications, ClinicalTrials.gov rescue protocol listings, and United States poison control center annual reports furnished validation datasets. Bottom-up manufacturer shipment analysis and top-down hospital expenditure modeling enabled cross-verification.
Granularity-level modeling disaggregated volume and value outputs by formulation type, delivery mode, therapy area, and end-user channel across the analysis window. Segment-specific CAGRs derived from therapeutic protocol expansion rates, regulatory stockpiling mandate implementation timelines, and oncology treatment intensity projections. Forecast inputs incorporated REACH framework compliance costs for European industrial poisoning readiness and PMDA fast-track designation velocity for Japanese emergency-use approvals.
Underlying measurement precision varies by segment; intravenous antidote and auto-injector device-drug combinations carry tighter precision than oral generic formulations due to concentrated manufacturer disclosure. Forecasts reflect assumptions on regulatory harmonization progress and poison control center integration depth. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Influenza Medication Market
Pharmacology
Artemisinin Antimalarial Drugs Market
Pharmacology
Drug Repurposing Market
Pharmacology
Ibuprofen API Market
Pharmacology
Hyperkalemia Drugs Market
Pharmacology
Aldosterone Receptor Antagonists Market
Pharmacology
Angiotensin II Receptor Blockers (Arbs) Market
Pharmacology
Pegylated Drugs Market
Pharmacology
Global Asthma Therapeutics Market
Pharmacology
Anti-Hypertensive Drugs Market
Pharmacology
Thromboprophylactic Drugs Market
Pharmacology
ACE Inhibitors Market
Pharmacology
Antimycotics Market
Pharmacology
Aspirin API Market
Pharmacology
Antihyperlipidemic Drugs Market
Pharmacology
Prescription Narcotic Cough Preparations and Expectorants Market