
 Anti-Hypertensive Drugs Market | 2026-2036
Anti-Hypertensive Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Hypertensive Drugs Market Analytics
The anti-hypertensive drugs landscape is restructuring around a sharp divergence between premium patented fixed-dose combinations and commodity generic monotherapies. Novartis AG leverages its entrenched cardiovascular portfolio to sustain pricing power in renin-angiotensin system inhibitors across European and North American hospital networks. Pfizer Inc. competes through manufacturing scale in calcium channel blockers, anchoring volume contracts with large pharmacy benefit managers.
Anti-hypertensive drugs comprise pharmacological agents that modulate blood pressure through mechanisms including vasodilation, sodium excretion, or renin-angiotensin-aldosterone system inhibition, with formulations ranging from immediate-release tablets to extended-release matrix systems designed for twenty-four-hour hemodynamic control. Their primary purpose is reducing cardiovascular morbidity and mortality in hypertensive patient populations across outpatient and acute care settings. The drug class dimension shows calcium channel blockers and angiotensin II receptor blockers commanding the largest prescription volumes, while ACE inhibitors face margin compression from generic saturation. Oral administration routes dominate commercial value, though intravenous formulations capture disproportionate margins in emergency medicine settings where rapid blood pressure reduction is clinically critical.
The FDA's bioequivalence standards for generic antihypertensives and the EMA's centralized marketing authorization procedures jointly govern product approval pathways, with both agencies tightening pharmacovigilance requirements for drug classes associated with chronic lifetime exposure. India's CDSCO aligns domestic manufacturing standards with WHO prequalification norms, enabling contract production for export markets. Stakeholders must monitor evolving FDA guidance on complex generic formulations and emerging real-world evidence requirements from European payers as determinants of future market access and reimbursement positioning.
Market Dynamics
Hospital pharmacy procurement of fixed-dose combination therapies is accelerating as cardiology departments prioritize simplified regimens over complex multi-pill protocols. The FDA's streamlined ANDA review pathways for generic antihypertensives are compressing competitive entry timelines and eroding pricing power in commoditized monotherapy segments.
Growth Catalysts
- Medicare Part D Coverage Structures:The United States sustains volume leadership through aging demographics and comprehensive reimbursement frameworks that reduce patient out-of-pocket exposure for chronic cardiovascular medications.
- EMA Centralized Marketing Authorization:European pharmaceutical manufacturers benefit from unified approval procedures that accelerate cross-border commercialization of novel renin-angiotensin system inhibitors.
- CDSCO-WHO Alignment:Indian contract manufacturers leverage prequalification norms to capture export production contracts for generic calcium channel blockers destined for emerging markets.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient production for ACE inhibitors concentrates in specific Asian manufacturing clusters, exposing formulation specialists to single-source dependency risks.
- Generic Saturation Dynamics:Patent cliffs in angiotensin II receptor blockers have triggered price erosion exceeding therapeutic category norms, compressing margins for originator portfolios.
- Pharmacovigilance Intensification:Both FDA and EMA have tightened adverse event reporting requirements for drug classes with chronic lifetime exposure, extending post-market surveillance costs.
Strategic Opportunities
- Rural Outpatient Penetration:Community health centers in India's tier-2 and tier-3 cities present underexploited demand for affordable extended-release matrix formulations.
- Digital Therapeutic Convergence:Remote patient monitoring platforms are integrating with antihypertensive adherence programs to create differentiated value propositions for payers.
- Complex Generic Pathways:FDA guidance on bioequivalence standards for modified-release formulations offers first-mover advantages to manufacturers with advanced formulation capabilities.
Industry Challenges
- Formulation Talent Scarcity:Extended-release matrix development requires specialized expertise in polymer science and dissolution engineering that outpaces current training pipeline output.
- Legacy System Integration:Hospital pharmacy information systems require costly reconfiguration to accommodate automated dispensing protocols for fixed-dose combination therapies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Hypertensive Drugs Market |
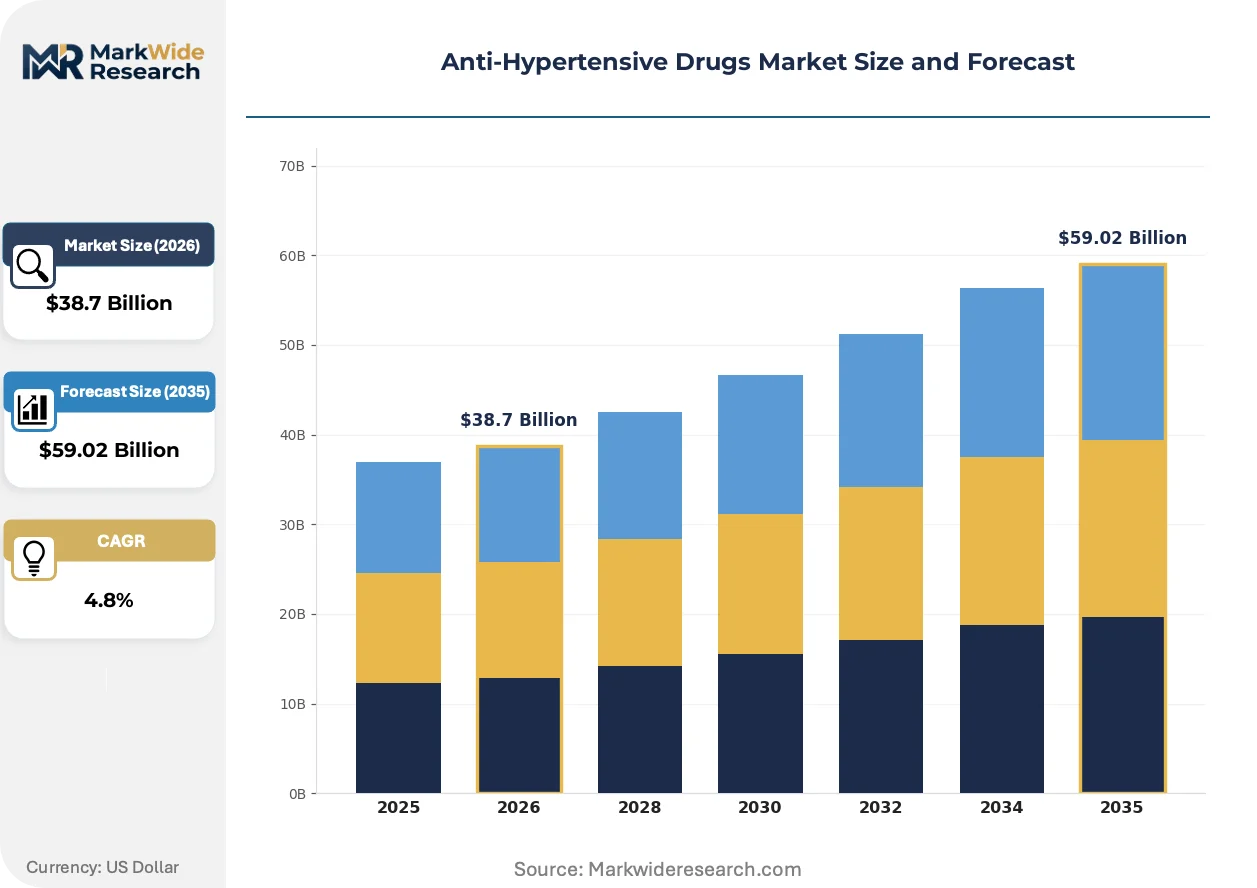
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: ACE Inhibitors, Angiotensin II Receptor Blockers, Calcium Channel Blockers, Diuretics Administration Route: Oral, Intravenous, Subcutaneous, Transdermal Patient Type: Adults, Elderly, Pediatric, Pregnant Women Therapeutic Area: Cardiology, Nephrology, Endocrinology, Emergency Medicine |
| Companies Covered | Novartis AG, Sanofi, Bayer AG, Boehringer Ingelheim, Pfizer Inc., Merck & Co. Inc., Daiichi Sankyo Company Limited, Takeda Pharmaceutical Company Limited, AstraZeneca plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Hypertensive Drugs Market Evolving Landscape
Antihypertensive drug development is pivoting toward precision dosing platforms and patient-centric delivery mechanisms that transcend conventional tablet formulations. Formulation scientists are exploiting advances in polymer engineering and connected health infrastructure to redefine therapeutic value.
Extended-release matrix systems incorporating hydrophilic polymer gradients are integrating real-time dissolution telemetry for twenty-four-hour hemodynamic control. Cardiology departments in integrated delivery networks are adopting these platforms at accelerating pace to reduce emergency department revisits. The technology is integrating clinical workflow optimization with remote therapeutic monitoring, compressing the traditional separation between acute and chronic care settings.
REACH compliance requirements for pharmaceutical manufacturing excipients are reshaping supplier qualification protocols across European production facilities. Industrial consequence includes accelerated substitution of conventional tablet binders with bio-based alternatives certified under circular economy frameworks. Generic manufacturers sourcing from Asian contract partners face disproportionate reformulation costs as ECHA substance evaluation timelines extend.
Hospital pharmacy procurement committees are consolidating vendor relationships around single-source contracts for therapeutic class bundles rather than molecule-by-molecule purchasing. Large pharmacy benefit managers are displacing traditional wholesale distribution channels with direct manufacturer agreements that capture volume discounts. This concentration is most visible in United States Medicare Advantage networks where annual formulary lock-in periods reduce switching flexibility.
Anti-Hypertensive Drugs Market Segmentation
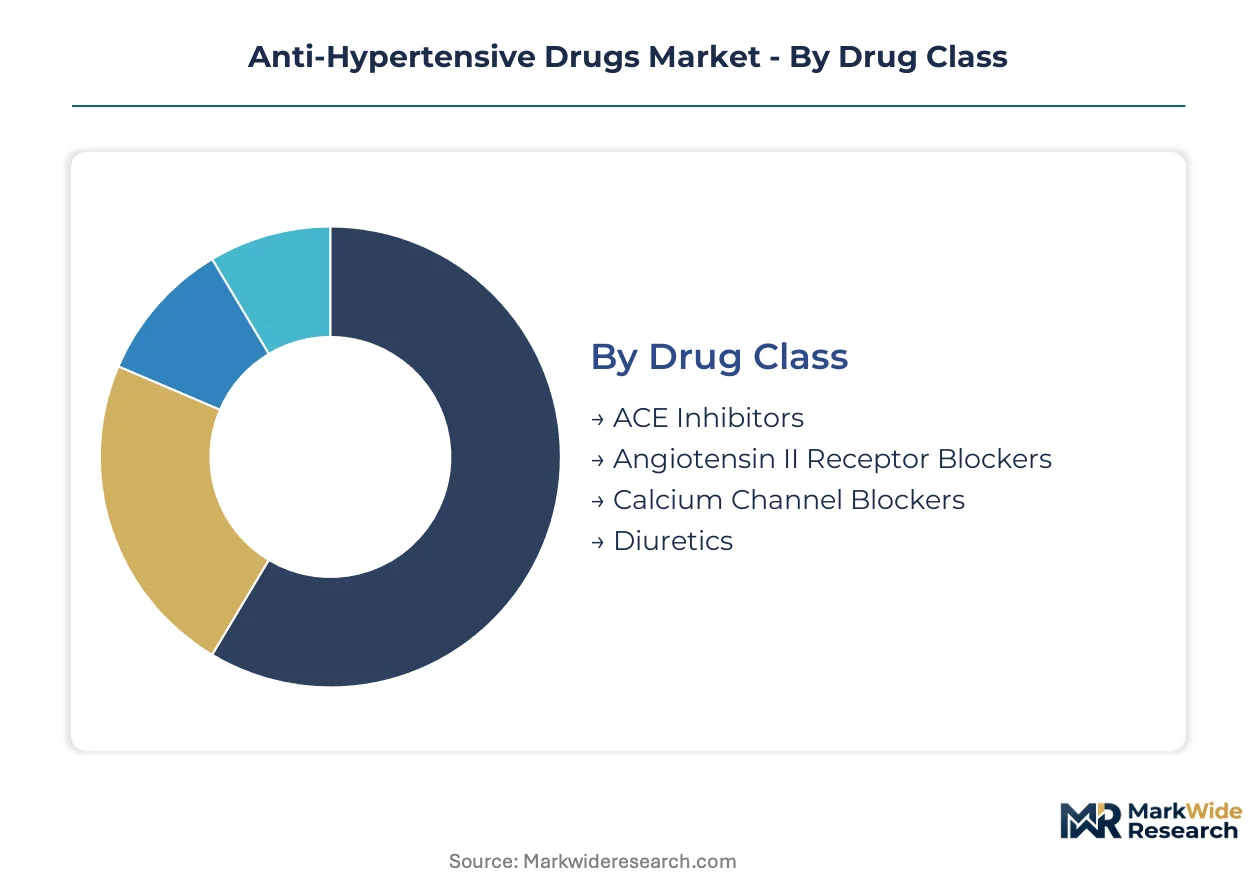
Anti-hypertensive drug segmentation reveals how regulatory pathways, clinical settings, and patient physiology intersect to shape commercial strategy. Manufacturers must align formulation investments with the specific approval burdens and reimbursement structures governing each category.
Drug Class:
EMA centralized marketing authorization and FDA bioequivalence standards impose distinct evidentiary requirements across pharmacological categories, with chronic lifetime exposure drugs facing intensified pharmacovigilance obligations.
- ACE Inhibitors:These agents block angiotensin-converting enzyme to reduce vasoconstriction and aldosterone secretion. Hospital networks in the United States favor generic lisinopril for formulary placement due to Medicare Part D reimbursement stability, though margin compression from ANDA saturation constrains originator investment.
- Angiotensin II Receptor Blockers:Selective AT1 receptor antagonists provide renin-angiotensin system inhibition without bradykinin-mediated cough. European cardiology departments prioritize valsartan and losartan combinations for their established efficacy profiles and streamlined EMA maintenance procedures.
- Calcium Channel Blockers:Dihydropyridine derivatives dominate outpatient prescribing for their predictable hemodynamic effects.
- Diuretics:Thiazide and loop variants retain essential status in combination regimens despite commodity pricing.
Calcium channel blockers sit at the top of the volume ranking, with angiotensin II receptor blockers climbing the fastest.
Administration Route:
Formulation complexity and manufacturing scale determine cost positioning, with extended-release oral matrices commanding premium pricing against immediate-release alternatives.
- Oral:Immediate-release tablets and extended-release matrix systems constitute the commercial backbone, with hydrophilic polymer gradients enabling twenty-four-hour coverage that reduces dosing frequency and improves adherence in chronic outpatient populations.
- Intravenous:Rapid-acting formulations capture disproportionate margins in emergency medicine settings where controlled blood pressure reduction is clinically critical, particularly nicardipine and clevidipine used in hypertensive crisis management.
- Subcutaneous:Depot formulations and implantable devices serve niche populations with severe adherence challenges.
- Transdermal:Patch-based delivery systems exploit skin permeation enhancers for patients with swallowing difficulties or gastrointestinal intolerance.
Oral formulations dominate absolute value contribution, while intravenous routes deliver the steepest margin expansion trajectory.
Patient Type:
Demographic-specific dosing protocols and pregnancy safety categories shape clinical trial design and label expansion investments.
- Adults:The core prescribing population drives volume through standardized dosing algorithms and broad formulary inclusion across commercial and government payers.
- Elderly:Age-related pharmacokinetic changes necessitate modified starting doses and enhanced monitoring for orthostatic hypotension, creating demand for simplified regimens in Medicare Advantage networks.
- Pediatric:Off-label use predominates due to limited trial data, with FDA pediatric exclusivity incentives motivating sponsor investment in liquid formulations and weight-based dosing tables.
- Pregnant Women:Teratogenicity concerns restrict options to methyldopa, labetalol, and nifedipine, with labeling requirements from FDA and EMA driving conservative prescribing patterns in obstetric settings.
Adult populations anchor volume rankings, with elderly segments expanding most quickly as aging demographics concentrate in developed markets.
Therapeutic Area:
Specialty care integration and comorbidity management patterns determine prescriber targeting and key opinion leader engagement strategies.
- Cardiology:Hypertension specialists and general cardiologists drive fixed-dose combination adoption, with hospital pharmacy committees consolidating vendor relationships around therapeutic class bundles rather than molecule-by-molecule purchasing.
- Nephrology:Proteinuric kidney disease protocols prioritize ACE inhibitors and ARBs for renoprotection, with dialysis unit formularies emphasizing agents cleared by non-renal mechanisms.
- Endocrinology:Diabetic nephropathy guidelines align prescribing with cardiology preferences, though endocrinologists emphasize agents with metabolic neutrality or beneficial effects on insulin sensitivity.
- Emergency Medicine:Rapid-acting intravenous agents command dedicated procurement channels, with integrated delivery networks adopting real-time hemodynamic telemetry to reduce revisits.
Cardiology sits at the top of the volume ranking, with emergency medicine gaining share fastest through acute care integration initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiovascular pharmacology specialists cluster in research-intensive metropolitan areas across North America, Europe, and Asia-Pacific, with hospital pharmacy networks and regulatory science hubs anchoring commercial deployment of antihypertensive therapies.
United States
Medicare Part D reimbursement frameworks sustain prescription volumes for chronic cardiovascular medications among aging populations. FDA streamlined ANDA review pathways compress generic entry timelines for calcium channel blockers and ACE inhibitors. Boston and Research Triangle Park host dense concentrations of cardiology clinical trial infrastructure and pharmacovigilance operations.
Germany
EMA centralized marketing authorization procedures accelerate cross-border commercialization of novel renin-angiotensin system inhibitors across German hospital networks. REACH compliance requirements for pharmaceutical excipients reshape supplier qualification protocols at manufacturing facilities in the Rhine-Main region. Heidelberg and Munich anchor pharmaceutical formulation research clusters developing extended-release matrix systems.
India
CDSCO alignment with WHO prequalification norms enables contract manufacturers to capture export production for generic antihypertensives destined for emerging markets. The country's national pharmaceutical regulator maintains stringent bioequivalence standards for oral solid dosage forms. Hyderabad and Ahmedabad concentrate active pharmaceutical ingredient production for ACE inhibitors and angiotensin II receptor blockers.
Japan
PMDA marketing authorization procedures govern the approval of fixed-dose combination therapies for elderly hypertensive populations in integrated care networks. METI industrial policy supports domestic manufacturing of extended-release formulations through targeted R&D subsidies. Tokyo and Osaka metropolitan areas host specialized polymer science research facilities advancing hydrophilic matrix engineering.
United Kingdom
NHS England procurement frameworks drive formulary placement decisions for generic antihypertensives across hospital pharmacy committees. MHRA pharmacovigilance requirements for chronic lifetime exposure drugs extend post-market surveillance obligations for cardiovascular agents. London and Cambridge concentrate clinical pharmacology expertise and real-world evidence generation capabilities for hypertension management protocols.
Anti-Hypertensive Drugs Market Competitive Landscape
Top-tier vendors anchor originator portfolios in patented fixed-dose combinations, while mid-tier specialists compete through manufacturing scale in commodity generic segments. The competitive terrain stratifies between premium-tier innovators with entrenched hospital network relationships and volume-driven manufacturers capturing pharmacy benefit manager contracts. Three archetypes dominate: multinational originators defending renin-angiotensin system inhibitor franchises, Indian contract manufacturers exploiting CDSCO-WHO alignment for export production, and European formulation specialists leveraging EMA centralized procedures for novel delivery systems. Consolidation pressures intensify through hospital pharmacy vendor consolidation around therapeutic class bundles and direct manufacturer agreements displacing wholesale distribution.
Within the multinational originator tier, Novartis AG and Pfizer Inc. exemplify divergent strategic positioning. Novartis occupies a position anchored in cardiovascular portfolio depth across European and North American hospital networks, while Pfizer sits within the scale-driven manufacturing archetype competing through volume contracts with large pharmacy benefit managers. Daiichi Sankyo Company Limited represents the Asia-Pacific specialist model, with its corporate structure reflecting concentrated investment in cardiovascular therapeutic areas.
| Leading Market Players |
|---|
| Novartis AG |
| Sanofi |
| Bayer AG |
| Boehringer Ingelheim |
| Pfizer Inc. |
| Merck & Co. Inc. |
| Daiichi Sankyo Company Limited |
| Takeda Pharmaceutical Company Limited |
| AstraZeneca plc |
| Others |
Value Network & Pricing Analysis
REACH compliance requirements for pharmaceutical manufacturing excipients gate both qualified supply and premium-tier pricing access in European production networks, forcing generic manufacturers to absorb disproportionate reformulation costs while originators with certified bio-based alternatives capture margin expansion.
Pricing Analysis
The bundled-versus-unbundled service split separates originator fixed-dose combinations commanding hospital formulary premiums from commodity generic monotherapies sold on per-unit transactional terms. Price differentiation hinges on FDA bioequivalence certification tier and manufacturing scale, with volume contracts anchoring pharmacy benefit manager negotiations. Cost compression in ACE inhibitor generics intensifies because ANDA saturation erodes originator pricing power. Community health centers exhibit highest price sensitivity, while integrated delivery networks in Medicare Advantage demonstrate lowest sensitivity due to annual lock-in protections.
Supply Chain Analysis
Active pharmaceutical ingredient production for renin-angiotensin system inhibitors rests on specialized manufacturing clusters in India and China, with formulation specialists in the United States and Europe completing downstream processing. Key inputs include hydrophilic polymer matrices for extended-release engineering, certified excipients meeting REACH standards, and specialized packaging for moisture-sensitive compounds. Single-source vulnerability in ACE inhibitor API supply exposes formulation networks to disruption. Distribution runs through consolidated hospital pharmacy committees and direct manufacturer agreements displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti-hypertensive drugs market functions as a regulatory compounder where FDA streamlined ANDA review pathways and EMA centralized marketing authorization procedures continuously reshape competitive entry economics and demand generation.
For Market Incumbents: Anchor defensive positioning through backward integration into API production for angiotensin II receptor blockers, eliminating single-source dependency risks from Asian manufacturing clusters. Accelerate certification investment in bio-based excipient alternatives ahead of ECHA substance evaluation timelines. Patent cliff exposure in commoditized monotherapy segments demands priority attention. For New Entrants and Emerging Players: Enter via rural outpatient penetration in India's tier-2 and tier-3 cities, where community health centers present underexploited demand for affordable extended-release matrix formulations. Digital therapeutic convergence with remote patient monitoring platforms offers the most penetrable go-to-market angle for payer differentiation. For Investors and Strategic Acquirers: Roll-up economics work for Indian contract manufacturers with CDSCO-WHO prequalification alignment because export production contracts for generic calcium channel blockers concentrate in a limited supplier base with high customer switching costs. Platform consolidation across formulation capabilities and regulatory certifications sustains long-term viability. Watch FDA guidance on complex generic bioequivalence standards as the inflection signal for first-mover advantage windows.| Strategic Initiative | Industry Significance |
|---|---|
| Complex Generic Pathway Advancement | FDA bioequivalence guidance for modified-release formulations creates first-mover positioning for advanced polymer science capabilities. |
| Fixed-Dose Combination Pipeline Expansion | Hospital pharmacy procurement consolidation around therapeutic class bundles rewards single-source contract depth. |
| Digital Therapeutic Integration | Remote patient monitoring platform partnerships differentiate adherence programs for Medicare Advantage formulary placement. |
| API Supply Security Investment | Backward integration into ACE inhibitor and ARB active pharmaceutical ingredients mitigates Asian cluster concentration risk. |
| REACH-Compliant Excipient Transition | ECHA substance evaluation timelines accelerate substitution of conventional tablet binders with certified bio-based alternatives. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining executive interviews with drug development leads, regulatory affairs specialists, hospital procurement managers, and payer access strategists alongside secondary validation through FDA filings, EMA centralized procedure databases, ClinicalTrials.gov records, and formulary placement trackers. Bottom-up prescription volume modeling triangulates against top-down therapeutic category expenditure estimates.
Rate-of-change decomposition separates volume drivers from price effects across the analysis window, with segmentation modeling incorporating drug class, administration route, patient population, and regional regulatory cluster dimensions. CAGRs derive from fitted trend extrapolation adjusted for patent cliff timing and generic entry acceleration. Forecast inputs include Medicare Part D enrollment trajectories, EMA centralized approval pipelines, and CDSCO-WHO prequalification expansion rates.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-world adherence data and emerging market pricing transparency introduce uncertainty bands around volume projections. Forecasts reflect documented assumptions regarding ANDA review timeline stability and pharmacovigilance cost trajectories. Regulatory guidance revisions, API supply disruptions, and digital therapeutic reimbursement determinations warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Propranolol Drug Market
Pharmacology
Hydroxychloroquine Drugs Market
Pharmacology
Antimycotics Market
Pharmacology
Aspirin API Market
Pharmacology
Apixaban Market
Pharmacology
Ibuprofen API Market
Pharmacology
Hypertension Drug Market
Pharmacology
ACE Inhibitors Market
Pharmacology
UK Pharmacovigilance Market
Pharmacology
Anti Inflammatory Therapeutics Market
Pharmacology
Injectable Drugs Market
Pharmacology
Alzheimer Drugs Market
Pharmacology
Hyperkalemia Drugs Market
Pharmacology
Global Artemisinin Combination Therapy Market
Pharmacology
Antithrombotic Drugs Market
Pharmacology
Cough Remedies Market