
 Global Geriatric Medicines Market | 2026-2036
Global Geriatric Medicines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Geriatric Medicines Market Foresight
Combination pill bundling for hypertension and diabetes is repositioning prescribing behavior in geriatric populations. Pfizer Inc. leverages its cardiovascular portfolio to anchor hospital pharmacy contracts across North America. AbbVie Inc. sustains leadership in immunology through specialized dosing protocols for patients over 75. Sanofi competes on insulin delivery systems tailored to declining dexterity in aging users.
Geriatric medicines comprise pharmaceutical formulations engineered with adjusted pharmacokinetics—reduced renal clearance compensation, modified hepatic metabolism buffers, and lower starting dose thresholds—to ensure therapeutic efficacy and minimize adverse drug interactions in patients aged 65 and older. Antihypertensives and antidiabetics generate the largest prescription volumes due to the chronic nature of cardiovascular and metabolic conditions in aging populations. Neurology therapies command premium pricing as Alzheimer's and Parkinson's disease pipelines face high clinical trial failure rates and prolonged development cycles.
The FDA's geriatric labeling guidelines and the EMA's age-appropriate formulation standards shape clinical trial design and commercialization pathways for new molecular entities targeting older adults. Japan's PMDA accelerates reviews for drugs addressing unmet needs in super-aged societies, creating a regulatory template that other agencies observe. Stakeholders must monitor how pharmacovigilance databases evolve to capture polypharmacy interactions, as real-world evidence becomes the decisive factor in payer reimbursement decisions for complex therapeutic regimens.
Market Dynamics
Polypharmacy risk management protocols are restructuring clinical trial endpoints and commercialization timelines for geriatric-focused molecular entities. Pharmaceutical sponsors now embed renal impairment cohorts and drug-drug interaction matrices earlier in development to preempt FDA and EMA rejection.
Growth Catalysts
- Japan's PMDA Accelerated Review Pathway:The regulator prioritizes submissions addressing unmet needs in super-aged populations, compressing approval timelines for dementia and sarcopenia therapies.
- Long-term care facility procurement expansion:Skilled nursing operators in the United States and Germany are expanding pharmacy budgets as patient acuity rises and length-of-stay extends.
- Real-world evidence integration:Payer organizations now mandate pharmacovigilance database submissions for polypharmacy interaction profiles before reimbursement authorization.
Market Restraints
- Clinical trial recruitment scarcity:Eligible patients over 75 with single-comorbidity profiles are increasingly difficult to enroll, inflating per-patient trial costs.
- Active pharmaceutical ingredient concentration:Contract manufacturers for modified-release geriatric formulations cluster in India and China, creating supply vulnerability.
- EU MDR compliance burden:The Medical Device Regulation imposes extended documentation requirements on drug-device combination products for insulin delivery and inhalation.
Strategic Opportunities
- Home-based infusion services:Specialty pharmacies in Germany and France are deploying nurse networks for parenteral biologic administration outside hospital settings.
- Digital therapeutics convergence:Cognitive training platforms paired with cholinesterase inhibitors are expanding into Alzheimer's care protocols in the United States.
- Combination pill formulation:Fixed-dose antihypertensive-antidiabetic bundles address adherence gaps in Brazil's public health system.
Industry Challenges
- Clinical pharmacology expertise scarcity:Qualified investigators with geriatric pharmacokinetics specialization are concentrated at academic medical centers in Japan, the United Kingdom, and the United States.
- Legacy electronic health record incompatibility:Polypharmacy screening algorithms fail to integrate with hospital systems deployed before 2015.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Geriatric Medicines Market |
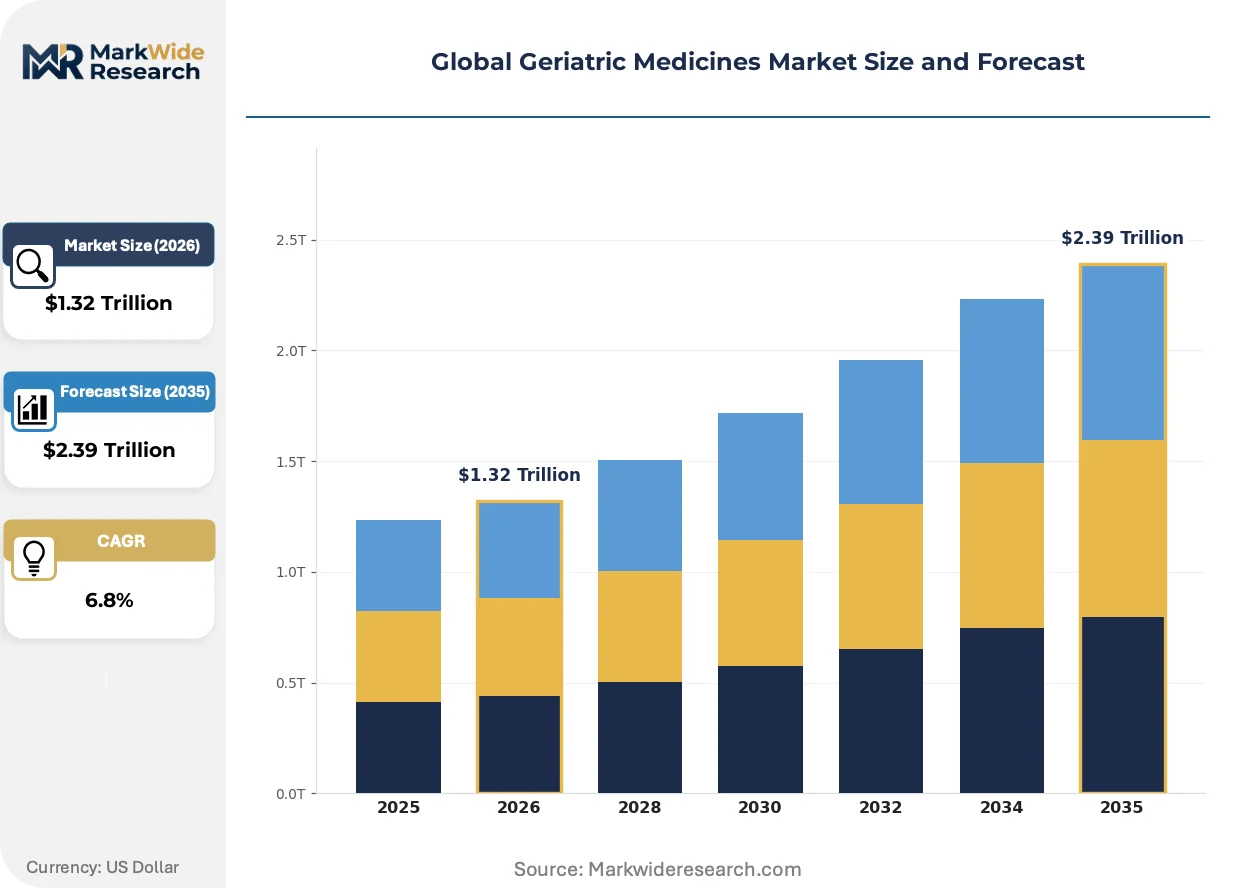
| Market Size in 2026 | $1.32 Trillion |
| Market Size in 2035 | $2.39 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Antidepressants, Antihypertensives, Antidiabetics, Anticoagulants, Vitamins Therapy Area: Neurology, Cardiology, Endocrinology, Musculoskeletal, Respiratory, Dermatology End User: Long-Term Care Facilities, Geriatric Clinics, Home Healthcare, Rehabilitation Centers, Specialty Hospitals Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Wholesale Distributors, Direct-to-Patient |
| Companies Covered | AstraZeneca PLC, AbbVie Inc., Pfizer Inc., Bristol-Myers Squibb Company, GlaxoSmithKline plc, Merck & Co., Inc., Sanofi, F. Hoffmann-La Roche Ltd., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Geriatric Medicines Market Shifts & Advancements
Pharmaceutical formulation science is pivoting toward patient-centric delivery mechanisms that compensate for physiological decline. Manufacturers now engineer dosage forms around swallowing difficulty, tremor-induced dosing errors, and declining hepatic reserve rather than assuming standard adult metabolism.
Modified-release oral solids with embedded taste-masking and rapid disintegration properties are expanding into nursing home and assisted-living formularies. European and Japanese long-term care operators are adopting these formulations at twice the rate of traditional immediate-release equivalents. The technology is expanding into combination therapies where timing synchronization between multiple actives determines efficacy.
The FDA's 2023 geriatric labeling guidance mandates dedicated pharmacokinetic studies in patients aged 75 and older for all new molecular entities with systemic exposure. This industrial consequence forces sponsors to extend Phase I programs by six to twelve months. Oncology and neurology pipelines face the steepest compliance costs, with Alzheimer's drug developers in the United States restructuring protocols to include frailty index stratification.
Hospital pharmacy procurement committees in the United States are consolidating vendor relationships around single-source contracts for entire therapeutic classes. Group purchasing organizations now bundle anticoagulant, antidiabetic, and osteoporosis portfolios under three-year agreements with inflation-linked escalators. This concentration is most visible in the southeastern states, where health system mergers have reduced the number of independent formulary decision-makers by half since 2019.
Global Geriatric Medicines Market Segmentation
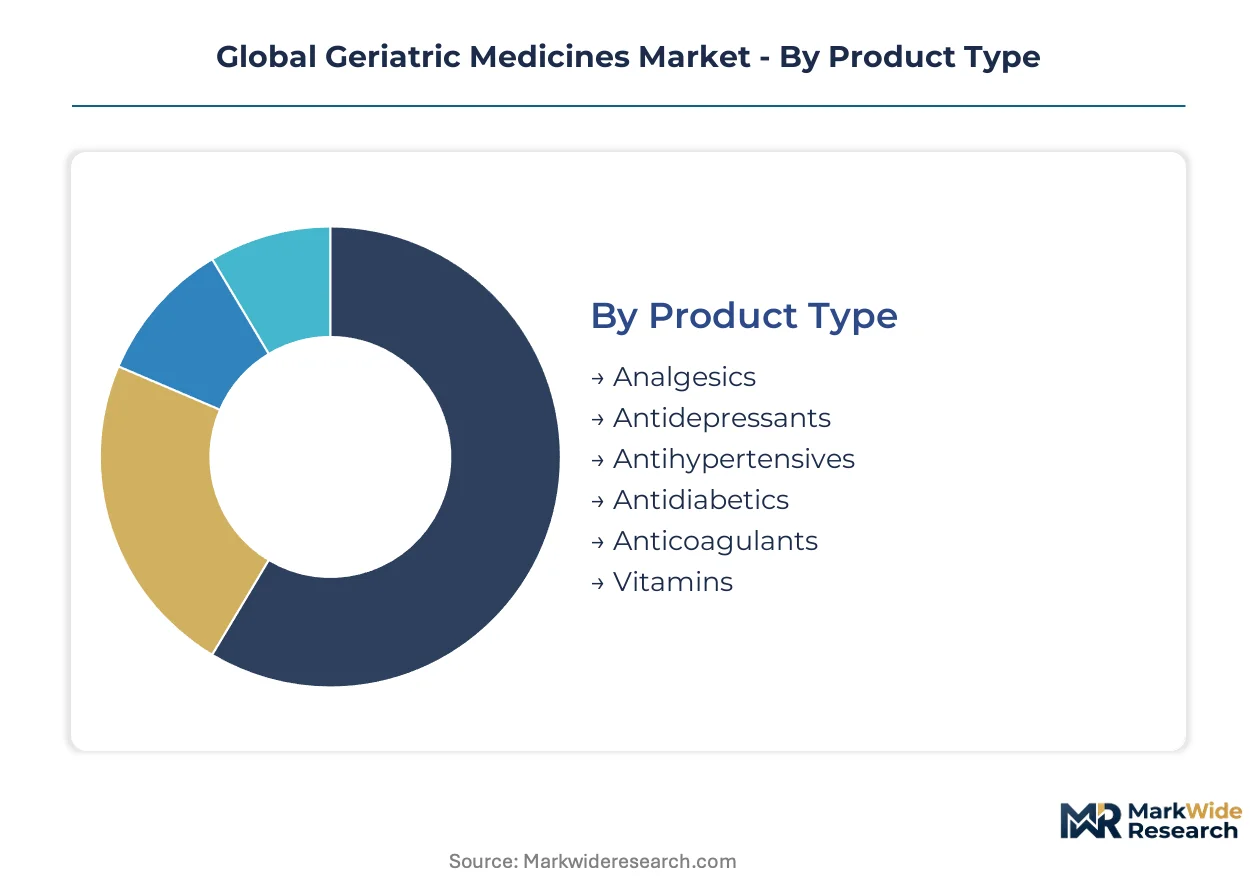
Geriatric medicine segmentation reflects distinct prescribing patterns across physiological systems and care settings. Product formulation requirements vary sharply between institutional buyers managing polypharmacy and home-based patients prioritizing administration simplicity.
Product Type:
Cost tier separates chronic maintenance therapies from acute intervention drugs in procurement decisions.
- Antihypertensives:Formulations incorporate modified-release mechanisms compensating for reduced renal clearance in patients over 75. Demand concentrates in Japan's long-term care facilities where stroke prevention protocols mandate combination angiotensin receptor blocker therapy.
- Antidiabetics:Sulfonylurea derivatives and DPP-4 inhibitors dominate with dose-adjustment protocols for hepatic impairment. Germany's diabetes disease management programs drive volume through fixed-dose combination bundling with cardiovascular agents.
- Analgesics:NSAID-sparing acetaminophen formulations with abuse-deterrent properties serve osteoarthritis populations in the United States.
- Antidepressants:SSRI variants with reduced anticholinergic burden address depression comorbid with dementia in European nursing homes.
- Anticoagulants:Direct oral anticoagulants with renal dose adjustment replace warfarin in atrial fibrillation protocols across North American health systems.
- Vitamins:High-dose D3 and B12 supplementation targets malabsorption in gastritis patients across Mediterranean markets.
Antihypertensives lead volumes today; anticoagulants are gaining share fastest as atrial fibrillation prevalence rises with population aging.
Therapy Area:
Application urgency determines reimbursement tiering and formulary placement speed.
- Cardiology:Chronic heart failure and arrhythmia medications require titration protocols accommodating frailty indices. Japanese super-aged societies generate concentrated demand for mineralocorticoid receptor antagonists in post-myocardial infarction regimens.
- Neurology:Alzheimer's and Parkinson's disease pipelines command premium development costs due to blood-brain barrier penetration requirements. The FDA's amyloid-targeting approval pathway accelerates investment in disease-modifying therapies for the United States market.
- Endocrinology:Thyroid replacement and osteoporosis therapies address metabolic decline in post-menopausal populations across France and Italy.
- Musculoskeletal:Rheumatoid arthritis biologics with subcutaneous administration options serve homebound elderly in the United Kingdom.
- Respiratory:COPD maintenance inhalers with breath-actuated delivery compensate for declining inspiratory force in German pulmonary rehabilitation centers.
- Dermatology:Topical corticosteroid-sparing immunomodulators treat chronic eczema in immunosenescent patients across Scandinavian markets.
Cardiology commands the largest revenue base; neurology exhibits the steepest expansion trajectory as dementia prevalence accelerates.
End User:
Customer type dictates packaging specifications, dosing support requirements, and procurement contract structures.
- Long-Term Care Facilities:Centralized medication administration drives demand for blister-packaged, crush-resistant formulations with barcode verification. United States skilled nursing operators consolidate purchasing through group purchasing organizations covering anticoagulant and antidiabetic portfolios.
- Home Healthcare:Nurse-administered parenteral therapies require cold-chain logistics and patient-specific compounding. French and German specialty pharmacy networks deploy visiting nurses for biologic administration outside hospital settings.
- Geriatric Clinics:Comprehensive geriatric assessment programs in Japan coordinate polypharmacy reviews and deprescribing protocols.
- Rehabilitation Centers:Post-acute stroke and fracture recovery facilities in Italy prioritize pain management with minimized sedation risk.
- Specialty Hospitals:Acute geriatric units in the United Kingdom focus on delirium prevention and rapid functional restoration.
Long-term care facilities lead institutional volumes; home healthcare is expanding most quickly as aging-in-place policies advance.
Distribution Channel:
Supply concentration shapes margin structures and patient access timelines across geographies.
- Hospital Pharmacies:Formulary committees enforce therapeutic class standardization with inflation-linked multi-year contracts. Southeastern United States health system mergers have halved independent decision-making entities since 2019.
- Retail Pharmacies:Medication therapy management programs address adherence gaps through synchronization and packaging services. Brazilian public health system retail networks distribute fixed-dose antihypertensive-antidiabetic bundles.
- Online Pharmacies:Automated refill systems with caregiver notification features serve dispersed rural elderly in Australia.
- Wholesale Distributors:Temperature-controlled logistics networks supply modified-release formulations to nursing home chains across Canada.
- Direct-to-Patient:Specialty pharmacy home delivery with nurse support coordinates complex biologic regimens in the Netherlands.
Hospital pharmacies retain the dominant volume position; direct-to-patient channels are climbing the fastest as chronic disease management migrates from institutional to residential settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern geriatric medicines industry traces its commercial roots to post-war pharmaceutical expansion in Switzerland and the United States, where early cardiovascular and metabolic therapies established dosing protocols that now govern age-adjusted pharmacokinetics worldwide.
United States
Hospital pharmacy consolidation and group purchasing organization dominance drive procurement concentration across the Southeast and Midwest. The FDA's 2023 geriatric labeling guidance mandates dedicated pharmacokinetic studies for patients aged 75 and older, extending Phase I timelines. Greater Boston anchors clinical pharmacology expertise, with academic medical centers training specialists in polypharmacy risk management.
Japan
The world's oldest population generates concentrated demand for dementia and sarcopenia therapies across Kanto and Kansai regions. PMDA accelerated review pathways compress approval timelines for drugs addressing unmet needs in super-aged societies. Tokyo's geriatric clinics coordinate comprehensive assessment programs that serve as global templates for deprescribing protocols.
Germany
Diabetes disease management programs and long-term care facility expansion drive fixed-dose combination bundling across Bavaria and North Rhine-Westphalia. The EU's MDR imposes extended documentation requirements on drug-device combination products for insulin delivery. Cologne and Düsseldorf host specialty pharmacy networks deploying nurse-administered parenteral therapies outside hospital settings.
United Kingdom
Post-acute rehabilitation centers and acute geriatric units prioritize delirium prevention and rapid functional restoration across London and the Midlands. NHS formulary committees enforce therapeutic class standardization with multi-year contracts. Manchester and Birmingham clusters concentrate rheumatoid arthritis biologic administration for homebound elderly populations.
France
Public health system retail networks and home healthcare expansion support aging-in-place policies across Île-de-France and Auvergne-Rhône-Alpes. ANSM pharmacovigilance requirements shape polypharmacy interaction profiling for reimbursement decisions. Lyon and Marseille specialty pharmacies coordinate cold-chain logistics for modified-release formulations in nursing home chains.
Global Geriatric Medicines Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the patent protection and clinical differentiation spectrum. The market structure organizes into three tiers: research-intensive innovators commanding therapeutic class leadership, mid-cap specialists with regional hospital pharmacy contracts, and generic manufacturers competing on modified-release formulation availability. Strategic moves concentrate on portfolio bundling for group purchasing organization access and backward integration into active pharmaceutical ingredient supply.
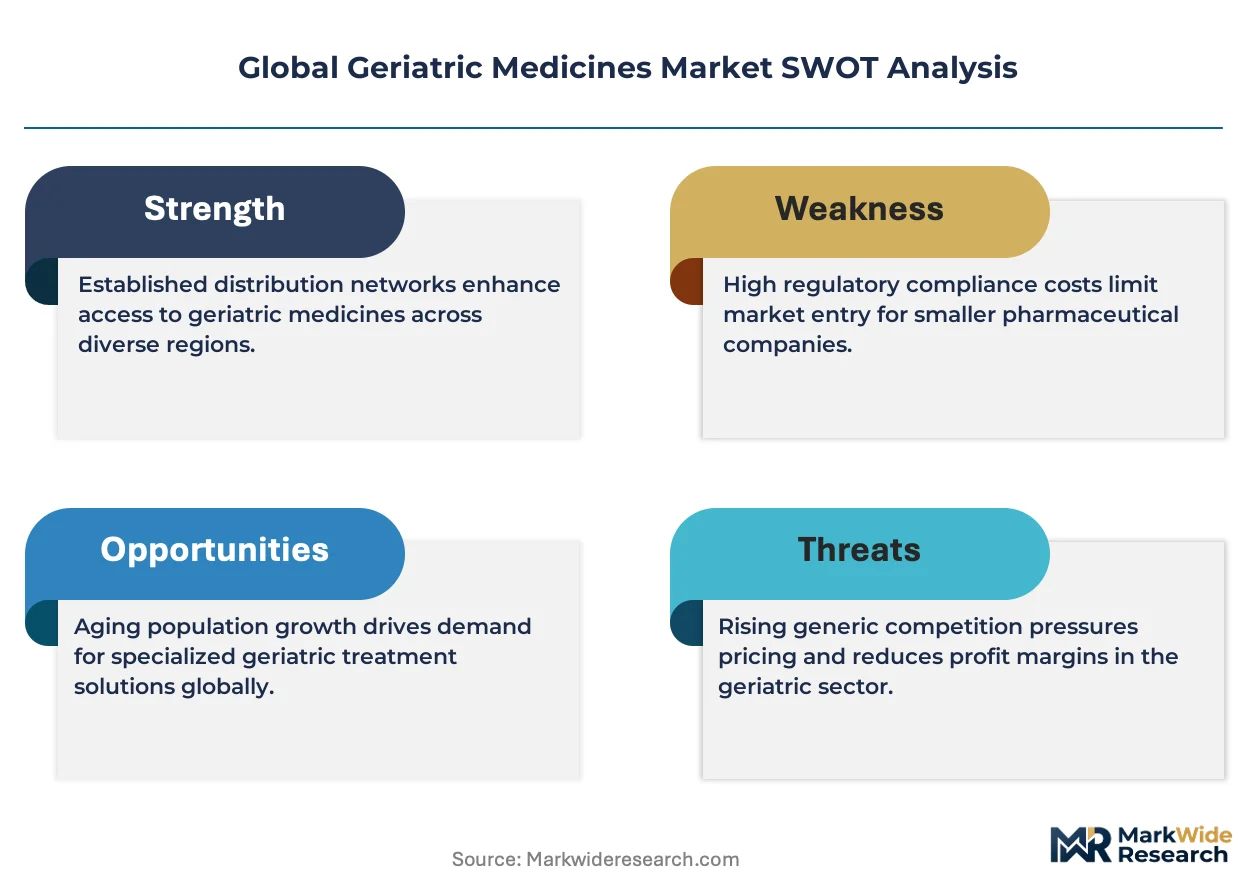
Among research-intensive innovators, Pfizer Inc., AbbVie Inc., and Sanofi exemplify distinct competitive archetypes. Pfizer anchors cardiovascular portfolio contracting across North American health systems. AbbVie occupies a position in immunology through specialized dosing protocols for patients over 75. Sanofi sits within the diabetes delivery tier, competing on insulin systems adapted to declining dexterity in aging users. These three represent how therapeutic focus and formulation adaptation determine hospital pharmacy procurement positioning.
| Leading Market Players |
|---|
| AstraZeneca PLC |
| AbbVie Inc. |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| GlaxoSmithKline plc |
| Merck & Co., Inc. |
| Sanofi |
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| Others |
Supply & Pricing Matrix
Active pharmaceutical ingredient costs for modified-release geriatric formulations flow from Indian and Chinese contract manufacturers through hospital pharmacy procurement committees in the United States and Germany, with pricing power accumulating at the group purchasing organization tier.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates patented combination therapies from branded generics and commodity immediate-release equivalents. Price differentiation rests on FDA geriatric labeling certification and volume scale through long-term care facility contracts. Pricing pressure stems from EU MDR compliance costs for drug-device combinations. Retail pharmacy segments exhibit highest price sensitivity; specialty hospital formulary committees show lowest.
Supply Chain Analysis
Direct-to-patient specialty pharmacy channels handle complex biologic regimens for homebound elderly in France and the Netherlands. API manufacturing concentrates in India, China, and Switzerland. Finished dose formulation draws from Germany, Japan, and the United States. Single-source vulnerability in modified-release excipient supply creates exposure. Distribution runs through wholesale networks with temperature-controlled logistics for nursing home chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The geriatric medicines market compounds regulatory value through the FDA's 2023 mandate for dedicated pharmacokinetic studies in patients aged 75 and older, forcing extended development timelines that favor established players with clinical infrastructure.
For Market Incumbents: To counter biosimilar erosion in anticoagulant portfolios, secure backward integration into modified-release API supply and anchor hospital pharmacy contracts through therapeutic class bundling with inflation-linked escalators. Invest in frailty-index stratification capabilities for Alzheimer's trial protocols ahead of competitor pipeline entries.
For New Entrants and Emerging Players: Capture white-space in home-based infusion services across German and French specialty pharmacy networks, where nurse-administered parenteral biologics bypass hospital procurement concentration. Target digital therapeutics convergence with cholinesterase inhibitors in United States Alzheimer's protocols as the most penetrable entry vector.
For Investors and Strategic Acquirers: Consolidation pressure builds where clinical pharmacology expertise scarcity intersects with PMDA accelerated review pathway access in Japan's super-aged markets. Five-to-ten year viability favors mid-cap specialists with regional hospital pharmacy contracts and captive formulation science capabilities. Monitor pharmacovigilance database integration rates as the decisive inflection signal for payer reimbursement positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Frailty-index stratification in Alzheimer's protocols satisfies FDA geriatric labeling mandates. |
| Regulatory Approval Pathway | PMDA accelerated review access compresses timelines for dementia therapies in Japan. |
| Manufacturing Scale-Up | Modified-release capacity expansion in India secures API supply for long-term care formularies. |
| Pipeline Diversification | Combination pill bundling addresses adherence gaps in Brazilian public health distribution. |
| Strategic Partnership | Specialty pharmacy nurse networks enable home-based biologic administration outside hospitals. |
Research Methodology
Bottom-up long-term care facility procurement modeling reconciled against top-down active pharmaceutical ingredient production tracking forms the analytical core. Primary interviews with drug development executives, formulary directors, hospital procurement managers, and payer access specialists combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Triangulation between demand-side prescribing pattern analysis and supply-side manufacturing capacity assessment ensures cross-verification.
Input-output matrices segment volume and value projections across therapy area, product formulation, end-user setting, and regional regulatory cluster throughout the forecast period. CAGRs derive from patent expiration schedules, biosimilar entry curves, and demographic aging trajectories. Forecast inputs incorporate PMDA review pathway utilization rates and group purchasing organization contract renewal cycles.
Regulatory guideline revisions, clinical trial recruitment failures, and API supply disruptions are the dominant revision risks. Forecasts reflect base-case assumptions regarding payer reimbursement continuity and polypharmacy database integration timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Anti-Asthma Drugs Market
Pharmacology
Aspirin API Market
Pharmacology
Immunotherapy Drugs Market
Pharmacology
UK Pharmacovigilance Market
Pharmacology
Drug Delivery Across the Blood-Brain Barrier Market
Pharmacology
Thromboprophylactic Drugs Market
Pharmacology
Drug Eruptions Treatment Market
Pharmacology
Intranasal Drug and Vaccine Delivery Market
Pharmacology
Injectable Drugs Market
Pharmacology
Aldosterone Receptor Antagonists Market
Pharmacology
Autacoids and Related Drugs Market
Pharmacology
Ketoprofen API Market
Pharmacology
Drug Repurposing Market
Pharmacology
Hydroxychloroquine Drugs Market
Pharmacology
Antimycotics Market
Pharmacology
ACE Inhibitors Market