
 ASEAN Poultry Vaccines Market | 2026-2036
ASEAN Poultry Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Poultry Vaccines Market Intelligence
Veterinary pharmaceutical distribution across Southeast Asia is rewriting procurement pathways for commercial poultry operations. Zoetis leverages its established cold-chain logistics network to sustain supply continuity across Indonesian archipelago farms. Boehringer Ingelheim International GmbH anchors its regional position through dedicated vaccine production facilities serving Thai and Vietnamese integrators. Ceva competes by specializing in respiratory disease combinations tailored to tropical climate stressors.
Poultry vaccines comprise biological preparations containing attenuated or inactivated pathogens, antigenic subunits, or recombinant vectors designed to stimulate protective immune responses in chickens against virulent field strains. These formulations typically require refrigerated storage between 2°C and 8°C and deliver efficacy through mucosal, humoral, or cell-mediated immunity depending on delivery mode and antigen design. Live attenuated vaccines dominate volume consumption across ASEAN hatcheries where mass-administration economics favor spray or drinking-water application methods. Recombinant vaccines capture expanding share among layer management operations seeking differentiated protection profiles against evolving field challenges.
Indonesia's Ministry of Agriculture, Thailand's Department of Livestock Development, and Vietnam's Department of Animal Health collectively enforce vaccination compliance through farm registration systems and border biosecurity checkpoints. These frameworks elevate product registration barriers while channeling procurement toward manufacturers with established dossier track records and local stability data. Stakeholders must monitor shifting strain prevalence patterns and regulatory harmonization initiatives across ASEAN economic corridors to align R&D pipelines with emerging disease control priorities.
Market Dynamics
Contract farming consolidation across Vietnam's Mekong Delta and Indonesia's Java corridor is concentrating vaccine procurement decisions into fewer integrator hands, amplifying price leverage and reshaping supplier relationships.
Growth Catalysts
- Indonesia's compulsory immunization mandates:The Ministry of Agriculture's enforcement of Newcastle disease and avian influenza schedules creates guaranteed demand volume for registered products across commercial broiler and layer operations.
- Climate-adapted respiratory combinations:Heat stress in tropical environments elevates susceptibility to secondary bacterial infections, driving uptake of multivalent vaccines targeting E. coli and Mycoplasma gallisepticum in tandem with viral coverage.
- Hatchery biosecurity investment:Thai and Vietnamese integrators are embedding vaccination protocols into day-old chick production workflows, shifting administration earlier in the production cycle.
Market Restraints
- Cold-chain infrastructure gaps:Last-mile temperature excursions above 8°C degrade live attenuated vaccine potency across Indonesian archipelago farms lacking reliable refrigeration.
- Regulatory dossier requirements:ASEAN member states maintain non-harmonized registration pathways, forcing manufacturers to replicate stability studies and field trials for each national veterinary authority.
- Antigenic drift surveillance limitations:Field strain monitoring networks remain underdeveloped in Laos, Cambodia, and Myanmar, delaying vaccine strain updates against evolving Newcastle disease genotypes.
Strategic Opportunities
- Myanmar's underpenetrated commercial sector:Transition from backyard to semi-intensive production creates first-mover positioning for hatchery-linked vaccination programs in Yangon and Mandalay corridors.
- Recombinant vector platforms:HVT-vectored vaccines enabling differentiation between infected and vaccinated animals unlock premium positioning for layer operations supplying export-certified product.
- Digital traceability integration:Farm registration systems in Vietnam and Thailand are creating data infrastructure for outcome-linked vaccine procurement contracts.
Industry Challenges
- Field vaccinator skill gaps:Mass-administration techniques via spray or drinking water require consistent technique across contract grower networks where training continuity is uneven.
- Serological monitoring capacity:Commercial farms lack in-house laboratory infrastructure to validate immune response post-vaccination, complicating protocol optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Poultry Vaccines Market |
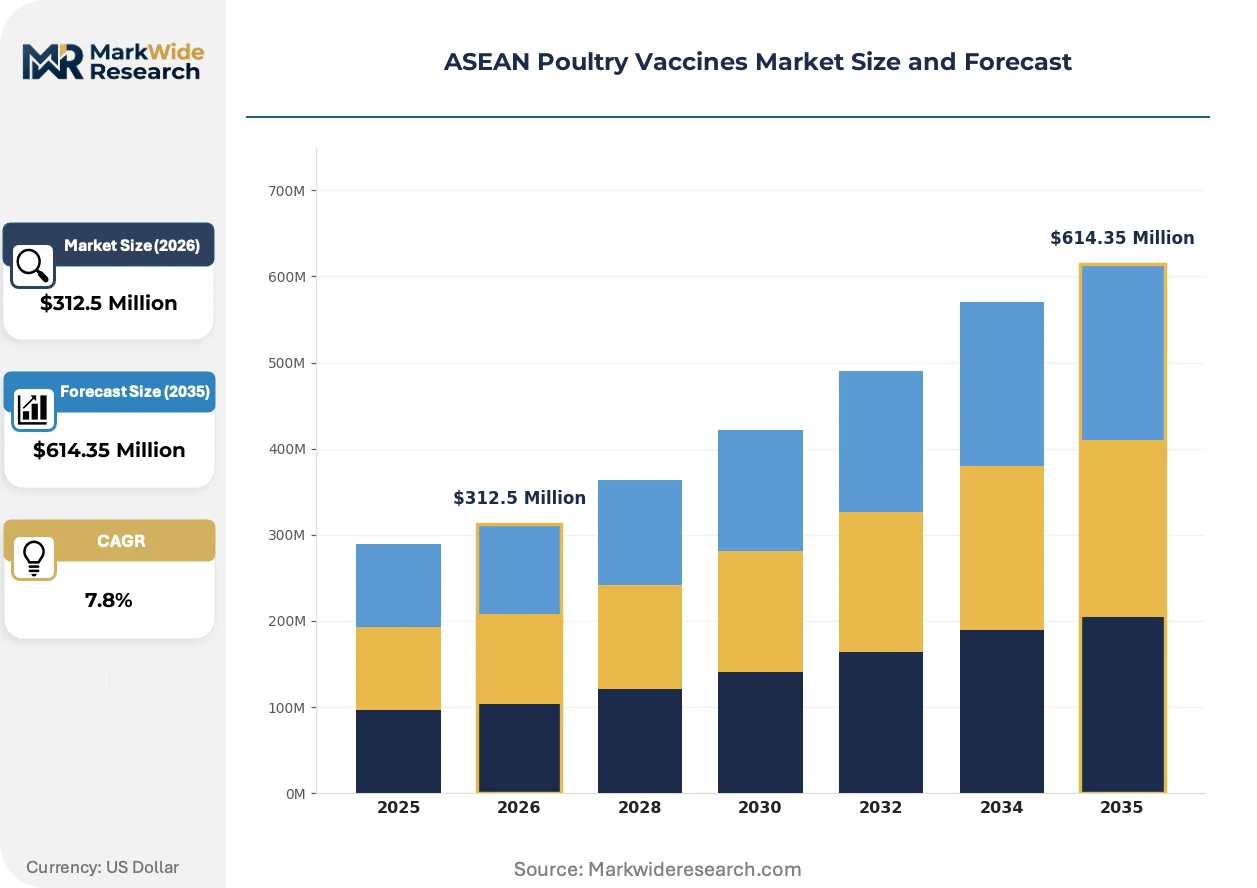
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $614.35 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Attenuated Vaccines, Inactivated Vaccines, Subunit Vaccines, Recombinant Vaccines Application: Broiler Production, Layer Management, Hatchery, Breeder Flocks Delivery Mode: Oral Administration, Injectable Vaccines, Water Medication, Spray Vaccination End User: Poultry Farms, Veterinary Clinics, Agricultural Cooperatives, Research Institutions |
| Companies Covered | Boehringer Ingelheim International GmbH, Zoetis, Ceva, Phibro Animal Health Corporation, Elanco, Merck & Co., Inc., HIPRA, Medion Farma, Malaysian Vaccines & Pharmaceuticals Sdn Bhd, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Poultry Vaccines Market Strategic Shifts & Innovations
Digitalization of cold-chain monitoring and precision delivery systems is compressing waste rates and enabling outcome-based supplier relationships across Southeast Asian poultry operations.
Recombinant vector technology is virtualizing traditional live attenuated vaccine economics by enabling single-dose protection against multiple pathogens. Thai layer integrators are adopting HVT-vectored infectious laryngotracheitis vaccines to reduce handling stress and labor costs. This platform is compressing the competitive advantage of conventional multivalent cocktails by delivering differentiated serological profiles that satisfy export health certification requirements.
Indonesia's Ministry of Agriculture is tightening farm registration and movement control regulations through its veterinary authority compliance frameworks. These measures are elevating documentation burdens for vaccine procurement while channeling demand toward suppliers with established local stability dossiers. Commercial farms in Java and Sumatra are responding by consolidating supplier relationships to reduce regulatory exposure.
Integrator procurement offices are consolidating vaccine purchasing through direct manufacturer agreements, displacing traditional veterinary distributor intermediaries. Thai and Vietnamese contract farming companies are negotiating annual supply contracts with volume commitments and technical service bundling. This pattern is most pronounced in the Mekong Delta where integrated poultry companies operate captive hatcheries and vertically controlled grow-out networks.
ASEAN Poultry Vaccines Market Segmentation
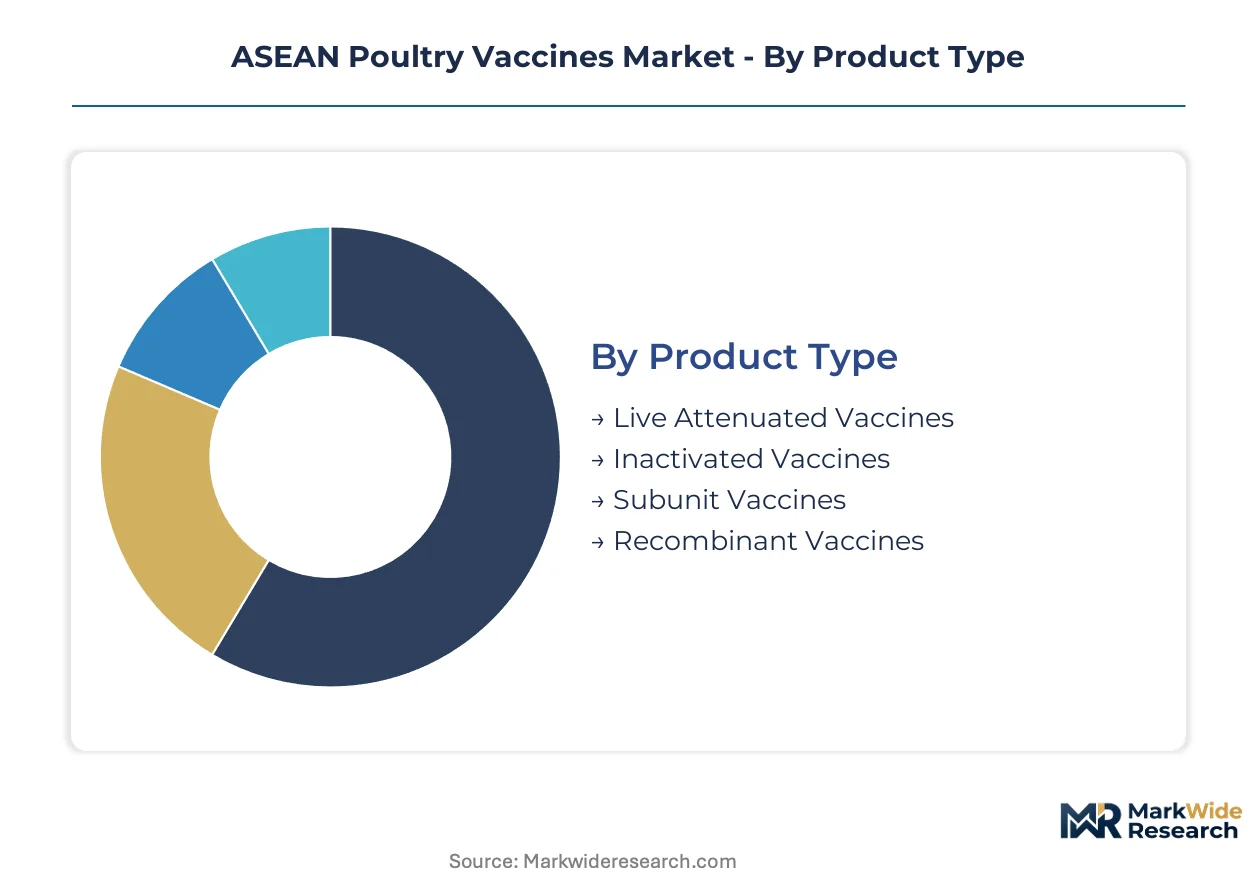
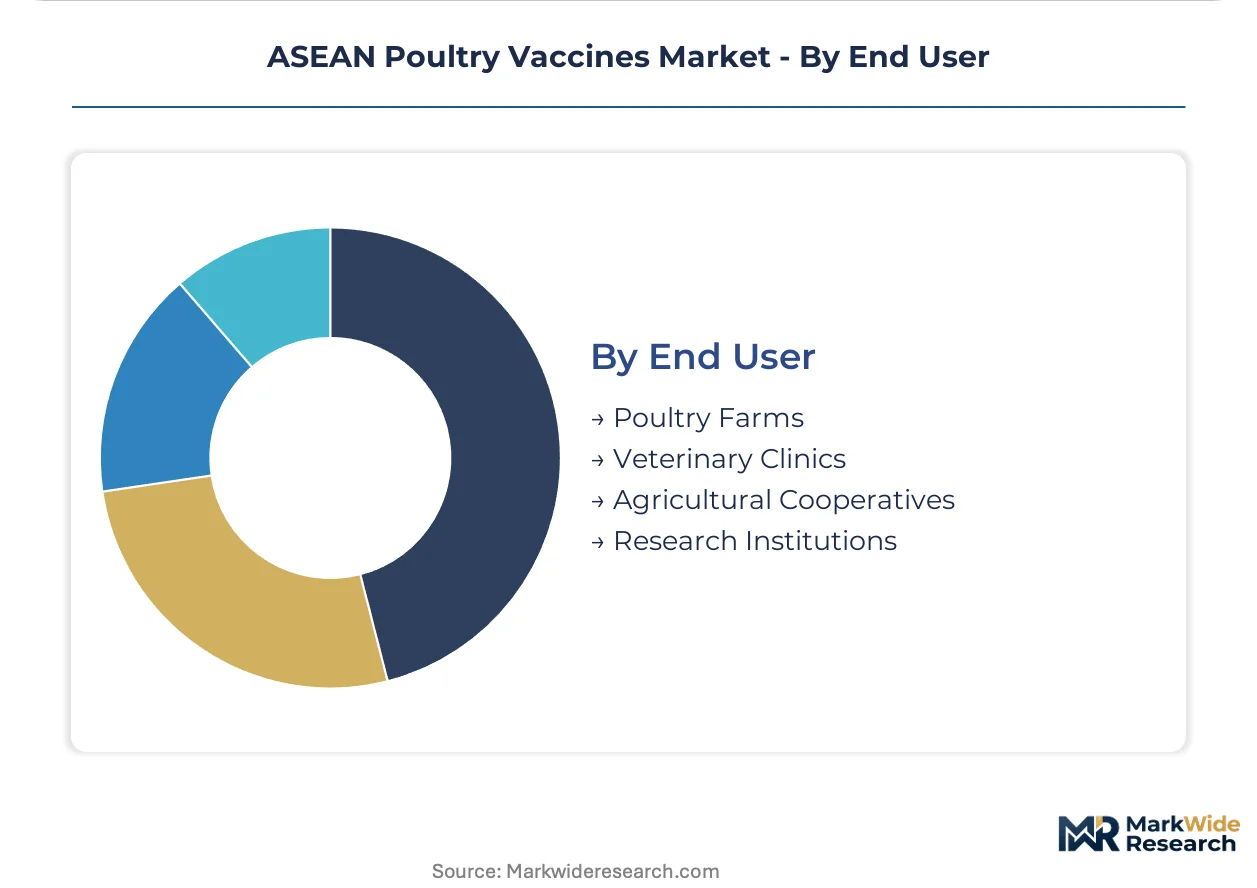
Vaccine segmentation across ASEAN poultry operations determines cold-chain logistics intensity, administration labor requirements, and technical service bundling. Product type and delivery mode choices cascade through procurement economics, hatchery workflow design, and farm-level compliance documentation. Understanding these segment boundaries enables suppliers to align formulation portfolios with integrator scale and regulatory pathway complexity.
Product Type:
After-sales service intensity varies sharply across vaccine technology platforms, with live attenuated formulations demanding continuous cold-chain monitoring and field technical support throughout the distribution network.
- Live Attenuated Vaccines:These formulations contain weakened pathogen strains that replicate minimally in the host to stimulate durable cellular immunity without causing clinical disease. Indonesian broiler integrators in Java and Sumatra favor mass-administration economics via spray or drinking-water delivery at hatchery or farm level, though temperature excursions above 8°C during archipelago transport degrade potency and trigger technical service interventions.
- Recombinant Vaccines:Genetically engineered vectors—typically herpesvirus of turkey (HVT)—deliver pathogen-specific antigens while enabling serological differentiation between infected and vaccinated animals. Vietnamese layer operations in the Mekong Delta adopt these platforms to satisfy export health certification requirements, accepting premium pricing for reduced handling stress and labor cost compression across multi-dose replacement schedules.
- Inactivated Vaccines:Killed pathogen preparations requiring adjuvant formulation and parenteral administration, predominantly used in breeder flock protocols where maternal antibody transfer to progeny is critical.
- Subunit Vaccines:Purified antigenic components excluding pathogen genetic material, offering safety advantages for research institutions and high-value genetic stock with limited local production presence.
Live attenuated vaccines hold the largest share; momentum sits with recombinant platforms.
Application:
Cost tier stratification across production systems drives vaccine portfolio complexity, with broiler operations prioritizing unit-dose economics and layer management accepting premium formulations for extended depreciation periods.
- Broiler Production:Short-cycle meat bird operations across Thailand's central plains and Indonesia's Java corridor concentrate demand for low-cost, mass-administered respiratory and enteric protection. Contract farming consolidation amplifies volume purchasing leverage while compressing margins for suppliers lacking hatchery integration or direct technical service deployment.
- Layer Management:Egg production facilities with 60-80 week depreciation horizons justify recombinant and inactivated investments targeting sustained output and export certification compliance. Thai integrators in Saraburi and Nakhon Ratchasima provinces lead adoption of HVT-vectored infectious laryngotracheitis vaccines to reduce field revaccination labor.
- Hatchery:Day-old chick vaccination protocols embedding immunity before farm placement, requiring precision spray equipment and standardized technique across contract grower networks.
- Breeder Flocks:Genetic multiplication operations commanding highest biosecurity tiers and maternal antibody programming for vertical integration into commercial progeny supply.
Broiler production commands volume leadership; layer management is climbing the fastest on value per dose.
Delivery Mode:
Volume scale across ASEAN hatcheries and farms determines administration infrastructure investment, with automated spray systems and medicated water lines displacing manual injection in integrated operations.
- Spray Vaccination:Aerosol delivery of live attenuated respiratory vaccines enabling thousands of day-old chicks to receive uniform dosing within minutes. Thai and Vietnamese hatcheries embed automated cabinet systems into production workflows, though field vaccinator skill gaps across contract grower networks create technique inconsistency and efficacy variability.
- Water Medication:Oral delivery via drinking water lines suited to grower and finisher phase revaccination in broiler houses, demanding precise chlorine neutralization and consumption monitoring.
- Injectable Vaccines:Parenteral administration of inactivated formulations requiring trained personnel and individual bird handling, concentrated in breeder and layer replacement programs.
- Oral Administration:Direct gavage or feed-based delivery with limited commercial penetration outside research and smallholder contexts.
Spray vaccination dominates hatchery throughput; water medication is gaining share fastest in grow-out phase protocols.
End User:
Customer type fragmentation across farm scale and veterinary access shapes procurement channel design, with integrator direct purchasing displacing distributor intermediaries in concentrated production corridors.
- Poultry Farms:Commercial operations spanning backyard to industrial scale, with Indonesia's Ministry of Agriculture farm registration systems channeling procurement toward registered suppliers with local stability dossiers. Java and Sumatra integrators consolidate supplier relationships to reduce regulatory exposure and secure volume pricing.
- Veterinary Clinics:Service providers to semi-intensive and smallholder sectors, particularly in Vietnam's Mekong Delta periphery and Indonesian outer islands where cold-chain infrastructure gaps limit live vaccine viability.
- Agricultural Cooperatives:Collective purchasing bodies aggregating smallholder demand in Myanmar's Yangon and Mandalay corridors as semi-intensive production transitions accelerate.
- Research Institutions:Universities and government laboratories conducting field trials and strain surveillance, requiring specialized subunit and experimental vector platforms with limited commercial scale.
Poultry farms represent the largest demand pool; agricultural cooperatives are expanding most quickly in underpenetrated markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Tanjung Priok Port cold-chain terminals in Jakarta anchor vaccine distribution across the Indonesian archipelago, while the Laem Chabang Deep Sea Port in Thailand funnels European and American pharmaceutical imports into Mekong Delta supply chains.
Indonesia
Java's broiler corridor drives vaccine consumption as flock densities intensify around Surabaya and Bandung. The Ministry of Agriculture mandates compulsory Newcastle disease and avian influenza immunization schedules for all commercial farms. Cold-chain infrastructure gaps across Sumatra and Sulawesi degrade live attenuated vaccine potency during last-mile transport.
Thailand
Central plains integrators concentrate demand for mass-administered respiratory combinations in Saraburi and Nakhon Ratchasima provinces. The Department of Livestock Development enforces farm registration systems linking procurement to documented stability dossiers. Hatchery automation in Bangkok's peripheral zones embeds spray vaccination into day-old chick production workflows.
Vietnam
Mekong Delta contract farming consolidation channels vaccine purchasing through fewer integrator procurement offices in Can Tho and Long An. The Department of Animal Health operates border biosecurity checkpoints elevating product registration barriers for unregistered suppliers. Layer operations in Dong Nai province adopt recombinant platforms to satisfy export health certification requirements.
Myanmar
Yangon and Mandalay corridors transition from backyard to semi-intensive production, creating first-mover positioning for hatchery-linked vaccination programs. The national veterinary authority maintains underdeveloped field strain monitoring networks delaying vaccine updates against evolving Newcastle disease genotypes. Agricultural cooperatives aggregate smallholder demand as commercial sector penetration accelerates.
Philippines
Luzon's poultry belt around Bulacan and Pampanga provinces sustains steady vaccine uptake amid integrator expansion. The Bureau of Animal Industry enforces import licensing requirements channeling procurement toward manufacturers with established ASEAN dossier track records. Cold-chain investments in Manila's pharmaceutical logistics hubs improve archipelago distribution reliability.
ASEAN Poultry Vaccines Market Key Industry Players
On the supply side, the industry is consolidating around three strategic tiers distinguished by manufacturing scale, cold-chain reach, and regulatory dossier depth. Multinational pharmaceutical conglomerates with dedicated ASEAN production facilities anchor the premium tier, while regional manufacturers compete on price and local registration agility. Portfolio diversification into recombinant vector platforms and geographic expansion through distributor acquisition represent the dominant competitive moves reshaping supplier relationships.
Within the multinational tier, Boehringer Ingelheim International GmbH exemplifies European-origin pharmaceutical scale with GmbH structure, occupying a position anchored by regional manufacturing presence. Zoetis represents US-based animal health specialization, sitting within the cold-chain logistics leadership archetype through archipelago distribution networks. Ceva occupies a position exemplifying respiratory disease combination specialization tailored to tropical climate stressors.
| Leading Market Players |
|---|
| Boehringer Ingelheim International GmbH |
| Zoetis |
| Ceva |
| Phibro Animal Health Corporation |
| Elanco |
| Merck & Co., Inc. |
| HIPRA |
| Medion Farma |
| Malaysian Vaccines & Pharmaceuticals Sdn Bhd |
| Others |
Cost & Logistics Intelligence
Laem Chabang's pharmaceutical import terminals concentrate cold-chain vaccine throughput for Thai and Vietnamese integrators, amplifying procurement leverage for volume buyers while compressing margins for suppliers lacking direct hatchery relationships or archipelago distribution reach.
Pricing Analysis
Volume-discount tiering structures dominate ASEAN poultry vaccine procurement, with annual supply contracts separating premium recombinant platforms from standard live attenuated formulations and economy bulk respiratory combinations. Price differentiation rests on cold-chain reliability certification and technical service bundling rather than antigen sophistication alone. Pricing pressure stems from integrator consolidation in Vietnam's Mekong Delta and Indonesia's Java corridor, where fewer procurement offices command steeper volume rebates. Broiler operations exhibit highest price sensitivity, while layer management accepts premium positioning for export certification compliance.
Supply Chain Analysis
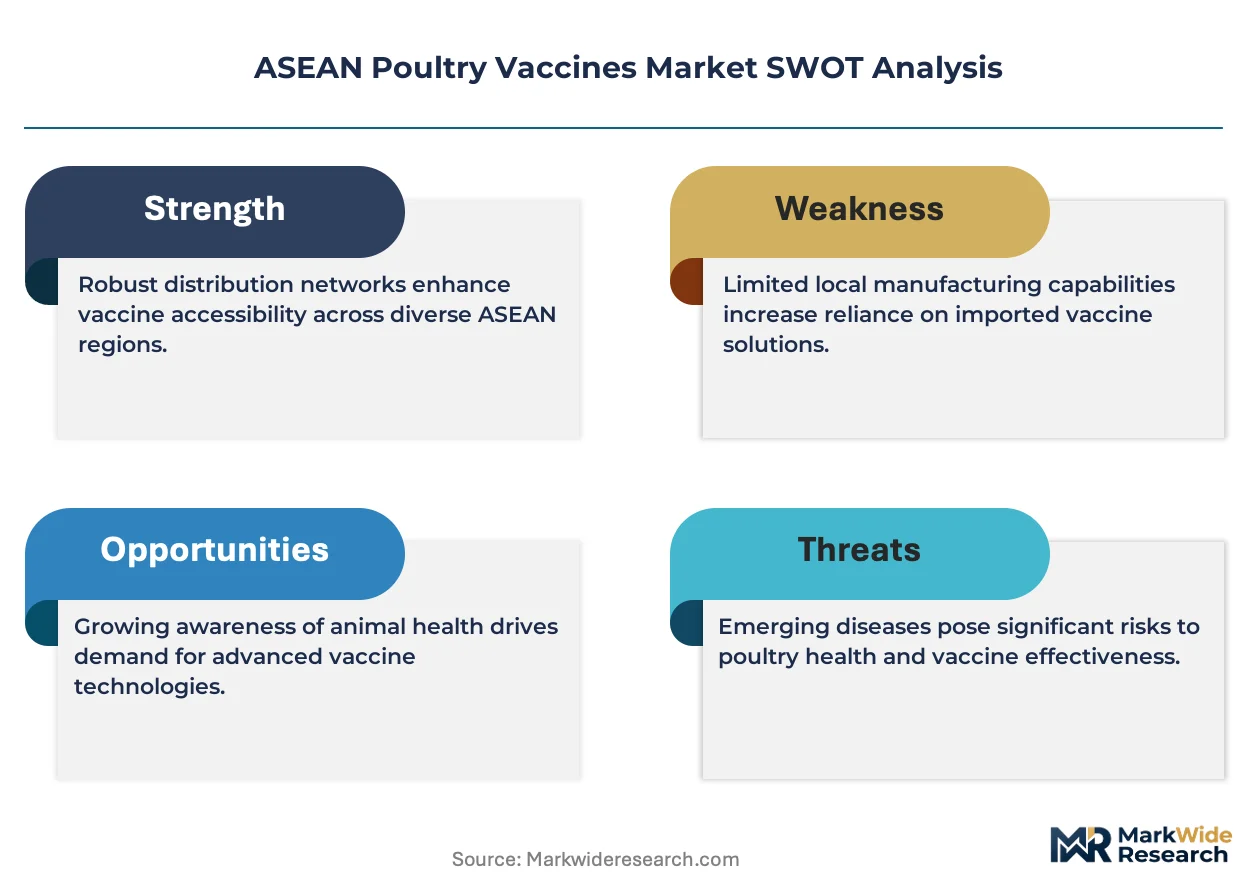
Tariff exposure between European manufacturing hubs and ASEAN veterinary authorities elevates registration cost burdens for imported recombinant platforms. Supply concentrates in Germany, the United States, and France for vector technology, while Indonesia and Thailand anchor regional fill-finish capacity for live attenuated formulations. Raw material dependencies span embryonated eggs, cell culture media, and stabilizer formulations. Single-source vulnerability characterizes HVT vector supply chains. Distribution runs through integrator-direct agreements displacing traditional veterinary distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibiotic-free production protocols threaten conventional vaccine adjuvant formulations, forcing incumbents to navigate substitution toward novel immunostimulant platforms.
For Market Incumbents: Harden cold-chain infrastructure across Indonesia's outer islands to defend against regional manufacturers with archipelago logistics agility. Deepen captive hatchery relationships through technical service co-location in Vietnam's Mekong Delta. Prioritize recombinant vector R&D to offset margin compression from live attenuated commoditization. For New Entrants and Emerging Players: Pursue Myanmar's Yangon corridor where semi-intensive transition creates first-mover positioning for hatchery-linked vaccination programs. Target agricultural cooperative aggregators in underpenetrated peripheral markets. Lead with digital traceability integration to differentiate against established cold-chain players. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because contract farming concentration concentrates procurement decisions into fewer integrator hands. Target regional manufacturers with established ASEAN dossier track records and local stability data. Watch strain surveillance network development in Laos, Cambodia, and Myanmar as inflection indicator for vaccine update cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Temperature-controlled distribution into Indonesia's outer islands secures live vaccine potency and technical service reach. |
| Recombinant Vector Platform Development | HVT-vectored differentiation unlocks premium positioning for layer operations supplying export-certified product. |
| Hatchery Technical Service Co-Location | Embedded spray vaccination expertise in Thai and Vietnamese captive hatcheries cements supplier relationships. |
| Digital Traceability Integration | Farm registration system connectivity in Vietnam enables outcome-linked procurement contracts and compliance automation. |
| Regional Dossier Registration Acceleration | ASEAN harmonization navigation reduces replicated stability studies and field trial burdens across member states. |
Research Approach
Initial hypotheses were tested against primary input from veterinary pharmaceutical executives, hatchery operations managers, integrator procurement officers, and regulatory affairs specialists at national animal health departments, then refined through secondary validation against customs import records, veterinary authority registration databases, FAO livestock production statistics, and industry association trade flow reports. Bottom-up demand modeling triangulated with top-down pharmaceutical trade value analysis.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, modeling segmentation dimensions spanning product type, application, delivery mode, and end-user category alongside regional regulatory cluster differentiation. CAGRs derived from fitted growth curves applied to hatchery throughput projections and flock density intensification patterns. Industry-specific inputs incorporated strain surveillance network coverage gaps and compulsory immunization mandate enforcement trajectories.
Sensitivities concentrate around regulatory harmonization pace, Newcastle disease genotype evolution, and cold-chain infrastructure investment timing. Forecasts reflect assumptions about integrator consolidation continuity and export certification demand growth. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Pet Obesity Management Market
Veterinary
Japan Veterinary Healthcare Market
Veterinary
Global Animal Parasiticides Market
Veterinary
Companion Animal Vaccines Market
Veterinary
Global Veterinary Grooming Aids Market
Veterinary
Global Avian Influenza Vaccines Market
Veterinary
Spain Veterinary Healthcare Market
Veterinary
Global Dog Vaccines Market
Veterinary
Veterinary CRO and CDMO Market
Veterinary
OTC Cat Medicines Market
Veterinary
Bovine Mastitis Market
Veterinary
Veterinary Scales Market
Veterinary
Veterinary Intravenous (IV) Solutions Market
Veterinary
Bovine Respiratory Disease Treatment Market
Veterinary
Global Porcine Vaccine Market
Veterinary
Animal Drug Compounding Market