
 Cardiac Sutures Market | 2026-2036
Cardiac Sutures Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Sutures Market Outlook
Buyer consolidation among hospital networks is repositioning procurement leverage toward larger integrated delivery systems. Medtronic plc leverages its broad cardiovascular portfolio to sustain long-term supply contracts with major health systems. Johnson & Johnson anchors its position through Ethicon's specialized cardiac suture lines and deep surgeon training infrastructure.
Cardiac sutures are sterile, implantable threads manufactured from polymers such as braided polyester or monofilament polypropylene, designed to withstand cyclic cardiac tissue tension while maintaining tensile strength through the critical healing window. Their primary purpose is to secure prosthetic valves, close septal defects, and anastomose bypass grafts in procedures where suture failure risks fatal hemorrhage. Absorbable sutures command expanding share in pediatric cardiac closures where permanent foreign body retention raises long-term complication concerns. Robotic-assisted suturing technology attracts capital investment as hospitals seek to differentiate surgical programs and reduce operator-dependent variability in minimally invasive valve repairs.
FDA 510(k) clearance pathways and EMA Medical Device Regulation conformity assessments govern material biocompatibility, sterilization validation, and clinical performance claims for cardiac sutures. ISO 10993 biological evaluation standards and ASTM tensile testing protocols further constrain formulation flexibility and supplier qualification timelines. Stakeholders must monitor how FDA's evolving software-as-a-medical-device framework applies to automated suturing platforms and whether EMA's str notified-body capacity extends European market entry delays.
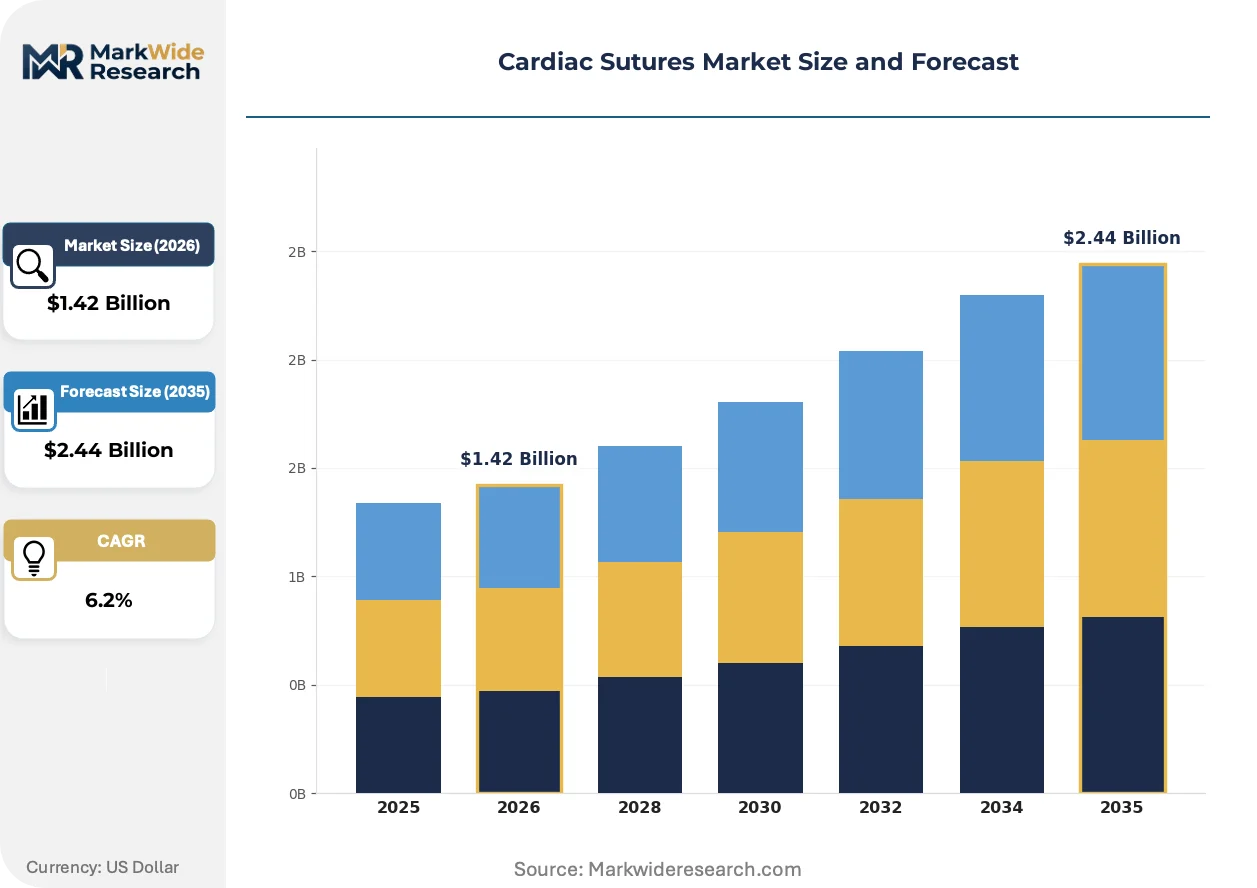
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while elevating the strategic importance of long-term supply contracts and integrated service agreements. This buyer-side concentration demands that manufacturers deliver not merely suture products but comprehensive clinical support ecosystems.
Growth Catalysts
- EMA Medical Device Regulation:The MDR's stricter clinical evidence requirements for implantable devices is accelerating the exit of marginal suppliers, concentrating volume among qualified manufacturers with robust technical files.
- Robotic-assisted suturing platforms:Da Vinci surgical systems and competing platforms are expanding addressable procedure volumes in minimally invasive cardiac surgery, creating pull-through demand for compatible suture configurations.
- Braided polyester absorbables:Next-generation synthetic absorbables with controlled tensile strength degradation profiles are capturing share in pediatric septal defect closures where permanent foreign body retention risks long-term complications.
Market Restraints
- Polymer feedstock volatility:Medical-grade polypropylene and polyester raw material costs fluctuate with petrochemical indices, squeezing gross margins for suture manufacturers lacking backward integration into polymer synthesis.
- Notified-body bottlenecks:EMA's constrained MDR notified-body capacity extends European market entry timelines by 12-18 months, freezing capital deployment and delaying revenue recognition for new product launches.
- Surgical sealant substitution:Advanced hemostatic sealants and tissue adhesives are displacing traditional suturing in select anastomosis applications, particularly in venous graft attachments where bleeding risk is moderate.
Strategic Opportunities
- India's cardiac surgery expansion:India's CDSCO is streamlining medical device registration pathways, opening access to a surgical volume growth market where public hospital procurement budgets are expanding.
- Bioactive surface coatings:Antimicrobial-impregnated and growth-factor-eluting suture coatings represent unpenetrated premium segments where clinical outcomes data commands price premiums.
- Direct-to-hospital digital procurement:Specialized medical device e-commerce platforms are disintermediating traditional distributor networks, enabling manufacturers to capture margin and build direct customer data assets.
Industry Challenges
- Specialized surgical skill scarcity:Robotic cardiac suturing demands fellowship-trained surgeons with platform-specific certification; training pipeline constraints limit procedure volume expansion regardless of capital equipment availability.
- ISO 10993 biological evaluation timelines:Comprehensive biocompatibility testing for novel polymer formulations or surface modifications extends development cycles and delays regulatory submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Sutures Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.44 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester Sutures, Polypropylene Sutures, Silk Sutures, Absorbable Sutures End User: Cardiac Centers, Hospitals, Clinics, Ambulatory Surgical Centers Technology: Traditional Suturing, Knotless Technology, Automated Suturing, Robotic-Assisted Suturing Application: Cardiac Surgery, Valve Repair, Coronary Bypass, Closure of Atrial Septal Defect |
| Companies Covered | Medtronic plc, Johnson & Johnson, B. Braun SE, Teleflex Incorporated, Smith & Nephew plc, Boston Scientific Corporation, Abbott Laboratories, CONMED Corporation, DemeTECH Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Sutures Market Strategic Shifts
Automation and material science convergence is redefining performance benchmarks for implantable cardiovascular devices. Three developments are restructuring competitive advantage.
Barbed suture technology is absorbing substantial R&D investment from manufacturers seeking to eliminate knot-tying in time-critical cardiac procedures. Academic medical centers in Germany and Japan are piloting unidirectional and bidirectional barbed configurations in mitral valve repair and atrial septal defect closure. The technology is absorbing procedural time compression benefits that translate to operating room throughput gains and reduced cardiopulmonary bypass duration.
FDA's evolving software-as-a-medical-device framework is extending oversight to automated suturing platforms with algorithmic needle-driving control. The guidance creates compliance complexity for robotic system manufacturers who must validate software updates through 510(k) supplements rather than internal quality systems. Cardiac surgery platforms with embedded suturing modules face the most stringent scrutiny, delaying feature releases and increasing regulatory affairs headcount requirements.
Integrated delivery networks are consolidating cardiac surgery procurement under centralized value-analysis committees. Traditional distributor relationships with individual surgeons or department chiefs are yielding to enterprise-level contracting with standardized product formularies. This concentration is most pronounced in United States metropolitan markets where health system mergers have created multi-hospital networks with substantial leverage over suture vendors.
Cardiac Sutures Market Segmentation
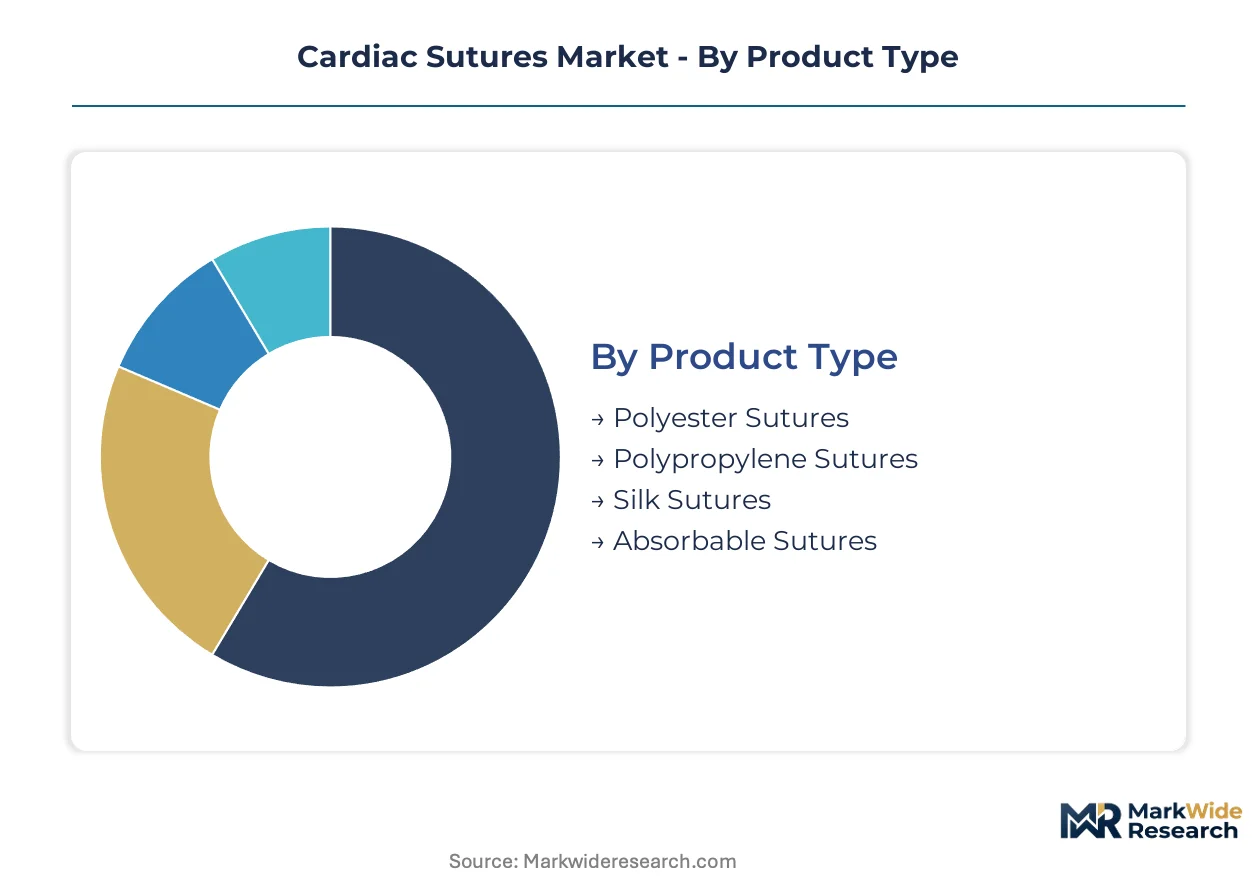
Cardiac suture segmentation reflects divergent clinical requirements across procedure complexity, patient age profiles, and institutional capabilities. Material selection and technology adoption vary sharply between high-volume coronary bypass programs and specialized congenital defect centers.
Product Type:
Polymer composition determines tensile strength retention, tissue reactivity, and absorption kinetics in cardiac applications.
- Polyester Sutures:Braided polyethylene terephthalate constructions deliver superior knot security and tensile strength for prosthetic valve fixation. Demand concentrates in German cardiac surgery centers where mitral valve replacement volumes sustain premium suture procurement.
- Polypropylene Sutures:Monofilament polypropylene offers minimal tissue drag and reduced bacterial adherence for coronary anastomosis. Japanese teaching hospitals favor these configurations for off-pump bypass procedures where precise needle control matters.
- Silk Sutures:Natural protein fiber with excellent handling characteristics retains niche use in ligation applications where long-term tensile strength is non-critical.
- Absorbable Sutures:Synthetic polymers with hydrolytic degradation profiles address pediatric septal defect closures where permanent foreign body avoidance drives material selection.
Polyester sutures lead on scale; absorbable sutures lead on momentum.
End User:
Procurement authority and clinical volume distribution reshape vendor access and pricing architecture across delivery settings.
- Cardiac Centers:Dedicated cardiovascular institutes in the United States perform concentrated valve and congenital surgery volumes, commanding direct manufacturer relationships and customized suture kits.
- Hospitals:General acute care facilities with cardiac surgery programs represent the volume anchor, particularly in Germany where DRG-based reimbursement standardizes suture formularies.
- Clinics:Outpatient cardiac catheterization and minor procedural sites generate limited suture demand focused on emergency backup inventory.
- Ambulatory Surgical Centers:Freestanding surgical facilities in Japan are expanding minimally invasive cardiac volumes, creating pull-through for specialized suture configurations compatible with limited-access approaches.
Hospitals dominate procurement scale; cardiac centers concentrate margin capture.
Technology:
Automation depth separates capital-intensive academic settings from conventional instrument-based practice.
- Traditional Suturing:Hand-needle techniques with conventional forceps and needle holders persist across low-complexity procedures and cost-constrained institutions.
- Knotless Technology:Barbed suture designs eliminate knot-tying in time-critical cardiac repairs, with German university hospitals piloting bidirectional configurations for mitral valve annuloplasty.
- Automated Suturing:Mechanized needle-driving systems reduce operator variability in anastomosis formation, attracting investment from United States integrated delivery networks seeking procedural standardization.
- Robotic-Assisted Suturing:Platform-integrated suturing modules enable minimally invasive valve repair through port-access approaches, with Japanese centers leading da Vinci cardiac certification density.
Traditional suturing retains volume dominance; robotic-assisted configurations are climbing the fastest.
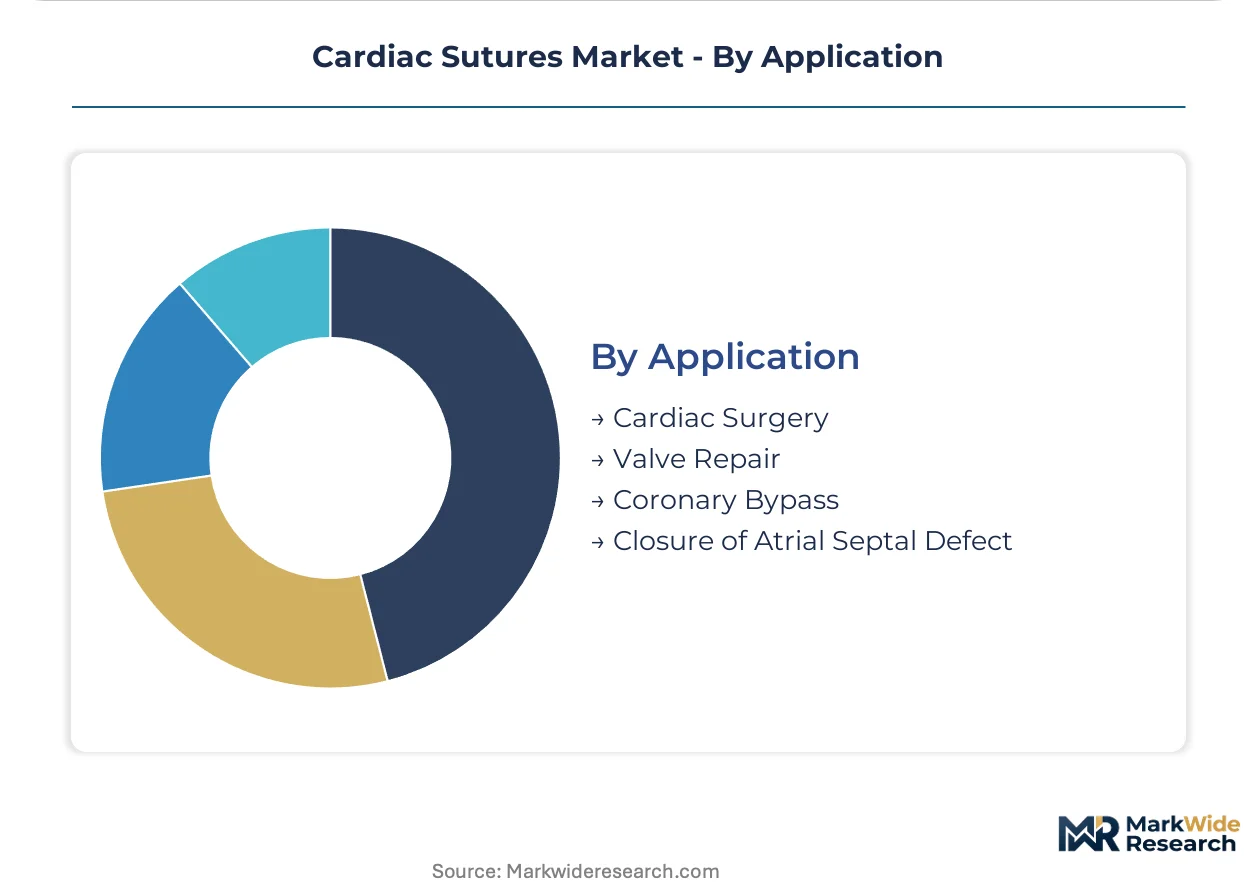
Application:
Procedure-specific mechanical demands dictate suture specification selection and inventory depth.
- Cardiac Surgery:Broad category encompassing myocardial reconstruction and tumor resection, with polyester braided sutures preferred for tissue approximation under cyclic loading.
- Valve Repair:Mitral and tricuspid reconstruction demands high-strength, low-profile sutures for annuloplasty band fixation and leaflet resection closure.
- Coronary Bypass:Arterial and venous graft anastomosis requires monofilament polypropylene for precise, thromboresistant vessel approximation.
- Closure of Atrial Septal Defect:Pediatric and adult congenital repairs increasingly specify absorbable sutures to eliminate long-term foreign body complications.
Coronary bypass procedures anchor volume; atrial septal defect closures are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's cardiac suture procurement runs through DRG-standardized hospital networks, while Japan's aging demographic profile concentrates surgical volumes in metropolitan teaching hospitals with distinct technology adoption patterns.
United States
Integrated delivery networks in metropolitan markets consolidate cardiac surgery procurement under centralized value-analysis committees, shifting leverage toward multi-hospital systems. FDA 510(k) clearance pathways govern material biocompatibility and sterilization validation for implantable sutures. The Cleveland Clinic and Mayo Clinic cardiac centers anchor demand for premium suture configurations and robotic-compatible platforms.
Germany
University hospitals in Berlin and Heidelberg pilot barbed suture configurations for mitral valve annuloplasty, absorbing procedural time compression benefits. EMA Medical Device Regulation conformity assessments with stricter clinical evidence requirements accelerate supplier consolidation. The Baden-Württemberg medical technology cluster around Tübingen and Freiburg hosts specialized suture manufacturers with robust technical files.
Japan
Da Vinci cardiac certification density concentrates in Tokyo and Osaka metropolitan teaching hospitals, expanding minimally invasive valve repair volumes. PMDA regulatory frameworks align with international ISO 10993 biological evaluation standards for novel polymer formulations. The Kansai region's aging population sustains elevated coronary bypass and valve replacement procedure rates.
India
Public hospital procurement budgets for cardiac surgery are expanding as CDSCO streamlines medical device registration pathways for imported sutures. Government health insurance schemes extend surgical access to rural populations, driving volume growth in tier-2 cities. Tamil Nadu's medical device manufacturing corridor near Chennai attracts contract manufacturing investments from multinational suture suppliers.
Switzerland
Swissmedic maintains stringent purity benchmarks for implantable cardiovascular materials that exceed baseline EU requirements, filtering supplier access. Geneva and Zurich cardiac centers specialize in congenital defect repairs specifying absorbable sutures to eliminate long-term foreign body complications. The Basel pharmaceutical-medical technology nexus supports specialized coating technologies for antimicrobial-impregnated sutures.
Cardiac Sutures Market Competitive Environment
United States producers anchor one tier; European specialists hold differentiated positions in braided polyester and advanced absorbable configurations. Market structure reflects moderate consolidation with three to five dominant manufacturers capturing majority procurement volume among integrated delivery networks. Strategic archetypes include diversified cardiovascular portfolio holders, specialized suture-focused manufacturers, and contract development organizations with captive polymer synthesis. Competitive moves center on long-term supply agreements with health system networks and backward integration into medical-grade polymer production to defend margin positions against feedstock volatility.
Among diversified cardiovascular portfolio holders, Medtronic plc and Johnson & Johnson exemplify archetypes leveraging broad device ecosystems to secure enterprise-level contracts. B. Braun SE occupies a position representing European-based specialized surgical supply manufacturers with deep surgeon training infrastructure. These three entities anchor the competitive landscape through distinct geographic footprints and procurement relationship models rather than homogeneous product positioning.
| Leading Market Players |
|---|
| Medtronic plc |
| Johnson & Johnson |
| B. Braun SE |
| Teleflex Incorporated |
| Smith & Nephew plc |
| Boston Scientific Corporation |
| Abbott Laboratories |
| CONMED Corporation |
| DemeTECH Corporation |
| Others |
Value Chain & Pricing Dynamics
Hospital network consolidation into integrated delivery systems is compressing vendor margins and forcing manufacturers toward long-term supply contracts with embedded clinical service bundles. This buyer-side concentration elevates the strategic importance of backward integration into medical-grade polymer production to defend pricing power against feedstock volatility.
Pricing Analysis
Capacity additions in India and Southeast Asia are reshaping price floors for standard polyester and polypropylene suture configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 510(k) clearance tier and ISO 10993 certification depth. Pricing pressure stems from surgical sealant substitution in venous graft applications. General acute care hospitals in Germany exhibit highest price sensitivity; United States cardiac centers demonstrate lowest.
Supply Chain Analysis
Dual-sourcing mandates from United States integrated delivery networks and German DRG-standardized hospital systems require manufacturers to qualify redundant polymer suppliers. Medical-grade polypropylene and polyester feedstock concentrates in Germany, United States, and Japan. Supply chain risk centers on petrochemical index volatility for polymer precursors. Distribution runs through specialized medical device distributors with surgeon training infrastructure, though direct-to-hospital digital procurement platforms are gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cardiac sutures function as a stable compounder anchored by aging demographics across developed economies and procedural volume expansion in minimally invasive cardiac surgery. Hospital procurement consolidation sustains predictable demand trajectories with limited cyclicality.
For Market Incumbents: Hedge against surgical sealant substitution by accelerating bioactive coating R&D and securing captive polymer synthesis capacity. Lock in ten-year supply agreements with United States integrated delivery networks before value-analysis committees finalize standardized formularies. Prioritize FDA 510(k) pathway investments for robotic-compatible suture configurations. For New Entrants and Emerging Players: Barbed suture technology offers a technology-first wedge into German university hospital pilot programs for mitral valve annuloplasty. Target India's tier-2 city public hospitals as the most penetrable geography where CDSCO registration streamlining meets expanding surgical volumes. Pursue direct digital procurement partnerships to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized coating technology developers holding antimicrobial-impregnated or growth-factor-eluting surface modification IP. Five-to-ten year viability favors manufacturers with demonstrated EMA MDR technical file robustness and established Japanese PMDA relationships. Monitor FDA software-as-a-medical-device enforcement actions against automated suturing platforms as inflection indicator for regulatory compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Long-term supply agreements with United States integrated delivery networks lock in volume commitments and standardize formularies. |
| FDA Submission | 510(k) clearance for barbed suture configurations enables commercialization in time-critical cardiac repair applications. |
| CE Marking Pathway | EMA MDR conformity assessment accelerates market access across German and Swiss cardiac surgery centers. |
| Backward Integration | In-house production of medical-grade polyester and polypropylene insulates margins from petrochemical feedstock volatility. |
| Software Companion Development | Algorithmic needle-driving control modules for robotic platforms attract capital investment from academic medical centers. |
Study Parameters
Multiple input streams — cardiac surgeon interviews, hospital purchasing committee discussions, biomedical engineer consultations, and GPO contracts manager surveys — were reconciled against FDA 510(k) filing databases, EMA MDR technical file registries, hospital procurement databases, and ISO 10993 biological evaluation standards. Secondary validation drew from customs trade data for medical-grade polymer imports and SEC 10-K disclosures from diversified cardiovascular device manufacturers. Bottom-up procedure volume estimates and top-down market size assessments were triangulated to constrain forecast variance.
Historical surgical volume trajectories in United States, Germany, and Japan were cross-referenced against panel input from cardiac surgery department heads and health system supply chain executives. The analytical framework segmented by material type, technology adoption tier, application complexity, and end-user institutional category across the analysis window. CAGRs were derived from regression modeling of aging demographic projections correlated with cardiac procedure incidence rates and robotic platform installation curves.
The model holds under stable regulatory pathways for implantable device clearance; deviation in FDA software-as-a-medical-device enforcement stringency or EMA notified-body capacity constraints would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Vascular Screening Market
Cardiovascular Devices
Global Stents Market
Cardiovascular Devices
South Korea Cardiovascular Devices Market
Cardiovascular Devices
Global Cardiac Arrest Treatment Market
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
Thoracic Vascular Stent Grafts Market
Cardiovascular Devices
Global Embolotherapy Market
Cardiovascular Devices
Disposable Blood Pressure Cuffs Market
Cardiovascular Devices
Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
UAE Cardiovascular Devices Market
Cardiovascular Devices
Cardiovascular Stents Market
Cardiovascular Devices
Lung Stent Market
Cardiovascular Devices
Asia Pacific Interventional Cardiology Market
Cardiovascular Devices
Cardiovascular Needle Market
Cardiovascular Devices
Cardiovascular Ultrasound Market
Cardiovascular Devices
Heart Beat Irregularity Detection Device Market