
 Transcatheter Bioprosthesis Market | 2026-2036
Transcatheter Bioprosthesis Market Size, Share, and Industry Trends Forecast 2026-2036
Transcatheter Bioprosthesis Market Analytics
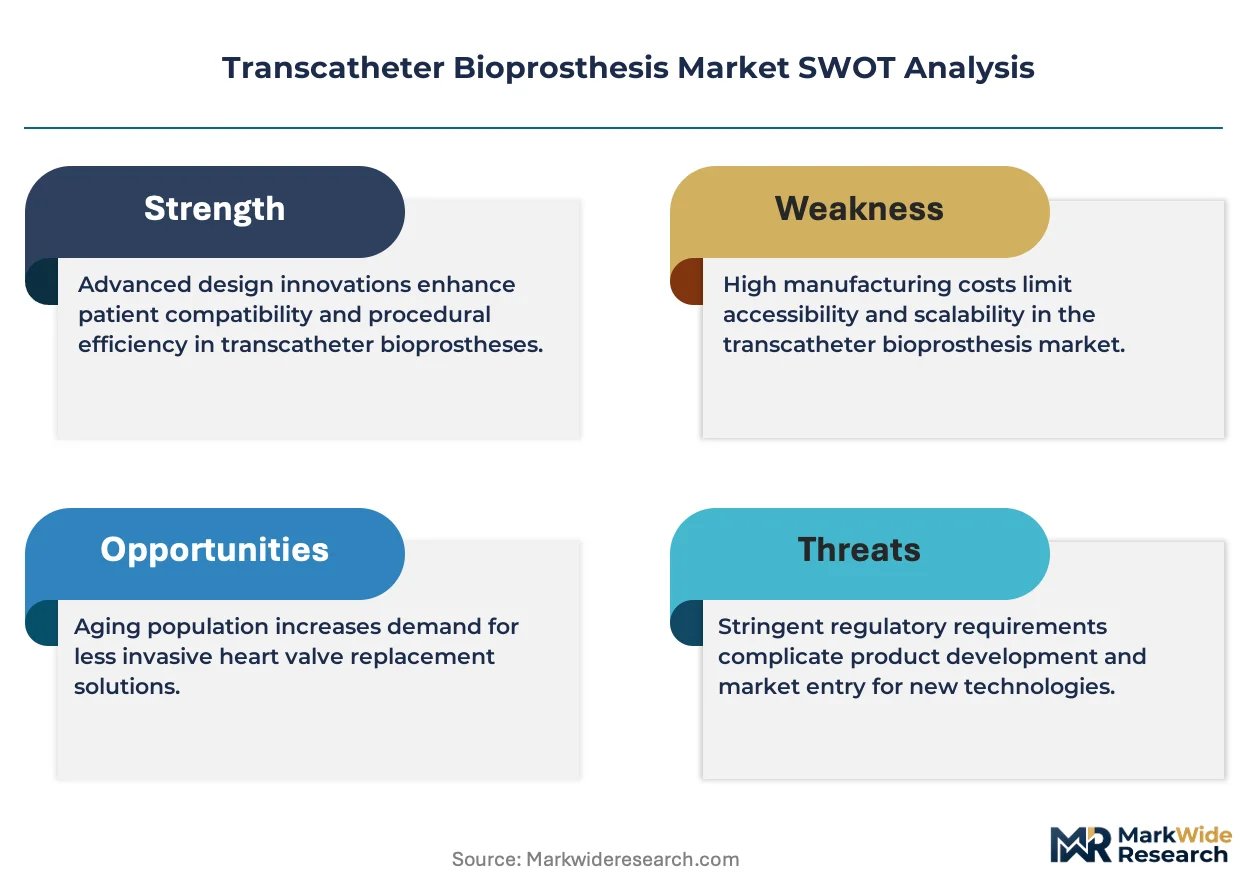
Multi-source procurement of bovine pericardial tissue is hardening as manufacturers buffer against supply volatility. Edwards Lifesciences Corporation leverages captive tissue processing facilities in the United States to secure consistent leaflet material. Medtronic anchors its supply position through long-term veterinary sourcing agreements across Australia and New Zealand. Abbott differentiates via synthetic polymer hybrid technologies that reduce dependence on biological tissue lots.
Transcatheter bioprosthesis denotes a collapsible valve or vascular implant fabricated from chemically treated biological tissue mounted on a metallic or polymeric frame, designed for percutaneous delivery via catheter-based systems without open-chest surgery. The device typically employs glutaraldehyde-fixed bovine pericardium or porcine aortic valve leaflets with radial strength provided by nitinol or cobalt-chromium stents, functioning to restore hemodynamic competence in stenotic or regurgitant cardiac valves. Transcatheter Aortic Valve Replacement commands the dominant revenue share due to established reimbursement and mature operator training ecosystems, while Valve-in-Valve applications represent the fastest-expanding procedural category as surgical bioprosthetic valves age into failure. Biologic Tissue material segments carry premium pricing power reflecting lengthy tissue qualification protocols, whereas Metal Alloy frames face margin compression from commoditized nitinol supply chains.
FDA premarket approval pathways and MDR technical documentation requirements in Europe impose substantial clinical evidence burdens that filter market entrants. Japan's PMDA Shonin process adds a distinct regulatory gate with mandatory domestic clinical trials for novel transcatheter designs. Stakeholders must monitor evolving FDA guidance on durability endpoints and EU notified body capacity constraints that could delay product introductions regardless of clinical merit.
Market Dynamics
Bovine pericardial tissue supply concentration is compressing manufacturer margins and forcing captive sourcing investments across the transcatheter bioprosthesis value chain.
Growth Catalysts
- MDR Streamlined Pathways:CE marking technical documentation harmonization under EU MDR Article 52 is accelerating novel bioprosthetic introductions by reducing notified body review cycles.
- Valve-in-Valve Procedural Expansion:Aging surgical bioprosthetic cohorts in Germany and Japan are generating replacement demand without primary surgical risk.
- Heart Team Infrastructure:Dedicated multidisciplinary programs in United States academic medical centers are standardizing operator training and expanding treatable patient pools.
Market Restraints
- Tissue Input Volatility:Bovine pericardium qualification protocols span 18-24 months, creating lot-to-lot variability that constrains production scaling.
- PMDA Domestic Trial Mandate:Japan's pharmaceutical and medical device agency requires in-country clinical evidence for novel transcatheter designs, duplicating development costs.
- Surgical Valve Substitution:Sutureless aortic valve prostheses retain preference in low-risk surgical candidates, capping transcatheter penetration in younger demographics.
Strategic Opportunities
- Synthetic Polymer Convergence:Hybrid biological-synthetic leaflet technologies reduce tissue dependence while maintaining hemodynamic performance.
- FDA Breakthrough Device Designation:Expedited premarket approval pathways for durability-enhanced designs compress competitive entry timelines.
- Rural United States Penetration:Hub-and-spoke catheterization laboratory networks extend procedural access beyond tertiary academic centers.
Industry Challenges
- Interventional Cardiologist Training Bottlenecks:Proctoring requirements and case volume thresholds limit qualified operator supply in expansion markets.
- Notified Body Capacity Constraints:EU MDR implementation has reduced available conformity assessment bodies, extending certification timelines regardless of clinical merit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transcatheter Bioprosthesis Market |
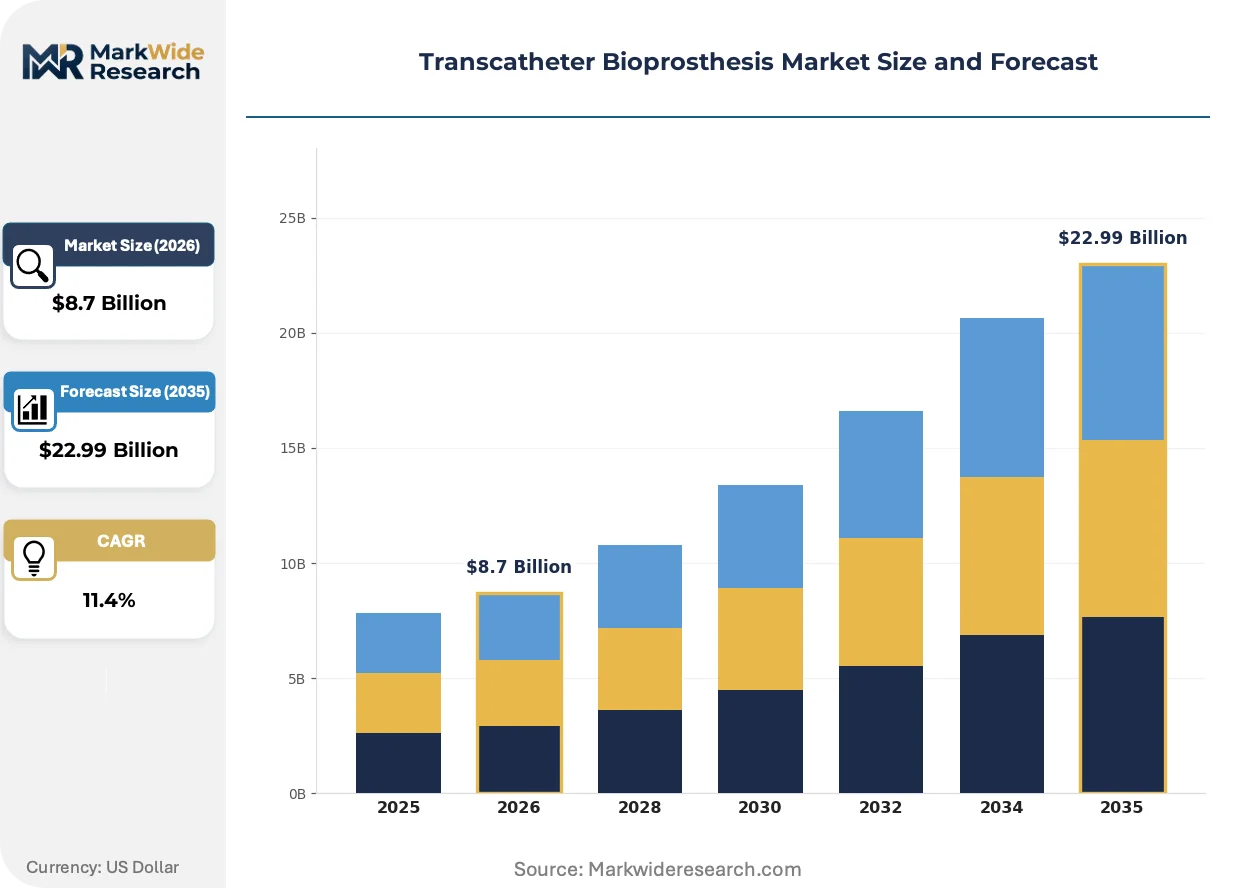
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Valve, Graft, Ring, Patch End User: Hospitals, Clinics, Surgical Centers, Ambulatory Care Material: Biologic Tissue, Metal Alloy, Polymer, Composite Technology: Transcatheter Aortic Valve Replacement, Valve-in-Valve, Balloon Valvuloplasty, Others |
| Companies Covered | Edwards Lifesciences Corporation, Medtronic, Abbott, Boston Scientific Corporation, JenaValve Technology, Meril Life Sciences, LivaNova, Terumo Corporation, Braile Biomedica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transcatheter Bioprosthesis Market Evolving Landscape
Leaflet material science and delivery system miniaturization are converging to enable transcatheter solutions for younger, lower-risk patient segments previously reserved for surgery.
Polymer hybrid leaflet technologies are expanding into bovine pericardium-dominated supply chains. Manufacturers incorporating synthetic sublayers report reduced calcification rates in preclinical models. Academic medical centers in Germany and the United States are expanding compassionate use protocols for these devices, compressing the validation timeline for full biocompatibility claims.
EU MDR Annex XVI expansion is reclassifying certain transcatheter accessories as Class III devices. This technical documentation burden is filtering marginal suppliers from the European market. Notified body backlog in Germany and the Netherlands is forcing manufacturers to sequence regulatory submissions by member state reimbursement readiness rather than clinical priority.
Hospital procurement departments are consolidating transcatheter valve purchasing through multi-year single-source agreements. This channel concentration is displacing distributor-mediated spot purchasing in United States integrated delivery networks. The shift is most visible in Florida and Texas health systems where procedure volumes justify direct manufacturer contracting.
Transcatheter Bioprosthesis Market Segmentation
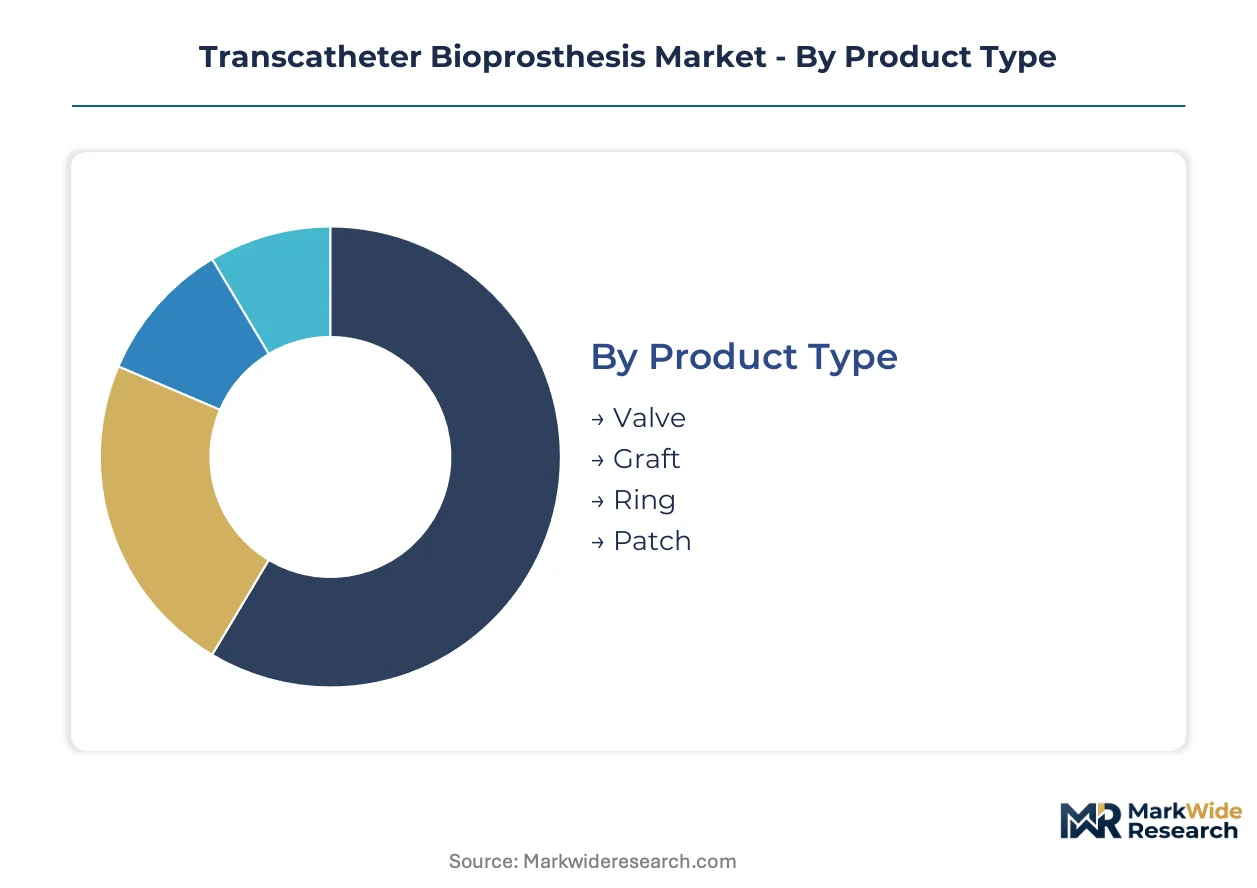
Segmentation in transcatheter bioprosthesis markets reveals how capital deployment, regulatory pathways, and clinical infrastructure shape competitive positioning. Each dimension exposes distinct barriers to entry and margin structures that determine manufacturer viability.
Product Type:
Valve platforms demand the heaviest upfront investment due to multi-year clinical trials and PMA documentation burdens.
- Valve:Collapsible leaflets mounted on self-expanding or balloon-expandable frames command premium pricing. Demand concentrates in United States academic medical centers where heart team infrastructure supports complex implantation. Edwards Lifesciences and Medtronic anchor manufacturing capacity in California and Minnesota to serve these high-volume sites.
- Graft:Tubular biological constructs for aortic arch or peripheral applications require specialized crimping profiles. German hospital systems in Bavaria and North Rhine-Westphalia generate replacement demand for failed surgical conduits. Smaller addressable volumes limit dedicated manufacturing lines.
- Ring:Annuloplasty devices for valve repair rather than replacement occupy niche indications. Mitral repair programs in Japan's university hospitals drive procedural adoption.
- Patch:Pericardial tissue sheets for cardiac reconstruction carry lower regulatory thresholds. Pediatric congenital programs in Boston and Philadelphia represent concentrated demand pockets.
Most installed capacity flows through Valve. Expansion is steepest in Graft as Valve-in-Valve salvage indications multiply.
End User:
Customer concentration determines contracting leverage and service intensity requirements across the value chain.
- Hospitals:Tertiary centers with catheterization laboratory infrastructure perform the bulk of implantations. United States integrated delivery networks in Florida and Texas consolidate purchasing through multi-year single-source agreements. Direct manufacturer relationships displace distributor intermediaries.
- Clinics:Outpatient diagnostic and follow-up facilities lack implantation capability but capture pre-procedural workup. Cardiology group practices in Germany's outpatient sector refer patients to hospital heart teams.
- Surgical Centers:Ambulatory surgical facilities remain excluded from transcatheter valve reimbursement in most jurisdictions. Structural heart procedures require overnight observation capabilities.
- Ambulatory Care:Post-discharge monitoring and anticoagulation management flow through these settings. Home health agencies in Japan's long-term care infrastructure support elderly recovery.
Hospital procurement departments wield dominant negotiating power. Ambulatory Care captures the fastest-climbing service revenue as remote monitoring protocols expand.
Material:
Input qualification timelines and supply security differentiate margin sustainability across material platforms.
- Biologic Tissue:Glutaraldehyde-fixed bovine pericardium dominates leaflet construction. Eighteen to twenty-four month tissue qualification protocols constrain production scaling. Manufacturers maintain captive sourcing through veterinary agreements in Australia and New Zealand.
- Metal Alloy:Nitinol and cobalt-chromium stent frames face commoditized supply chains. Chinese and German metallurgical suppliers compete on wire and tube pricing.
- Polymer:Synthetic leaflet substrates reduce calcification in preclinical models. Abbott's hybrid technologies illustrate this convergence pathway.
- Composite:Biological-synthetic laminates merge hemodynamic performance with supply security. Academic medical centers in Germany and the United States run compassionate use protocols.
Biologic Tissue commands the highest unit economics. Composite formulations are gaining share fastest as durability concerns reshape R&D priorities.
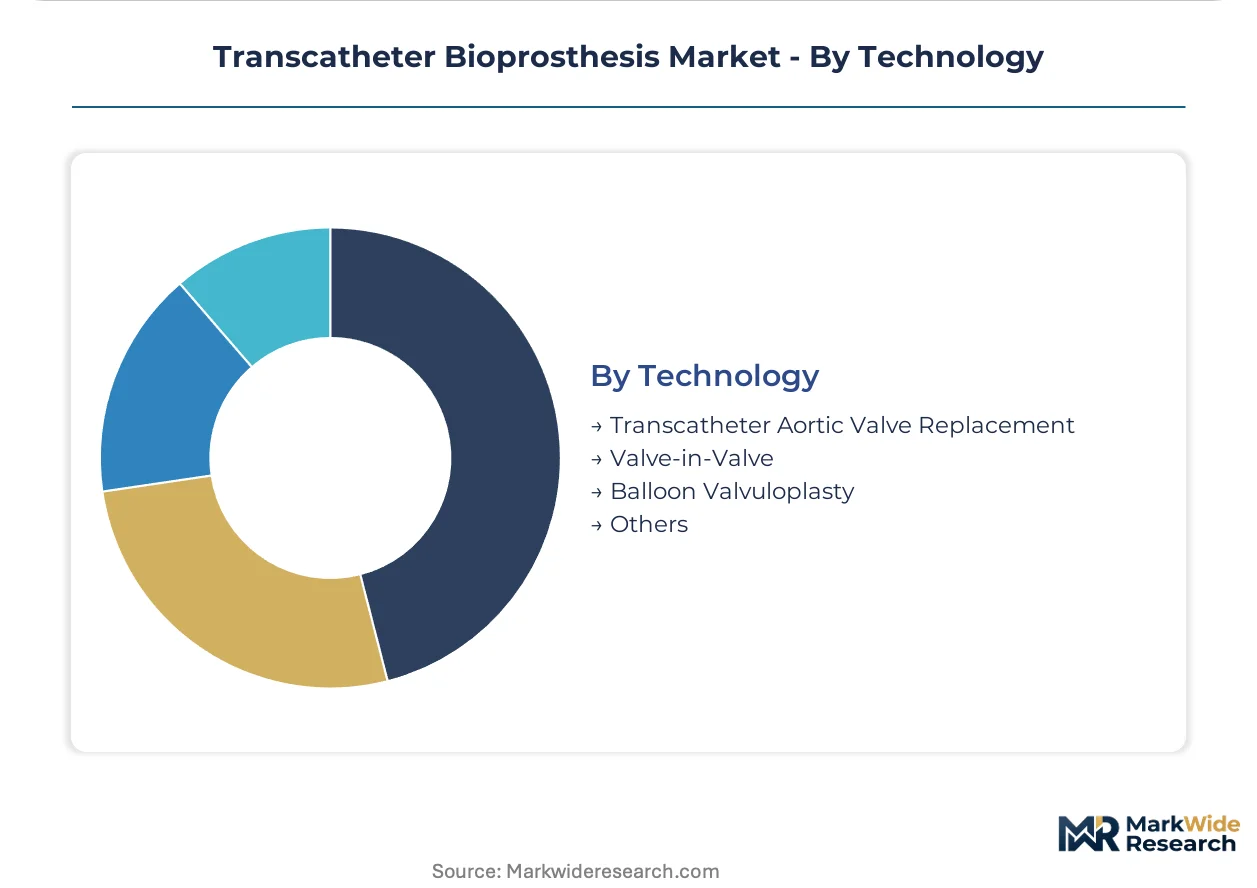
Technology:
Procedural complexity and reimbursement maturity segment addressable patient populations.
- Transcatheter Aortic Valve Replacement:Established CPT codes and operator training ecosystems support volume growth. United States Medicare reimbursement clarity sustains procedure expansion in patients unsuitable for surgery.
- Valve-in-Valve:Salvage implantation inside failing surgical bioprostheses avoids reoperative risk. Aging surgical cohorts in Germany and Japan generate replacement demand without sternotomy.
- Balloon Valvuloplasty:Palliative dilation for inoperable candidates bridges to definitive therapy. Emerging market applications persist where valve replacement remains unavailable.
- Others:Transcatheter mitral and tricuspid repair platforms remain in clinical validation. PMDA domestic trial requirements delay Japanese market entry.
Transcatheter Aortic Valve Replacement carries the deepest installed base. Valve-in-Valve applications are climbing the fastest as surgical bioprosthetic failures accumulate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's cardiovascular device corridor anchors transcatheter bioprosthesis development, with Edwards Lifesciences and Abbott maintaining manufacturing and R&D facilities in Irvine and Santa Clara. Hospital systems in Florida and Texas consolidate purchasing through integrated delivery networks, while academic medical centers in Massachusetts and Minnesota drive procedural innovation.
United States
Medicare reimbursement clarity for Transcatheter Aortic Valve Replacement sustains procedure volumes in patients unsuitable for surgery. FDA breakthrough device designations compress premarket approval timelines for durability-enhanced designs. Florida hospital systems in Tampa and Miami deploy hub-and-spoke catheterization laboratory networks to extend procedural access beyond tertiary centers.
Germany
Aging surgical bioprosthetic cohorts in Bavaria and North Rhine-Westphalia generate Valve-in-Valve replacement demand without reoperative risk. EU MDR Article 52 harmonization accelerates novel bioprosthetic introductions by reducing notified body review cycles. Munich and Berlin academic medical centers expand compassionate use protocols for polymer hybrid leaflet technologies.
Japan
Elderly patient demographics and specialized heart team infrastructure concentrate demand in Tokyo and Osaka university hospitals. PMDA Shonin process mandates domestic clinical trials for novel transcatheter designs, duplicating development costs. Kanto region catheterization laboratories report rising Valve-in-Valve volumes as early surgical bioprostheses age into failure.
United Kingdom
NHS England specialized commissioning frameworks determine transcatheter valve procedure allocations across cardiac networks. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical documentation standards. London and Manchester heart centers standardize operator training through national proctoring programs.
Australia
Medtronic's long-term veterinary sourcing agreements across New South Wales and Queensland secure bovine pericardial tissue supply. TGA conformity assessment pathways recognize FDA and CE marking evidence, streamlining market entry. Sydney and Melbourne tertiary centers participate in international clinical trials for next-generation bioprosthetic designs.
Transcatheter Bioprosthesis Market Competitive Landscape
Global majors compete with regional champions across regulatory sophistication and tissue supply security. Market structure consolidates around vertically integrated manufacturers with captive sourcing capabilities and established heart team relationships. Three archetypes dominate: integrated tissue-to-device operators, hybrid technology specialists, and regional distributors with regulatory navigation expertise. Competitive moves center on backward integration into veterinary supply chains and strategic partnerships with academic medical centers for clinical evidence generation.
Within the integrated operator tier, Edwards Lifesciences Corporation and Medtronic exemplify scale-driven positions anchored by captive tissue processing and long-term sourcing agreements. Abbott occupies a distinct hybrid-technology position, reducing biological tissue dependence through synthetic polymer convergence. Among regional specialists, JenaValve Technology and Meril Life Sciences represent European and Asian market-focused archetypes with tailored regulatory strategies. Boston Scientific Corporation sits within the diversified medical technology tier, leveraging cross-platform catheter expertise. Terumo Corporation exemplifies Asia-Pacific regional champions with cardiovascular device manufacturing heritage.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| Medtronic |
| Abbott |
| Boston Scientific Corporation |
| JenaValve Technology |
| Meril Life Sciences |
| LivaNova |
| Terumo Corporation |
| Braile Biomedica |
| Others |
Value Network & Pricing Analysis
Hospital procurement consolidation across United States integrated delivery networks is forcing manufacturers toward direct contracting arrangements that compress distributor margins and elevate price transparency. This buyer-side restructuring compels suppliers to absorb logistics costs previously externalized, reshaping how valve platforms compete on total landed cost rather than list price alone.
Pricing Analysis
Input-cost pass-through from bovine pericardium qualification protocols drives premium pricing for biologic tissue platforms, with eighteen-to-twenty-four-month lot validation cycles embedding scarcity value into unit economics. Price differentiation hinges on FDA PMA tier versus CE MDR certification pathway and heart team service bundling intensity. Pricing pressure stems from nitinol frame commoditization as Chinese and German metallurgical suppliers compete on wire pricing. Academic medical centers exhibit lowest price sensitivity due to reimbursement clarity, while rural hub-and-spoke networks face acute cost compression.
Supply Chain Analysis
Regional distribution centers in California, Minnesota, and Bavaria coordinate hub-and-spoke catheterization laboratory networks that position inventory proximate to high-volume implantation sites. Manufacturing concentrates in United States, Germany, and Japan where heart team infrastructure anchors demand. Raw material flows draw from Australian and New Zealand veterinary sourcing agreements for pericardial tissue, Chinese nitinol wire supply, and German cobalt-chromium tube production. Single-source vulnerability in qualified tissue lots poses structural risk. Distribution runs through manufacturer-direct contracting with hospital procurement departments, displacing distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where durability-enhanced designs command procurement preference as surgical bioprosthetic failures accumulate and repeat intervention costs escalate.
For Market Incumbents: Lock in captive tissue supply through long-term veterinary agreements across Australia and New Zealand before competitor backward integration exhausts qualified supplier pools. Expand polymer hybrid R&D investment to reduce biological input dependence as regulatory scrutiny on xenograft sourcing intensifies. Prioritize heart team training infrastructure in German and Japanese academic medical centers to entrench procedural loyalty. For New Entrants and Emerging Players: Begin with Valve-in-Valve salvage indications in aging surgical bioprosthetic cohorts where established players underinvest in delivery system miniaturization. Target Bavaria and North Rhine-Westphalia hospital systems where replacement demand outpaces local manufacturer service capacity. Pursue EU MDR Article 52 streamlined pathways to compress regulatory timelines relative to FDA PMA burdens. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid-technology specialists possessing synthetic polymer convergence capabilities that reduce tissue supply vulnerability. Five-to-ten-year viability favors platforms with demonstrated durability endpoints and established CE marking precedence. Watch FDA guidance on long-term valve performance metrics as the inflection signal for reimbursement expansion into lower-risk patient segments.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Tissue Processing Investment | Edwards Lifesciences' Irvine facilities secure consistent bovine pericardium supply against lot volatility. |
| Polymer Hybrid Technology Development | Abbott's synthetic sublayer integration reduces calcification rates in preclinical German protocols. |
| Heart Team Training Infrastructure | United States academic medical centers standardize operator certification and expand treatable pools. |
| EU MDR Streamlined Pathway Utilization | Article 52 harmonization accelerates novel bioprosthetic introductions via reduced notified body cycles. |
| Hub-and-Spoke Distribution Networks | Florida health systems extend procedural access beyond tertiary centers through catheterization laboratory partnerships. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down tissue supply tracking forms the analytical core of this study. Primary interviews with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers informed demand-side assumptions. Secondary validation drew from FDA PMA filings, EUDAMED MDR registration data, CMS Medicare reimbursement databases, and hospital procurement contract disclosures. Triangulation across these sources anchored volume and value estimates.
Input-output matrices mapped biologic tissue qualification throughput to finished device production capacity across the projection horizon. Segmentation dimensions modeled include product platform, material composition, technology type, and end-user facility tier. CAGRs derived from procedure volume trajectories and unit pricing trends indexed to reimbursement clarity. Forecast inputs incorporated heart team training pipeline constraints and notified body capacity bottlenecks.
Several conditions sit outside the modeled scope, including regulatory guidance revisions on durability endpoints, novel anticoagulation protocols that alter valve performance requirements, and unforeseen tissue supply disruptions from veterinary disease outbreaks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Leadless Pacemakers Market
Medical Devices
Ultrasound Probe Market
Medical Devices
Global Intra-Cranial Pressure (ICP) Monitor Market
Medical Devices
Global Trauma Devices Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Market
Medical Devices
Japan Anesthesia Devices Market
Medical Devices
Global Medical Implants Market
Medical Devices
Global Tracheal Tube and Airway Products Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Global Thoracic Drainage Devices Market
Medical Devices
ETCO2 Masks Market
Medical Devices
Global Angiography Devices Market
Medical Devices
Global Aneurysm Clips Market
Medical Devices
Muscle Stimulator Market
Medical Devices
India Contraceptive Devices Market
Medical Devices
Active Implantable Devices Market