
 Non-Invasive Blood Pressure Monitors Market | 2026-2036
Non-Invasive Blood Pressure Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Invasive Blood Pressure Monitors Market Outlook
ISO 81060-2 validation for automated non-invasive blood pressure monitors is unwinding the competitive landscape, forcing smaller participants toward costly third-party clinical studies. Omron Healthcare leverages its vertically integrated manufacturing footprint across Asia to sustain cost leadership in automated monitor production. Welch Allyn anchors the professional clinical segment through direct hospital contracting relationships in North America. GE Healthcare competes on integrated vital-signs platforms that bundle blood pressure with pulse oximetry and temperature monitoring.
Non-invasive blood pressure monitors measure arterial pressure through external cuff inflation and sensor-based detection without vascular penetration, typically achieving accuracy within ±3 mmHg when validated to ISO standards. These devices serve hypertension screening, chronic disease management, and acute care triage where repeated measurement safety outweighs invasive precision. Digital monitors lead unit volume due to consumer accessibility, while oscillometric technology captures the largest revenue pool through its dominance in both home and clinical automated systems. Photoplethysmography wrist monitors represent the fastest-growing segment as wearable form factors attract younger preventive healthcare users, though margin pools remain concentrated in hospital-grade automated systems.
FDA 510(k) clearance timelines and CE marking under the EU MDR are extending market access barriers for new entrants, particularly for software-enabled connected devices. The EPA and state-level e-waste regulations in California and New York are adding material compliance costs to monitor disposal and battery design. Stakeholders must monitor evolving CMS reimbursement codes for remote therapeutic monitoring, as coverage decisions will determine whether home-use devices shift from consumer retail to prescription channels.
Market Dynamics
ISO 81060-2 validation protocols are compressing the competitive landscape, forcing manufacturers to absorb substantial third-party clinical study costs or exit automated monitor production entirely.
Growth Catalysts
- Aging demographics:Japan, Germany, and the United States face expanding hypertensive populations requiring continuous home monitoring without clinical visits.
- Remote Patient Monitoring reimbursement:CMS coverage pathways for RTM codes are converting consumer retail purchases into prescription-channel revenue streams.
- Wearable form factor adoption:Photoplethysmography wrist monitors attract preventive healthcare users seeking continuous data integration with smartphones.
Market Restraints
- Regulatory access friction:FDA 510(k) clearance timelines and EU MDR CE marking requirements extend market entry barriers for software-enabled connected devices.
- Sensor cost volatility:MEMS pressure transistors and lithium battery materials face supply concentration risks from Asian component suppliers.
- Accuracy limitations:Oscillometric methods struggle with arrhythmia detection, restricting clinical adoption in cardiac care settings.
Strategic Opportunities
- Underpenetrated rural markets:India's tier-2 and tier-3 cities lack diagnostic infrastructure, creating whitespace for low-cost validated monitors.
- AI-enabled arrhythmia detection:Machine learning algorithms paired with photoplethysmography signals enable atrial fibrillation screening in home settings.
- Direct-to-employer channels:Corporate wellness programs in Germany and Japan bypass traditional retail and prescription distribution entirely.
Industry Challenges
- Biomedical engineering talent scarcity:ISO 81060-2 clinical validation requires specialized expertise in blood pressure physiology and statistical analysis.
- Legacy hospital system integration:New connected monitors must interface with proprietary electronic health record architectures from incumbent vendors.
- Software-as-medical-device compliance:Continuous algorithm updates trigger recurring FDA 510(k) submissions for AI-enhanced measurement features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Invasive Blood Pressure Monitors Market |
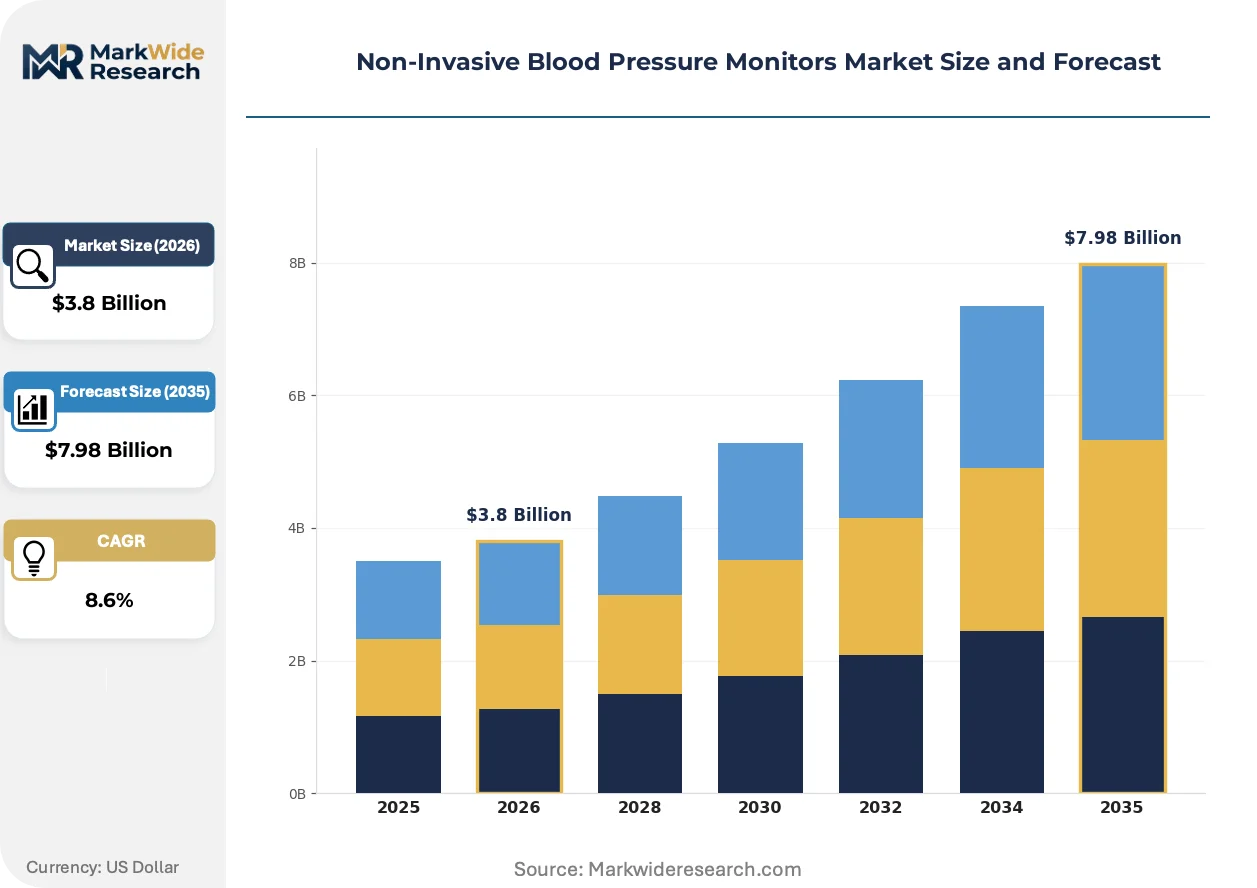
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Monitors, Automated Monitors, Wrist Monitors, Manual Monitors End User: Home Users, Hospitals, Clinics, Research Institutions Technology: Oscillometric, Auscultatory, Continuous Wave, Photoplethysmography Application: Hypertension Management, Cardiovascular Monitoring, Emergency Care, Preventive Healthcare |
| Companies Covered | SunTech Medical, Withings, Omron Healthcare, Microlife AG, GE Healthcare, Welch Allyn, American Diagnostic Corporation, Rossmax International Ltd., A&D Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Invasive Blood Pressure Monitors Market Strategic Shifts
Measurement modalities are diverging sharply between clinical-grade accuracy requirements and consumer convenience priorities, reshaping how manufacturers allocate R&D investment across product portfolios.
Photoplethysmography-based wrist monitors is bifurcating the home-use segment from upper-arm cuff devices. Younger preventive health consumers in the United States and Japan adopt continuous-wear form factors despite ±5-7 mmHg accuracy trade-offs. This divergence pressures oscillometric specialists to defend hospital-grade revenue pools while ceding mass-market volume to wearable entrants.
EU MDR CE marking requirements are extending technical documentation burdens for automated non-invasive blood pressure monitors. Manufacturers must demonstrate clinical evidence across broader patient populations including pregnancy and obesity subgroups. Small and mid-sized device firms are consolidating or partnering with notified bodies to absorb compliance costs.
Subscription-based remote monitoring services are displacing standalone hardware transactions in chronic disease management. United States health systems bundle blood pressure monitors with telehealth platforms under value-based care contracts. This shift concentrates procurement decisions at integrated delivery network headquarters rather than individual physician practices.
Non-Invasive Blood Pressure Monitors Market Segmentation
Product architecture in non-invasive blood pressure monitors splits sharply between clinical-grade accuracy requirements and consumer convenience priorities. Manufacturers must balance ISO 81060-2 validation investments against mass-market volume capture.
Product Type:
Domestic demand concentrates in automated and digital monitors across aging populations in Japan, Germany, and the United States, while wrist monitors drive export-led growth into Asian preventive health markets.
- Automated Monitors:Oscillometric pump-and-cuff systems with MEMS pressure sensors achieve ±3 mmHg accuracy under ISO 81060-2 protocols. Hospital procurement in the United States and Germany favors these units for their integration with electronic health record systems and reduced operator variability.
- Wrist Monitors:Photoplethysmography-based wearable form factors sacrifice absolute precision for continuous monitoring capability. Younger preventive health consumers in Japan and South Korea adopt these devices for smartphone data integration despite ±5-7 mmHg measurement variance.
- Digital Monitors:Consumer-grade upper-arm units with LCD displays dominate retail pharmacy channels through price accessibility and one-button operation simplicity.
- Manual Monitors:Auscultatory sphygmomanometers with mercury or aneroid gauges persist in clinical training environments and low-resource settings where power reliability constrains automated alternatives.
Automated monitors hold the largest share; momentum sits with wrist monitors.
End User:
Customer economics diverge between institutional procurement with multi-year service contracts and retail consumers making discrete purchase decisions.
- Home Users:Aging hypertensive populations in Japan and Germany drive replacement cycles for validated home monitoring devices. CMS remote therapeutic monitoring reimbursement in the United States is converting these purchases from retail to prescription-channel transactions.
- Hospitals:Acute care facilities require multi-parameter vital signs platforms integrating blood pressure with pulse oximetry and temperature monitoring. North American integrated delivery networks centralize procurement decisions at headquarters level under value-based care contracts.
- Clinics:Outpatient facilities prioritize cost-efficient validated monitors for routine hypertension screening without intensive care precision requirements.
- Research Institutions:Academic medical centers and contract research organizations demand calibrated devices with data export capabilities for clinical trial endpoints.
Hospitals generate the highest revenue per unit; home users are climbing the fastest.
Technology:
Intellectual property concentration and component supply chains determine which modalities achieve cost-competitive scale.
- Oscillometric:Cuff-based pressure sensing with algorithmic mean arterial pressure estimation dominates automated monitor production. Asian MEMS sensor suppliers concentrate component supply for this technology.
- Photoplethysmography:Optical wrist-worn sensors using LED-photodiode arrays enable continuous monitoring but face accuracy limitations in motion artifacts and peripheral vasoconstriction.
- Auscultatory:Korotkoff sound detection through stethoscope or electronic microphone remains the clinical reference standard despite operator dependency.
- Continuous Wave:Experimental tonometric and pulse transit time methods seek cuffless measurement but lack regulatory validation for diagnostic use.
Oscillometric methods hold the largest share; photoplethysmography shows the steepest expansion trajectory.
Application:
Clinical utility and reimbursement pathways segment demand across acute intervention versus longitudinal management use cases.
- Hypertension Management:Chronic disease protocols require validated home monitoring for medication titration and cardiovascular risk stratification. Japan's aging population drives volume in this segment through national health insurance coverage.
- Cardiovascular Monitoring:Post-surgical and cardiac rehabilitation settings demand arrhythmia-sensitive measurement that oscillometric methods struggle to provide, creating whitespace for AI-enhanced photoplethysmography solutions.
- Emergency Care:Pre-hospital and triage environments prioritize rapid measurement speed and durability over absolute precision.
- Preventive Healthcare:Corporate wellness programs in Germany and employer-sponsored health initiatives in the United States bypass traditional distribution channels entirely.
Hypertension management holds the largest share; preventive healthcare is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMS remote therapeutic monitoring reimbursement codes are converting United States home-use device purchases from retail to prescription channels. Germany's DiGA fast-track pathway accelerates digital health app integration with validated monitors. Japan's national health insurance coverage drives replacement cycles for aging hypertensive populations.
United States
Integrated delivery networks centralize procurement decisions under value-based care contracts. FDA 510(k) clearance timelines extend market access barriers for software-enabled connected devices. Minneapolis and Boston medical device clusters concentrate hospital-grade automated monitor production.
Germany
Corporate wellness programs bypass traditional retail and prescription distribution entirely. EU MDR CE marking requirements extend technical documentation burdens for automated monitors. Baden-Württemberg and Bavaria host precision engineering suppliers for MEMS pressure sensor components.
Japan
Aging demographics expand hypertensive populations requiring continuous home monitoring without clinical visits. METI standards alignment with ISO 81060-2 protocols tightens validation requirements. Tokyo and Osaka metropolitan areas concentrate photoplethysmography wearable development for preventive health consumers.
India
Tier-2 and tier-3 cities lack diagnostic infrastructure, creating whitespace for low-cost validated monitors. CDSCO medical device regulations under the Medical Devices Rules 2017 are tightening import and manufacturing compliance. Hyderabad and Bengaluru medical technology clusters attract contract manufacturers for oscillometric monitor assembly.
China
Domestic MEMS pressure sensor suppliers concentrate component supply for oscillometric technology. NMPA Class II medical device registration requirements extend approval timelines for automated monitors. Shenzhen and Shanghai hardware manufacturing ecosystems support cost-competitive digital monitor production for export markets.
Non-Invasive Blood Pressure Monitors Market Competitive Environment
Listed leaders compete with private specialists across regulatory validation capabilities and distribution channel access. The competitive structure consolidates around vertically integrated manufacturers with captive sensor supply and specialized clinical validation firms serving hospital procurement. Three archetypes dominate: Asia-based cost leaders with backward integration into MEMS components, North American hospital contract specialists with direct integrated delivery network relationships, and European precision engineering firms with DiGA pathway expertise. Competitive moves concentrate on ISO 81060-2 clinical study partnerships and software-as-medical-device compliance infrastructure.
Among Japan-based healthcare conglomerates, Omron Healthcare occupies a position exemplifying cost leadership through in-house production of automated monitors. Welch Allyn and GE Healthcare represent the North American hospital contract archetype, anchoring professional clinical segments through direct procurement relationships with integrated delivery networks. These three companies illustrate the geographic and strategic bifurcation between consumer-accessible retail channels and institutional procurement systems.
| Leading Market Players |
|---|
| SunTech Medical |
| Withings |
| Omron Healthcare |
| Microlife AG |
| GE Healthcare |
| Welch Allyn |
| American Diagnostic Corporation |
| Rossmax International Ltd. |
| A&D Medical |
| Others |
Value Chain & Pricing Dynamics
MEMS pressure sensor substitution for legacy piezoresistive components is redrawing component sourcing maps from Japan toward Chinese domestic suppliers while compressing sensor module costs by half across automated monitor production tiers.
Pricing Analysis
Certification level creates the primary spread between hospital-grade and retail-channel units. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 81060-2 validation investment, FDA 510(k) clearance status, and bundled software service terms. Price differentiation hinges on clinical evidence depth and after-sales calibration support. Home users exhibit highest price sensitivity; integrated delivery networks prioritize total cost of ownership over unit acquisition cost. Cost compression in economy-tier digital monitors is intensifying because Chinese contract manufacturers are scaling oscillometric assembly capacity.
Supply Chain Analysis
Strategic stockpiling of MEMS pressure transistors and lithium battery cells dominates inventory strategy among tier-one automated monitor producers facing Asian component lead time volatility. Manufacturing concentration centers on China, Japan, and South Korea for sensor fabrication and final assembly. Raw material dependencies draw from rare earth magnet supply for pump motors, medical-grade silicone for cuff bladders, and lithium cobalt oxide for power cells. Single-source vulnerability in Taiwanese MEMS foundry capacity threatens production continuity. Distribution runs through medical device distributors, direct hospital contracting, and retail pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around ISO 81060-2 validation protocols constructs formidable defensive moats for established automated monitor producers, as clinical study costs and FDA clearance timelines deter opportunistic entrants.
For Market Incumbents: Fortify ISO 81060-2 validation capabilities through captive clinical study infrastructure or exclusive partnerships with academic medical centers. Deepen backward integration into MEMS sensor fabrication to offset Asian supply concentration risks. Defend hospital-grade revenue pools against photoplethysmography wearable entrants by embedding automated monitors within electronic health record workflows at integrated delivery network headquarters.
For New Entrants and Emerging Players: Anchor in India's tier-2 and tier-3 cities where diagnostic infrastructure gaps and CDSCO regulatory maturation create whitespace for low-cost validated monitors. Target corporate wellness programs in Germany and employer-sponsored health initiatives in the United States that bypass traditional retail and prescription channels entirely. Pursue direct-to-employer go-to-market models with subscription-based remote monitoring service bundling.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed clinical validation specialists possessing ISO 81060-2 study infrastructure and notified body relationships. Five-to-ten year viability favors manufacturers with software-as-medical-device compliance infrastructure and recurring FDA 510(k) submission capabilities. Monitor CMS reimbursement code expansions for remote therapeutic monitoring as inflection indicator for home-use device channel shift from retail to prescription.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 81060-2 Clinical Validation Partnership | Accelerates regulatory clearance timelines for automated oscillometric monitors under FDA and EU MDR pathways. |
| Software-as-Medical-Device Compliance Infrastructure | Enables continuous algorithm updates for AI-enhanced arrhythmia detection without recurring 510(k) submission delays. |
| Hospital System Partnership | Secures multi-year procurement contracts with integrated delivery networks under value-based care reimbursement models. |
| MEMS Sensor Backward Integration | Reduces supply concentration exposure to Asian component suppliers and stabilizes production cost structures. |
| Remote Therapeutic Monitoring Reimbursement Strategy | Converts consumer retail purchases into prescription-channel revenue streams under CMS coverage pathways. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EU MDR notified body documentation, and CMS reimbursement code filings. Primary interviews engaged biomedical engineers at automated monitor manufacturers, hospital purchasing committee members at integrated delivery networks, GPO contracts managers, and regulatory affairs specialists at notified bodies. Secondary sources encompassed ISO 81060-2 validation study publications, CDSCO Medical Devices Rules 2017 compliance records, and NMPA Class II registration filings. Bottom-up unit shipment estimates triangulate against top-down healthcare expenditure allocation models.
Segmentation dimensions modeled span product architecture (automated, wrist, digital, manual monitors), end-user economics (home users, hospitals, clinics, research institutions), measurement technology (oscillometric, photoplethysmography, auscultatory, continuous wave), and clinical application (hypertension management, cardiovascular monitoring, emergency care, preventive healthcare). CAGRs derive from regression analysis of historical validation study volumes, reimbursement code adoption curves, and replacement cycle dynamics across aging hypertensive populations. Forecast inputs incorporate MEMS sensor cost trajectories and EU MDR technical documentation burden estimates.
Decision-makers should treat outputs as directional under assumptions of stable CMS remote therapeutic monitoring reimbursement and continued ISO 81060-2 protocol adherence; material deviation would warrant model refresh. Specific risk factors encompass FDA 510(k) timeline extensions for software-enabled devices, lithium battery supply disruptions, and photoplethysmography accuracy improvements that accelerate wrist monitor clinical adoption. Revision becomes warranted when photoplethysmography validation studies achieve diagnostic-grade equivalence thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Pulmonary Stents Market
Cardiovascular Devices
Continuous Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Perfusion Market
Cardiovascular Devices
Cardiovascular Ultrasound Market
Cardiovascular Devices
Atrial Fibrillation (AF) Ablation Market
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
Fractional Flow Reserve-Computed Tomography (FFR-CT) Market
Cardiovascular Devices
Global Angio Suites Market
Cardiovascular Devices
Normal Balloon Catheter Market
Cardiovascular Devices
Single-Use Hemoperfusion Device Market
Cardiovascular Devices
Arteriotomy Closure Devices Market
Cardiovascular Devices
Infusion System Market
Cardiovascular Devices
US Hemostats Market
Cardiovascular Devices
3D Cardiac Mapping Systems Market
Cardiovascular Devices
Fibromuscular Dysplasia Treatment Market