
 Modular Anatomic Reconstruction Market | 2026-2036
Modular Anatomic Reconstruction Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Anatomic Reconstruction Market Foresight
The EU Medical Device Regulation is realigning product development priorities across the modular anatomic reconstruction sector, forcing manufacturers to rebuild clinical evidence packages for legacy implant systems. Zimmer Biomet leverages its European notified body relationships to sustain market access for complex revision systems. Stryker Corporation anchors its competitive position through in-house production of titanium porous structures for osseointegration.
Modular anatomic reconstruction encompasses patient-adaptable implant systems composed of interchangeable components—typically titanium or cobalt-chrome stems, polyethylene liners, and modular heads—engineered to restore biomechanical function across variable anatomies. These systems rely on taper-lock or Morse-taper junctions with sub-micron machining tolerances to prevent fretting corrosion and ensure load transfer. Orthopedic surgery commands the dominant share of product demand, driven by knee and hip arthroplasty volume, while maxillofacial surgery represents the fastest-growing application as computer-guided reconstruction protocols diffuse from academic centers to community hospitals. Titanium-based constructs capture premium pricing due to fatigue resistance and biocompatibility, though polymer components in bearing surfaces face intensifying scrutiny over wear-debris generation.
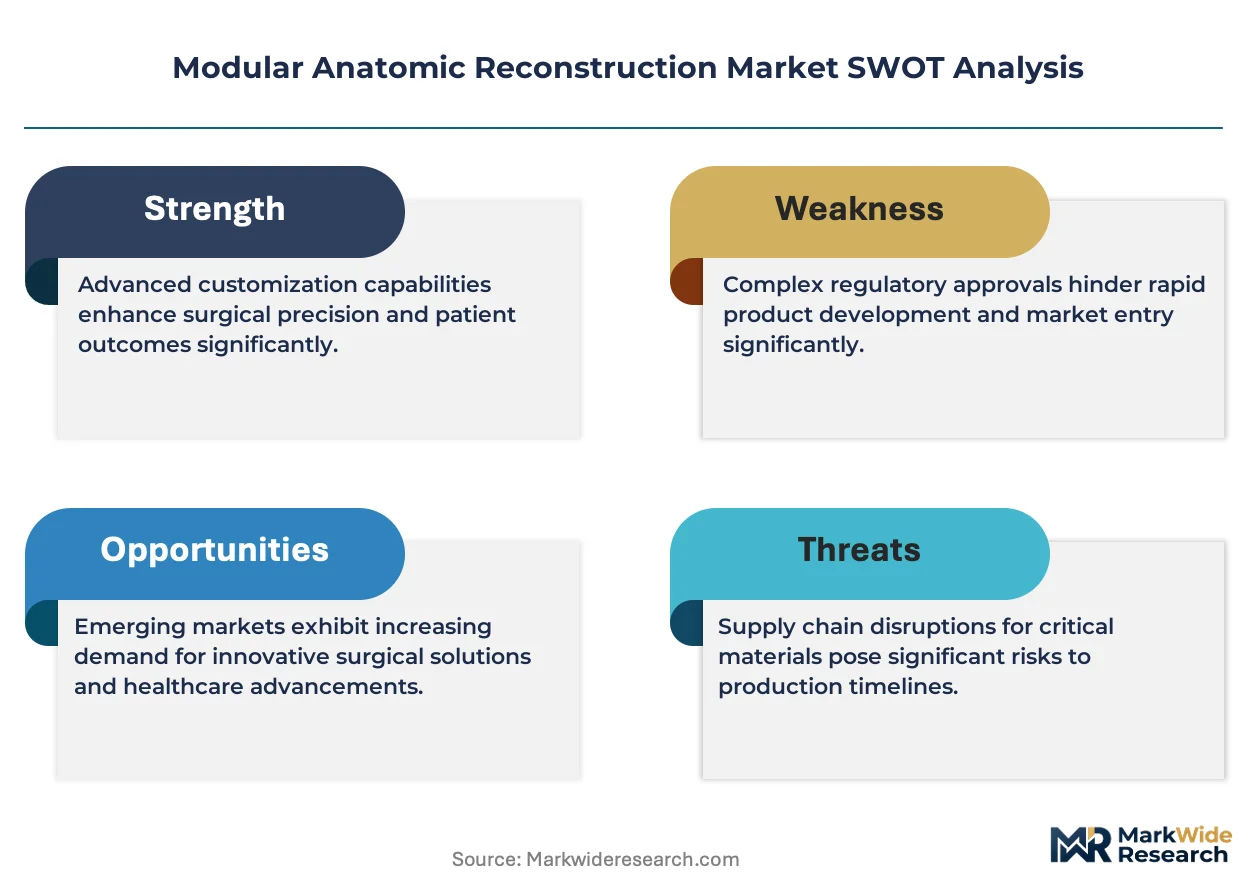
FDA premarket notification pathways and the EU MDR's stricter clinical evaluation requirements are extending development timelines and raising capital barriers for new entrants. ISO 5832 material standards and ASTM F2077 testing protocols govern mechanical validation, with notified bodies now demanding expanded biocompatibility documentation for modular interfaces. Stakeholders must monitor evolving FDA guidance on patient-matched device boundaries, as the distinction between configurable standard implants and true custom devices determines regulatory pathway and market access speed.
Market Dynamics
EU MDR's clinical evidence mandates are forcing manufacturers to rebuild legacy implant documentation while hospital procurement consolidates around value-based frameworks.
Growth Catalysts
- Aging surgical volume:Hip and knee arthroplasty procedures are climbing across OECD healthcare systems, pulling demand for revision-compatible modular systems.
- Computer-guided protocols:Maxillofacial reconstruction is electrifying community hospital adoption as navigation systems standardize.
- Germany's research density:Orthopedic clusters in Berlin-Düsseldorf-Stuttgart corridor concentrate specialized surgical centers and early adopter demand.
Market Restraints
- EU MDR compliance costs:Legacy implant systems require expensive clinical data regeneration for notified body recertification.
- Titanium feedstock concentration:Sponge and mill product supply concentrates in limited geographies, exposing margin volatility.
- Polyethylene wear limitations:Bearing surface debris generation restricts application in high-activity patient cohorts.
Strategic Opportunities
- Patient-matched boundaries:FDA guidance evolution on custom device definitions creates pathway arbitrage for configurable systems.
- Additive manufacturing convergence:Porous titanium structures combined with robotic surgical planning compress lead times for complex revisions.
- Direct hospital contracting:IDN procurement centralization in US systems enables bypass of traditional distributor markups.
Industry Challenges
- Notified body capacity:EU MDR implementation has thinned certifier availability, extending review timelines for new modular interfaces.
- Taper junction engineering:Sub-micron machining tolerance requirements demand capital-intensive metrology infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Anatomic Reconstruction Market |
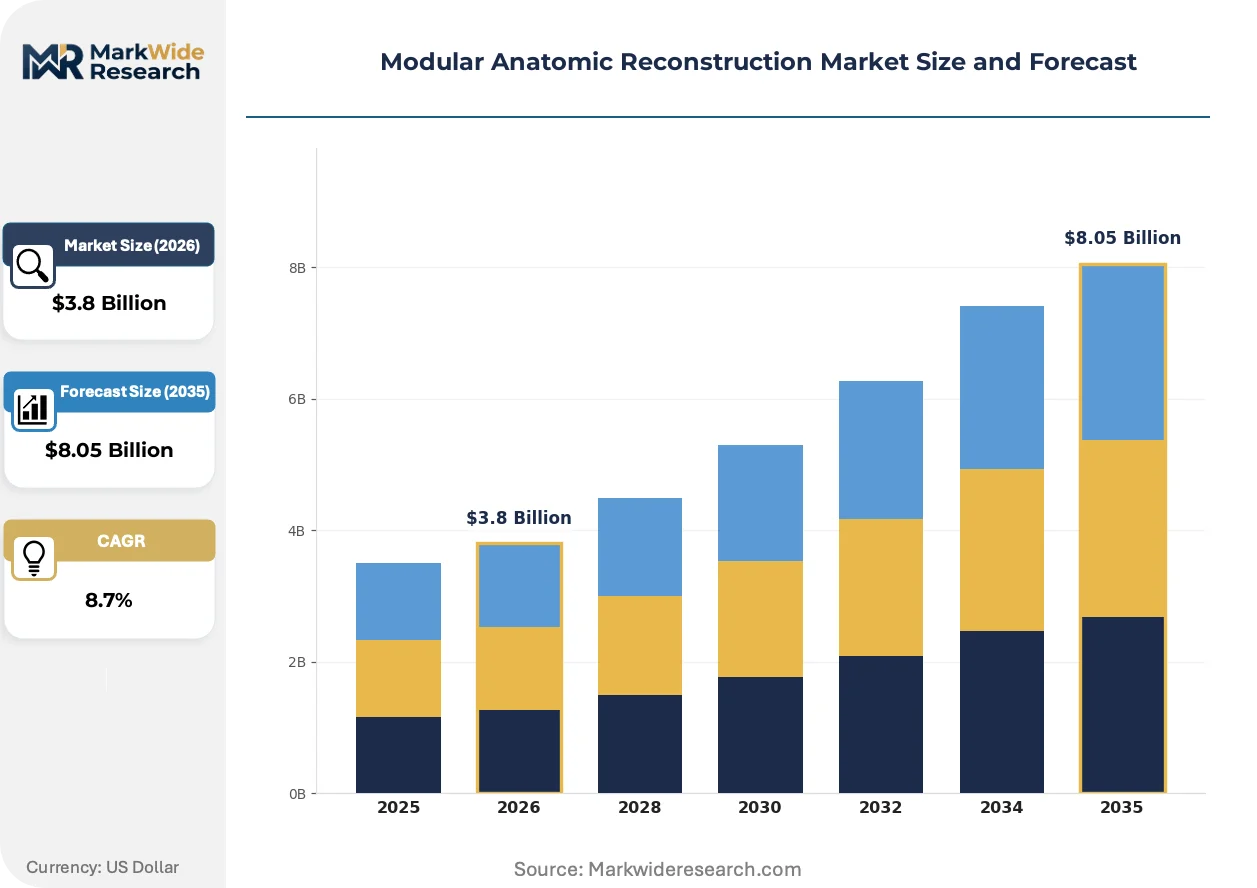
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Grafts, Surgical Instruments, Accessories Application: Orthopedic Surgery, Maxillofacial Surgery, Cardiac Surgery, Trauma Surgery End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Research Institutions Material: Polymer, Titanium, Stainless Steel, Composite |
| Companies Covered | Zimmer Biomet, Stryker Corporation, DePuy Synthes, Smith & Nephew plc, Arthrex Inc., Medtronic plc, ArthroCare Corporation, Conmed Corporation, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Anatomic Reconstruction Market Shifts & Advancements
Digital surgical planning and additive manufacturing are converging to compress the customization-to-implantation cycle for complex anatomic reconstructions.
Additive-manufactured porous titanium constructs are electrifying osseointegration performance in revision arthroplasty. Academic medical centers in Germany and the US are adopting these structures for segmental bone defect cases. The technology is compressing reliance on bulk allograft and extending implant survivorship in compromised bone stock.
EU MDR's Annex XIV clinical evaluation requirements are extending development timelines for legacy modular systems. Manufacturers must regenerate biocompatibility documentation for taper interfaces previously cleared under MDD. High-volume hip and knee platforms face the steepest compliance burden as notified bodies demand prospective data.
Hospital procurement centralization is consolidating vendor relationships around outcome guarantees. US integrated delivery networks are unbundling implant provision from surgical instrumentation services. This behavioral shift is most visible in Midwestern health systems where orthopedic service line consolidation has proceeded fastest.
Modular Anatomic Reconstruction Market Segmentation
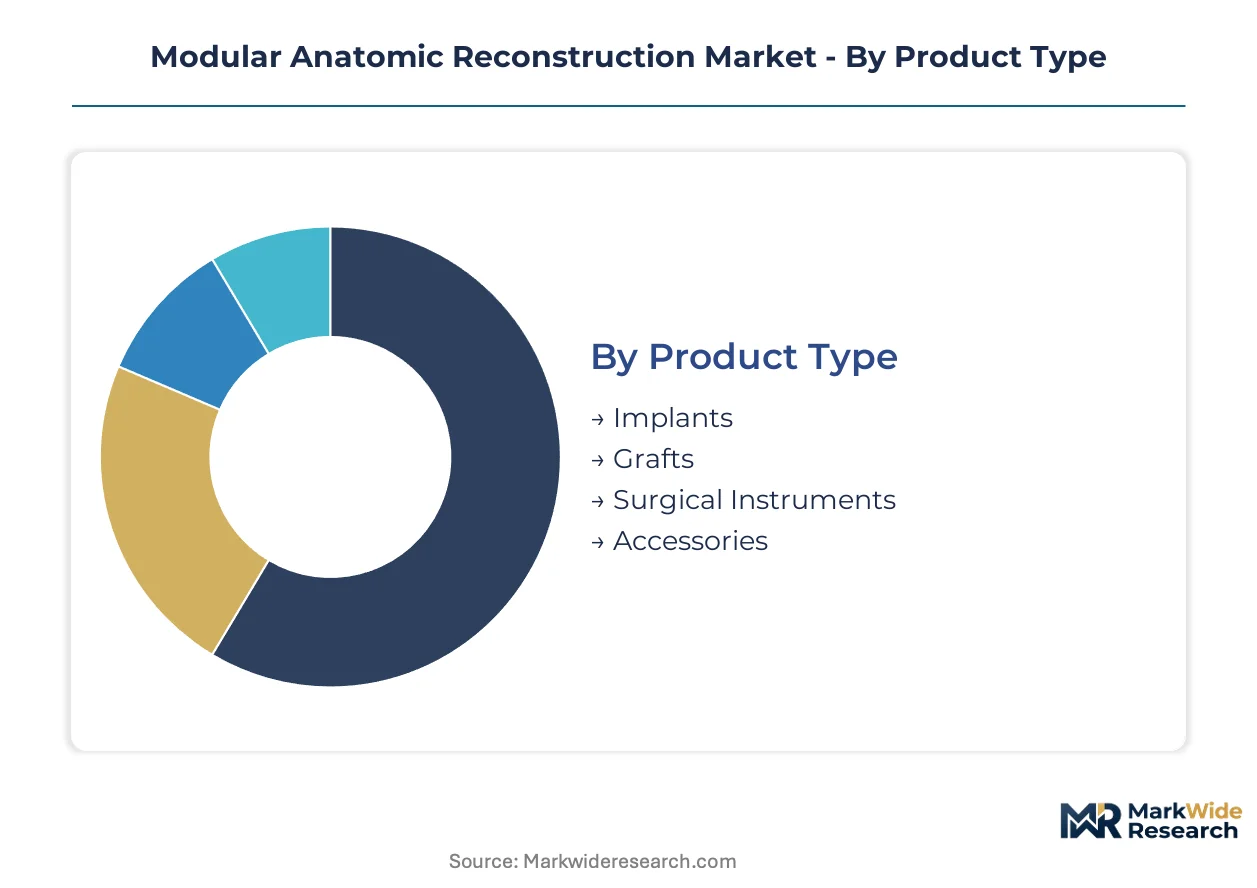
Segmentation in modular anatomic reconstruction reveals how procurement authority, clinical setting, and material specification interact to determine vendor access and pricing power. Understanding these fault lines exposes where configurable implant systems command premium positioning versus commoditized alternatives.
Product Type:
Procurement sophistication separates high-acuity hospitals seeking revision-compatible platforms from cost-constrained facilities prioritizing single-use disposables.
- Implants:Patient-adaptable systems with taper-lock junctions and modular heads constitute the revenue core, with German university hospitals driving demand for osseointegration-optimized titanium stems.
- Grafts:Bone void fillers and structural allografts concentrate in trauma centers managing segmental defects, though supply volatility from tissue bank networks constrains utilization.
- Surgical Instruments:Modular instrument trays with quick-connect interfaces reduce operative time; volume sits with high-throughput arthroplasty centers.
- Accessories:Positioning guides, trial heads, and liner insertion tools generate recurring revenue through procedure-matched consumption.
Volume sits with Implants; growth tilts toward Grafts as biological augmentation protocols diffuse.
Application:
Procedure complexity and reimbursement intensity determine which surgical specialties absorb the steepest implant costs.
- Orthopedic Surgery:Hip and knee arthroplasty dominates procurement budgets, with revision cases requiring modular stem systems that accommodate variable bone loss patterns.
- Maxillofacial Surgery:Computer-guided reconstruction protocols are electrifying community hospital adoption; navigation system integration compresses the customization-to-implantation cycle.
- Cardiac Surgery:Aortic root and valve reconstruction applications remain niche, constrained by cardiovascular device regulatory pathways.
- Trauma Surgery:Emergency fixation with modular plates and intramedullary nails concentrates in level-one trauma centers.
Orthopedic Surgery captures installed base; Maxillofacial Surgery climbs the fastest as digital planning standardizes.
End User:
Capital availability and case volume dictate whether facilities invest in configurable implant inventories or rely on consignment models.
- Hospitals:Integrated delivery networks in the US Midwest are consolidating vendor relationships around outcome guarantees, unbundling implant provision from instrumentation services.
- Ambulatory Surgery Centers:Outpatient joint replacement expansion is pulling demand for streamlined modular systems with reduced instrument footprint.
- Specialty Clinics:Orthopedic-focused facilities concentrate high-margin revision work, though limited sterilization infrastructure constrains implant storage.
- Research Institutions:Berlin-Düsseldorf-Stuttgart corridor centers pilot additive-manufactured porous structures, generating clinical evidence for subsequent commercial adoption.
Hospitals anchor procurement volume; Ambulatory Surgery Centers gain share fastest as site-of-service migration accelerates.
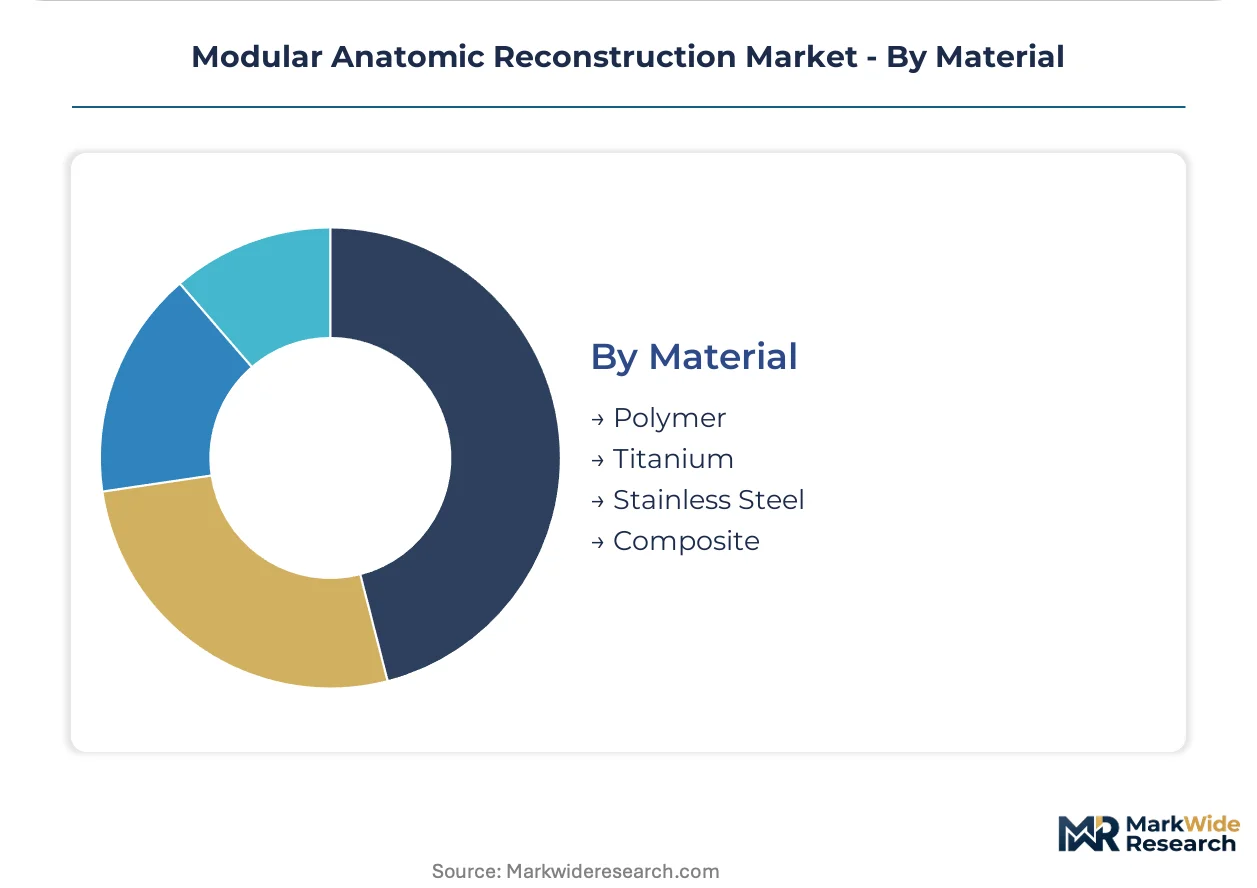
Material:
Mechanical performance requirements and biocompatibility mandates segment material selection across load-bearing and bearing-surface applications.
- Titanium:Fatigue-resistant alloys with optimized elastic modulus dominate revision stems and porous fixation surfaces, commanding premium positioning in German and US academic centers.
- Polymer:Cross-linked polyethylene liners face intensifying scrutiny over wear-debris generation, restricting utilization in high-activity patient cohorts.
- Stainless Steel:Cobalt-chrome and 316L variants persist in provisional fixation and trauma applications where cost sensitivity exceeds performance demands.
- Composite:Carbon fiber-reinforced polymers and PEEK constructs are penetrating spinal and craniomaxillofacial niches requiring radiolucency.
Titanium commands value share; Composite materials expand most quickly in specialized anatomical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of titanium sponge and mill products concentrates in limited geographies, while consumption patterns diverge across healthcare systems with varying procurement sophistication and regulatory stringency.
United States
Integrated delivery networks in the Midwest are consolidating vendor relationships around outcome guarantees, pulling demand toward revision-compatible modular platforms. FDA premarket notification pathways determine market access speed for configurable implant systems. Greater Boston and Pacific Northwest academic medical centers pilot additive-manufactured porous structures for complex segmental defects.
Germany
The Berlin-Düsseldorf-Stuttgart corridor concentrates orthopedic research clusters and specialized surgical centers driving early adoption of osseointegration-optimized stems. EU MDR notified body relationships sustain market access for legacy implant systems requiring clinical data regeneration. Baden-Württemberg manufacturing bases supply precision-machined taper junctions with sub-micron tolerances.
United Kingdom
NHS procurement centralization is unbundling implant provision from instrumentation services across orthopedic service lines. MHRA convergence with EU MDR standards extends documentation requirements for modular interfaces previously cleared under MDD. London and Southeast England academic hospitals generate clinical evidence for subsequent commercial adoption of patient-matched boundaries.
Japan
PMDA regulatory pathways favor incremental innovation in bearing surface materials, constraining polyethylene liner applications in high-activity cohorts. METI industrial policy supports domestic titanium alloy production for fatigue-resistant stems. Kansai region manufacturing clusters supply precision components for regional arthroplasty volume.
Switzerland
Swissmedic certification requirements align with EU MDR stringency, filtering market access to established manufacturers with robust clinical evidence packages. Private hospital procurement concentrates in Zurich and Geneva corridors with premium positioning for revision-compatible systems. Domestic precision machining capabilities serve as regional suppliers for taper-lock junction components.
Modular Anatomic Reconstruction Market Competitive Landscape
The competitive structure tilts toward diversified orthopedic conglomerates with notified body relationships and in-house metrology infrastructure. Market access depends on clinical evidence regeneration capabilities under EU MDR timelines. Three archetypes dominate: diversified device conglomerates with European regulatory scale, precision machining specialists with sub-micron taper capabilities, and additive manufacturing integrators with porous titanium expertise. Competitive moves concentrate on M&A for notified body relationships and backward integration into titanium feedstock.
Within the diversified conglomerate tier, Zimmer Biomet and Stryker Corporation occupy positions anchored by European market access scale. DePuy Synthes sits within the Johnson & Johnson medical device structure, representing integrated supply chain control over bearing surface materials. These three entities exemplify the capital-intensive archetype capable of absorbing EU MDR compliance costs while sustaining legacy platform recertification timelines.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Stryker Corporation |
| DePuy Synthes |
| Smith & Nephew plc |
| Arthrex Inc. |
| Medtronic plc |
| ArthroCare Corporation |
| Conmed Corporation |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
EU MDR sustainability and biocompatibility documentation mandates gate qualified supply access and premium-tier pricing power for modular anatomic reconstruction systems. Manufacturers absorbing clinical data regeneration costs pass through pricing premiums to German university hospitals and US integrated delivery networks seeking revision-compatible platforms with validated taper-lock junctions.
Pricing Analysis
Outcome-based pricing anchored to implant survivorship and revision-free intervals dominates procurement negotiations between hospital systems and orthopedic conglomerates. Price differentiation stratifies across CE-marked premium tiers with full Annex XIV clinical packages, standard MDD-transitioned platforms with regenerated biocompatibility data, and economy tiers for cost-constrained ambulatory surgery centers. Pricing pressure stems from US IDN procurement centralization unbundling implant provision from instrumentation services. Ambulatory surgery centers exhibit highest price sensitivity due to constrained capital availability and outpatient joint replacement reimbursement compression.
Supply Chain Analysis
Reverse-logistics flows for explanted modular components and surgical instrument refurbishment concentrate servicing capacity in Baden-Württemberg machining clusters and Greater Boston medical device corridors. Titanium sponge supply draws from Kazakhstan, Ukraine, and Russian Federation feedstock concentration, while precision-machined taper junctions source from Germany, Switzerland, and Japan. Single-source vulnerability in titanium mill product exposes margin volatility to commodity price swings. Distribution runs through orthopedic distributor networks consolidating around GPO contracts and direct hospital system agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into titanium feedstock and precision machining capabilities constitutes the defining vertical-integration race in modular anatomic reconstruction, as EU MDR compliance costs and taper junction engineering demands concentrate competitive advantage with capital-intensive players.
For Market Incumbents: Deepen in-house production of porous titanium structures for osseointegration to offset additive manufacturing specialist encroachment. Secure notified body capacity through exclusive certification partnerships before EU MDR implementation thins reviewer availability further. Anchor backward integration into titanium sponge sourcing to defend margin position against Kazakhstan-Ukraine supply volatility.
For New Entrants and Emerging Players: Computer-guided maxillofacial reconstruction protocols offer a technology-first wedge into community hospital adoption outside orthopedic-saturated metropolitan corridors. Target ambulatory surgery centers in US Midwestern health systems where outpatient joint replacement volume accelerates fastest. Pursue FDA premarket notification pathway arbitrage on patient-matched device boundaries to compress market access timelines versus full PMA submissions.
For Investors and Strategic Acquirers: Notified body relationship scarcity is the leading indicator that EU MDR regulatory scale will consolidate vendor relationships around three diversified conglomerates. Five-to-ten year viability favors precision machining specialists with sub-micron taper capabilities and existing European market access. Monitor FDA guidance evolution on custom device definitions for inflection signals in configurable system pathway economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Capacity Acquisition | EU MDR implementation thins certifier availability, extending review timelines for modular interfaces. |
| Additive Manufacturing Integration | Porous titanium structures compress lead times for complex revision cases in German academic centers. |
| Direct Hospital System Contracting | US IDN procurement centralization enables bypass of traditional distributor markups in Midwestern corridors. |
| Clinical Evidence Regeneration | Legacy implant systems require expensive biocompatibility documentation for EU MDR recertification. |
| Titanium Feedstock Backward Integration | Kazakhstan-Ukraine sponge concentration exposes margin volatility requiring upstream supply control. |
Research Methodology
Multi-period observation of hip and knee arthroplasty procedure volumes, EU MDR notified body capacity, and titanium sponge pricing anchored the trend analysis, supplemented by interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EU MDR Annex XIV clinical evaluation summaries, hospital procurement databases, CMS Medicare claims data, and orthopedic society registry publications. Bottom-up implant demand modeling triangulated against top-down healthcare expenditure projections.
Segment-weighting across product type, application, end user, material specification, and regional regulatory cluster determined value distribution. CAGRs derived from procedure volume elasticity to aging demographics, revision surgery incidence curves, and technology adoption S-cycles for computer-guided protocols. Forecast inputs incorporated EU MDR compliance cost trajectories, additive manufacturing penetration rates in porous titanium structures, and ambulatory surgery center site-of-service migration patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR implementation delays or titanium supply disruptions. Practitioners should monitor notified body capacity expansion, FDA patient-matched device guidance releases, and Kazakhstan-Ukraine titanium sponge export flows for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Urinary Collection Device Market
Medical Devices
Deaver Retractor Market
Medical Devices
Bone Densitometer Devices Market
Medical Devices
General Surgical Devices Market
Medical Devices
US Anti-Blue Ray Myopia Lenses Market
Medical Devices
Artificial Implants Market
Medical Devices
Biliary Catheters Market
Medical Devices
Anesthesia Face Masks Market
Medical Devices
Global Hernia Repair Devices and Consumables Market
Medical Devices
Metered Dose Squeeze Dispenser Market
Medical Devices
Implantable Neurostimulators Market
Medical Devices
Light Therapy Beauty Devices Market
Medical Devices
Permanent Artificial Skin Market
Medical Devices
Drug and Gene Delivery Devices Market
Medical Devices
Incubator Devices Market
Medical Devices
PET Injectors Market